
 Global Phytopathological Disease Diagnostics Market | 2026-2036
Global Phytopathological Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phytopathological Disease Diagnostics Market Foresight
EU Green Deal agricultural sustainability targets are restructuring compliance obligations for crop protection input suppliers across member states. Agdia, Inc. leverages its dominance in immunofluorescence reagent manufacturing to sustain North American field diagnostic penetration. TwistDx Limited anchors its competitive position through proprietary recombinase polymerase amplification chemistry that accelerates pathogen detection in resource-limited settings. Thermo Fisher Scientific extends its installed base of quantitative PCR platforms into emerging agricultural testing workflows.
Phytopathological disease diagnostics encompass laboratory and field-based analytical methods for detecting, identifying, and quantifying plant pathogens including fungi, bacteria, viruses, and nematodes through serological, molecular, microscopic, or biochemical techniques, typically achieving detection thresholds of picogram-scale antigen concentration or single-copy nucleic acid sensitivity. These systems enable crop protection decisions, seed certification, quarantine enforcement, and pesticide resistance monitoring across commercial agriculture and plant breeding programs. Molecular diagnostics platforms command premium pricing due to multiplexing capability and quantitative precision, while serological assays retain volume leadership in routine screening applications. Agricultural laboratories represent the most consolidated end-user channel, though seed testing facilities exhibit the fastest growth trajectory driven by regulatory expansion of certified seed programs.
EPA biopesticide registration requirements under FIFRA shape product development priorities for US diagnostic kit manufacturers, while EFSA plant health risk assessments under EU Regulation 2016/2031 establish harmonized quarantine pathogen lists that standardize detection menu specifications across European testing providers. India's BIS seed certification standards and China's GB/T national standards for plant quarantine create parallel compliance architectures that multinational suppliers must navigate simultaneously. Stakeholders should monitor convergence between digital agriculture platforms and point-of-need diagnostics as integrated disease management systems redefine procurement criteria.
Market Dynamics
CRISPR-based detection platforms are compressing detection timelines from days to hours, forcing agricultural laboratories across Brazil, India, and the European Union to retire legacy serological workflows and restructure capital allocation toward nucleic acid chemistry.
Growth Catalysts
- EU Regulation 2016/2031:Harmonized quarantine pathogen lists under EFSA oversight standardize detection menu specifications, compelling European testing providers to expand multiplex molecular capacity.
- Seed certification expansion:Brazil's MAPA phytosanitary export requirements drive molecular diagnostic adoption at seed testing facilities to maintain international market access for soybean and maize exports.
- Isothermal amplification chemistry:Recombinase polymerase amplification enables field-deployable pathogen detection without thermal cycling infrastructure, penetrating resource-limited agricultural regions.
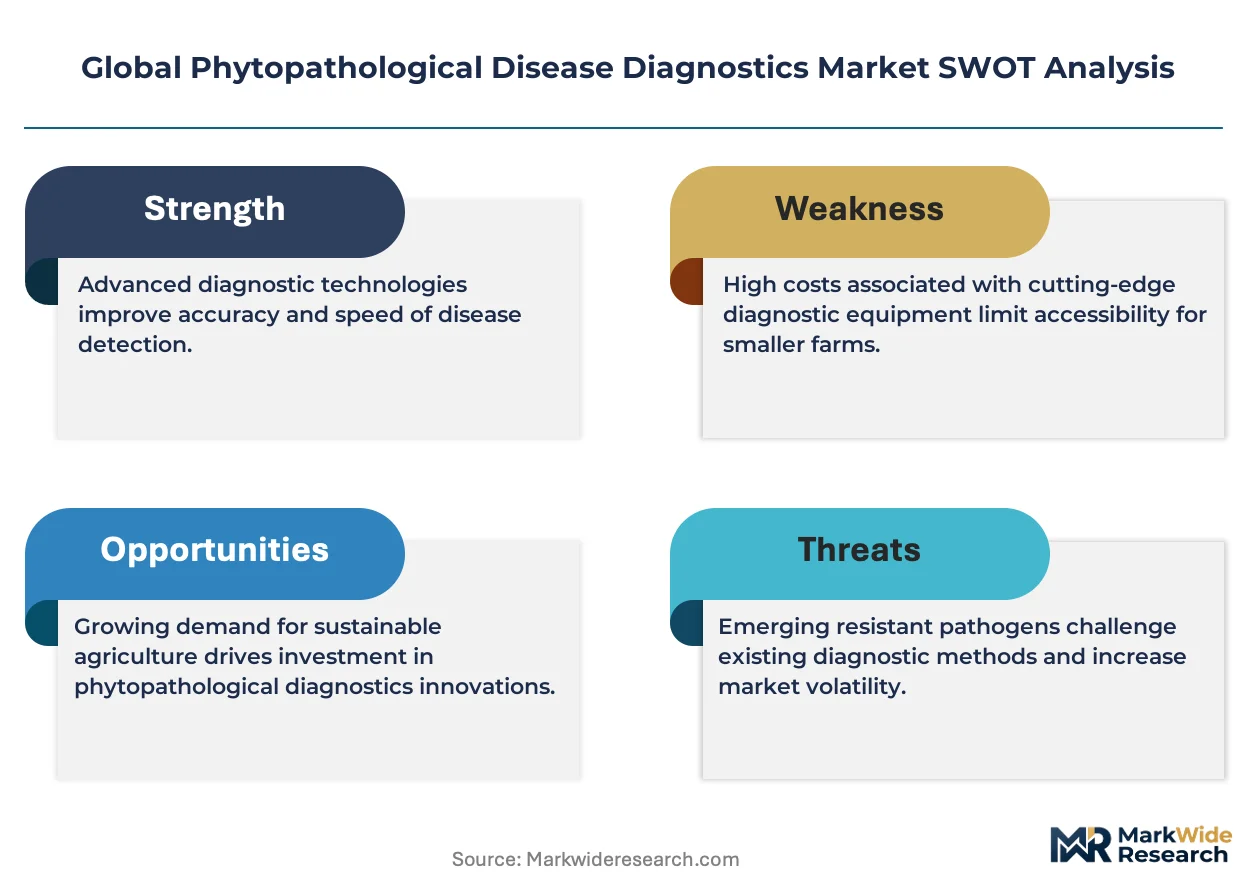
Market Restraints
- Reagent supply concentration:Polymerase enzymes and fluorescent probe synthesis concentrate among specialized biochemical suppliers in Germany and the United States, exposing diagnostic manufacturers to input cost volatility.
- Technical specificity limitations:Serological cross-reactivity between related viral strains generates false positives in routine screening, constraining assay reliability for quarantine enforcement.
- Regulatory fragmentation:Divergent BIS seed certification standards in India and GB/T national standards in China force multinational suppliers to maintain parallel validation dossiers, inflating compliance overhead.
Strategic Opportunities
- Digital agriculture convergence:Integration of point-of-need diagnostics with IoT-enabled crop monitoring platforms creates bundled disease management procurement criteria among large-scale farming operations.
- APEDA-mandated certification:India's export promotion authority requires molecular verification for basmati rice and spice consignments, expanding contract research organization capacity in Punjab and Kerala.
- LAMP-CRISPR hybrid platforms:Convergence of loop-mediated isothermal amplification with CRISPR-Cas12a detection chemistry enables smartphone-readable results without laboratory infrastructure.
Industry Challenges
- Multiplex assay development timelines:Validation of simultaneous pathogen detection panels against EFSA and USDA reference strain collections extends product launch cycles by 18-24 months.
- Field technician molecular biology competency:Isothermal and CRISPR-based platforms require nucleic acid handling skills absent from traditional agricultural extension workforces, necessitating structured training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phytopathological Disease Diagnostics Market |
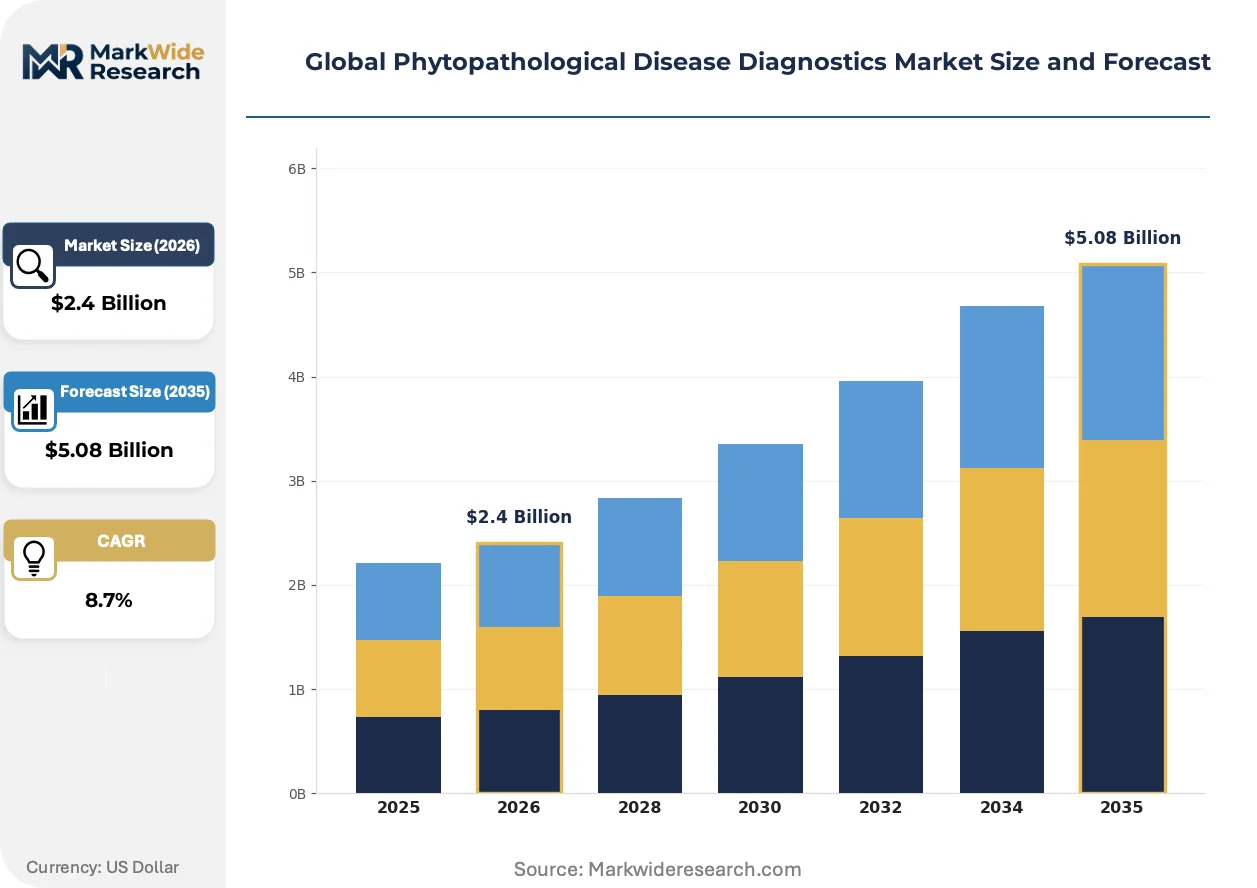
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serological Assays, Molecular Diagnostics, Microscopy, Biochemical Tests, Immunofluorescence Technology: PCR, ELISA, LAMP, Biosensors, Microarray Analysis Application: Cereal Crops, Horticultural Plants, Plantation Crops, Legumes, Turfgrass End User: Agricultural Laboratories, Research Institutes, Crop Consultants, Seed Testing Facilities |
| Companies Covered | Agdia, Inc., Creative Diagnostics, TwistDx Limited, Qualiplante SAS, Norgen Biotek Corp., BIOREBA AG, Abingdon Health, LOEWE Biochemica GmbH, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phytopathological Disease Diagnostics Market Shifts & Advancements
Portable nucleic acid detection platforms are collapsing the boundary between centralized agricultural laboratories and field-based decision-making, redefining where pathogen diagnosis occurs within crop protection workflows.
CRISPR-Cas12 and Cas13 detection systems is consolidating molecular diagnostic workflows by enabling single-molecule sensitivity without quantitative PCR thermal cycling infrastructure. Seed testing facilities in Brazil and contract research organizations in India are adopting these platforms to accelerate turnaround times for phytosanitary certification. The technology is consolidating competitive advantage around intellectual property position in guide RNA design and reporter chemistry, compressing margins for conventional ELISA reagent suppliers.
EU Green Deal agricultural sustainability targets under the European Commission's Farm to Fork Strategy are mandating reduced chemical pesticide application, which increases reliance on early pathogen detection for precision crop protection. This regulatory pressure elevates diagnostic specificity requirements above routine screening thresholds. European agricultural cooperatives and input distributors are responding by bundling molecular testing services with biocontrol product recommendations.
Testing service procurement by large-scale commodity growers is fragmenting from centralized laboratory contracts toward distributed point-of-need devices owned at farm or cooperative level. This displacement compresses revenue per test while expanding addressable test volume across mid-size operations. The shift is most visible in Brazil's soybean belt and India's contract farming clusters for export-oriented horticulture, where real-time detection informs same-day fungicide application decisions.
Global Phytopathological Disease Diagnostics Market Segmentation
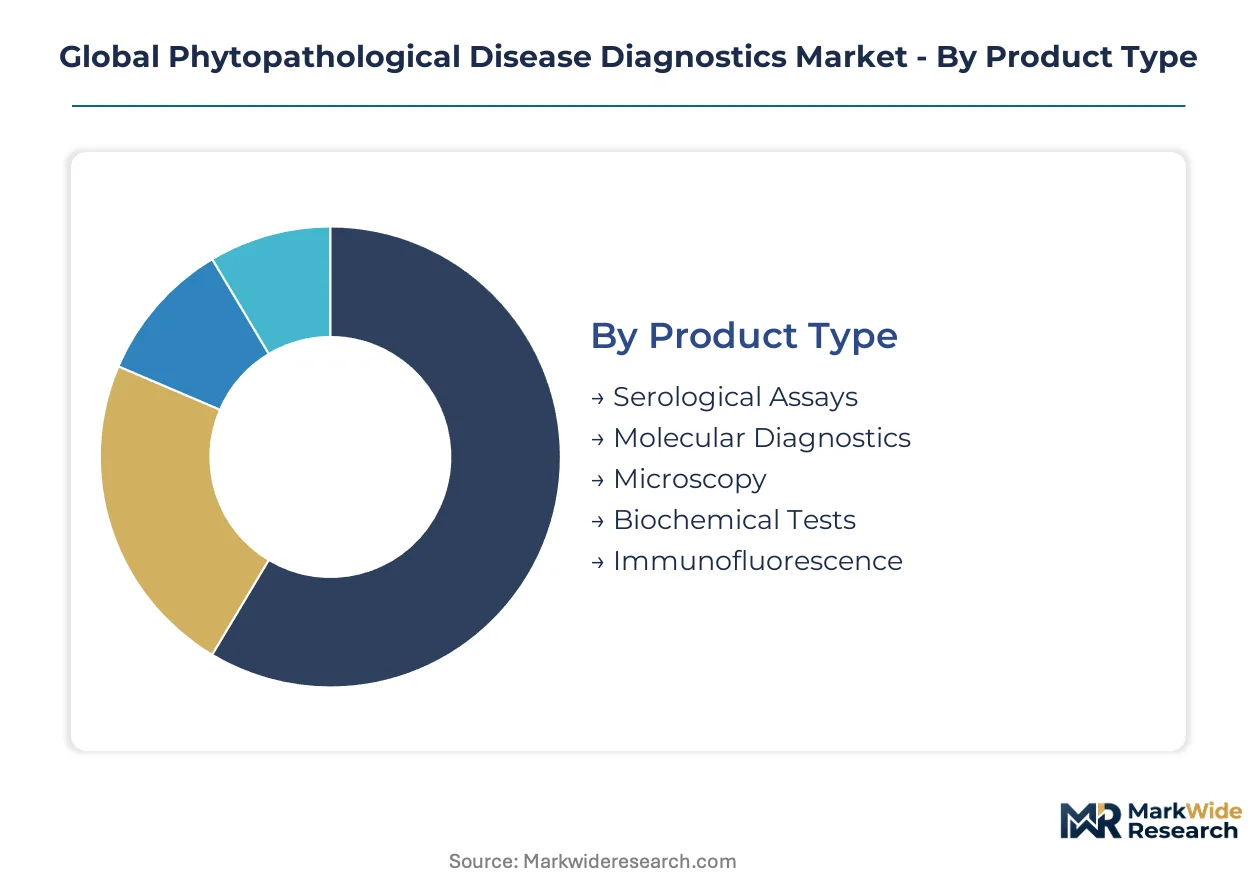
Segmentation in phytopathological diagnostics reveals divergent technology maturity curves and pricing architectures across detection modalities. Laboratories allocate capital based on throughput requirements, regulatory stringency, and field accessibility constraints.
Product Type:
Volume leadership concentrates in established serological workflows, while molecular platforms command premium positioning through multiplexing capability and quantitative precision.
- Serological Assays:Antibody-based detection methods achieve picogram-scale antigen sensitivity through ELISA and lateral flow formats. Routine screening at Brazil's seed testing facilities and India's contract research organizations sustains volume demand despite longer incubation periods than molecular alternatives.
- Molecular Diagnostics:Nucleic acid amplification platforms deliver single-copy pathogen sensitivity with 2-4 hour turnaround times. European agricultural laboratories under EFSA Regulation 2016/2031 are displacing legacy serological workflows for quarantine pathogen verification.
- Microscopy:Morphological identification remains essential for fungal pathogen classification and nematode enumeration. Resource-limited extension services in India and Brazil retain this modality for cost-constrained field verification.
- Biochemical Tests:Metabolic fingerprinting and selective media-based identification support preliminary screening in decentralized agricultural settings. These methods serve as triage tools before confirmatory molecular testing.
- Immunofluorescence:Direct visualization of labeled antibodies enables rapid pathogen localization in plant tissue sections. North American field diagnostic penetration leverages this format for on-site viral detection in perennial crops.
Mature deployment sits with Serological Assays. Newer deployment is concentrated in Molecular Diagnostics.
Technology:
Thermal cycling infrastructure requirements separate centralized laboratory dominance from field-deployable isothermal chemistry expansion.
- PCR:Quantitative real-time amplification remains the reference standard for regulatory certification across EFSA and USDA reference strain collections. Thermo Fisher Scientific's installed base penetration anchors this technology in high-throughput agricultural laboratories.
- ELISA:Enzyme-linked immunosorbent assay formats dominate routine viral screening at seed certification facilities. Agdia's immunofluorescence reagent manufacturing sustains North American field diagnostic penetration through standardized kit formats.
- LAMP:Loop-mediated isothermal amplification eliminates thermal cycling infrastructure, enabling smartphone-readable results in resource-limited settings. TwistDx's recombinase polymerase amplification chemistry accelerates adoption in Brazil's soybean belt and India's contract farming clusters.
- Biosensors:Electrochemical and optical transduction platforms integrate with IoT-enabled crop monitoring systems. Large-scale farming operations in Brazil are piloting these devices for same-day fungicide application decisions.
- Microarray Analysis:High-density pathogen detection panels support multiplex screening in breeding program quarantine facilities. Extended validation timelines against harmonized reference collections constrain commercial deployment velocity.
Established infrastructure dominates PCR and ELISA deployment. Biosensors and LAMP configurations are climbing the fastest among emerging technology adopters.
Application:
Export certification intensity and pesticide resistance pressure determine diagnostic specificity requirements across crop categories.
- Cereal Crops:Wheat and maize pathogen surveillance focuses on Fusarium species and viral complexes affecting yield and mycotoxin accumulation. Seed testing facilities in Brazil prioritize molecular verification for MAPA phytosanitary export compliance.
- Horticultural Plants:High-value vegetable and fruit production demands rapid turnaround for precision crop protection decisions. European agricultural cooperatives bundle molecular testing with biocontrol recommendations under EU Green Deal sustainability targets.
- Plantation Crops:Perennial systems including oil palm and rubber require longitudinal pathogen monitoring across multi-year production cycles. Southeast Asian plantation operators deploy portable nucleic acid platforms for field-based decision-making.
- Legumes:Soybean and bean pathogen diagnostics concentrate on seed-borne bacterial and viral transmission. Argentina's export-oriented production clusters drive contract laboratory capacity expansion for phytosanitary certification.
- Turfgrass:Nematode and fungal pathogen detection supports golf course and sports field maintenance. North American turf management services integrate point-of-need devices for immediate treatment authorization.
Diagnostic standardization is most advanced in Cereal Crops. Turfgrass and Horticultural Plants are gaining share fastest through precision agriculture integration.
End User:
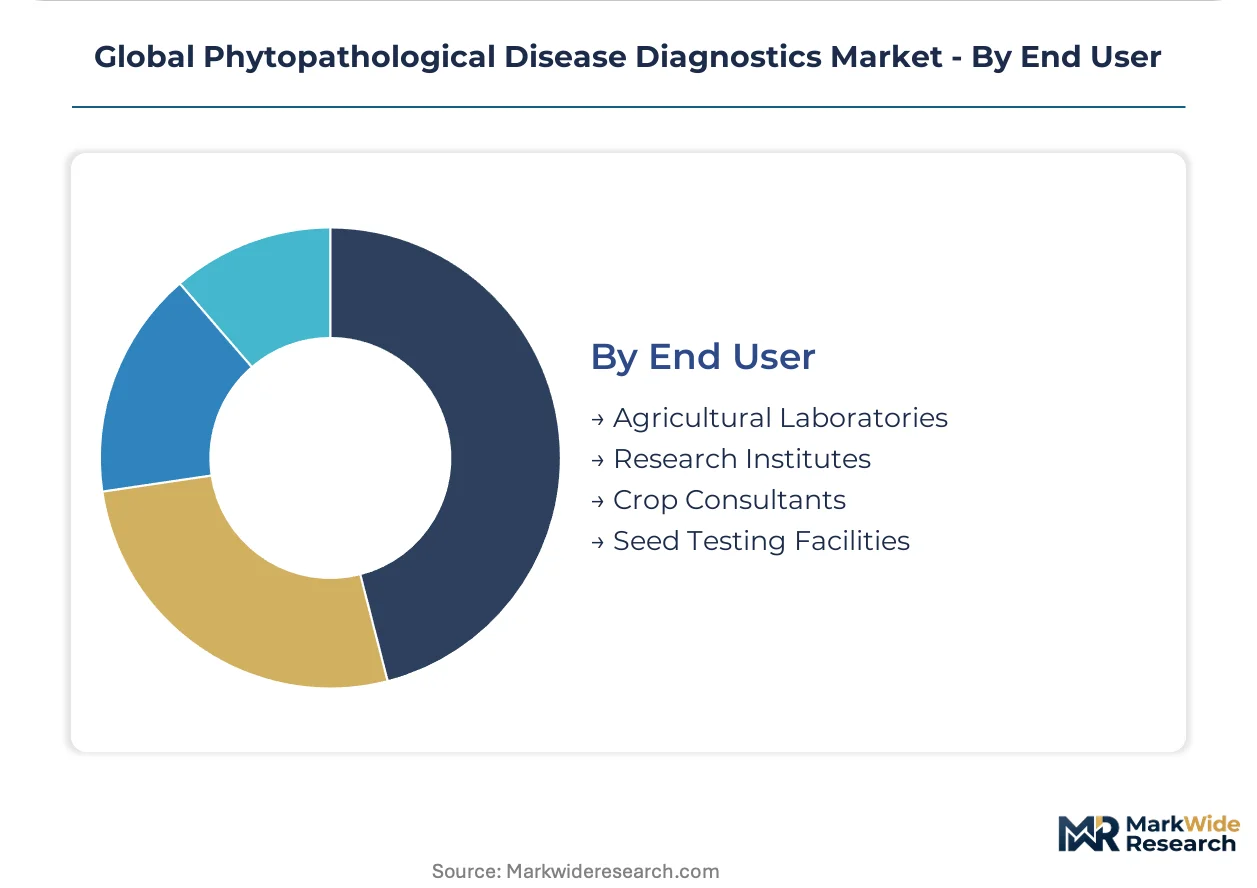
Capital intensity and technical competency requirements fragment procurement patterns between centralized laboratories and distributed field deployment.
- Agricultural Laboratories:Centralized facilities with quantitative PCR infrastructure process high-volume certification samples under BIS, GB/T, and EFSA regulatory frameworks. These operations represent the most consolidated channel with established vendor relationships.
- Research Institutes:Plant breeding programs and academic institutions drive assay development for emerging pathogen threats. CRISPR-based detection platform validation occurs primarily within these settings before commercial transfer.
- Crop Consultants:Independent advisory services integrate rapid diagnostic results with agronomic recommendations. Smartphone-readable LAMP-CRISPR hybrid platforms are penetrating this channel in India's Punjab and Kerala export clusters.
- Seed Testing Facilities:Certification compliance for international market access drives molecular diagnostic adoption. Brazil's MAPA regulatory expansion and India's APEDA mandates are accelerating capacity investment in this fastest-expanding channel.
Procurement consolidation centers on Agricultural Laboratories. Seed Testing Facilities show the steepest expansion trajectory driven by regulatory certification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's seed certification infrastructure, India's export-oriented contract research organizations, and European agricultural laboratories under harmonized quarantine frameworks. These three markets anchor procurement volume for molecular diagnostic platforms.
Brazil
MAPA phytosanitary export requirements for soybean and maize are forcing seed testing facilities to retire serological workflows. The country's national agricultural regulator mandates molecular verification for international market access. São Paulo and Paraná clusters drive capacity expansion for pathogen detection in export-oriented production belts.
India
APEDA-mandated certification for basmati rice and spice consignments is expanding contract research organization capacity. BIS seed certification standards create parallel compliance obligations for diagnostic kit validation. Punjab and Kerala export clusters are adopting smartphone-readable detection platforms for field-based verification.
Germany
EFSA plant health risk assessments under EU Regulation 2016/2031 standardize detection menu specifications across testing providers. The country's national biochemical suppliers concentrate polymerase enzyme and fluorescent probe synthesis for diagnostic manufacturers. Bavaria and North Rhine-Westphalia host agricultural laboratories displacing legacy workflows with CRISPR-based platforms.
United States
EPA biopesticide registration requirements under FIFRA shape product development priorities for diagnostic kit manufacturers. The country's national agricultural regulator enforces reference strain collection alignment for assay validation. Midwest agricultural cooperatives and California's perennial crop specialists drive field diagnostic penetration for on-site viral detection.
China
GB/T national standards for plant quarantine create compliance architectures that multinational suppliers must navigate for market entry. The country's national standards body mandates specific detection protocols for seed import certification. Yangtze River Delta agricultural testing facilities are expanding quantitative PCR capacity for domestic crop protection decisions.
Global Phytopathological Disease Diagnostics Market Competitive Landscape
North American producers anchor one tier; European specialists hold another through proprietary chemistry positions. The vendor base separates between consolidated life science conglomerates with quantitative PCR installed bases and focused biochemical suppliers with recombinase polymerase amplification expertise. Three archetypes dominate: immunofluorescence reagent manufacturers, isothermal amplification chemistry specialists, and diversified molecular platform providers. Competitive moves concentrate on technology licensing for CRISPR-guide RNA design and strategic partnerships bundling diagnostics with digital agriculture platforms.
Among the named participants, Agdia, Inc. and TwistDx Limited occupy positions representing distinct competitive vectors. Agdia exemplifies the immunofluorescence reagent manufacturing archetype sustaining field diagnostic penetration. TwistDx anchors the isothermal amplification chemistry specialization enabling resource-limited deployment. Thermo Fisher Scientific sits within the diversified platform provider tier leveraging quantitative PCR infrastructure into agricultural workflows.
| Leading Market Players |
|---|
| Agdia, Inc. |
| Creative Diagnostics |
| TwistDx Limited |
| Qualiplante SAS |
| Norgen Biotek Corp. |
| BIOREBA AG |
| Abingdon Health |
| LOEWE Biochemica GmbH |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
CRISPR-based detection platform adoption simultaneously compresses reagent manufacturing scale requirements and concentrates polymerase enzyme sourcing among German and United States biochemical suppliers, reshaping cost economics for diagnostic kit producers while amplifying input price volatility exposure.
Pricing Analysis
Volume leadership in serological assays commands thin margins at commodity price points, while molecular diagnostics platforms sustain premium positioning through multiplexing capability and quantitative precision. Pricing stratifies across premium, standard, and economy tiers based on certification grade against EFSA and USDA reference strain collections and volume scale of seed testing facility procurement. Cost compression in the serological tier is intensifying because Brazilian and Indian laboratories are retiring legacy workflows faster than manufacturers can restructure production. Agricultural laboratories with established quantitative PCR infrastructure exhibit lowest price sensitivity, while mid-size crop consultants in India's contract farming clusters demonstrate highest elasticity to per-test costs.
Supply Chain Analysis
EFSA Regulation 2016/2031 harmonized quarantine pathogen list compliance gates supplier qualification, forcing diagnostic manufacturers to validate assay components against reference strain collections before commercial deployment. Polymerase enzymes and fluorescent probe synthesis concentrate in Germany and the United States, while CRISPR guide RNA manufacturing scales through contract research organizations in India and China. Single-source vulnerability runs through specialized biochemical suppliers for recombinase polymerase amplification chemistry, exposing TwistDx Limited and similar specialists to input disruption. Distribution runs through agricultural laboratory procurement channels with consolidated vendor relationships, though seed testing facilities are fragmenting toward direct manufacturer relationships as capacity expands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around molecular platform providers with validated CRISPR-guide RNA intellectual property, as regulatory compliance costs and extended validation timelines force serological assay specialists toward exit or acquisition.
For Market Incumbents: Lock in exclusive supply agreements with German and United States polymerase enzyme manufacturers to secure input cost stability against reagent supply concentration. Anchor competitive position through proprietary guide RNA design portfolios that accelerate CRISPR-based detection platform validation against EFSA and USDA reference strain collections, displacing smaller immunofluorescence reagent suppliers unable to fund multiplex assay development timelines. For New Entrants and Emerging Players: Enter via LAMP-CRISPR hybrid platform development for smartphone-readable field diagnostics, targeting India's Punjab and Kerala export clusters where APEDA-mandated certification is expanding contract research organization capacity. Penetrate the crop consultant advisory channel with portable nucleic acid detection devices bundled with agronomic recommendation services, exploiting technical competency gaps in traditional agricultural extension workforces. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking quantitative PCR installed base extension into agricultural workflows. Five-to-ten year viability favors isothermal amplification chemistry specialists with validated recombinase polymerase amplification platforms over legacy serological assay manufacturers facing workflow displacement. Monitor convergence velocity between digital agriculture platforms and point-of-need diagnostics as inflection indicator for bundled disease management system procurement criteria adoption.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Guide RNA IP Acquisition | Consolidates molecular diagnostic workflows around single-molecule sensitivity platforms displacing ELISA suppliers. |
| Isothermal Amplification Chemistry Licensing | Enables field-deployable pathogen detection without thermal cycling infrastructure in Brazil's soybean belt. |
| Digital Agriculture Platform Integration | Bundles point-of-need diagnostics with IoT-enabled crop monitoring for same-day fungicide decisions. |
| Seed Testing Facility Capacity Partnership | Secures molecular diagnostic adoption driven by MAPA phytosanitary export requirements in São Paulo clusters. |
| EFSA Reference Strain Collection Alignment | Validates multiplex assay panels against harmonized quarantine pathogen lists under EU Regulation 2016/2031. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining with primary interviews with diagnostic kit manufacturing executives, agricultural laboratory procurement managers, seed testing facility directors, and CRISPR platform R&D leads. EPA biopesticide registration filings under FIFRA, EFSA plant health risk assessments, India's BIS seed certification standards, and China's GB/T national standards provided regulatory validation. Bottom-up test volume modeling across Brazilian seed certification facilities and Indian contract research organizations triangulated against top-down molecular diagnostic platform revenue estimates.
Granularity-level modeling deployed test volume and pricing by product type, technology platform, crop application, and end-user channel across the analysis window. Serological assay and molecular diagnostics splits were projected with technology displacement curves calibrated to CRISPR-based detection platform adoption rates in European agricultural laboratories. Cereal crop, horticultural plant, and plantation crop application segments incorporated export certification intensity and pesticide resistance pressure differentials.
Revisions become necessary when EFSA or USDA expands harmonized quarantine pathogen lists, accelerating assay revalidation requirements, or when polymerase enzyme supply disruptions alter reagent cost structures. A model refresh is warranted upon material change in digital agriculture platform convergence with point-of-need diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Allergy Diagnostics Market