
 Liquid Oxygen Devices Market | 2026-2036
Liquid Oxygen Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Oxygen Devices Market Analytics
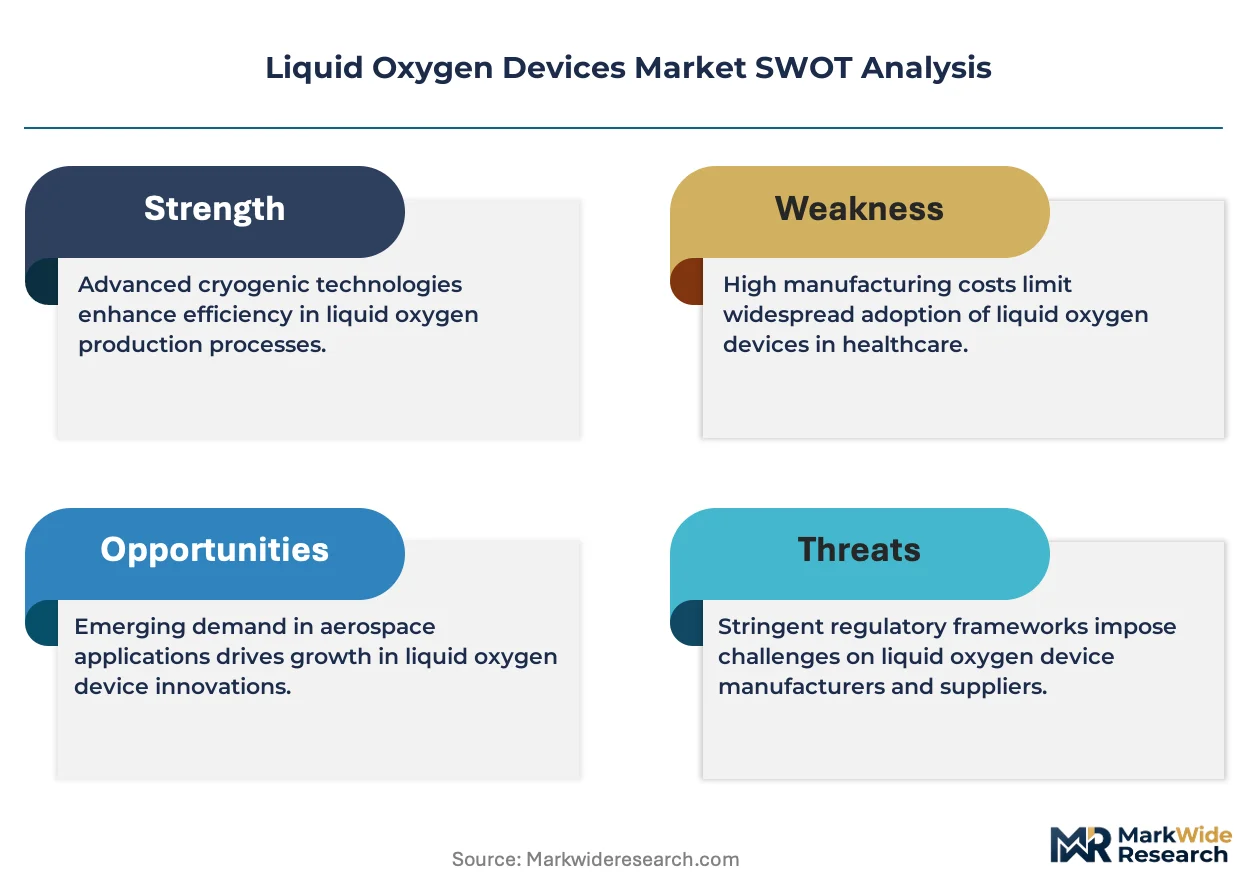
Project finance and equipment leasing for cryogenic infrastructure is tilting competitive dynamics toward asset-light operators. Linde plc leverages captive production of industrial gases to sustain margin structures across liquid oxygen supply chains. Chart Industries Inc. anchors its position through specialized vacuum-insulated tank manufacturing that dominates hospital and home care segments. CAIRE Inc. differentiates via portable system specialization that navigates reimbursement complexity in North American markets.
Liquid oxygen devices are cryogenic systems engineered to store and deliver oxygen at temperatures below minus 183 degrees Celsius, utilizing vacuum-insulated double-wall construction to minimize boil-off losses during storage and transport. These systems serve critical functions in medical oxygen therapy, industrial gas supply, and aerospace life support where high-purity oxygen delivery at controlled flow rates is essential. Portable systems lead product type revenue pools due to home care migration and ambulatory patient preference, while stationary systems retain institutional anchoring in hospitals. Cryogenic cooling technology occupies the dominant technology position, though vacuum insulation is gaining traction as efficiency standards tighten across medical and industrial end users.
FDA medical device regulations and EU MDR conformity requirements shape product certification timelines and barrier structures for new entrants in medical liquid oxygen segments. ISO 13485 quality management standards and OSHA workplace exposure limits further constrain system design and operational protocols across manufacturing and end-use environments. Stakeholders must monitor evolving reimbursement codes for home oxygen therapy and industrial carbon intensity thresholds that will reshape equipment replacement cycles and technology investment priorities.
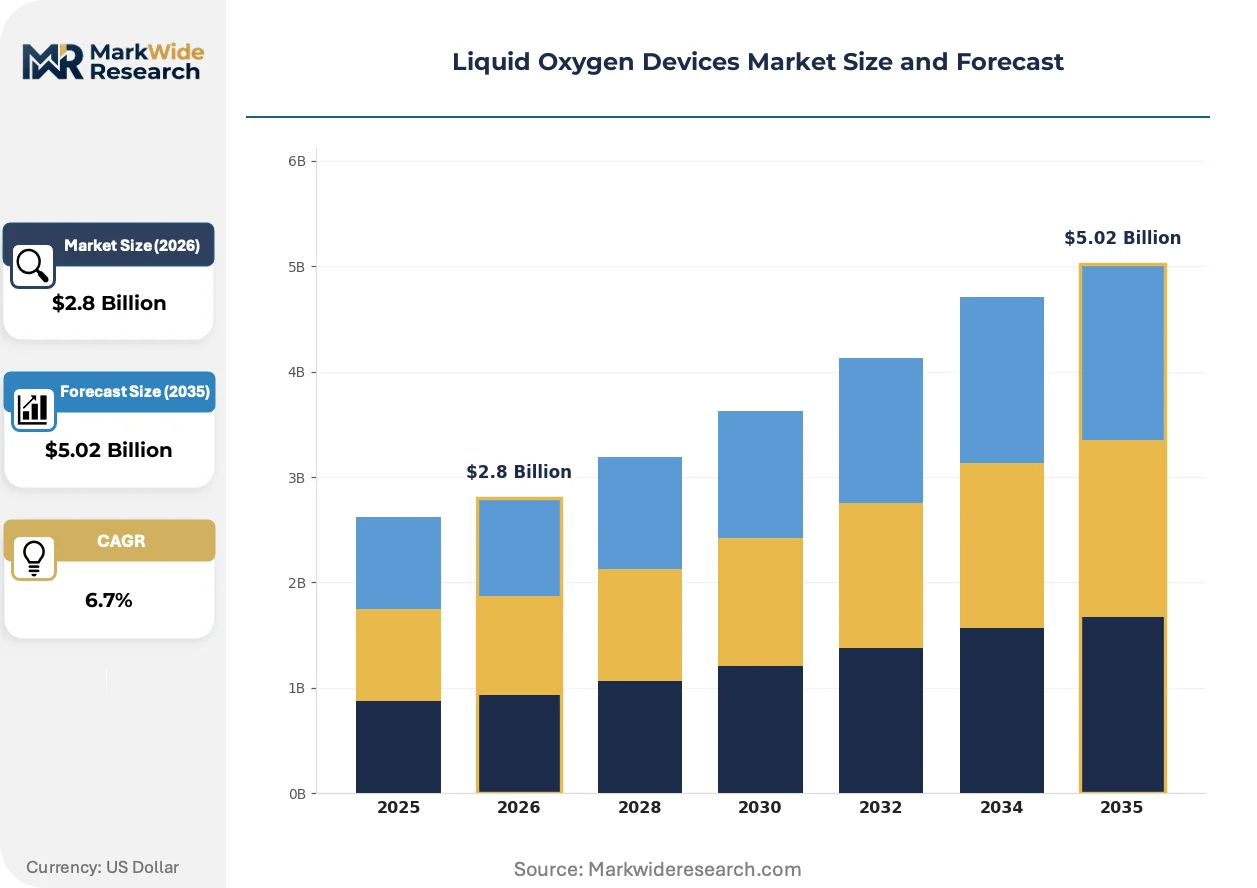
Market Dynamics
Home care migration is compressing hospital-based stationary system demand while portable oxygen concentrators capture ambulatory patient volumes, forcing manufacturers to rebalance production capacity toward lightweight cryogenic vessels and away from bulk institutional tanks.
Growth Catalysts
- Ambulatory Patient Preference:Medicare reimbursement codes for portable oxygen therapy in the United States incentivize home care providers to deploy lightweight liquid oxygen systems for COPD patients requiring mobility.
- EU MDR Quality Mandates:Stricter conformity assessment pathways for medical oxygen equipment under the Medical Device Regulation are accelerating replacement cycles for legacy systems across German and French hospital networks.
- Vacuum-Insulated Tank Efficiency:Advances in multi-layer insulation technology reduce boil-off losses below 0.5% daily, extending storage duration for rural home care deliveries and reducing refill frequency.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 75% of global helium production, creating input cost volatility for super-insulated cryogenic vessel manufacturing.
- FDA 510(k) Pathway Friction:Substantial equivalence determinations for new portable oxygen concentrators average 180 days, delaying product launches and freezing development budgets.
- Compressed Gas Substitution:High-pressure cylinder systems with integrated conservation devices compete directly with liquid oxygen for stationary home therapy, particularly where delivery infrastructure is sparse.
Strategic Opportunities
- Japanese Aging Demographics:METI forecasts 30% of Japan's population over 65 by 2035, creating concentrated demand for home-based oxygen therapy in Tokyo and Osaka metropolitan corridors.
- Industrial Carbon Thresholds:EU Green Deal carbon intensity benchmarks for steel and chemical production are mandating oxygen-enriched combustion retrofits, expanding non-medical equipment demand.
- Remote Patient Monitoring Convergence:Integration of liquid oxygen flow sensors with telehealth platforms enables real-time adherence tracking and predictive refill scheduling for home care agencies.
Industry Challenges
- Cryogenic Welding Certification:ASME Section IX qualification for stainless steel vessel fabrication requires 2,000+ hour apprenticeship pipelines that lag current hiring needs in North American manufacturing.
- Legacy System Interoperability:Hospital oxygen manifold installations from the 1990s utilize incompatible connection standards that complicate portable system docking and patient transfer protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Oxygen Devices Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Stationary Systems, Liquid Oxygen Tanks, Gas Delivery Systems End User: Hospitals, Home Care Providers, Emergency Services, Industrial Applications Technology: Cryogenic Cooling, Pressure Swing Adsorption, Vacuum Insulation, Static Storage Application: Medical Use, Aerospace, Welding, Aquaculture |
| Companies Covered | Air Liquide S.A., Linde plc, Chart Industries Inc., CAIRE Inc., Invacare Corporation, Teijin Limited, Cryofab Inc., Taylor-Wharton International LLC, DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Oxygen Devices Market Evolving Landscape
Active technological substitution across insulation materials, regulatory digitization of quality systems, and procurement model fragmentation are simultaneously compressing equipment margins and opening service revenue streams for adaptive suppliers.
Multi-layer vacuum insulation is migrating from aerospace-derived aluminized Mylar films toward aerogel-composite interlayers that halve thermal conductivity at equivalent thickness. Japanese home care providers are piloting these systems for weekly-refill rural deployments. The technology is migrating from premium aerospace applications into standard medical product tiers, compressing differentiation windows for incumbent vessel manufacturers.
EU MDR electronic quality management system requirements are mandating real-time post-market surveillance data collection for Class IIb oxygen devices. German notified bodies now require automated adverse event reporting integration before CE marking approval. Portable system manufacturers serving European markets are restructuring regulatory affairs departments to maintain continuous compliance rather than periodic recertification cycles.
Hospital procurement departments are unbundling oxygen equipment acquisition from long-term gas supply contracts, reversing decades of bundled pricing structures. Independent home care distributors in the United States are capturing direct purchasing relationships with skilled nursing facilities, displacing incumbent industrial gas suppliers. This fragmentation is most visible in Texas and Florida, where deregulated healthcare markets enable rapid channel switching based on equipment leasing terms rather than gas pricing.
Liquid Oxygen Devices Market Segmentation
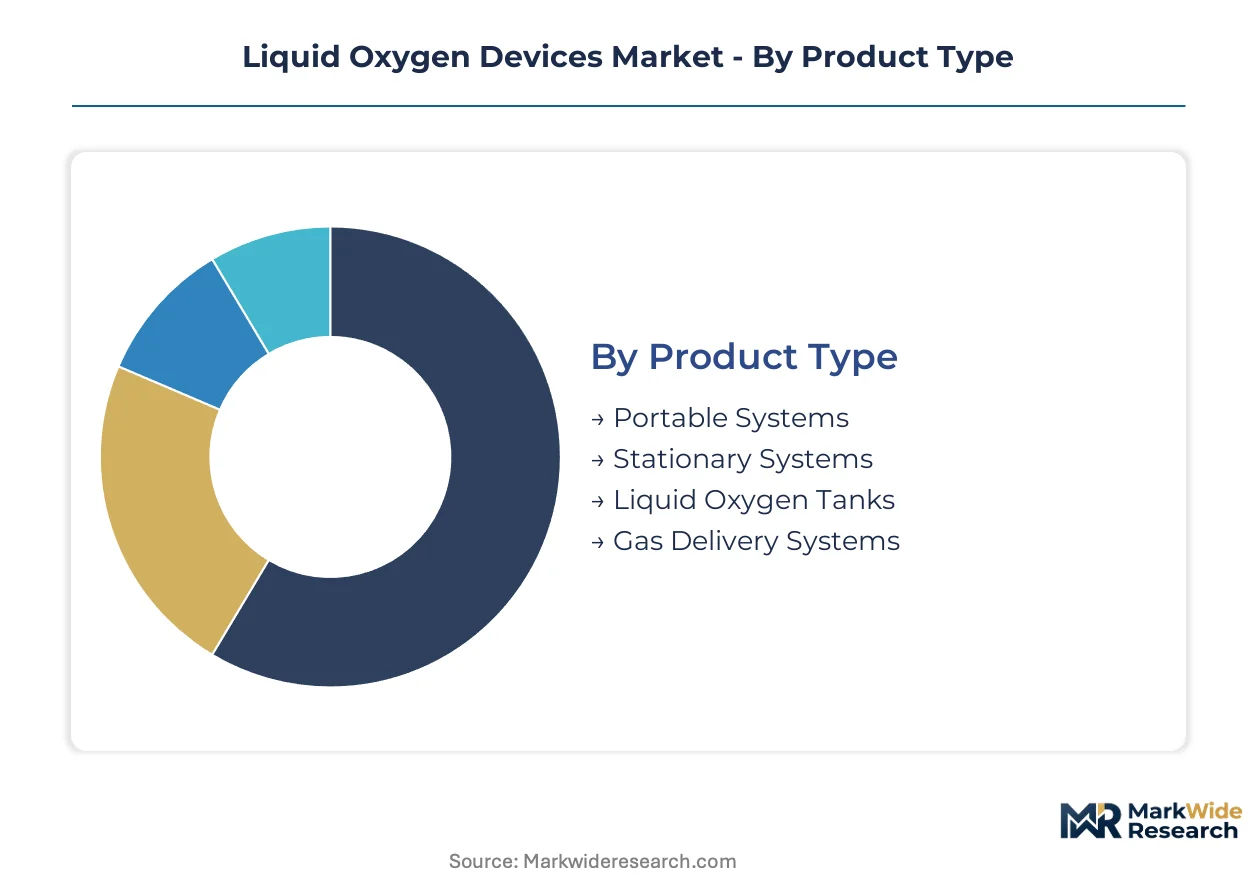
Segmentation in liquid oxygen devices reveals how technology specialization and end-use requirements fragment manufacturing priorities. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning across medical, industrial, and aerospace verticals.
Product Type:
Cost tier differentiation separates premium cryogenic engineering from commodity vessel fabrication, with reimbursement codes and delivery frequency determining which configurations capture profitable volume.
- Portable Systems:Lightweight vacuum-insulated vessels under 10 pounds enable ambulatory oxygen therapy for COPD patients. Medicare reimbursement in the United States concentrates demand among home care agencies serving rural corridors where refill logistics dominate operational costs.
- Stationary Systems:Bulk storage tanks exceeding 100-liter capacity anchor hospital oxygen supply infrastructure. German hospital networks under EU MDR replacement mandates are accelerating upgrade cycles for legacy manifold connections.
- Liquid Oxygen Tanks:Intermediate-capacity vessels bridge home and institutional use with weekly refill intervals.
- Gas Delivery Systems:Vaporizer and regulator assemblies control flow rates from cryogenic storage to point-of-use.
Portable systems hold installed capacity. Stationary systems are rotating up the share rankings.
End User:
Application context determines performance specifications, with life-safety medical deployments imposing stricter quality protocols than industrial oxygen supply.
- Hospitals:Centralized oxygen supply systems require 99.5% purity with redundant backup capacity for surgical suites and intensive care units. French hospital procurement unbundling is separating equipment acquisition from long-term gas contracts.
- Home Care Providers:Distributed delivery models prioritize lightweight portability and extended duration between refills. Japanese metropolitan corridors face concentrated demand from aging demographics requiring mobility-enabled therapy.
- Emergency Services:Rapid-deployment systems for ambulances and field hospitals emphasize durability under transport vibration.
- Industrial Applications:Steel and chemical production oxygen-enriched combustion retrofits drive non-medical equipment demand under EU Green Deal carbon intensity benchmarks.
Hospitals retain the dominant revenue base. Home care providers are gaining share fastest.
Technology:
Volume efficiency separates incumbent cryogenic methods from emerging alternatives, with insulation performance determining boil-off losses and delivery economics.
- Cryogenic Cooling:Standard liquefaction systems compress and cool atmospheric oxygen to minus 183 degrees Celsius for storage and transport. Qatar helium supply concentration creates input cost volatility for super-insulated vessel manufacturing.
- Vacuum Insulation:Multi-layer aluminized Mylar and aerogel-composite interlayers reduce thermal conductivity below 0.005 W/mK. Japanese rural deployments are piloting weekly-refill systems using advanced interlayer technology.
- Pressure Swing Adsorption:On-site oxygen generation from compressed air competes with liquid delivery for stationary institutional use.
- Static Storage:Non-mechanical retention of cryogenic liquid minimizes moving parts and maintenance requirements.
Cryogenic cooling holds installed capacity. Vacuum insulation is rotating up the share rankings.
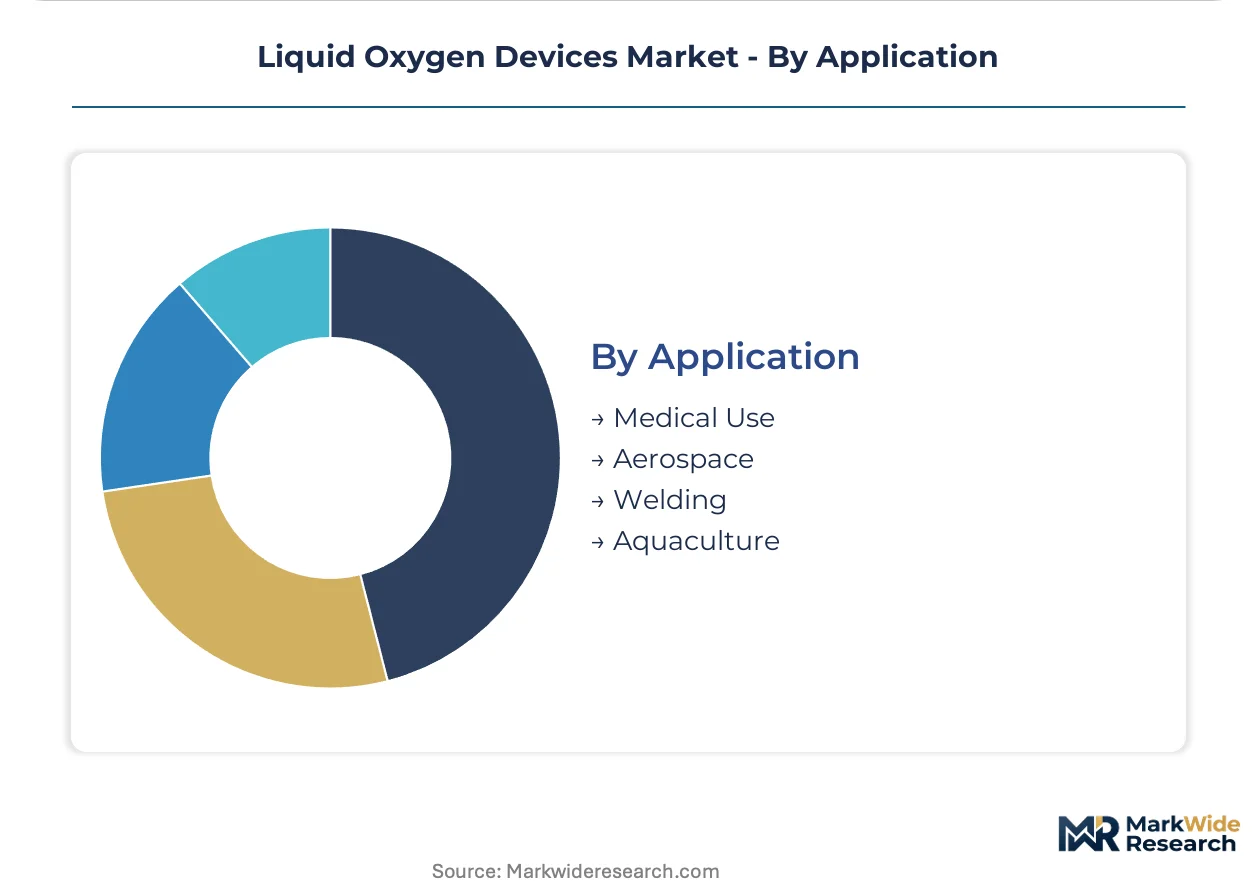
Application:
Customer type maturity separates regulated medical markets from emerging industrial and specialty deployments with diverging certification timelines.
- Medical Use:FDA 510(k) and EU MDR pathways govern oxygen therapy devices with Class IIb conformity requirements. German notified bodies now mandate automated adverse event reporting integration before CE marking approval.
- Aerospace:Life support systems for crewed spacecraft and high-altitude aircraft demand extreme reliability under vibration and acceleration loads.
- Welding:Oxy-fuel cutting and gas metal arc welding processes consume industrial oxygen for flame temperature elevation.
- Aquaculture:Dissolved oxygen supplementation for intensive fish farming represents a developing application with limited standardization.
Medical use holds installed capacity. Aerospace is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement codes and EU MDR replacement mandates are redistributing liquid oxygen device demand across aging populations and tightening regulatory jurisdictions. National procurement unbundling and home care migration create divergent growth trajectories by market maturity.
United States
Medicare portable oxygen therapy reimbursement incentivizes home care agencies to deploy lightweight systems for ambulatory COPD patients. FDA 510(k) pathway friction averages 180 days for substantial equivalence determinations, freezing development budgets. Texas and Florida deregulated healthcare markets enable rapid channel switching based on equipment leasing terms.
Germany
EU MDR conformity assessment pathways accelerate replacement cycles for legacy hospital manifold systems. German notified bodies mandate automated adverse event reporting integration before CE marking approval for Class IIb oxygen devices. Bavarian hospital networks under replacement mandates are separating equipment acquisition from long-term gas supply contracts.
Japan
METI forecasts 30% of the population over 65 by 2035, concentrating demand for mobility-enabled home oxygen therapy. PMDA quality management standards govern medical device certification timelines for domestic and imported equipment. Tokyo and Osaka metropolitan corridors face acute demand pressure from aging demographics requiring weekly-refill rural deployment systems.
France
Hospital procurement unbundling reverses decades of bundled oxygen equipment and gas supply contracting. ANSM post-market surveillance requirements align with EU MDR electronic quality management system mandates. Paris-region hospital networks are piloting unbundled acquisition models that separate vessel procurement from long-term industrial gas relationships.
United Kingdom
NHS home oxygen service reforms prioritize portable system deployment for ambulatory patient populations. MHRA conformity assessment maintains alignment with EU MDR standards post-Brexit transition. London and Southeast England home care distributors are capturing direct purchasing relationships with skilled nursing facilities.
Liquid Oxygen Devices Market Competitive Landscape
On the supply side, the industry is consolidating around industrial gas majors with captive cryogenic production and specialized vessel fabricators with vacuum insulation expertise. Tiered competitive dynamics separate scale-driven gas suppliers from technology-focused equipment specialists. Strategic archetypes include integrated industrial gas conglomerates, specialized cryogenic vessel manufacturers, and portable system specialists navigating reimbursement complexity. Dominant competitive moves encompass backward integration into captive helium supply and geographic expansion through distribution partnerships.
Among integrated industrial gas suppliers, Linde plc and Air Liquide S.A. exemplify scale-driven archetypes leveraging captive production networks. Chart Industries Inc. and Cryofab Inc. represent specialized vessel fabricators with vacuum insulation expertise. CAIRE Inc. occupies a position within the portable system specialist tier. Teijin Limited anchors Japanese market presence through materials science capabilities. Taylor-Wharton International LLC and Invacare Corporation sit within durable medical equipment diversification strategies, while DeVilbiss Healthcare represents respiratory therapy portfolio positioning.
| Leading Market Players |
|---|
| Air Liquide S.A. |
| Linde plc |
| Chart Industries Inc. |
| CAIRE Inc. |
| Invacare Corporation |
| Teijin Limited |
| Cryofab Inc. |
| Taylor-Wharton International LLC |
| DeVilbiss Healthcare |
| Others |
Value Network & Pricing Analysis
Undercapacity in North American cryogenic vessel fabrication is pushing lead times past 18 months for FDA-grade portable systems, compressing margins for distributors while granting pricing leverage to qualified manufacturers with ASME-certified welding pipelines.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared portable systems and uncertified industrial-grade vessels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 quality management investment, EU MDR conformity assessment costs, and helium-insulated super-vacuum engineering. Pricing pressure stems from compressed gas cylinder substitution in rural home care markets where delivery infrastructure remains sparse. Medicare-reimbursed home care agencies exhibit highest price sensitivity, while hospital procurement committees prioritize redundancy and purity specifications over unit cost.
Supply Chain Analysis
Export control regimes on super-insulated cryogenic technology limit vacuum-insulation manufacturing equipment transfers to Chinese and Russian end-users, constraining capacity expansion outside established jurisdictions. Production concentrates in the United States, Germany, and Japan where ASME Section IX welding certification and EU MDR notified body proximity anchor fabrication. Supply chains draw from Qatari and US helium feedstock, Japanese stainless steel precision rolling, and German multi-layer insulation film lamination. Single-source vulnerability runs through helium supply concentration, with Qatar and the United States controlling over three-quarters of global production. Distribution runs through industrial gas majors with captive cryogenic production networks and independent home care distributors capturing direct skilled nursing facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed gas oxygen concentrators pose a direct substitution threat to liquid oxygen portable systems, forcing incumbents to defend reimbursement-linked installed bases while new entrants seek white-space in industrial carbon-intensity retrofit markets.
For Market Incumbents: Harden FDA 510(k) clearance pipelines against compressed gas substitution by embedding flow sensors with telehealth platforms for real-time adherence tracking. Deepen backward integration into captive helium supply through long-term offtake agreements with Qatari producers, insulating margin structures from input volatility. Secure ASME-certified welding apprenticeship pipelines in Texas and Florida manufacturing corridors to sustain capacity utilization above competitor levels. For New Entrants and Emerging Players: Establish a beachhead in EU Green Deal oxygen-enriched combustion retrofit markets for steel and chemical production, where carbon intensity benchmarks mandate equipment replacement without entrenched gas supply relationships. Target Japanese metropolitan corridors facing acute aging demographic pressure, leveraging PMDA quality management consulting partnerships to accelerate domestic certification timelines. Pursue unbundled hospital procurement relationships in Bavarian and Paris-region networks separating vessel acquisition from long-term industrial gas contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum-insulated portable system manufacturing due to EU MDR electronic quality management system mandates and multi-layer aerogel-composite insulation R&D requirements. Acquisition target archetypes include specialized cryogenic vessel fabricators with ASME Section IX qualification and established notified body relationships, positioned between integrated industrial gas majors and durable medical equipment distributors. Watch for helium supply contract renegotiation cycles as inflection indicators for margin compression or expansion across the equipment supply chain.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Helium Supply | Captive feedstock access insulates margin structures from Qatar-US production concentration volatility. |
| EU MDR Electronic Quality Management System Deployment | Automated adverse event reporting integration satisfies German notified body mandates for Class IIb CE marking. |
| Telehealth Platform Sensor Integration | Real-time flow monitoring enables predictive refill scheduling for Medicare-reimbursed home care agencies. |
| Aerogel-Composite Insulation R&D Investment | Japanese rural weekly-refill pilots demonstrate path to halve thermal conductivity below aluminized Mylar baselines. |
| ASME Welding Certification Pipeline Expansion | 2,000-hour apprenticeship programs address North American manufacturing capacity constraints extending lead times. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital GPO contracts managers, home care agency procurement directors, and cryogenic vessel fabrication plant managers converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body conformity assessment records, CMS Medicare reimbursement code filings, and METI demographic projection datasets. Bottom-up patient population modeling and top-down industrial gas supply chain analysis were triangulated against equipment shipment customs records.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, end user, technology, and application dimensions. CAGRs were derived from installed base replacement cycles, reimbursement policy elasticity estimates, and carbon intensity regulatory threshold implementation timelines. Forecast inputs incorporated COPD prevalence epidemiology, helium supply contract renewal schedules, and EU Green Deal oxygen-enriched combustion retrofit mandates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, helium spot pricing, or EU MDR enforcement intensity would shift the trajectory materially. Forecasts reflect documented assumptions regarding patient mobility preferences and hospital procurement unbundling velocity. Material shifts in FDA 510(k) substantial equivalence determination timelines or Qatar helium export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market