
 US Semi-Trailer Dealership Market | 2026-2036
US Semi-Trailer Dealership Market Size, Share, and Industry Trends Forecast 2026-2036
US Semi-Trailer Dealership Market Intelligence
Fleet operators is rotating toward refrigerated and specialized trailer configurations as cold-chain logistics and pharmaceutical transport expand. Wabash National Corporation leverages its manufacturing scale to dominate the dry van segment through captive production networks. Utility Trailer Manufacturing Company sustains brand strength in dealer channel control across the Sun Belt. Great Dane anchors its position through product specialization in temperature-controlled platforms for foodservice distributors.
A semi-trailer dealership functions as a commercial intermediary that procures, inventories, and retails tractor-detached freight trailers typically rated for gross vehicle weights exceeding ten thousand pounds, with structural configurations including steel-aluminum composite frames, air-ride suspension systems, and aerodynamic skirt packages designed to reduce drag coefficients. The primary commercial purpose centers on enabling motor carriers and private fleets to acquire capital equipment without direct manufacturer engagement, while bundling financing, warranty administration, and aftermarket service. Dry van and refrigerated product types command the largest margin pools due to standardized replacement cycles and premium pricing on insulation-equipped units, while flatbed configurations face mature demand tied to cyclical construction activity. Dealer networks and direct sales channels compete for fleet procurement volume, with dealer networks retaining advantage in relationship-based account management and localized service bundling.
The EPA regulates trailer aerodynamics and tire rolling resistance under Phase 2 and Phase 3 greenhouse gas standards, while NHTSA governs brake system performance and conspicuity requirements under Federal Motor Vehicle Safety Standards. FMCSA hours-of-service rules and electronic logging device mandates shape fleet utilization rates and replacement timing, directly influencing dealership order patterns. Stakeholders must monitor how California Air Resources Board waivers and potential federal preemption disputes reshape equipment compliance costs and inventory planning horizons.
Market Dynamics
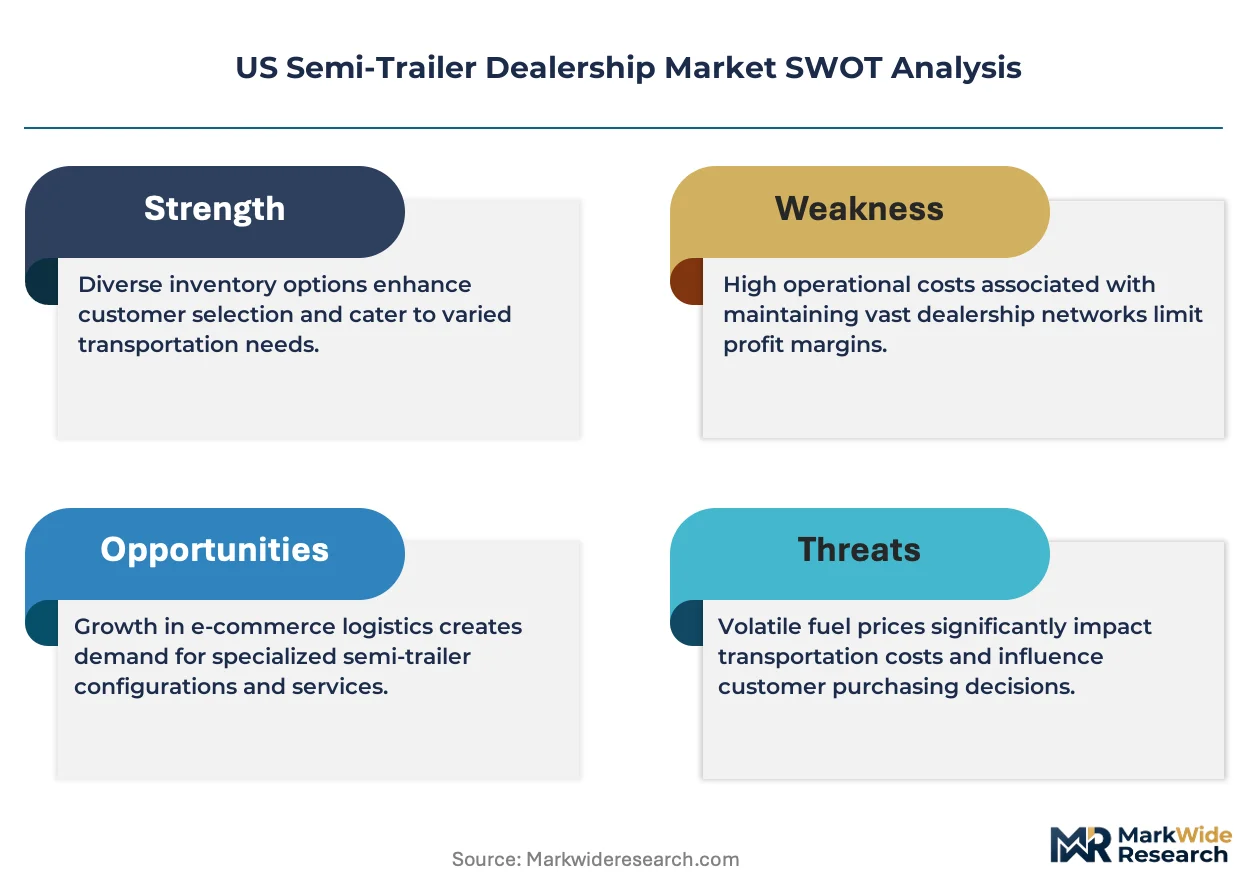
Fleet electrification timelines and EPA Phase 3 greenhouse gas standards are compressing replacement cycles while forcing dealerships to reconfigure inventory toward aerodynamic, low-emission trailer platforms.
Growth Catalysts
- Refrigerated trailer demand:Cold-chain logistics expansion for pharmaceutical and foodservice distribution is pulling specialized inventory through dealer channels.
- EPA Phase 3 standards:Federal greenhouse gas regulations mandate aerodynamic skirt packages and low-rolling-resistance tires, accelerating equipment turnover.
- Texas port activity:Gulf Coast energy-sector freight and containerized imports sustain heavy equipment procurement velocity in the South Central region.
Market Restraints
- Aluminum sheet volatility:Input cost swings for steel-aluminum composite frames compress margin predictability across dry van inventory.
- Axle and suspension supply concentration:Dependence on concentrated Midwest component suppliers creates vulnerability to production bottlenecks.
- Electric tractor-trailer mismatch:Battery-electric tractor deployment lags compatible trailer infrastructure, stranding electrified inventory investment.
Strategic Opportunities
- Telematics integration:Sensor-equipped reefers and dry vans enable predictive maintenance contracts, shifting dealer revenue toward recurring service streams.
- California CARB waivers:State-level zero-emission mandates ahead of federal timelines create premium positioning for compliant inventory in Western markets.
- Used equipment remarketing:Standardized replacement cycles generate predictable off-lease volume for certified pre-owned programs.
Industry Challenges
- Diesel technician scarcity:Maintenance departments face recruitment gaps for powertrain and after-treatment system specialists.
- FMCSA compliance documentation:Electronic logging device integration and hours-of-service recordkeeping require ongoing dealer staff training investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Semi-Trailer Dealership Market |
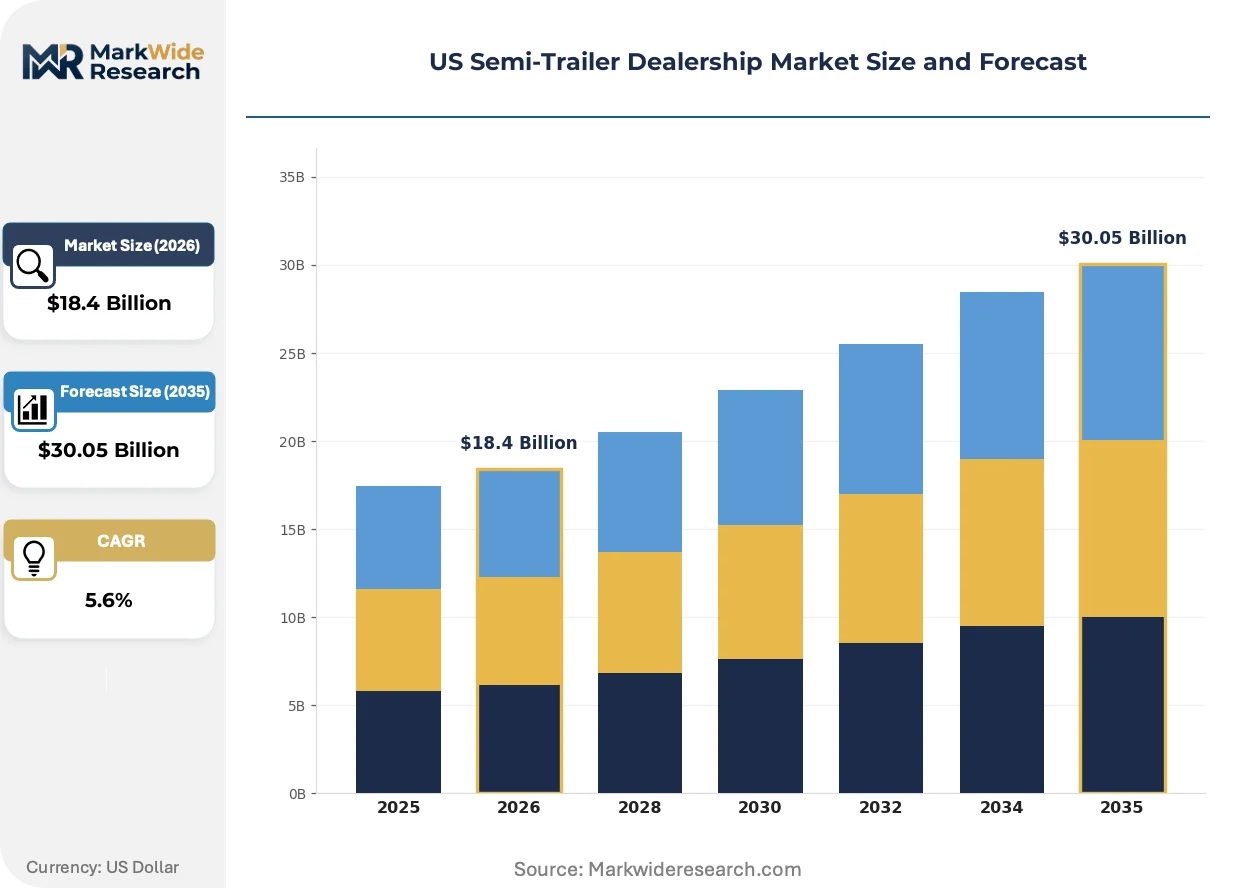
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.05 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Refrigerated, Dry Van, Tanker End User: Logistics Companies, Freight Carriers, Construction, Agriculture Sales Channel: Direct Sales, Online Sales, Auctions, Dealer Networks Service Type: Maintenance, Financing, Leasing, Trade-ins |
| Companies Covered | Northeast Great Dane, Valley Equipment, Mid-States Utility Trailer Sales, Wabash National Corporation, Utility Trailer Manufacturing Company, Utility Trailer of Texas, Great Dane, Hyundai Translead, Double A Utility Trailer Sales, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Semi-Trailer Dealership Market Strategic Shifts & Innovations
Digital freight matching platforms and embedded trailer telematics are rewiring how fleets spec, procure, and maintain capital equipment outside traditional sales relationships.
Advanced aerodynamic skirt systems are miniaturizing. These composite undercarriage fairings reduce drag coefficients for dry van configurations. Foodservice distributors and pharmaceutical carriers are specifying them on new orders. The technology is miniaturizing component footprints while maintaining performance, allowing retrofit compatibility with legacy chassis.
EPA Phase 3 greenhouse gas standards tighten trailer-specific fuel efficiency requirements through 2032. The rule mandates automatic tire inflation systems and aerodynamic device verification. Refrigerated trailer operators face the steepest compliance cost escalation, driving demand for factory-installed compliant packages over aftermarket retrofits.
Fleet procurement departments are consolidating vendor relationships and demanding lifecycle cost guarantees. Large motor carriers now negotiate total cost of ownership contracts bundling acquisition, maintenance, and residual value protection. This behavior concentrates volume with multi-location dealership groups possessing service network density, particularly visible among Texas and California based fleets.
US Semi-Trailer Dealership Market Segmentation
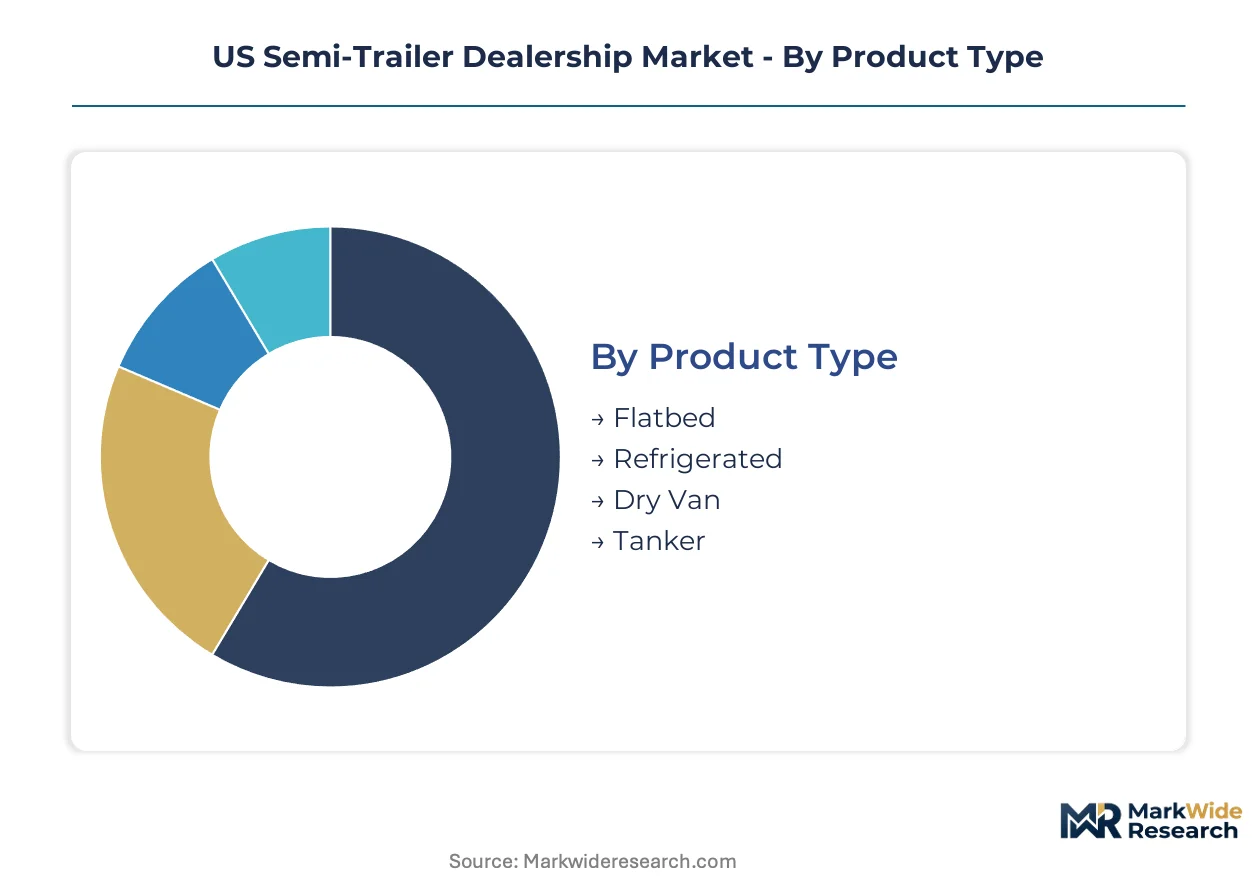
Segmentation in the US semi-trailer dealership market determines inventory financing structures, service bundling economics, and regulatory compliance pathways. Each dimension shapes how dealerships allocate capital across aerodynamic platforms and temperature-controlled configurations.
Product Type:
EPA Phase 3 greenhouse gas standards impose differentiated aerodynamic and tire rolling resistance requirements across structural configurations, altering procurement economics and replacement cycle timing.
- Dry Van:Steel-aluminum composite frames with air-ride suspension systems dominate fleet procurement volume. Texas-based freight carriers and Gulf Coast logistics operators sustain heavy turnover for standardized box configurations serving containerized import corridors.
- Refrigerated:Insulated composite panels with integrated refrigeration units command premium pricing through cold-chain pharmaceutical distribution and foodservice logistics. California CARB waiver compliance adds zero-emission refrigeration specifications for Western market penetration.
- Flatbed:Open-deck steel configurations serve cyclical construction and energy-sector freight demand concentrated in South Central states.
- Tanker:Specialized cylindrical vessels for liquid bulk transport face NHTSA conspicuity and brake system performance mandates under FMVSS regulations.
Established volume favors dry van configurations; emerging adoption favors refrigerated platforms with integrated telematics.
End User:
Customer procurement scale determines whether dealerships deploy direct sales teams or relationship-based account management across multi-location service networks.
- Logistics Companies:Third-party providers consolidate vendor relationships and negotiate total cost of ownership contracts bundling acquisition, maintenance, and residual value protection. These operators concentrate procurement with dealership groups possessing dense service footprints in Texas and California.
- Freight Carriers:Asset-based motor carriers face FMCSA hours-of-service and electronic logging device mandates that compress equipment utilization rates and accelerate replacement timing. Fleet standardization programs favor aerodynamic skirt packages compliant with federal greenhouse gas regulations.
- Construction:Project-based demand for flatbed configurations tracks regional infrastructure spending cycles and energy-sector development.
- Agriculture:Seasonal procurement patterns for refrigerated units align with harvest logistics and produce distribution corridors.
Procurement concentration sits with logistics companies; margin expansion tracks freight carrier lifecycle contracts.
Sales Channel:
Channel economics hinge on inventory carrying costs, localized service bundling requirements, and digital platform penetration in fleet procurement departments.
- Dealer Networks:Multi-location groups leverage relationship-based account management and aftermarket service density to capture large fleet volume. These intermediaries bundle financing, warranty administration, and predictive maintenance contracts through telematics-enabled platforms.
- Direct Sales:Manufacturer-owned channels bypass margin stacking for national accounts with standardized specification requirements and centralized procurement functions.
- Online Sales:Digital freight matching platforms and embedded configuration tools enable remote specification and pricing transparency for smaller fleet operators.
- Auctions:Secondary market liquidity for off-lease and certified pre-owned equipment supports remarketing programs and residual value guarantees.
Volume flows through dealer networks; digital adoption climbs fastest among smaller fleet operators.
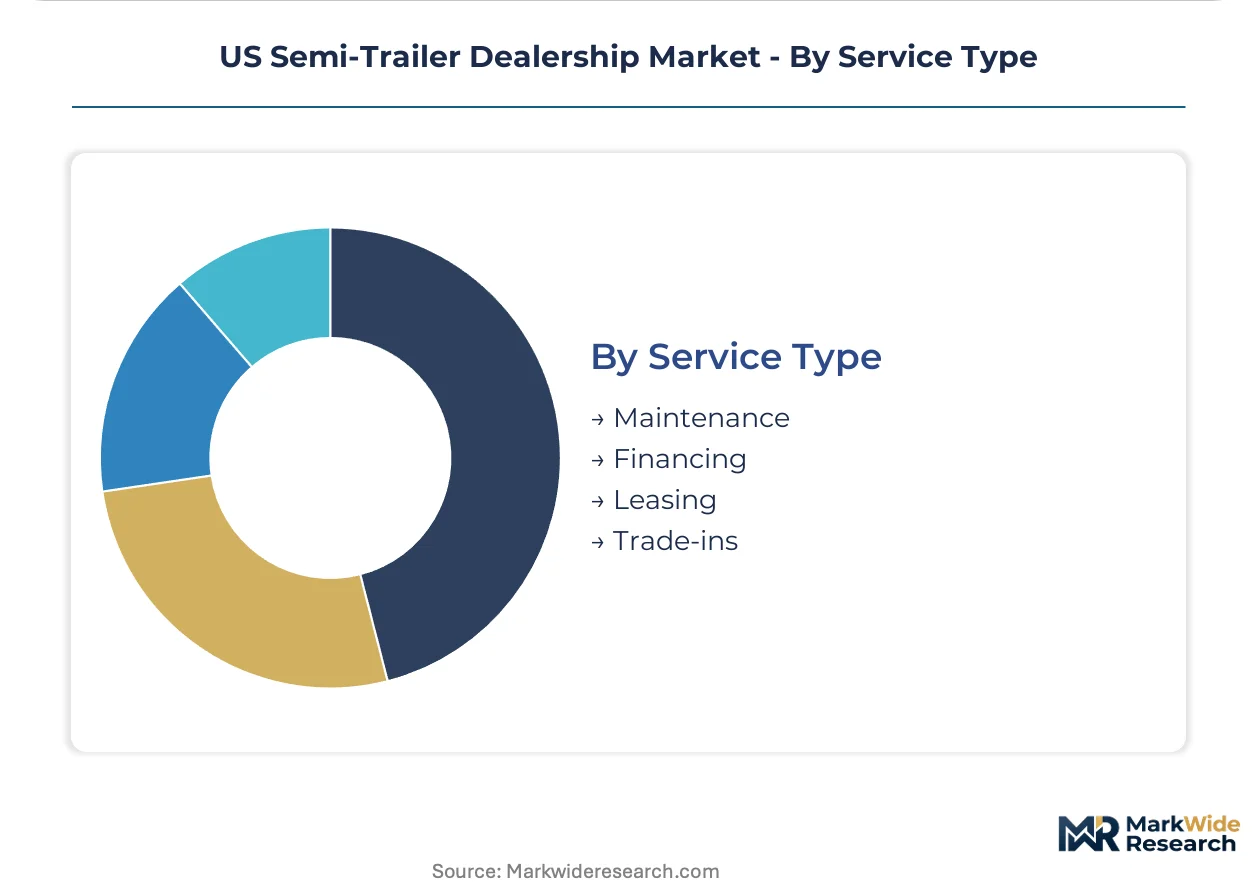
Service Type:
Revenue mix shifts from equipment margin toward recurring service streams as telematics integration enables outcome-based maintenance contracts.
- Maintenance:Predictive service programs using sensor-equipped reefers and dry vans transform dealer economics from transactional repair to subscription revenue. Diesel technician scarcity constrains service department expansion.
- Financing:Captive finance arms and third-party lenders structure equipment loans with residual value protection tied to standardized replacement cycles.
- Leasing:Full-service leases bundle maintenance and compliance administration for fleets seeking balance sheet flexibility.
- Trade-ins:Certified pre-owned programs generate predictable off-lease volume from replacement cycles and remarketing infrastructure.
Maintenance contracts deepen recurring revenue; leasing structures gain traction among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports semi-trailers and components into the US Southwest and Texas corridor, feeding dealer inventory pipelines that serve cross-border freight flows and maquiladora supply chains.
Texas
Gulf Coast port activity and Permian Basin energy-sector freight sustain heavy equipment turnover across Houston, Dallas-Fort Worth, and San Antonio dealer networks. EPA Phase 3 greenhouse gas standards accelerate aerodynamic trailer procurement for fleets serving containerized import corridors. The I-35 corridor from Laredo through Dallas anchors the highest dealership density for cross-border logistics equipment.
California
Cold-chain pharmaceutical distribution and foodservice logistics drive refrigerated trailer demand through Los Angeles, Central Valley, and Bay Area dealer channels. California Air Resources Board waivers impose zero-emission refrigeration specifications ahead of federal timelines. The Ports of Los Angeles and Long Beach generate concentrated procurement velocity for compliant dry van and reefer configurations.
Illinois
Midwest distribution hub concentration and Chicago-area intermodal terminals sustain standardized dry van replacement cycles. FMCSA hours-of-service enforcement shapes fleet utilization patterns and equipment turnover timing. The I-80/I-55 corridor through Joliet and Rochelle supports multi-location dealership groups serving national carrier networks.
Georgia
Southeast manufacturing reshoring and Savannah port expansion pull specialized trailer inventory through Atlanta and Augusta dealer networks. NHTSA brake system performance mandates under FMVSS govern conspicuity requirements for regional freight operators. The I-75 corridor anchors service network density for temperature-controlled platforms serving Florida-bound produce distribution.
Ohio
Great Lakes manufacturing freight and Columbus distribution hub development sustain flatbed and dry van procurement across Cleveland, Cincinnati, and Toledo markets. Midwest axle and suspension supplier concentration creates component availability advantages for regional dealerships. The I-70/I-71 intersection supports certified pre-owned remarketing programs tied to standardized fleet replacement cycles.
US Semi-Trailer Dealership Market Key Industry Players
Player mix skews toward manufacturer-captive dealerships and independent multi-location groups. The vendor base concentrates around legacy trailer fabricators with established distribution networks. Three archetypes dominate: manufacturer-owned direct sales channels, regional dealership groups with service density, and specialized refrigerated trailer specialists. Competitive moves center on telematics integration partnerships and used equipment remarketing program expansion.
Among manufacturer-anchored players, Wabash National Corporation and Great Dane occupy positions representing scale-driven fabrication and temperature-controlled specialization respectively. Utility Trailer Manufacturing Company and its regional affiliates exemplify the captive distribution model. Hyundai Translead sits within the import-based competitive tier. Northeast Great Dane and Utility Trailer of Texas represent geographic concentration strategies in high-velocity freight corridors.
| Leading Market Players |
|---|
| Northeast Great Dane |
| Valley Equipment |
| Mid-States Utility Trailer Sales |
| Wabash National Corporation |
| Utility Trailer Manufacturing Company |
| Utility Trailer of Texas |
| Great Dane |
| Hyundai Translead |
| Double A Utility Trailer Sales |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Wabash National's Lafayette fabrication complex and Utility Trailer's Paragould assembly lines shapes both component procurement scale and dealer floor pricing. These manufacturing concentrations create tiered cost structures that flow downstream through captive distribution networks and independent dealer groups.
Pricing Analysis
Technology-generation pricing gaps separate EPA Phase 2-compliant legacy inventory from Phase 3-ready aerodynamic platforms and emerging electrified-compatible configurations. Transactional per-unit pricing dominates, with differentiation driven by CARB waiver certification tier and factory-installed telematics bundling. Cost compression in standard dry van configurations is intensifying because aluminum sheet volatility compresses margin predictability. Logistics companies demonstrate lowest price sensitivity due to total cost of ownership contracting, while smaller agricultural operators exhibit highest sensitivity.
Supply Chain Analysis
Inbound logistics costs from Port of Veracruz and Port of Lázaro Cárdenas feed Mexico-to-Texas component corridors serving maquiladora-linked dealer networks. Manufacturing concentration centers on Indiana, Arkansas, and Georgia fabrication facilities. Raw material dependencies include steel-aluminum composite sheet, air-ride suspension assemblies, and refrigeration unit compressors. Single-source vulnerability in Midwest axle and suspension supplier concentration creates production bottleneck exposure. Distribution runs through manufacturer-captive dealerships and multi-location independent groups with regional service density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation among top fifty motor carriers is shifting negotiation leverage toward volume buyers with standardized specification requirements. This buyer-power concentration rewards dealership groups possessing multi-state service network density.
For Market Incumbents: Shield margin pools by deepening captive supply of aerodynamic skirt packages and low-rolling-resistance tire assemblies. Expand certified pre-owned remarketing infrastructure to capture replacement cycle predictability. Vertical integration into telematics-enabled predictive maintenance contracts defends against digital freight platform disintermediation.
For New Entrants and Emerging Players: Differentiate on California CARB waiver pre-compliance for zero-emission refrigeration specifications ahead of federal timelines. Target secondary market auction liquidity and used equipment certification programs as penetrable white space. Deploy direct-to-fleet digital configuration tools for sub-fifty-unit operators underserved by relationship-based dealer networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-location dealership groups with dense Texas and California service footprints. Long-term viability hinges on telematics integration capability and aftermarket recurring revenue mix. Acquisition targets should demonstrate established utility fleet relationships and EPA Phase 3 inventory positioning. The signal to watch is battery-electric tractor deployment velocity against compatible trailer infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Sensor-equipped reefers enable predictive maintenance subscriptions with pharmaceutical carriers. |
| CARB Pre-Compliance Inventory | Zero-emission refrigeration specifications secure premium positioning in Western markets. |
| Used Equipment Remarketing | Certified pre-owned programs capture predictable off-lease volume from fleet replacement cycles. |
| Service Network Expansion | Multi-location density wins total cost of ownership contracts from consolidated logistics companies. |
| Aerodynamic Package Standardization | Factory-installed EPA Phase 3 compliant configurations accelerate equipment turnover velocity. |
Research Approach
Cross-validation between dealer principal interviews and manufacturer production data anchors the qualitative findings. Primary fieldwork engaged fleet procurement directors, dealership operations managers, aftermarket service heads, and captive finance executives. Secondary sources included FMCSA regulatory filings, EPA greenhouse gas standard documentation, state-level CARB waiver records, and equipment registration databases. Bottom-up dealer revenue aggregation and top-down manufacturer shipment analysis were reconciled through iterative triangulation.
Sensitivity analysis tested forecast robustness across aluminum price volatility scenarios and electric tractor adoption curves. The analytical framework modeled product type, end user scale, sales channel, and service revenue mix dimensions across the projection horizon. CAGRs were derived from replacement cycle timing analysis and regulatory compliance cost escalation trajectories. Fleet utilization rate assumptions and hours-of-service enforcement intensity served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of steady EPA Phase 3 implementation and moderate aluminum input cost fluctuation; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Iraq Trailer Market