
 Gas Powered Commercial Vehicle Market | 2026-2036
Gas Powered Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Powered Commercial Vehicle Market Insights
Dual-fuel engine architecture is reconfiguring powertrain development across the commercial vehicle sector. Daimler Truck AG leverages its European engineering base to sustain leadership in heavy-duty natural gas platforms. Volvo Group anchors Scandinavian markets through integrated driveline and tank system design. Isuzu Motors Ltd. competes aggressively in Asian light-duty segments with compact turbocharged gasoline engines.
Gas powered commercial vehicles employ internal combustion engines optimized for compressed natural gas, liquefied natural gas, gasoline, or biofuel blends, typically operating at compression ratios between 12:1 and 14:1 with spark ignition and stoichiometric or lean-burn strategies to meet torque and emissions targets for freight and passenger movement. Heavy-duty trucks dominate value generation due to fleet-scale procurement and total cost of ownership calculations favoring natural gas over diesel in specific route profiles. Dual-fuel systems represent the fastest-expanding technology segment as operators seek fuel flexibility without full powertrain replacement. Light-duty trucks and vans concentrate volume in urban delivery services where range anxiety limits battery-electric alternatives.
EPA greenhouse gas standards for medium- and heavy-duty vehicles shape product development timelines and certification costs for manufacturers selling into the United States. EMA and REACH compliance requirements in Europe constrain material selection for fuel storage and exhaust aftertreatment systems. India's BIS emission norms and PLI scheme incentives for alternative fuel vehicles redirect domestic production capacity toward compressed natural gas platforms. Fleet managers must weigh infrastructure availability against total ownership economics when committing to gas powertrains over emerging electric alternatives.
Market Dynamics
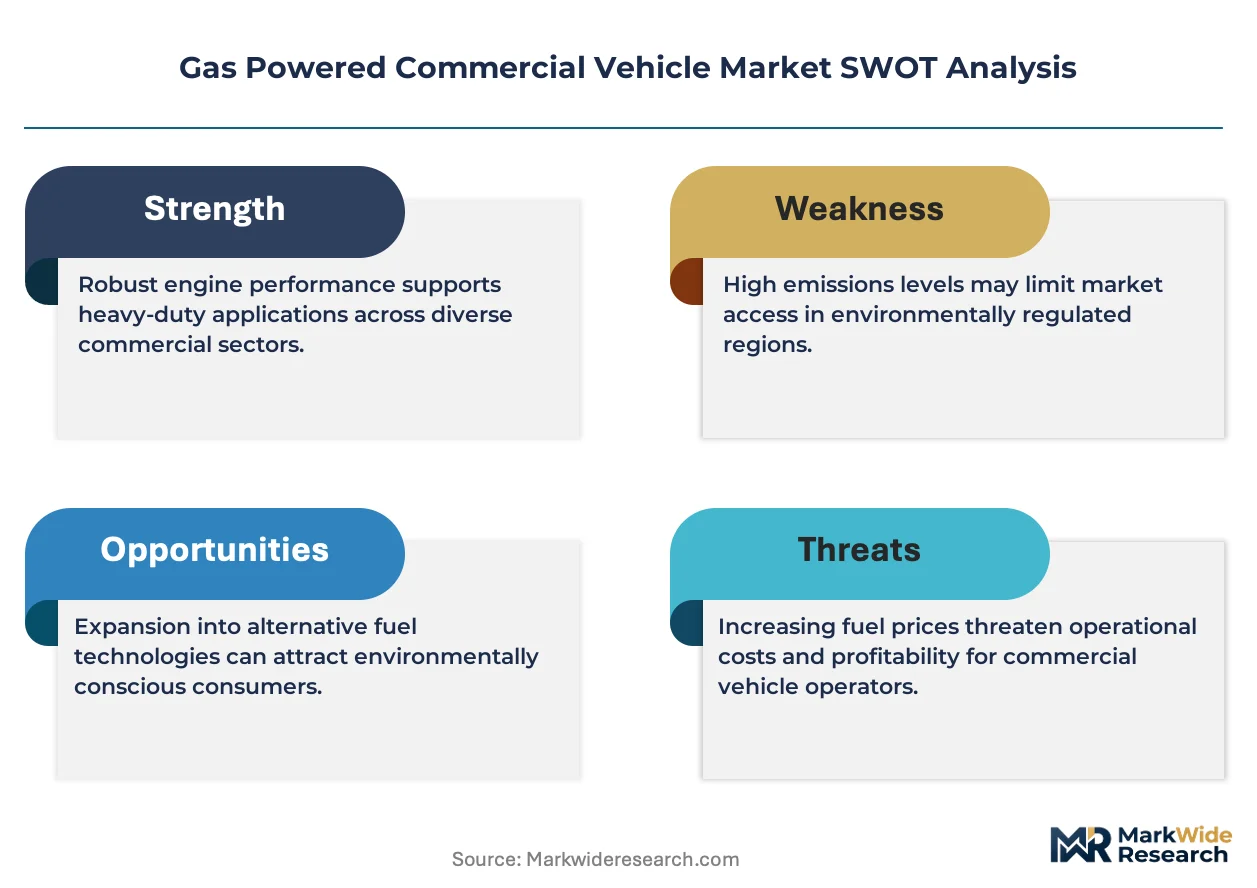
Dual-fuel engine architecture is compressing powertrain development cycles as fleet operators demand fuel flexibility without full platform replacement. EPA Phase 3 greenhouse gas standards and Euro VII proposals are forcing simultaneous investment in combustion optimization and aftertreatment miniaturization.
Growth Catalysts
- EPA Phase 3 Standards:Medium- and heavy-duty fleet operators in the United States face tightening CO2 limits that favor natural gas combustion over diesel in specific duty cycles, accelerating compressed natural gas truck procurement.
- Urban Last-Mile Delivery:E-commerce fulfillment networks in Brazil and India deploy light-duty gas vans where battery-electric range constraints and charging infrastructure gaps persist.
- Dual-Fuel Retrofit Kits:Aftermarket conversion systems allow existing diesel fleets to operate on blended natural gas without powertrain replacement, preserving capital deployment flexibility.
Market Restraints
- Liquefied Natural Gas Cryogenics:Tank insulation failures and boil-off losses in heavy-duty long-haul applications impose operational complexity that diesel avoids entirely.
- Refueling Infrastructure Concentration:Compressed natural gas station networks cluster along specific freight corridors in Germany and California, leaving route planning constrained.
- Battery-Electric Substitution:Declining lithium-ion pack costs and expanding megawatt charging standards erode the total cost of ownership advantage for urban gas-powered distribution vehicles.
Strategic Opportunities
- India's PLI Scheme for Alternative Fuels:Production-linked incentives redirect domestic commercial vehicle manufacturing capacity toward compressed natural gas platforms with localized tank and engine component sourcing.
- Biofuel Blend Compatibility:Renewable natural gas injection into existing pipeline networks allows fleet operators to claim carbon intensity reductions without vehicle modification.
- Telematics-Integrated Refueling:Real-time station availability data streamed to cab displays reduces driver range anxiety and enables dynamic route optimization.
Industry Challenges
- Homologation Timeline Compression:Simultaneous certification for EPA, CARB, and Euro VII standards requires parallel engineering tracks that strain validation resources.
- Aftertreatment System Integration:Three-way catalyst and methane oxidation catalyst packaging within constrained chassis rail space demands thermal management expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Powered Commercial Vehicle Market |
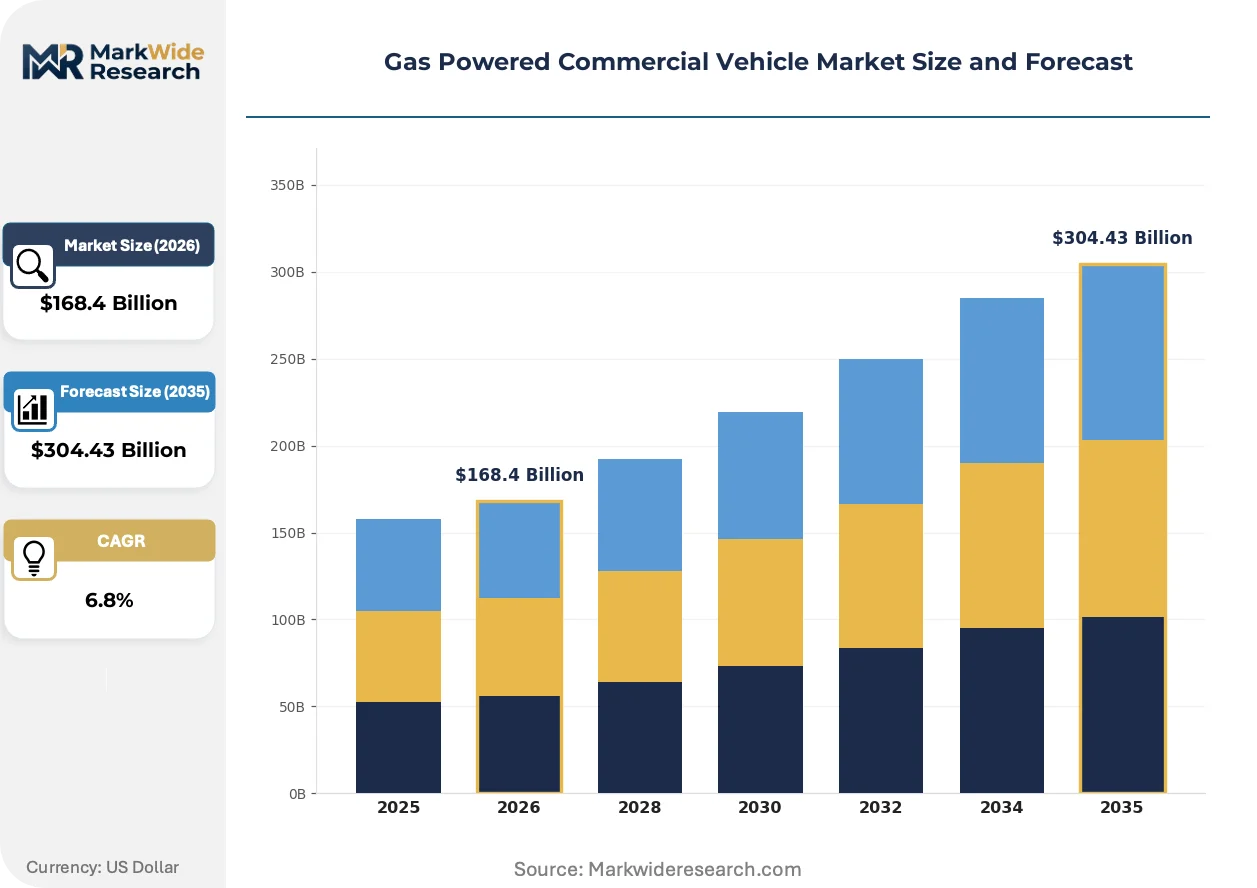
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Vans, Buses Fuel Type: Compressed Natural Gas, Liquefied Natural Gas, Gasoline, Biofuel End User: Logistics Companies, Public Transport, Construction, Delivery Services Technology: Conventional Engines, Dual-Fuel Systems, Turbocharged Engines, Hybrid Systems |
| Companies Covered | Volvo Group, Daimler Truck AG, IVECO S.p.A., Scania AB, MAN SE, Ford Motor Company, General Motors Company, PACCAR Inc, Isuzu Motors Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Powered Commercial Vehicle Market Trends and Innovations
Powertrain electrification is digitizing combustion control systems as manufacturers bridge conventional and zero-emission platforms. Software-defined engine management now governs fuel injection, ignition timing, and thermal regulation through over-the-air updates.
On-board diagnostic systems with predictive maintenance algorithms are digitizing fleet operations. Logistics operators in the United States adopt telematics platforms that anticipate spark plug degradation and catalyst efficiency loss before roadside failures occur. This capability is digitizing service intervals and compressing unplanned downtime costs for high-utilization freight operators.
EPA Phase 3 greenhouse gas standards and Euro VII proposals are tightening methane slip limits and particulate matter thresholds simultaneously. Manufacturers must integrate closed crankcase ventilation and heated oxygen sensors across heavy-duty engine families. The United States market responds with dedicated natural gas engine platforms rather than diesel derivatives, while European engineering prioritizes hybrid-electric range extenders.
Fleet procurement contracts now bundle fuel supply agreements with vehicle acquisition, displacing traditional equipment financing. Large logistics operators in Brazil and India negotiate compressed natural gas offtake guarantees directly with distribution utilities, collapsing the historical separation between asset ownership and energy procurement. This consolidation is most visible in municipal bus fleets where fuel cost certainty outweighs capital expenditure flexibility.
Gas Powered Commercial Vehicle Market Segmentation
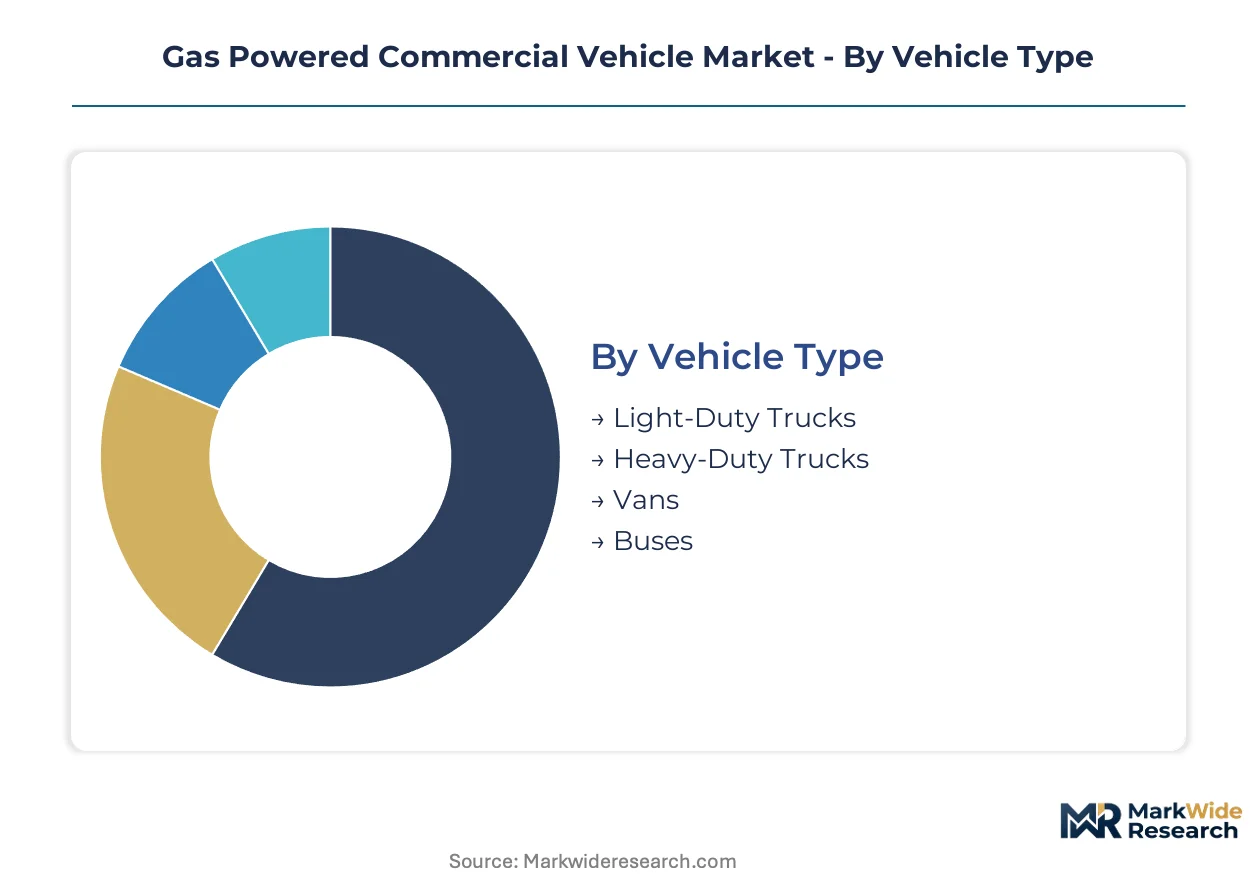
Segmentation in the gas powered commercial vehicle market reveals how fleet operators balance payload requirements, fuel availability, and regulatory compliance across divergent duty cycles. The four-dimensional structure below maps where capital concentrates and where emerging technologies displace conventional platforms.
Vehicle Type:
Mature segments dominate freight economics while emerging categories capture policy-driven fleet renewals.
- Heavy-Duty Trucks:These vehicles integrate 12:1 to 14:1 compression ratio engines with spark ignition optimized for compressed natural gas torque curves. Long-haul operators in the United States favor heavy-duty platforms where EPA Phase 3 CO2 limits penalize diesel particulate emissions; total cost of ownership calculations tilt toward natural gas on fixed corridor routes with established refueling infrastructure.
- Buses:Municipal procurement contracts now bundle compressed natural gas supply agreements with vehicle acquisition, collapsing traditional separation between asset ownership and energy procurement. Transit authorities in Brazil and India concentrate orders here where fuel cost certainty outweighs capital expenditure flexibility and range anxiety limits battery-electric alternatives.
- Light-Duty Trucks:Compact turbocharged gasoline engines serve urban delivery networks with frequent stop-start duty cycles.
- Vans:Last-mile fulfillment fleets in India deploy these where charging infrastructure gaps persist and BIS emission norms favor alternative fuel platforms.
Heavy-Duty Trucks retain volume leadership; Buses hold the steepest expansion curve.
Fuel Type:
Cost tier stratification separates infrastructure-dependent gases from liquid fuels with established distribution networks.
- Compressed Natural Gas:Stored at 3,600 psi in Type III or Type IV composite cylinders, this fuel enables stoichiometric or lean-burn combustion strategies with three-way catalyst aftertreatment. Logistics operators in Germany and California cluster procurement along specific freight corridors where station networks exist; India's PLI scheme redirects domestic manufacturing capacity toward localized tank and engine component sourcing for this segment.
- Liquefied Natural Gas:Cryogenic storage at -162°C extends range for heavy-duty long-haul applications but imposes boil-off losses and thermal management complexity that diesel avoids entirely.
- Gasoline:Light-duty segments in Asian markets leverage existing refining and retail infrastructure without dedicated vehicle modification.
- Biofuel:Renewable natural gas injection into pipeline networks allows carbon intensity reductions without vehicle modification, appealing to fleets with Scope 3 emissions targets.
Compressed Natural Gas dominates value generation; Biofuel climbs the fastest as renewable gas injection scales.
End User:
Customer type determines procurement scale and contract structure across fleet aggregation patterns.
- Logistics Companies:Large operators negotiate compressed natural gas offtake guarantees directly with distribution utilities, digitizing refueling through telematics-integrated station availability data. E-commerce fulfillment networks in Brazil deploy light-duty gas vans where battery-electric range constraints persist; these firms prioritize dual-fuel retrofit kits that preserve capital deployment flexibility across mixed-age fleets.
- Public Transport:Municipal bus fleets concentrate demand for dedicated natural gas engine platforms rather than diesel derivatives, with fuel cost certainty driving bundled procurement.
- Construction:Site-based refueling infrastructure and intermittent duty cycles favor conventional gasoline or dual-fuel systems with fuel flexibility.
- Delivery Services:Urban last-mile operators face battery-electric substitution pressure as lithium-ion pack costs decline and megawatt charging standards expand.
Logistics Companies retain volume leadership; Public Transport holds the steepest expansion curve.
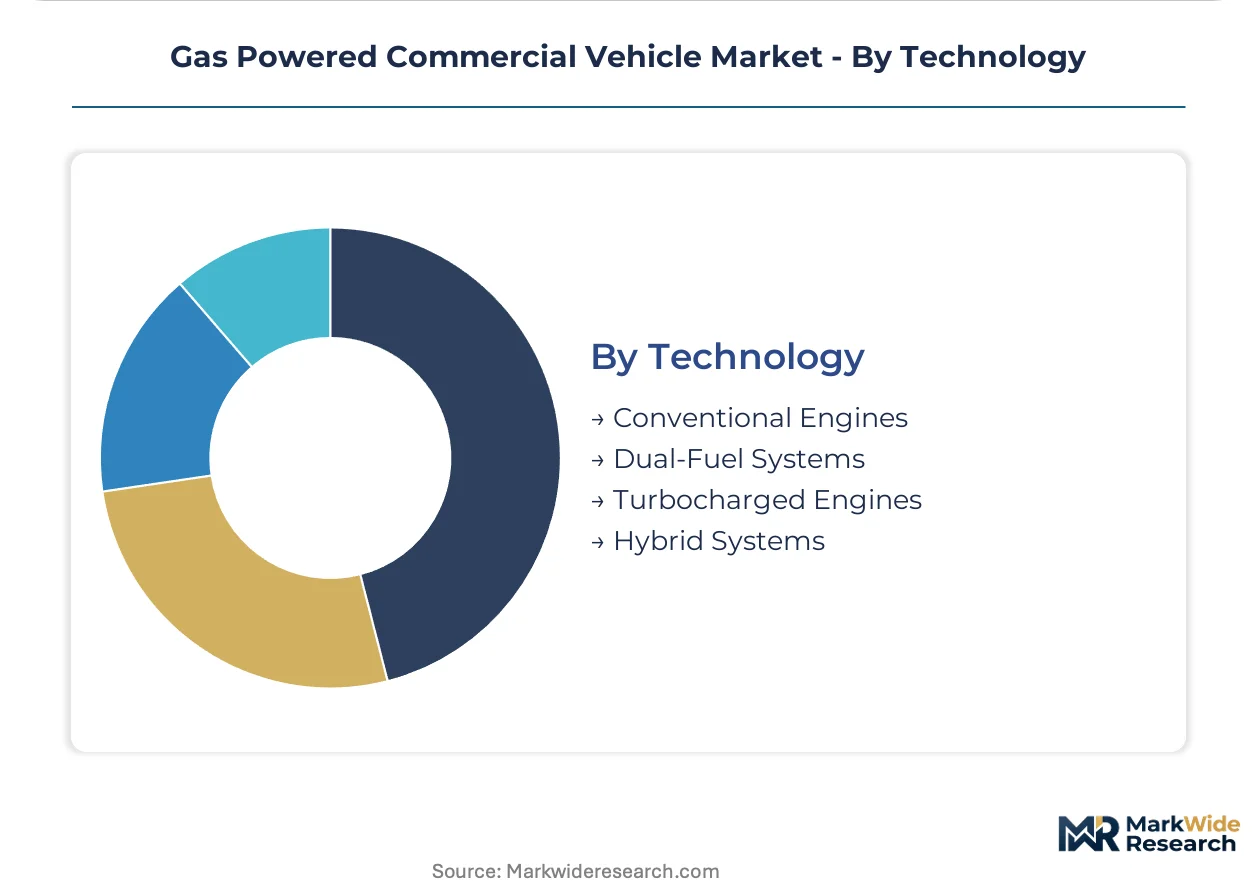
Technology:
Supply concentration in engine management systems and aftertreatment components shapes competitive positioning across architecture types.
- Dual-Fuel Systems:Aftermarket conversion systems allow existing diesel fleets to operate on blended natural gas without powertrain replacement, compressing development cycles as operators demand fuel flexibility. EPA Phase 3 and Euro VII proposals force simultaneous investment in combustion optimization and aftertreatment miniaturization; manufacturers integrate closed crankcase ventilation and heated oxygen sensors across heavy-duty engine families serving this segment.
- Conventional Engines:Spark-ignition platforms optimized for single-fuel operation dominate where infrastructure certainty exists and capital replacement cycles align.
- Turbocharged Engines:Isuzu Motors Ltd. competes aggressively in Asian light-duty segments with compact designs addressing urban delivery density.
- Hybrid Systems:European engineering prioritizes hybrid-electric range extenders as bridge technology toward zero-emission mandates.
Conventional Engines retain volume leadership; Dual-Fuel Systems gain share fastest through retrofit demand and fuel flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports compressed natural gas-powered buses and medium-duty trucks to Southeast Asian markets, while Germany supplies dual-fuel engine technology to freight operators across Central Europe. Brazil concentrates regional demand for gas-powered distribution vehicles serving agricultural commodity corridors.
United States
Logistics fleets along the I-10 and I-75 corridors deploy heavy-duty compressed natural gas trucks where EPA Phase 3 CO2 limits penalize diesel emissions. The EPA enforces greenhouse gas standards that compress manufacturer certification timelines. California's Central Valley hosts concentrated municipal fleet procurement, with Fresno and Bakersfield transit authorities bundling fuel supply agreements with vehicle acquisition.
Germany
Long-haul operators favor liquefied natural gas for cross-border freight to Poland and the Netherlands, despite boil-off management complexity. The KBA administers type approval under Euro VII proposals that mandate methane slip reduction. The Rhine-Ruhr industrial corridor anchors aftermarket dual-fuel retrofit activity, with Dortmund and Duisburg workshops converting existing diesel platforms for blended natural gas operation.
China
Urban bus fleets in the Yangtze River Delta replace aging diesel platforms with compressed natural gas alternatives where charging infrastructure gaps persist. MIIT oversees GB standards compliance for alternative fuel vehicle production quotas. Chengdu and Chongqing concentrate manufacturing capacity for medium-duty gas engines serving western provincial markets.
Brazil
Agricultural logistics operators in Mato Grosso and Goiás deploy light-duty gas vans for grain elevator distribution where battery-electric range constraints limit alternatives. ANVISA coordinates with environmental regulators on biofuel blend certification for commercial vehicle applications. São Paulo's metropolitan bus fleet represents the largest municipal compressed natural gas procurement in Latin America, with fuel cost certainty driving bundled contracts.
India
E-commerce fulfillment networks in Maharashtra and Karnataka expand light-duty gas van deployment ahead of BIS emission norm deadlines. The PLI scheme for alternative fuels redirects domestic manufacturing toward localized tank and engine component sourcing. Delhi-NCR transit operators concentrate orders for dedicated natural gas engine platforms, with fuel supply guarantees negotiated directly with Indraprastha Gas Limited.
Gas Powered Commercial Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base concentrates around heavy-duty engine families and integrated tank system design, with European engineering bases sustaining leadership in natural gas platform development. Two strategic archetypes dominate: integrated powertrain manufacturers with captive driveline expertise, and regional light-duty specialists leveraging compact turbocharged architectures. Competitive moves center on dual-fuel retrofit kit partnerships and telematics-integrated refueling platform licensing.
Within the integrated powertrain tier, Volvo Group and Daimler Truck AG exemplify channel-controlling archetypes with European engineering concentration. Isuzu Motors Ltd. occupies a specialist position in Asian light-duty segments. These three anchors represent divergent geographic and segment positioning rather than direct product overlap.
| Leading Market Players |
|---|
| Volvo Group |
| Daimler Truck AG |
| IVECO S.p.A. |
| Scania AB |
| MAN SE |
| Ford Motor Company |
| General Motors Company |
| PACCAR Inc |
| Isuzu Motors Ltd. |
| Others |
Pricing and Supply Chain Analysis
The I-10 freight corridor connecting Los Angeles to Houston concentrates compressed natural gas procurement economics, where supply concentration in Type III and Type IV composite cylinder manufacturing translates directly to fleet-level price differentiation between integrated powertrain bundles and aftermarket retrofit configurations.
Pricing Analysis
Current-generation dual-fuel retrofit kits command substantial premiums over prior-generation single-fuel conversions, while next-generation telematics-integrated platforms are compressing price realization timelines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in economy-tier conventional engines is intensifying because battery-electric substitution erodes total cost of ownership advantages. Light-duty van operators exhibit highest price sensitivity; heavy-duty fleet procurement teams prioritize fuel cost certainty over capital expenditure flexibility.
Supply Chain Analysis
Export-control regimes limiting advanced composite material flows constrain Type IV cylinder technology transfer to select manufacturing partners. China, Germany, and India anchor global supply for high-pressure storage systems, precision fuel injectors, and methane oxidation catalyst substrates. Raw material dependencies center on carbon fiber prepreg, rare-earth catalyst coatings, and cryogenic-grade stainless steel. Single-source vulnerability concentrates in European aftertreatment system engineering. Distribution runs through captive OEM service networks and authorized retrofit workshop chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-integrated refueling platforms are reconfiguring this market toward ecosystem economics, where interoperability between vehicle onboard diagnostics and station availability databases determines competitive positioning.
For Market Incumbents: Build certification moats around EPA Phase 3 and Euro VII homologation timelines to exclude capital-constrained challengers. Deepen backward integration into composite cylinder manufacturing to defend margin position against raw material volatility. Channel control through captive financing bundles preserves fleet customer lock-in against emerging dual-fuel specialists. For New Entrants and Emerging Players: Southeast Asian last-mile logistics corridors offer underpenetrated white space where charging infrastructure gaps persist and BIS-equivalent norms favor alternative fuel platforms. Target municipal bus procurement in secondary Indian cities where PLI scheme incentives redirect domestic manufacturing capacity. Partner with compressed natural gas distribution utilities for fuel supply guarantees that collapse traditional equipment financing separation. For Investors and Strategic Acquirers: Specialist aftermarket retrofit kit developers with telematics platform IP represent priority acquisition archetypes. Long-term viability hinges on dual-fuel technology retaining relevance through the zero-emission transition window. Watch battery-electric megawatt charging standard deployment velocity as inflection indicator for gas-powered urban delivery vehicle substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Retrofit Kit Partnership | Preserves capital deployment flexibility for mixed-age fleet operators facing EPA Phase 3 compliance deadlines. |
| Telematics-Integrated Refueling Platform | Reduces driver range anxiety through real-time station availability data streamed to cab displays. |
| Backward Integration into Composite Cylinders | Secures supply of Type III and Type IV high-pressure storage systems amid carbon fiber prepreg constraints. |
| PLI Scheme Manufacturing Localization | Redirects Indian domestic capacity toward localized tank and engine component sourcing for alternative fuel platforms. |
| Renewable Natural Gas Supply Agreement | Enables fleet operators to claim carbon intensity reductions without vehicle modification through pipeline injection. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, OEM platform engineers, aftermarket retrofit specialists, and compressed natural gas distribution utility planners and refined through secondary validation against EPA certification databases, Euro VII proposal drafts, IHS Markit vehicle production data, and customs trade records for high-pressure storage system imports. Bottom-up triangulation across fleet deployment surveys and top-down reconciliation against national alternative fuel vehicle registration aggregates anchored volume estimates.
Demand-supply balance framing governed the analytical framework across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, fuel storage technology tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to observed fleet replacement cycles and infrastructure buildout trajectories. Industry-specific forecast inputs included EPA Phase 3 compliance cost modeling and India's PLI scheme capacity addition schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric fast-charging network operators would shift outcomes beyond modeled ranges. Material shifts in lithium-ion pack cost trajectories or megawatt charging standard adoption velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Used Truck Market