
 Global Commercial Vehicles Market | 2026-2036
Global Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Vehicles Market Analysis
Chinese battery-electric truck production is decoupling from European diesel-centric supply chains as cell manufacturing scales domestically. Daimler Truck AG leverages integrated powertrain development to sustain premium positioning in long-haul segments. Volvo Group anchors Nordic markets through autonomous haulage pilots while Tata Motors dominates South Asian light-duty distribution with cost-engineered platforms.
Commercial vehicles encompass motorized transport equipment exceeding 3.5 tonnes gross vehicle weight, incorporating chassis-cab architectures, diesel or electric powertrains, and body configurations optimized for cargo or passenger carriage. Heavy-duty diesel variants retain structural dominance in transcontinental freight due to energy density requirements, though electric light-duty models within the fuel-type segmentation are capturing urban last-mile logistics. Telematics integration across the technology dimension creates recurring revenue pools, while emission-control hardware faces margin compression as aftertreatment systems commoditize.
EPA Phase 3 standards, the EU Green Deal framework, and China's MIIT dual carbon goals collectively mandate powertrain diversification and reshape certification requirements for market access. NHTSA safety protocols and ECHA REACH chemical compliance add layered compliance costs to cross-border manufacturers. Stakeholders must monitor regulatory divergence between California's Advanced Clean Trucks rule and EU F-Gas Regulation to anticipate powertrain investment timelines and geographic production allocation.
Market Dynamics
Powertrain electrification is fragmenting established supplier hierarchies as battery pack assembly migrates from tier-3 component sourcing to OEM captive production, forcing wholesale restructuring of procurement relationships and factory footprints across major manufacturing clusters.
Growth Catalysts
- EPA Phase 3 Standards:The regulation mandates progressive CO2 reduction thresholds for heavy-duty fleets operating across US interstate corridors, compelling freight operators to accelerate zero-emission vehicle deployment timelines.
- Urban Freight Electrification:Last-mile logistics providers in congested metropolitan zones are replacing diesel light-duty vans with battery-electric alternatives to comply with municipal low-emission zone mandates.
- Cell Manufacturing Scale:Domestic lithium-ion production expansion in China is decoupling battery supply from European chemical processing, reducing import dependency for electric truck assembly.
Market Restraints
- Lithium Price Volatility:Raw material cost swings for cathode-grade lithium carbonate strain OEM margin structures and complicate long-term fleet leasing rate calculations.
- Charging Infrastructure Gaps:Highway corridor electrification lags vehicle deployment in North American long-haul routes, creating operational range anxiety for transcontinental operators.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in vehicle climate systems forces costly redesign of thermal management architectures.
Strategic Opportunities
- India Light-Duty Distribution:Formalization of cold-chain logistics and e-commerce fulfillment networks creates first-mover advantage for electric small commercial vehicle platforms.
- Telematics-As-A-Service:Predictive maintenance algorithms and route optimization software generate recurring revenue streams beyond initial vehicle sale.
- Autonomous Haulage Pilots:Closed mining and quarry environments in Australia and Scandinavia permit regulatory sandbox deployment of driverless heavy trucks.
Industry Challenges
- Powertrain Engineering Talent Scarcity:Competition for battery thermal management and motor control specialists intensifies as automotive and energy sectors converge.
- Multi-Homologation Burden:Divergent certification requirements between California Air Resources Board, EU Whole Vehicle Type Approval, and China's MIIT testing protocols extend product launch timelines.
- Legacy Fleet Integration:Mixed diesel-electric operations complicate maintenance training, parts inventory, and depot charging coordination for diversified operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Vehicles Market |
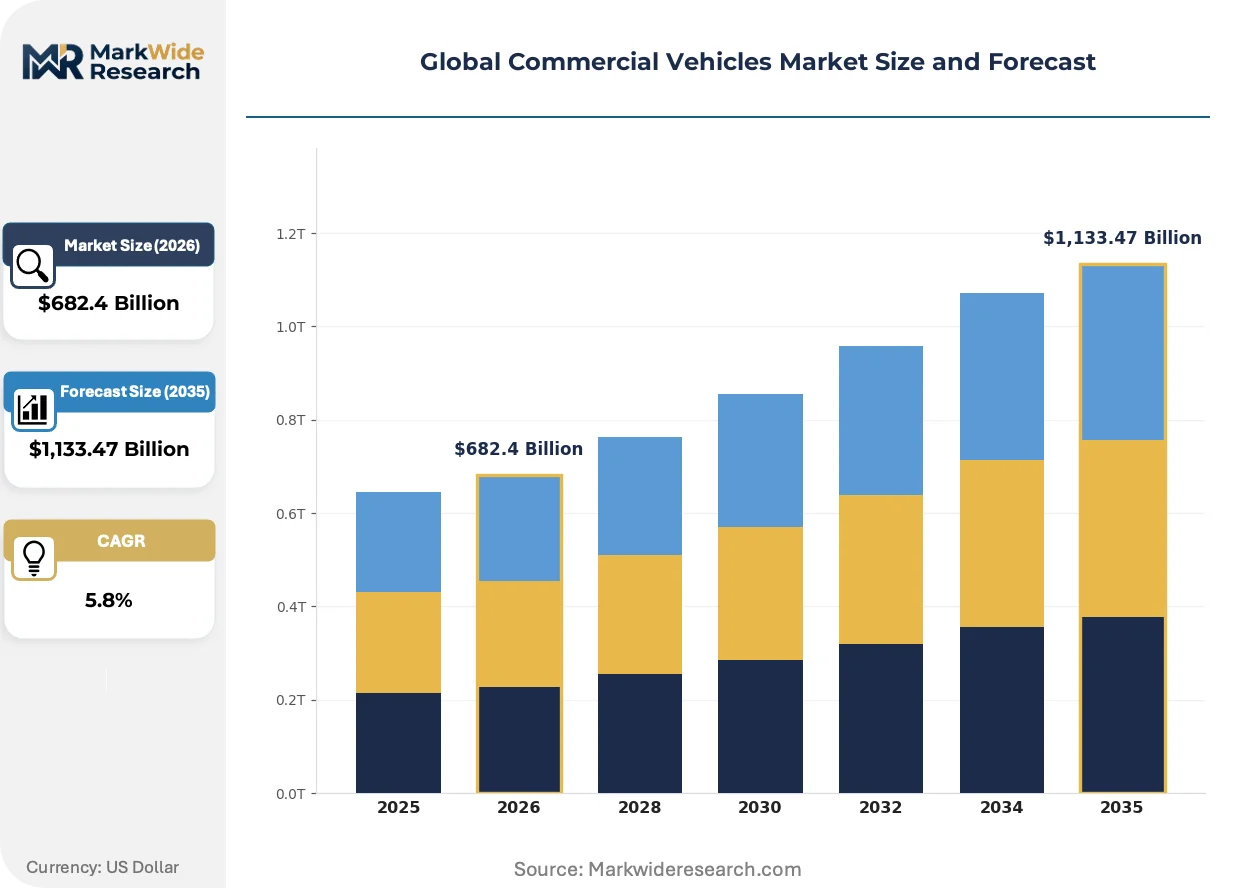
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,133.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Heavy Duty, Medium Duty, Buses Fuel Type: Diesel, Electric, Gasoline, Hybrid End User: Construction, Logistics, Agriculture, Public Transport Technology: Telematics, Autonomous, Connected, Emission Control |
| Companies Covered | Daimler Truck AG, Volvo Group, PACCAR Inc., Tata Motors, Traton SE, Ford Motor Company, General Motors, Ashok Leyland, Isuzu Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Vehicles Market Emerging Trajectories
Software-defined vehicle architectures are displacing mechanical differentiation as the primary competitive battleground, with over-the-air capability updates and data monetization reshaping how commercial vehicle value is captured and retained.
Platooning coordination technology is automating convoy formation and gap management on dedicated freight corridors. Long-haul carriers in the US Sun Belt are piloting linked-tractor configurations to reduce aerodynamic drag and driver fatigue. This convergence of V2V communication and adaptive cruise control is automating fuel consumption optimization previously dependent on individual operator skill.
The EU Green Deal's Fit for 55 package tightens emission performance standards for new heavy-duty vehicles through 2040. Manufacturers must certify powertrain portfolios against progressively stringent CO2 benchmarks or face fleet-average penalty payments. German and Swedish OEMs are accelerating hydrogen fuel cell development for regional haul segments where battery weight compromises payload capacity.
Asset-light operating leases are displacing traditional vehicle ownership among mid-sized logistics providers. Third-party fleet management platforms in Germany and the Netherlands bundle maintenance, insurance, and charging access into per-kilometer contracts. This shift transfers residual value risk to lessors and concentrates purchasing influence among specialized fleet aggregators.
Global Commercial Vehicles Market Segmentation
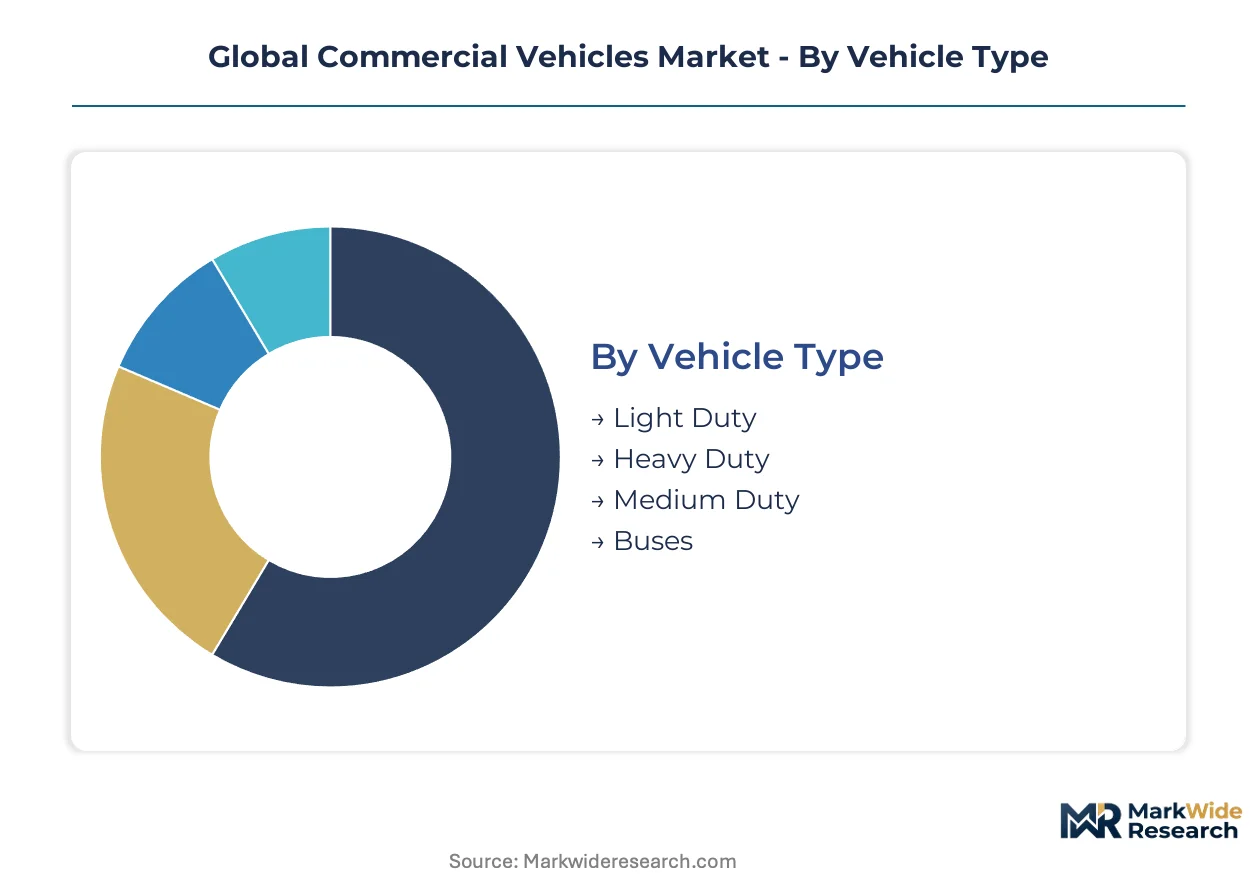
Commercial vehicle procurement decisions cascade through multiple specification layers, from chassis architecture to powertrain chemistry and fleet management systems. Understanding how these dimensions intersect reveals where margin pools concentrate and which technology bets carry the highest strategic stakes for manufacturers and operators alike.
Vehicle Type:
Chassis weight classifications determine regulatory treatment, energy density requirements, and duty-cycle engineering priorities across freight and passenger applications.
- Light Duty:Gross vehicle weight below 3.5 tonnes dominates urban last-mile fulfillment. E-commerce parcel networks in Germany and municipal delivery fleets in California are electrifying these platforms fastest under low-emission zone mandates.
- Heavy Duty:Long-haul tractors and rigid trucks exceeding 16 tonnes GVW retain diesel dominance due to energy density constraints. Transcontinental freight corridors across the US Sun Belt and China's G-series expressways sustain demand for high-torque compression-ignition powertrains.
- Medium Duty:Regional distribution trucks between 3.5-16 tonnes bridge urban and intercity logistics. Cold-chain operators in India favor these chassis for refrigerated multi-stop routes.
- Buses:Passenger-carrying platforms span urban transit and intercity coach configurations. Shenzhen's municipal fleet and Santiago's Transantiago system have achieved near-complete battery-electric conversion.
Heavy Duty leads on scale; Light Duty leads on momentum.
Fuel Type:
Powertrain chemistry choices are hardening into distinct geographic supply ecosystems as cell manufacturing localizes and emission regulations diverge.
- Diesel:Compression-ignition engines with advanced aftertreatment dominate transcontinental freight where refueling infrastructure density and energy-per-unit-mass ratios remain critical. EPA Phase 3 CO2 thresholds are forcing incremental thermal efficiency gains rather than displacement.
- Electric:Battery-electric configurations are capturing urban freight and fixed-route transit where depot charging and predictable duty cycles eliminate range anxiety. Chinese OEMs have achieved cost parity in light-duty segments through domestic lithium-iron-phosphate cell supply.
- Gasoline:Spark-ignition powertrains persist in emerging-market light-duty applications where fuel distribution infrastructure favors petrol over diesel. Southeast Asian urban delivery fleets maintain gasoline van procurement for first-cost sensitivity.
- Hybrid:Parallel and series-hybrid architectures serve regional haul segments where full electrification strains payload capacity. Japanese kei-truck derivatives and European PHEV vans target stop-and-go distribution patterns.
Diesel retains volume leadership; Electric climbs the fastest.
End User:
Application-specific duty cycles and asset utilization patterns drive divergent specifications for durability, connectivity, and total cost of ownership.
- Construction:Off-highway-capable chassis with reinforced suspensions serve quarry, mining, and infrastructure project sites. Autonomous haulage pilots in Western Australia's Pilbara region are validating driverless heavy trucks in closed environments.
- Logistics:Asset-light third-party fleet operators prioritize telematics integration and flexible lease structures. German and Dutch per-kilometer contracting models bundle maintenance, insurance, and charging access.
- Agriculture:Seasonal utilization patterns and rural refueling infrastructure favor diesel retention. Indian food-grain procurement logistics and Brazilian soybean transport sustain medium-duty truck demand.
- Public Transport:Municipal procurement mandates and dedicated infrastructure funding accelerate zero-emission transitions. Battery-electric and fuel-cell buses dominate new tender awards in Copenhagen, Shenzhen, and London.
Logistics leads on scale; Public Transport leads on momentum.
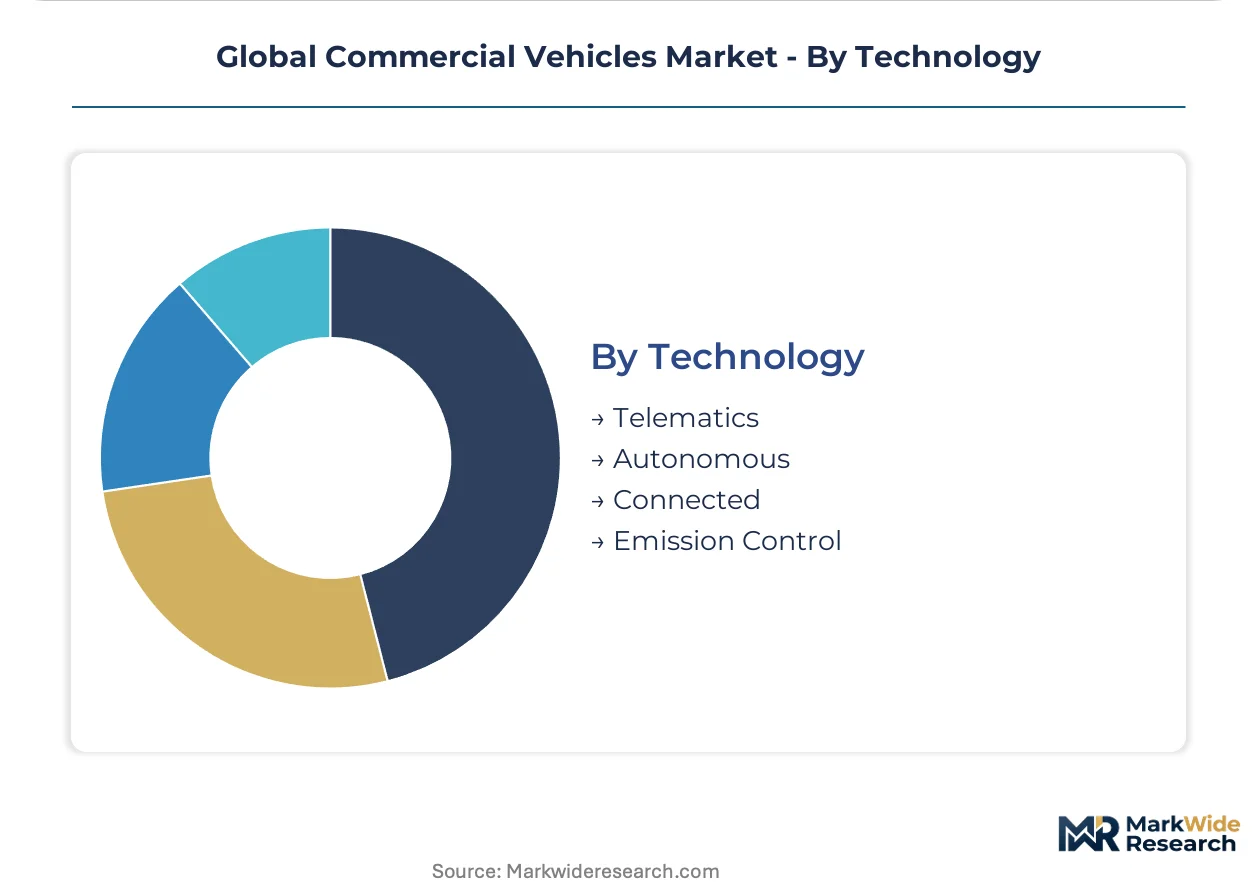
Technology:
Digital and automated systems are displacing mechanical differentiation as the primary value-capture mechanism in commercial vehicle platforms.
- Telematics:GPS-enabled fleet management systems generate recurring revenue through predictive maintenance and route optimization algorithms. German fleet aggregators bundle these services into per-kilometer operating leases.
- Autonomous:SAE Level 4 automation targets closed mining environments and dedicated freight corridors before urban generalization. V2V platooning coordination reduces aerodynamic drag on US interstate routes.
- Connected:Over-the-air software updates and cybersecurity-hardened architectures enable feature monetization post-sale. OEMs are restructuring engineering organizations around software-defined vehicle development cycles.
- Emission Control:Selective catalytic reduction and diesel particulate filter systems face margin compression as aftertreatment hardware commoditizes. EU F-Gas Regulation refrigerant phasedowns add thermal management redesign costs.
Telematics leads on scale; Autonomous leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing investment migrates toward jurisdictions where emission compliance costs diverge most sharply. OEMs reallocate assembly capacity between the EU Green Deal's carbon border adjustments and China's MIIT dual carbon timelines to optimize regulatory arbitrage returns.
China
Domestic lithium-iron-phosphate cell production decouples electric truck supply from European chemical processing. MIIT dual carbon mandates accelerate zero-emission vehicle certification timelines for heavy-duty platforms. The Yangtze River Delta cluster around Shanghai anchors battery pack assembly integration with chassis manufacturing.
United States
EPA Phase 3 CO2 thresholds compel fleet operators toward electrified light-duty procurement in California and New York corridors. NHTSA safety protocols layer compliance costs onto cross-border manufacturers serving multiple state jurisdictions. The US Sun Belt sustains diesel long-haul demand where highway electrification gaps persist.
Germany
KBA type-approval standards enforce EU Green Deal emission benchmarks through 2040 fleet-average calculations. Hydrogen fuel cell development concentrates in Baden-Württemberg where payload-critical regional haul applications resist full battery electrification. Stuttgart engineering clusters advance integrated powertrain architectures for premium positioning.
India
Formalization of cold-chain logistics and e-commerce fulfillment networks concentrates light-duty demand in Maharashtra and Gujarat. BIS certification requirements and PLI scheme incentives reshape domestic assembly footprints for electric small commercial vehicles. Tamil Nadu manufacturing corridors attract component localization investments.
Sweden
Autonomous haulage pilots in closed mining environments validate SAE Level 4 deployment before urban generalization. ECHA REACH chemical compliance adds thermal management redesign costs for climate system refrigerant phasedowns. Nordic telematics-as-a-service platforms bundle predictive maintenance into per-kilometer operating contracts.
Global Commercial Vehicles Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-electric and autonomous specialization vectors. The vendor base stratifies across integrated powertrain developers, regional cost-engineered platforms, and asset-light fleet service aggregators. Three archetypes dominate: legacy diesel incumbents defending long-haul positioning, electric-native challengers exploiting cell manufacturing scale, and software-defined service platforms capturing recurring revenue. Competitive moves concentrate on strategic partnerships for charging infrastructure access and geographic expansion through localized assembly joint ventures.
Within the integrated powertrain tier, Daimler Truck AG and Volvo Group exemplify established European engineering consolidation. Tata Motors anchors cost-engineered platform development for emerging-market distribution density. These three entities represent divergent geographic and technological positioning archetypes without overlapping segment concentration.
| Leading Market Players |
|---|
| Daimler Truck AG |
| Volvo Group |
| PACCAR Inc. |
| Tata Motors |
| Traton SE |
| Ford Motor Company |
| General Motors |
| Ashok Leyland |
| Isuzu Motors |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate feedstock from Chilean and Australian mining operations flows through Chinese cathode processing before reaching battery pack assemblers, creating tiered pricing structures that separate premium long-haul electric tractors from cost-engineered urban delivery vans.
Pricing Analysis
Distributor margins for heavy-duty diesel powertrains compress as aftertreatment systems commoditize, while battery-electric configurations command premium positioning through integrated telematics bundling. Three-tier pricing structure across premium, standard, and economy levels separates Daimler Truck AG's integrated powertrain architectures from Tata Motors' cost-engineered platforms and emerging Chinese OEMs' cell-scale advantages. Fleet aggregators in Germany and the Netherlands are driving pricing pressure through per-kilometer operating leases that transfer residual value risk. Small logistics operators exhibit highest price sensitivity, while mining and construction buyers prioritize durability specifications over first-cost considerations.
Supply Chain Analysis
Remanufacturing flows for diesel engine blocks and electric motor cores are concentrating in Mexico and Thailand to serve North American and Southeast Asian aftermarket demand with reduced logistics exposure. Battery cell production draws from Chinese lithium-iron-phosphate chemistry and South Korean nickel-cobalt-manganese formulations, creating dual-track dependencies for OEMs balancing cost against energy density requirements. Single-source vulnerability in rare-earth magnet supply from Chinese processing facilities threatens motor production timelines. Distribution runs through captive OEM service networks for premium segments and independent aftermarket channels for economy-tier replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as fleet operators prioritize total cost of ownership over procurement price, with telematics integration and predictive maintenance capability becoming baseline requirements rather than premium differentiators.
For Market Incumbents: Deploy software-defined vehicle architectures to capture recurring revenue through over-the-air feature monetization. Daimler Truck AG and Volvo Group should accelerate hydrogen fuel cell development for regional haul segments where battery weight compromises payload capacity, defending against emerging Chinese OEMs exploiting domestic cell manufacturing scale. Channel control through captive financing arms retains fleet customer relationships against asset-light third-party aggregators. For New Entrants and Emerging Players: The price-point gap between premium European integrated powertrains and economy-tier Chinese battery-electric platforms offers white-space opportunity for mid-market regional haul specialization. Target India's formalizing cold-chain logistics networks where BIS certification requirements and PLI scheme incentives reshape competitive entry conditions. Pursue joint venture assembly with Tamil Nadu manufacturing corridors to satisfy domestic content thresholds while accessing component localization investments. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined vehicle capability gaps separate viable platforms from stranded mechanical-differentiation assets. Long-term viability favors OEMs with captive battery supply agreements and autonomous haulage validation in closed environments. Acquisition targets include telematics-as-a-service platforms with predictive maintenance algorithm deployment and Nordic autonomous pilot operators. Monitor EPA Phase 3 compliance cost divergence between California's Advanced Clean Trucks rule and US Sun Belt diesel retention for geographic portfolio reallocation signals.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell manufacturing scale in China decouples European OEMs from import-dependent cathode processing. |
| Software-Defined Vehicle Investment | Over-the-air capability updates enable feature monetization beyond initial vehicle sale for recurring revenue. |
| Charging Infrastructure Partnership | Highway corridor electrification partnerships address operational range anxiety for transcontinental operators. |
| Geographic Manufacturing Footprint | Tamil Nadu and Maharashtra assembly localization satisfies India's PLI scheme domestic content thresholds. |
| Platform Standardization | Modular chassis architectures reduce engineering costs across light-duty and medium-duty product portfolios. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator logistics directors, and aftermarket service heads grounded qualitative insights in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA Phase 3 regulatory filings, and EU Green Deal implementation trackers. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers across the analysis window.
Segmentation outputs reflect modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from production volume trajectories, fleet replacement cycle analysis, and regulatory compliance timeline alignment. Industry-specific inputs incorporated MIIT dual carbon certification schedules and NHTSA safety protocol implementation phases.
Caveats apply where lithium price volatility, charging infrastructure deployment gaps, or regulatory divergence between California Air Resources Board and EU Whole Vehicle Type Approval could materially shift the outlook. Practitioners should monitor cell manufacturing capacity utilization rates and autonomous haulage pilot regulatory sandbox expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
United States Vans Market