
 Automotive Trailer Market | 2026-2036
Automotive Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trailer Market Intelligence
The European Union's updated General Safety Regulation is rebalancing the cost-of-entry calculus for manufacturers by mandating advanced safety features. Wabash National Corporation leverages its manufacturing scale to serve large North American fleet operators. In Europe, Schmitz Cargobull differentiates with advanced telematics and modular designs. Utility Trailer Manufacturing Company sustains its market presence through a strong focus on refrigerator trailers and a vast service network.
An automotive trailer is an unpowered vehicle, typically featuring a high-strength steel or aluminum frame, designed to be towed by a motorized vehicle. Its primary purpose is the bulk transport of goods and equipment over public roadways. Axle configurations and suspension systems are engineered for specific load capacities and deployment environments like construction sites or logistics hubs. Flatbed and enclosed trailers constitute the largest segments by volume, while specialized refrigerator trailers offer higher margins for fleet operators in the cold chain.
Compliance frameworks such as the U.S. Department of Transportation's federal motor vehicle safety standards and the EU's vehicle type-approval system are critical. These regulations mandate specific performance criteria for braking, lighting, and underride protection, influencing design and market access. Future investment decisions for manufacturers will hinge on balancing the development of EV-compatible trailers against optimizing current designs for maximum fuel efficiency and payload.
Market Dynamics
The central tension in the automotive trailer market is the conflict between regulatory mandates for advanced safety systems and the commercial imperative for maximizing payload capacity. This dynamic forces manufacturers to innovate with lightweight materials and aerodynamic designs to offset the weight and cost of new, required technologies.
Growth Catalysts
- Freight Forwarder Demand:Major logistics and freight forwarding companies require higher-capacity trailers to improve operational efficiency, driving investment in advanced axle configurations and high-strength steel frames for greater payload.
- EU Safety Mandates:The European Union's updated General Safety Regulation requires features like tire pressure monitoring and advanced emergency braking, creating a non-discretionary demand floor for trailers equipped with these technologies.
- US Logistics Network:The vast scale of the United States' interstate commerce system sustains consistent demand for durable long-haul trailers, particularly enclosed and flatbed models, to service its extensive supply chains.
Market Restraints
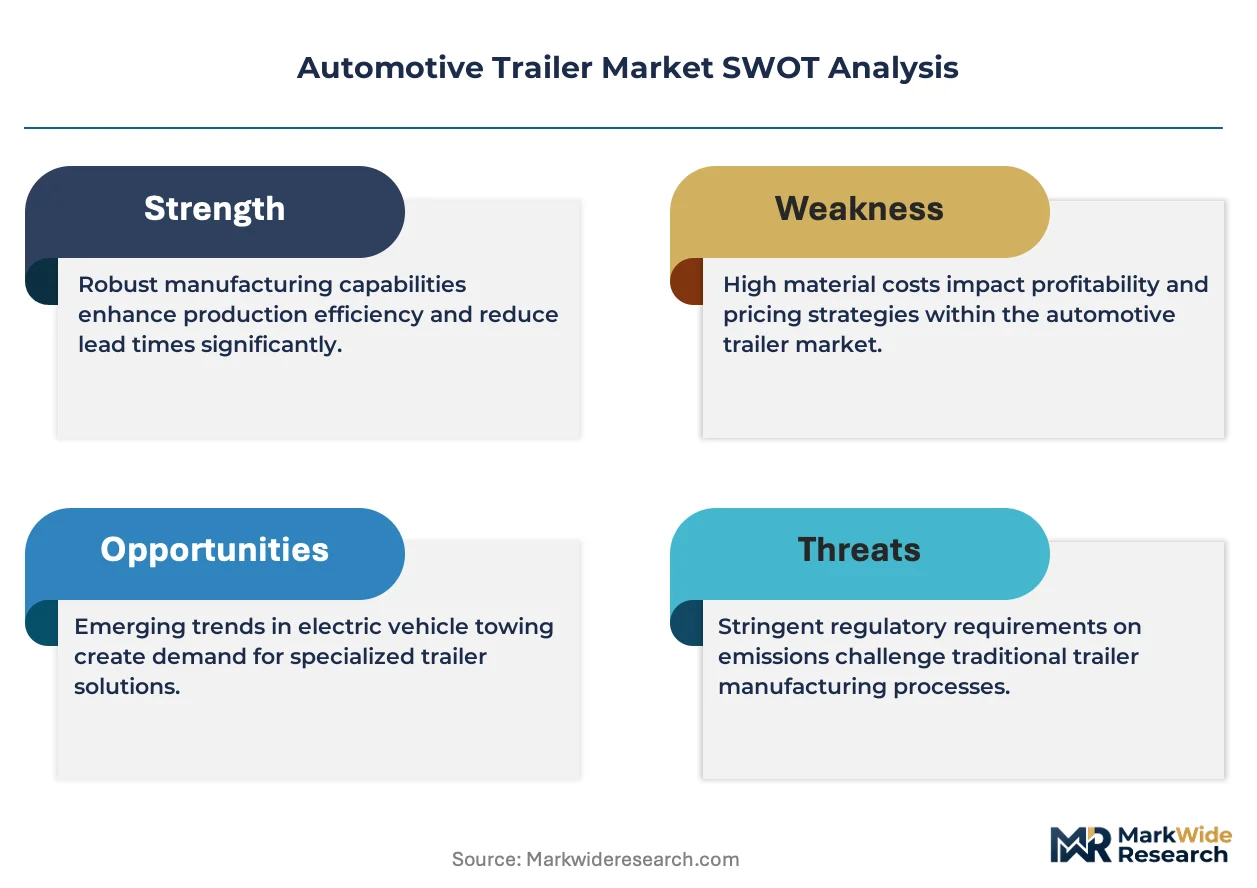
- Input Cost Volatility:Fluctuations in the price of essential raw materials, particularly high-strength steel and aluminum, create margin pressure for manufacturers and introduce pricing uncertainty for fleet operators.
- Payload Penalties:The additional weight of components required for EV-compatible trailers, such as reinforced frames or onboard charging hardware, can reduce maximum legal payload, a critical factor for operator profitability.
- Regulatory Divergence:Disparate standards between the U.S. Department of Transportation and the EU's type-approval framework for aspects like lighting and underride guards increase design complexity and compliance costs.
Strategic Opportunities
- Predictive Maintenance Services:The convergence of onboard telematics with cloud-based analytics allows manufacturers to offer predictive maintenance as a recurring revenue service, moving beyond the initial equipment sale.
- Cold Chain Expansion:Growing global demand for temperature-sensitive pharmaceuticals and perishable foods creates a high-margin opportunity for advanced refrigerator trailers equipped with precise climate control and tracking systems.
- Emerging Market Logistics:Developing logistics infrastructure in regions like Southeast Asia presents an opportunity for manufacturers to introduce mid-range, robust trailers tailored for less-developed road networks.
Industry Challenges
- Specialized Technician Scarcity:A shortage of technicians trained to diagnose and service complex electronic braking systems and integrated telematics platforms creates a maintenance bottleneck for modern fleets.
- High Capital Investment:Retooling manufacturing facilities to accommodate new materials like carbon fiber composites or to build structurally different EV-compatible trailer designs requires significant capital expenditure.
- Legacy System Integration:Integrating smart trailer data streams with the diverse and often outdated fleet management software used by many smaller logistics companies poses a significant interoperability challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trailer Market |
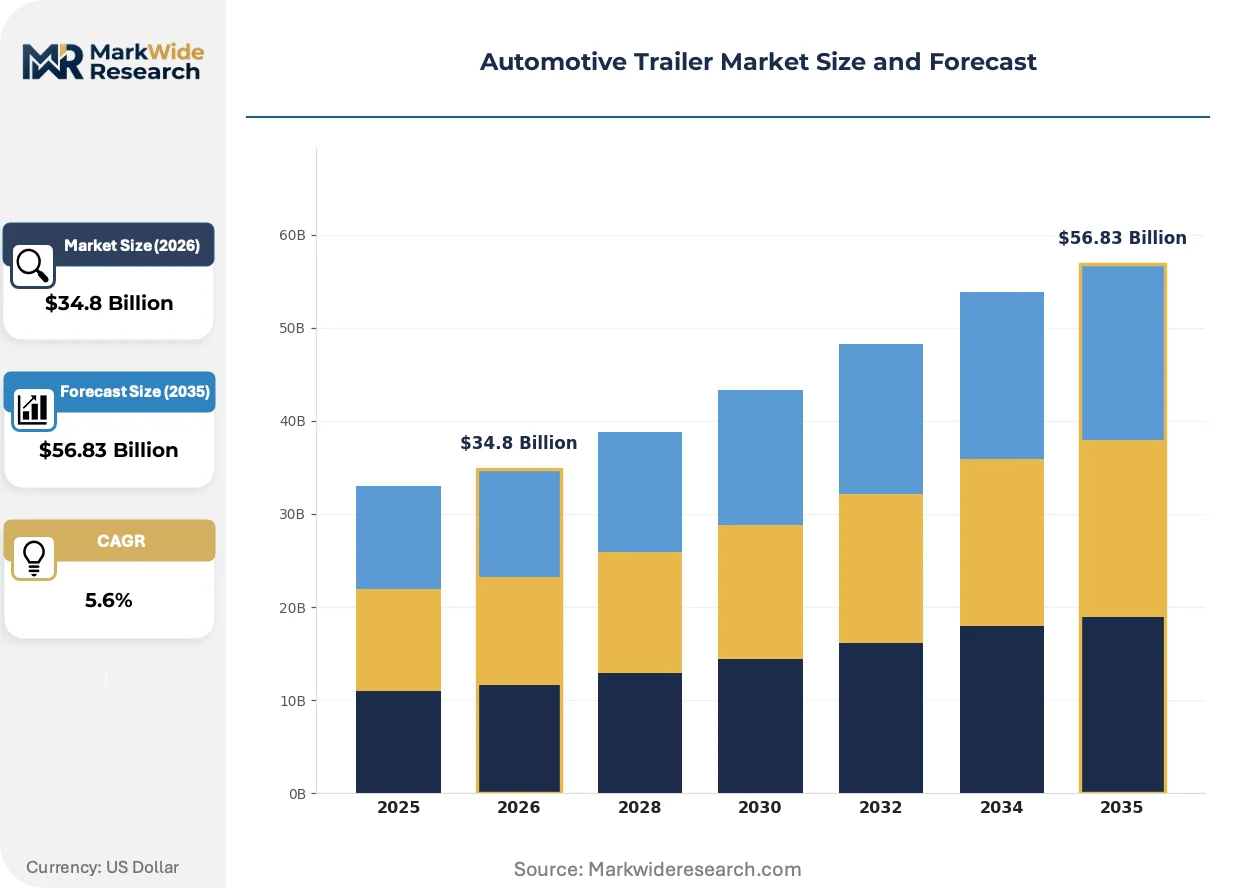
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $56.83 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trailer Type: Flatbed, Enclosed, Dump, Refrigerator, Tanker, Lowboy Powertrain Compatibility: Internal Combustion, Hybrid, Electric, Hydrogen Fuel Cell Deployment Environment: Construction Sites, Logistics Hubs, Agriculture Fields, Warehousing Units End User Segment: Fleet Operators, Freight Forwarders, Specialty Carriers, Equipment Rentals |
| Companies Covered | Wabash National Corporation, Utility Trailer Manufacturing Company, Great Dane, Schmitz Cargobull, Hyundai Translead, Böckmann Fahrzeugwerke GmbH, Dennison Trailers Ltd., Humbaur GmbH, Ifor Williams Trailers Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trailer Market Strategic Shifts & Innovations
The market's evolution is defined by the trailer's transformation from a passive container into an intelligent, data-generating asset. This shift is driven by the parallel pressures of digitalization for efficiency and sustainability mandates for reduced environmental impact, fundamentally altering design priorities and operational capabilities.
Advanced telematics systems incorporate GPS tracking, cargo status sensors, and tire pressure monitoring into a single, connected platform. Large fleet operators and freight forwarders are the primary adopters, seeking to maximize asset utilization and operational visibility. The integration of these hardware and software components is unifying previously separate data streams, enabling holistic fleet management and predictive diagnostics.
Regulatory frameworks globally are compelling design changes. China's GB standards for commercial vehicles, for instance, mandate stricter performance for braking and stability control. This forces manufacturers to integrate anti-lock braking systems and more aerodynamic features as standard. The enclosed and flatbed trailer segments are most affected, prompting design upgrades to maintain access to the country's vast logistics market.
A clear behavioral change is the move from outright equipment purchases toward long-term, full-service leasing models. This procurement shift transfers the responsibilities of maintenance, regulatory compliance, and technology upgrades from the operator to the leasing provider. The trend is most visible in Europe, where a focus on total cost of ownership encourages fleet managers to favor flexible, service-oriented contracts.
Automotive Trailer Market Segmentation
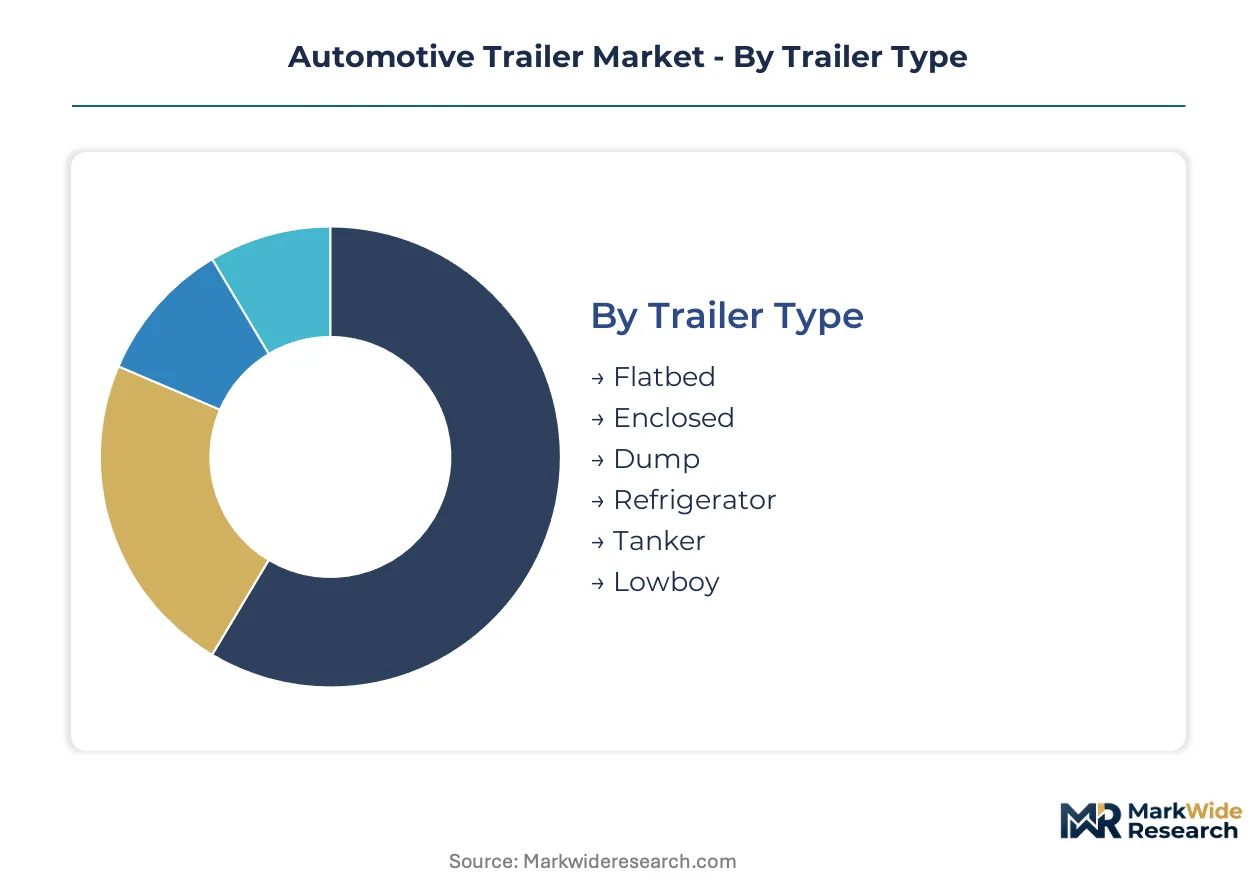
Market segmentation clarifies the diverse requirements driving demand across the automotive trailer industry. Understanding these distinctions allows manufacturers to tailor product development, optimize production lines, and align sales strategies with specific customer needs and regulatory landscapes. This granular view reveals where investment in advanced features or specialized designs yields the highest returns.
Trailer Type:
Supply concentration for automotive trailers remains strong in high-volume, general-purpose units, dictating manufacturing scale and material procurement for many producers.
- Enclosed:These trailers feature a fully enclosed cargo area, typically constructed from aluminum or steel panels, providing protection from weather and theft. Demand concentrates in the United States, driven by extensive interstate commerce requiring secure transport of general freight and consumer goods.
- Refrigerator:Equipped with insulated walls and a refrigeration unit, these trailers maintain precise temperature control for perishable goods or pharmaceuticals. Demand concentrates in Europe, spurred by stringent cold chain logistics requirements and a growing market for temperature-sensitive products.
- Flatbed:Open platforms without sides or a roof, flatbed trailers transport oversized or irregularly shaped cargo such as construction materials or heavy machinery.
- Dump:Designed with a hydraulic lifting mechanism, dump trailers facilitate the efficient unloading of bulk materials like sand, gravel, or agricultural produce.
- Tanker:Specialized cylindrical or elliptical vessels, tanker trailers transport liquids, gases, or dry bulk commodities, requiring specific safety and containment features.
- Lowboy:Featuring a drop-deck design, lowboy trailers accommodate the transport of tall or heavy equipment by lowering the center of gravity for improved stability.
Today's leader: Enclosed. Tomorrow's challenger: Refrigerator.
Powertrain Compatibility:
Cost tiers for powertrain compatibility heavily influence adoption rates, with established technologies offering lower upfront investment while newer options carry a premium for innovation.
- Internal Combustion:Trailers designed to be towed by traditional internal combustion engine (ICE) vehicles remain the market standard, optimized for fuel efficiency and payload capacity. This segment experiences consistent demand from established logistics companies globally, relying on existing fleet infrastructure and proven operational models.
- Electric:These trailers incorporate features like regenerative braking or integrated battery packs to reduce the energy consumption of electric towing vehicles, often requiring reinforced frames. Demand is expanding most quickly in Europe, driven by ambitious decarbonization targets and incentives for zero-emission transport solutions.
- Hybrid:Trailers compatible with hybrid towing vehicles offer a transitional solution, balancing traditional power with electric assistance to optimize fuel consumption.
- Hydrogen Fuel Cell:This emerging segment involves trailers designed to integrate with or be powered by hydrogen fuel cell vehicles, offering zero-emission transport with rapid refueling capabilities.
Internal Combustion still holds market dominance. Electric is climbing the fastest.
Deployment Environment:
Application diversity across deployment environments shapes specialized design requirements, from rugged construction site durability to precision logistics hub maneuverability.
- Logistics Hubs:Trailers for logistics hubs prioritize efficient loading, unloading, and maneuverability within confined spaces, often featuring advanced telematics for asset tracking. Demand concentrates in the United States, driven by the vast network of distribution centers and the need for optimized freight flow.
- Construction Sites:Designed for durability and heavy-duty performance, trailers for construction sites transport materials, equipment, and machinery over rugged terrain. Demand is gaining share fastest in developing economies, fueled by infrastructure projects and urbanization.
- Agriculture Fields:These trailers are engineered for specific agricultural tasks, including transporting crops, livestock, or farm equipment across varied rural landscapes.
- Warehousing Units:Trailers deployed in warehousing units often focus on internal transport efficiency, facilitating the movement of goods between storage areas and loading docks.
Logistics Hubs represent the largest application. Construction Sites are expanding quickly.
End User Segment:
Customer type significantly influences procurement patterns, with large fleet operators demanding scale and standardization, while specialty carriers require highly customized solutions.
- Fleet Operators:Large logistics companies managing extensive vehicle fleets require durable, high-capacity trailers for general freight and diverse operational needs. These operators prioritize total cost of ownership and seek advanced telematics for fleet management across North America.
- Freight Forwarders:Companies specializing in organizing shipments for individuals or corporations require efficient, reliable trailers capable of handling varied cargo types and volumes. Freight forwarders in Europe increasingly adopt modular designs for operational flexibility and compliance with evolving safety mandates.
- Specialty Carriers:These operators handle unique cargo, such as oversized loads, hazardous materials, or highly sensitive equipment, necessitating custom-built trailers with specific safety and handling features.
- Equipment Rentals:Rental companies provide temporary access to trailers for various purposes, serving a broad customer base from small businesses to individual users.
Fleet Operators drive the largest volume. Freight Forwarders exhibit significant growth in specialized units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled manufacturing workforce in key industrial regions anchors global automotive trailer production. These regions benefit from established supply chains and engineering expertise, driving innovation in trailer design and functionality. Demand for high-capacity and specialized units influences regional market dynamics.
United States
Consistent demand for durable long-haul trailers in the United States stems from its vast interstate commerce and logistics network. The U.S. Department of Transportation mandates specific performance criteria for braking and lighting, influencing trailer design. Indiana's manufacturing hubs remain central to North American production of enclosed and flatbed models.
Germany
German manufacturers prioritize advanced telematics and modular designs for European fleet operators. The EU's General Safety Regulation mandates advanced safety features, impacting design and market access. Production clusters in Bavaria and Lower Saxony focus on specialized units like refrigerator trailers for precise climate control.
China
China's vast logistics market and ongoing infrastructure development sustain significant demand for both enclosed and flatbed trailers. The nation's GB standards mandate stricter performance for braking and stability control, driving design upgrades. Manufacturing centers in the Yangtze River Delta actively integrate these compliance requirements into new vehicle platforms.
India
Developing logistics infrastructure in India drives demand for robust, mid-range trailers tailored for varied road networks. The country's national vehicle load capacity norms influence axle configurations and frame construction. Industrial zones in Maharashtra and Gujarat are expanding production to meet this growing domestic need.
France
French fleet managers increasingly favor full-service leasing models for trailer procurement, focusing on total cost of ownership. The EU's type-approval framework influences design for aspects like lighting and underride protection. Automotive manufacturing zones in the Grand Est region support production of advanced trailers for cross-border European transport.
Automotive Trailer Market Key Industry Players
The competitive structure tilts toward established manufacturers leveraging scale and specialized product portfolios. The market exhibits a tiered consolidation, with large players dominating high-volume general-purpose segments and niche specialists serving particular applications. Companies pursue strategic partnerships for technology integration and engage in capacity expansion to meet regional demand and regulatory shifts. Portfolio diversification into advanced telematics and cold chain solutions represents a key competitive move for market differentiation.
Among North American and European manufacturers, Wabash National Corporation exemplifies a scaled producer serving large North American fleet operators with a broad product range of enclosed and flatbed units. Germany-based Schmitz Cargobull occupies a position as an innovator, differentiating with advanced telematics and modular designs specifically for European markets and their evolving safety mandates. Utility Trailer Manufacturing Company, a North American entity, anchors its market presence through a strong focus on high-margin refrigerator trailers and an extensive service network, representing a specialist in temperature-controlled logistics solutions across the continent.
| Leading Market Players |
|---|
| Wabash National Corporation |
| Utility Trailer Manufacturing Company |
| Great Dane |
| Schmitz Cargobull |
| Hyundai Translead |
| Böckmann Fahrzeugwerke GmbH |
| Dennison Trailers Ltd. |
| Humbaur GmbH |
| Ifor Williams Trailers Ltd. |
Cost & Logistics Intelligence
The global high-strength steel price index significantly influences automotive trailer manufacturing costs, cascading directly into final product pricing tiers. This volatility necessitates dynamic pricing strategies across general-purpose and specialized units.
Pricing Analysis
Bundled maintenance and telematics services often differentiate pricing from unbundled equipment sales in the automotive trailer market. Per-unit transactional sales dominate, complemented by subscription models for advanced features like predictive diagnostics. Customization levels for specialized units and after-sales service network access command premium pricing, though pricing softness reflects intense competition in high-volume enclosed and flatbed segments. Small logistics companies exhibit high price sensitivity, while large fleet operators prioritize total cost of ownership.
Supply Chain Analysis
Direct-to-fleet sales channels manage large operator procurement, with regional dealerships serving smaller buyers, while manufacturing concentrates in the United States, Germany, and China, leveraging established industrial bases. The industry relies heavily on high-strength steel, aluminum, and advanced electronic components for telematics and safety systems. Commodity price volatility for steel and aluminum creates a significant structural risk, impacting manufacturer margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive trailer market functions as a stable compounder, driven by persistent global demand for goods transport and the continuous evolution of logistics networks. Investment in essential transport infrastructure ensures consistent, long-term growth.
For Market Incumbents: Extend existing service networks to cover emerging markets and new technology integration points, particularly for advanced telematics. Invest in modular design platforms to reduce manufacturing complexity and facilitate rapid adaptation to evolving safety mandates. R&D into lightweight materials like carbon fiber composites is a critical lever to mitigate payload penalties from EV-compatible trailers. Strategic partnerships with charging infrastructure providers can also broaden service offerings.
For New Entrants and Emerging Players: The European Union's updated General Safety Regulation in Europe opens a window for specialized manufacturers focusing on advanced safety features. Target mid-range, robust trailers for construction sites in developing economies like India and Southeast Asia. Develop advanced refrigerator trailers for temperature-sensitive pharmaceuticals, emphasizing precise climate control. Full-service leasing models offer a compelling go-to-market angle, reducing operator upfront capital expenditure.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized manufacturers integrating advanced telematics and cold chain technologies into their product lines. The market demonstrates long-term viability over a 5-10 year window, driven by logistics modernization and stringent regulatory compliance. Target mid-cap innovators with strong intellectual property in smart trailer systems or modular designs. The rate of EV-compatible trailer adoption in commercial fleets serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Streamlines manufacturing processes and reduces production costs for Wabash National Corporation. |
| Telematics Integration | Enhances operational efficiency and predictive maintenance offerings for Schmitz Cargobull customers. |
| Cold Chain Capacity Expansion | Addresses growing global demand for temperature-sensitive pharmaceuticals and perishable foods. |
| Lightweight Material R&D | Mitigates payload penalties associated with EV-compatible trailer designs and improves fuel efficiency. |
| Full-Service Leasing Models | Shifts procurement patterns in Europe, offering total cost of ownership advantages to fleet managers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel, forming the bedrock of this analysis. Primary interviews engaged fleet operators, manufacturing R&D directors, logistics managers, and regulatory compliance officers. Secondary validation drew from U.S. Department of Transportation reports, EU vehicle type-approval documents, company annual filings, and industry association publications. Bottom-up market sizing was triangulated with top-down validation against macroeconomic indicators.
Segment-specific weighting factors were applied to project growth across the analysis window, integrating historical performance data with future projections. Segmentation dimensions modeled included trailer type, powertrain compatibility, deployment environment, end-user, and regional regulatory compliance. Compound annual growth rates derived from a multi-variant regression model incorporated freight volume forecasts and raw material price trends.
Revisions are triggered by shifts in global trade or raw material supply, reflecting the inherent assumptions on economic stability and regulation. Geopolitical events or accelerated EV adoption could significantly revise these projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Europe Recreational Vehicle Market