
 Peru Commercial Vehicle Market | 2026-2036
Peru Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Commercial Vehicle Market Insights
Modular chassis-and-body bundling is consolidating buyer choice across Peru's commercial vehicle landscape. Toyota leverages its Hilux platform dominance to anchor fleet contracts in coastal agriculture and mining supply chains. Volvo Group competes through specialized heavy-duty configurations for Andean altitude operations, while DFSK sustains cost-positioned van sales among Lima-based last-mile delivery operators.
A commercial vehicle comprises a motorized road transport unit engineered for goods carriage or passenger movement, typically featuring a ladder-frame chassis, gross vehicle weight ratings exceeding 3.5 tonnes, and powertrains calibrated for continuous-duty cycles rather than consumer drive patterns. Diesel fuel type retains structural leadership in long-haul trucking and construction applications where torque requirements and refueling infrastructure density favor compression-ignition engines, though electric van configurations are gaining fastest growth in urban delivery segments where range anxiety diminishes and municipal access restrictions tighten. The logistics end user segment occupies the deepest margin pool as third-party fleet operators prioritize total cost of ownership metrics over acquisition price in procurement decisions.
Peru's Ministry of Transport and Communications enforces vehicle homologation standards aligned with United Nations Economic Commission for Europe frameworks, while the Ministry of Environment administers emissions testing protocols that shape diesel engine eligibility for metropolitan circulation permits. The Superintendency of Banking, Insurance and Private Pension Funds indirectly influences fleet finance accessibility through commercial credit provisioning rules. Stakeholders must monitor regulatory calibration between emissions stringency and infrastructure readiness as electrification timelines compress without corresponding charging network deployment in the Sierra and Amazon regions.
Market Dynamics
Emissions compliance timelines from Peru's Ministry of Transport and Communications are compressing diesel fleet replacement cycles while mining output expansion sustains heavy-duty procurement volumes. This regulatory-production tension defines current market mechanics.
Growth Catalysts
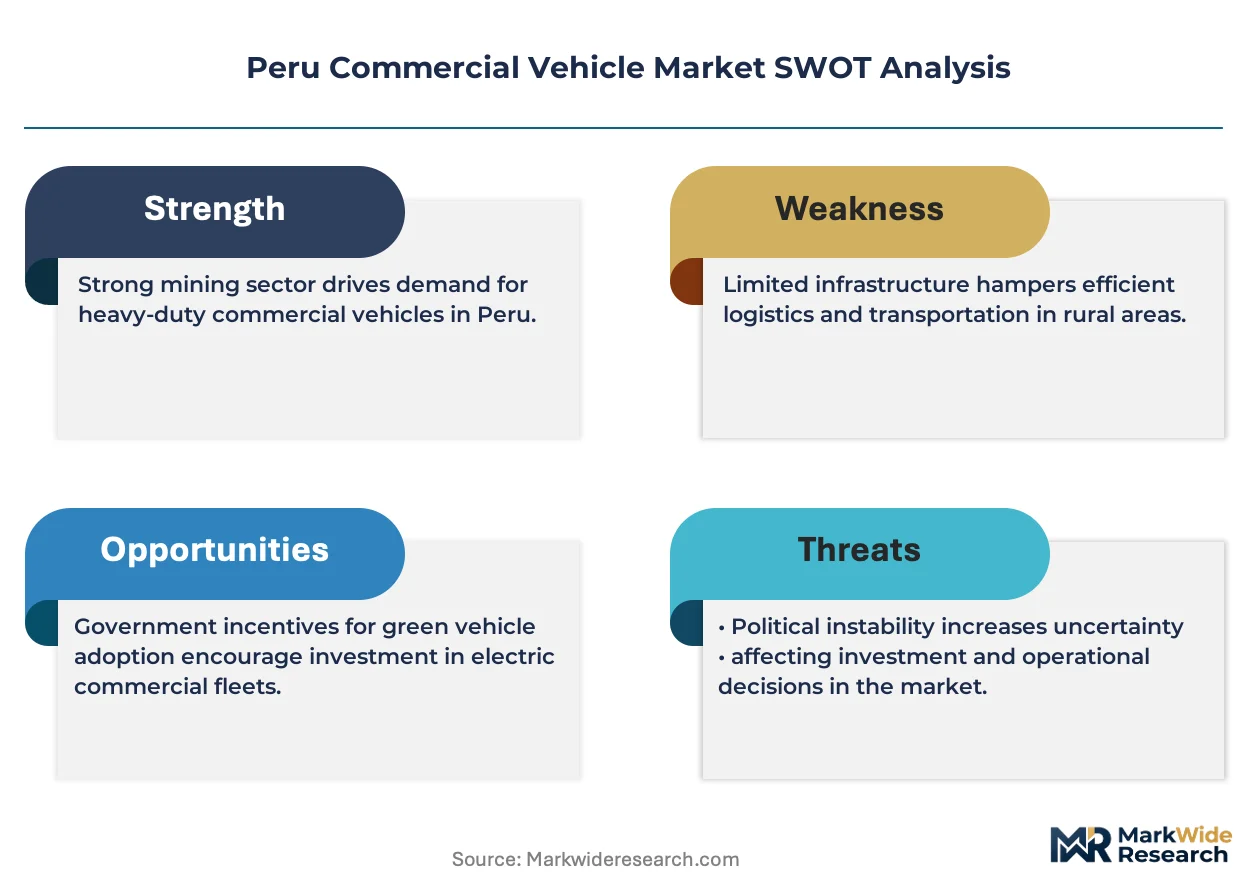
- Extractive sector fleet renewal:Mining operators in the Andean region are accelerating heavy-duty truck procurement to match copper and gold production targets. This sustains premium vehicle demand despite financing headwinds.
- Port logistics corridor concentration:The Lima-Callao metropolitan cluster generates concentrated commercial vehicle utilization through warehousing expansion and container throughput growth. Fleet operators prioritize route density in this corridor.
- Emissions testing protocols:Peru's Ministry of Environment has tightened metropolitan circulation permit eligibility, forcing older diesel units into replacement cycles. This regulatory pressure creates structured demand for compliant powertrains.
Market Restraints
- Charging infrastructure gaps:The Sierra and Amazon regions lack sufficient high-capacity charging deployment for electric commercial vehicle operation. This geographic asymmetry limits electrification beyond coastal urban centers.
- Import dependency for powertrain components:Diesel engine and transmission supply concentrates with European and Asian manufacturing bases. Currency volatility against the US dollar amplifies landed cost uncertainty for Peruvian fleet buyers.
- Altitude performance degradation:Andean operations above 4,000 meters impose 25-30% power loss on naturally aspirated engines. This technical limitation forces costly turbocharging specifications or reduced payload configurations.
Strategic Opportunities
- Amazon basin last-mile electrification:Urban delivery operators in Iquitos and other Amazonian cities face no intercity range constraints. Battery-electric vans can capture this captive geography before infrastructure spreads to long-haul corridors.
- Modular chassis-body bundling:Agricultural cooperatives and mining contractors seek standardized platforms with application-specific body configurations. This convergence of chassis commonality and body specialization opens margin expansion for flexible assemblers.
- Domestic assembly incentives:Peru's Ministry of Production has signaled preferential tax treatment for locally assembled commercial vehicles. This policy tailwind rewards investment in regional manufacturing footprints over pure import models.
Industry Challenges
- Homologation timeline compression:Peru's Ministry of Transport and Communications has aligned with United Nations Economic Commission for Europe frameworks, extending certification cycles for new powertrain entrants. This compliance burden delays product launches by 8-14 months.
- Technician training deficits:High-voltage electric powertrain maintenance requires skills absent from Peru's existing automotive vocational pipeline. Fleet operators face service capacity constraints as electrified units enter warranty periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Commercial Vehicle Market |
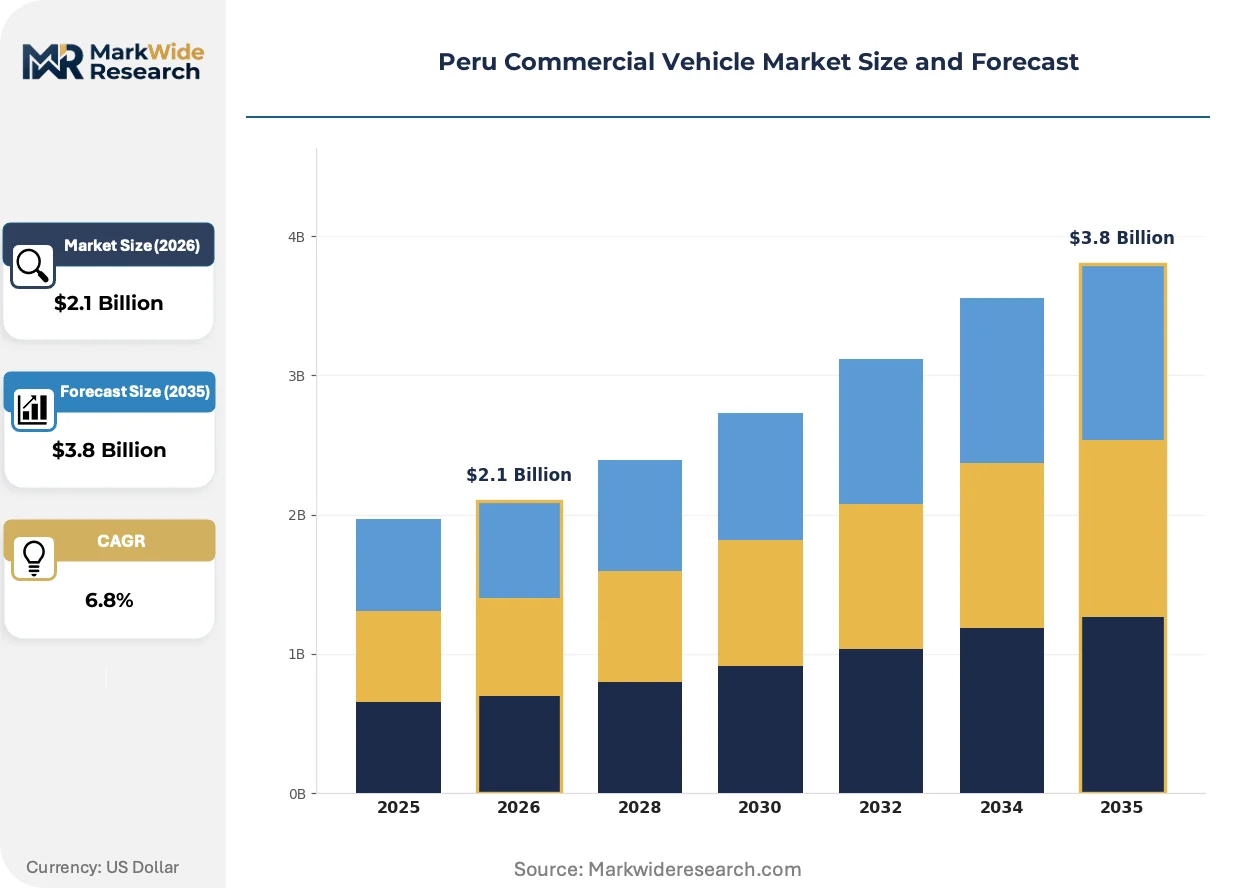
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Truck, Bus, Van, Trailer Fuel Type: Diesel, Gasoline, LPG, Electric Application: Transportation, Delivery, Construction, Agriculture End User: Logistics, Retail, Public Sector, Enterprises |
| Companies Covered | Changan, DFSK, Jiangling Motors Group, Chevrolet, Toyota, Nissan, Daimler, Volvo Group, PACCAR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Commercial Vehicle Market Trends and Innovations
Powertrain electrification and digital fleet management are converging to reshape asset utilization models across Peru's commercial vehicle base. These shifts compress traditional ownership cycles while opening new service revenue streams.
Modular battery-electric platforms are consolidating urban delivery fleet specifications in Lima's metropolitan zone. Last-mile operators at Mercado Libre and regional logistics providers specify standardized van architectures with swappable battery configurations. This technology is consolidating procurement decisions around total cost of ownership metrics rather than acquisition price alone.
Peru's Ministry of Environment has implemented emissions testing protocols that disqualify pre-Euro 4 diesel engines from metropolitan circulation permits. This regulatory tightening forces mining supply chain operators to accelerate fleet replacement ahead of depreciation schedules. Heavy-duty configurations for Andean altitude operations face the steepest compliance premiums.
Third-party fleet operators are unbundling after-sales service from vehicle purchase contracts, contracting maintenance separately through specialized providers. This buying-pattern shift disrupts traditional dealer channel economics in the Lima-Callao corridor. Mining contractors in the central Sierra region have pioneered this separation, treating vehicles as depreciating assets and maintenance as variable operating expenditure.
Peru Commercial Vehicle Market Segmentation
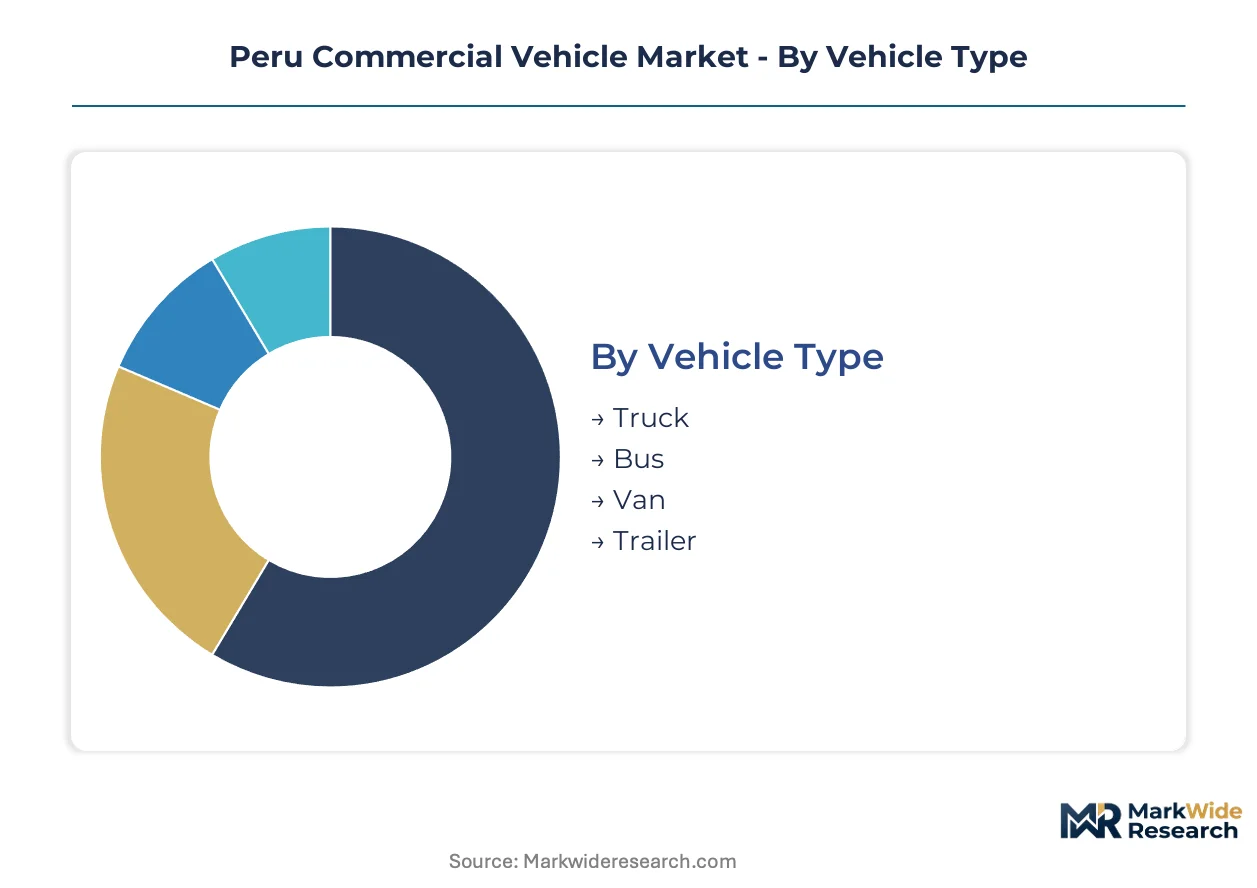
Segmentation in Peru's commercial vehicle market reveals how capital deployment, regulatory exposure, and altitude performance requirements fragment procurement decisions. Fleet operators balance acquisition cost against total cost of ownership across distinct operational profiles.
Vehicle Type:
Capital intensity varies sharply across chassis configurations, with heavy-duty platforms demanding substantially higher upfront investment than light commercial units.
- Truck:Heavy-duty configurations dominate mining supply chains and Andean freight corridors. Copper extraction operators in the central Sierra specify turbocharged diesel powertrains calibrated for altitude compensation above 4,000 meters. These units absorb the largest share of fleet finance capacity.
- Bus:Urban transit specifications concentrate in Lima-Callao metropolitan corridors where passenger volume justifies dedicated infrastructure. Interprovincial operators favor modular chassis platforms with standardized body mounting for route flexibility.
- Van:Last-mile delivery operators in coastal cities specify compact footprints for dense urban navigation. Battery-electric configurations are penetrating this segment fastest where daily range requirements stay below 150 kilometers.
- Trailer:Container logistics at Callao port drives specialized flatbed and refrigerated specifications. Third-party fleet operators treat trailers as separate depreciating assets from tractor units.
Trucks absorb the bulk of installed capacity; vans are expanding most quickly.
Fuel Type:
Powertrain selection tracks infrastructure density and regulatory pressure gradients across Peru's coastal, mountain, and jungle regions.
- Diesel:Compression-ignition engines retain structural leadership in long-haul and construction applications. Peru's Ministry of Environment emissions testing protocols now disqualify pre-Euro 4 units from metropolitan circulation permits, compressing replacement cycles.
- Gasoline:Light commercial applications in urban centers specify spark-ignition powertrains for lower acquisition cost. Fuel price volatility against the sol creates operating expenditure uncertainty for fleet managers.
- LPG:Alternative fuel conversions target cost-sensitive operators in provincial cities with established refueling networks. Conversion economics depend on annual mileage thresholds above 30,000 kilometers.
- Electric:Battery-electric vans penetrate Lima's last-mile delivery segment where municipal access restrictions tighten. Charging infrastructure gaps in the Sierra and Amazon regions constrain geographic expansion.
Diesel retains dominant installed base; electric powertrains are climbing the fastest.
Application:
Operational duty cycles determine depreciation rates and residual value calculations across commercial vehicle portfolios.
- Transportation:Long-haul freight between Lima and provincial centers specifies sleeper cab configurations for driver rotation compliance. Route density in the coastal corridor supports dedicated fleet investment.
- Delivery:Urban last-mile operations prioritize maneuverability and stop-start efficiency over highway cruising optimization. E-commerce logistics providers drive specification standardization.
- Construction:Off-road chassis with reinforced suspensions serve infrastructure projects in the Sierra. Payload ratings exceed highway-legal limits, restricting inter-site movement without permits.
- Agriculture:Coastal valley cooperatives specify flatbed and tanker configurations for produce and irrigation chemical transport. Seasonal demand peaks align with harvest windows.
Transportation applications deploy the greatest asset volume; delivery specifications are gaining share fastest.
End User:
Procurement authority and financing access differentiate customer segments in Peru's fleet-dominated market structure.
- Logistics:Third-party fleet operators prioritize total cost of ownership metrics over acquisition price, unbundling maintenance from purchase contracts. Mercado Libre and regional providers consolidate procurement for route density optimization.
- Retail:Large-format distributors specify dedicated delivery fleets for inventory control. Private label logistics investments separate from third-party contracting.
- Public Sector:Government procurement operates through centralized tender mechanisms with extended payment terms. Municipal transit authorities specify accessibility compliance in urban bus acquisitions.
- Enterprises:Mining contractors and agricultural cooperatives maintain captive fleets for supply chain control. Capital allocation competes with core operational investment priorities.
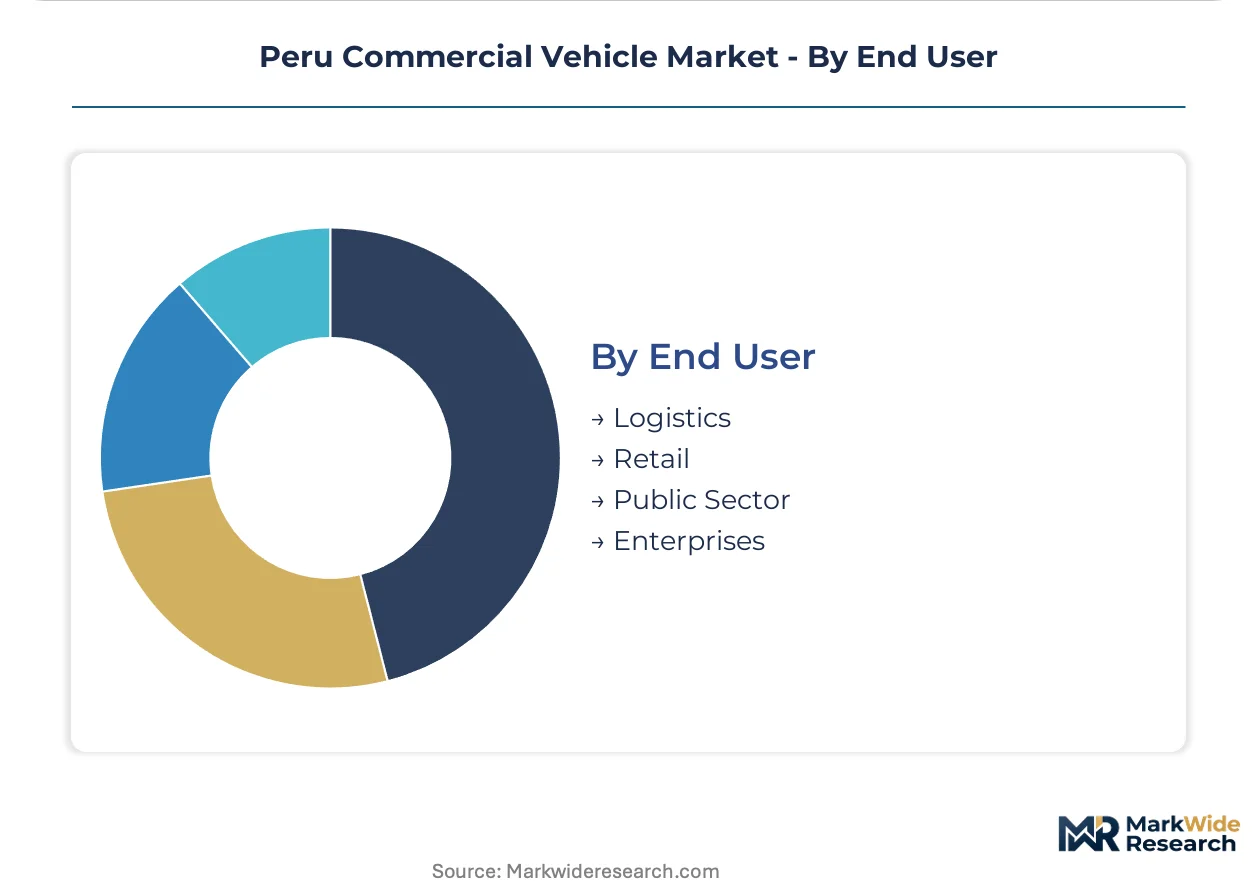
Logistics end users command the deepest procurement volume; enterprise fleets are restructuring most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's commercial vehicle production capacity concentrates in coastal assembly plants while consumption spreads across three distinct geographic zones with divergent infrastructure density and altitude challenges.
Lima-Callao Metropolitan Corridor
Port logistics and warehousing clusters drive concentrated commercial vehicle utilization in this coastal corridor. Peru's Ministry of Transport and Communications enforces emissions testing protocols that disqualify pre-Euro 4 diesel units from metropolitan circulation permits. Fleet operators in Callao prioritize route density optimization around container throughput expansion at the port.
Central Sierra Mining Belt
Copper and gold extraction operations sustain heavy-duty truck procurement despite financing headwinds from currency volatility. The Ministry of Environment administers emissions compliance timelines that compress fleet replacement cycles above 4,000 meters altitude. Mining contractors in Junín and Pasco regions specify turbocharged powertrains calibrated for 25-30% power loss compensation.
Arequipa-Tacna Southern Corridor
Agricultural cooperatives and mining supply chains generate dual-demand profiles for flatbed and tanker configurations. Peru's Ministry of Production signals preferential tax treatment for locally assembled vehicles. Coastal valley operations around Arequipa align seasonal demand peaks with harvest windows for produce transport.
Amazon Basin Urban Centers
Iquitos and other Amazonian cities present captive geographies for battery-electric van deployment without intercity range constraints. The absence of charging infrastructure in connecting corridors limits electrification to urban delivery circuits. Last-mile operators face no competition from long-haul diesel alternatives in this river-accessible zone.
North Coast Agricultural Valleys
Piura and La Libertad regions generate seasonal commercial vehicle demand for irrigation chemical transport and produce logistics. Coastal refueling infrastructure density favors compression-ignition engines over alternative powertrains. Agricultural cooperatives seek modular chassis platforms with standardized body mounting for harvest flexibility.
Peru Commercial Vehicle Market Competitive Landscape
The competitive structure tilts toward diversified multinational assemblers with regional manufacturing footprints. Heavy-duty specialists compete on altitude-calibrated configurations while mass-market brands dominate light commercial segments through fleet contract consolidation. Three strategic archetypes define positioning: mining-focused heavy-duty configurators, coastal agriculture-oriented light truck suppliers, and cost-positioned urban delivery van providers. Capacity expansion and modular chassis-body bundling constitute the dominant competitive moves.
Within the diversified multinational tier, Toyota leverages platform dominance to anchor fleet contracts, while Volvo Group occupies a position exemplifying heavy-duty specialization for Andean operations. DFSK represents the cost-positioned archetype targeting Lima-based last-mile delivery operators. These three companies illustrate how geographic coverage breadth, altitude technical capability, and acquisition price positioning segment competitive territory.
| Leading Market Players |
|---|
| Changan |
| DFSK |
| Jiangling Motors Group |
| Chevrolet |
| Toyota |
| Nissan |
| Daimler |
| Volvo Group |
| PACCAR |
| Others |
Pricing and Supply Chain Analysis
Fleet operators unbundling maintenance from purchase contracts force suppliers toward transparent lifecycle costing and compress upfront margin capture. Peru's Ministry of Transport and Communications emissions timelines accelerate compliant powertrain substitution, compelling importers to absorb currency volatility or cede volume to regional assemblers qualifying for domestic production incentives.
Pricing Analysis
Margin tightening in heavy-duty configurations reflects turbocharging premiums for altitude compensation and Euro 4-plus compliance costs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in light commercial segments intensifies as DFSK and Changan compete on acquisition price for Lima last-mile operators. Logistics end users exhibit lowest price sensitivity; provincial agricultural cooperatives remain most cost-responsive.
Supply Chain Analysis
Freight costs from Asian manufacturing bases amplify landed price uncertainty for Peruvian fleet buyers facing sol-dollar volatility. Diesel engine and transmission supply concentrates in Japan, Germany, and China. Steel, semiconductors, and battery cells constitute critical input dependencies. Single-source vulnerability in turbocharger components for altitude-rated powertrains threatens Andean mining fleet delivery schedules. Distribution runs through Callao port warehousing clusters and Lima metropolitan dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's commercial vehicle sector is consolidating around backward integration into regional assembly and captive after-sales service capacity. Players securing Ministry of Production preferential tax treatment and technician training pipelines will outcompete pure import-dependent rivals.
For Market Incumbents: Cement platform dominance through modular chassis-body bundling contracts with mining contractors and agricultural cooperatives. Defend against cost-positioned Chinese entrants by embedding telemetry-based fleet management into long-term service agreements. Prioritize technician certification programs for high-voltage powertrain maintenance before warranty capacity constraints erode customer retention. For New Entrants and Emerging Players: Mining supply chain procurement managers represent the most accessible entry channel for heavy-duty configurators lacking established Andean service networks. Amazon basin urban delivery operators in Iquitos present captive electrification opportunities without intercity infrastructure competition. Pursue joint service partnerships with existing Lima-Callao parts distributors to bypass homologation timeline delays. For Investors and Strategic Acquirers: The window for entry favors mid-scale assemblers with modular platform flexibility and existing regional manufacturing footprints. Long-term viability hinges on alignment with Peru's domestic assembly incentive trajectory and emissions compliance roadmap. Monitor Ministry of Environment metropolitan circulation permit enforcement intensity as the inflection signal for accelerated fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Reduces tooling costs for mining and agricultural body configurations across shared chassis architectures. |
| Domestic Assembly Footprint Expansion | Qualifies operators for Ministry of Production preferential tax treatment versus pure import competitors. |
| After-Sales Service Unbundling | Captures recurring revenue from logistics operators treating maintenance as variable operating expenditure. |
| Altitude Calibration Partnership | Secures mining fleet contracts through turbocharger specifications compensating 4,000-meter power loss. |
| Technician Training Pipeline Investment | Preempts service capacity constraints as battery-electric units enter warranty periods in Lima-Callao. |
Research Methodology
Independent corroboration across fleet procurement managers, mining supply chain operators, and Lima-based dealer principals underwrites the qualitative findings. Primary fieldwork engaged logistics directors at Mercado Libre and regional third-party providers, aftermarket service heads, and Ministry of Transport and Communications regulatory affairs contacts. Secondary validation drew from vehicle homologation filings, customs import records, and mining sector capital expenditure disclosures. Bottom-up fleet operator surveys and top-down production database triangulation anchored volume estimates.
Rate-of-change decomposition across vehicle type, fuel architecture, and altitude performance tier shaped the analytical framework. Segmentation modeling incorporated propulsion technology, application duty cycle, and regional infrastructure density throughout the forecast period. CAGRs derived from replacement cycle compression analysis and extractive sector production target alignment. Mining output trajectories and municipal emissions permit enforcement intensity served as industry-specific demand drivers.
Caveats apply where currency volatility against the US dollar, charging infrastructure deployment delays in the Sierra, or homologation timeline extensions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Van Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Semi-Tractor Trailer Market