
 Refrigerated Truck Market | 2026-2036
Refrigerated Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Truck Market Outlook
Third-party logistics providers is redrawing procurement patterns across the refrigerated truck landscape as pharmaceutical and e-grocery fulfillment volumes surge. Thermo King leverages its integrated transport refrigeration ecosystem to sustain technology leadership in electric and low-emission units. Carrier Transicold anchors North American fleet retrofit activity with aftermarket service density and dealer network control. Schmitz Cargobull dominates European trailer specifications through lightweight chassis engineering and modular body configurations.
Refrigerated trucks are insulated commercial vehicles engineered to maintain cargo temperatures between negative twenty-five and positive twenty degrees Celsius through vapor-compression or cryogenic refrigeration systems, with polyurethane foam insulation densities typically exceeding forty kilograms per cubic meter. Their primary purpose is to preserve perishable goods across multimodal supply chains where thermal deviation risks product loss or regulatory noncompliance. Trailer configurations command the largest installed base due to long-haul food distribution economics, while van segments represent the fastest-growing category as urban last-mile grocery delivery contracts multiply. Chassis-mounted systems concentrate margin pools among specialized upfitters serving pharmaceutical clients with validated temperature mapping and redundant cooling circuits.
The EPA regulates transport refrigeration unit emissions under Clean Air Act Title II standards, while the EU F-Gas Regulation mandates refrigerant phase-downs that reshape equipment procurement cycles across member states. NHTSA fuel economy standards for medium and heavy-duty vehicles further constrain powertrain choices, pushing fleet operators toward electrified refrigeration architectures. Stakeholders must monitor regulatory divergence between California's Advanced Clean Trucks mandate and federal baseline requirements, as compliance strategy fragmentation will determine equipment residual values and remarketing pathways.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets across European fleet procurement, forcing accelerated capital deployment into electric transport refrigeration units and alternative cooling architectures before hydrofluorocarbon phase-down deadlines bite.
Growth Catalysts
- Biologics distribution tightening:Pharmaceutical cold chains now require validated temperature mapping below negative seventy degrees Celsius for cell and gene therapies, expanding chassis-mounted system demand.
- California Advanced Clean Trucks mandate:Fleet operators face zero-emission sales quotas that accelerate electric refrigeration unit adoption alongside powertrain electrification.
- Urban last-mile grocery delivery:E-grocery fulfillment volumes are multiplying refrigerated van procurement in dense metropolitan corridors where trailer access is restricted.
Market Restraints
- Copper and aluminum price volatility:Vapor-compression unit manufacturing faces input cost swings that compress original equipment manufacturer margins and delay fleet refresh cycles.
- Compressor supplier concentration:European transport refrigeration depends on a narrow base of German and Italian component specialists, creating vulnerability to supply disruption.
- Electric range degradation under refrigeration load:Battery-electric trucks suffer payload-distance trade-offs when electric transport refrigeration units draw auxiliary power, limiting long-haul deployment.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO temperature integrity requirements for vaccine distribution are creating demand for validated refrigerated vehicles in a historically ambient logistics environment.
- Carbon border adjustment mechanism:EU importers of temperature-sensitive goods face embedded emissions accounting that rewards low-refrigerant-intensity transport modes.
- Telematics and predictive maintenance convergence:Real-time cargo temperature monitoring fused with refrigeration unit diagnostics enables outcome-based service pricing.
Industry Challenges
- Thermal engineer scarcity:Fleet operators struggle to recruit technicians qualified in both electric powertrain and cryogenic refrigeration system maintenance.
- Multi-temperature zone certification complexity:Pharmaceutical clients require redundant cooling circuit validation that extends equipment commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Truck Market |
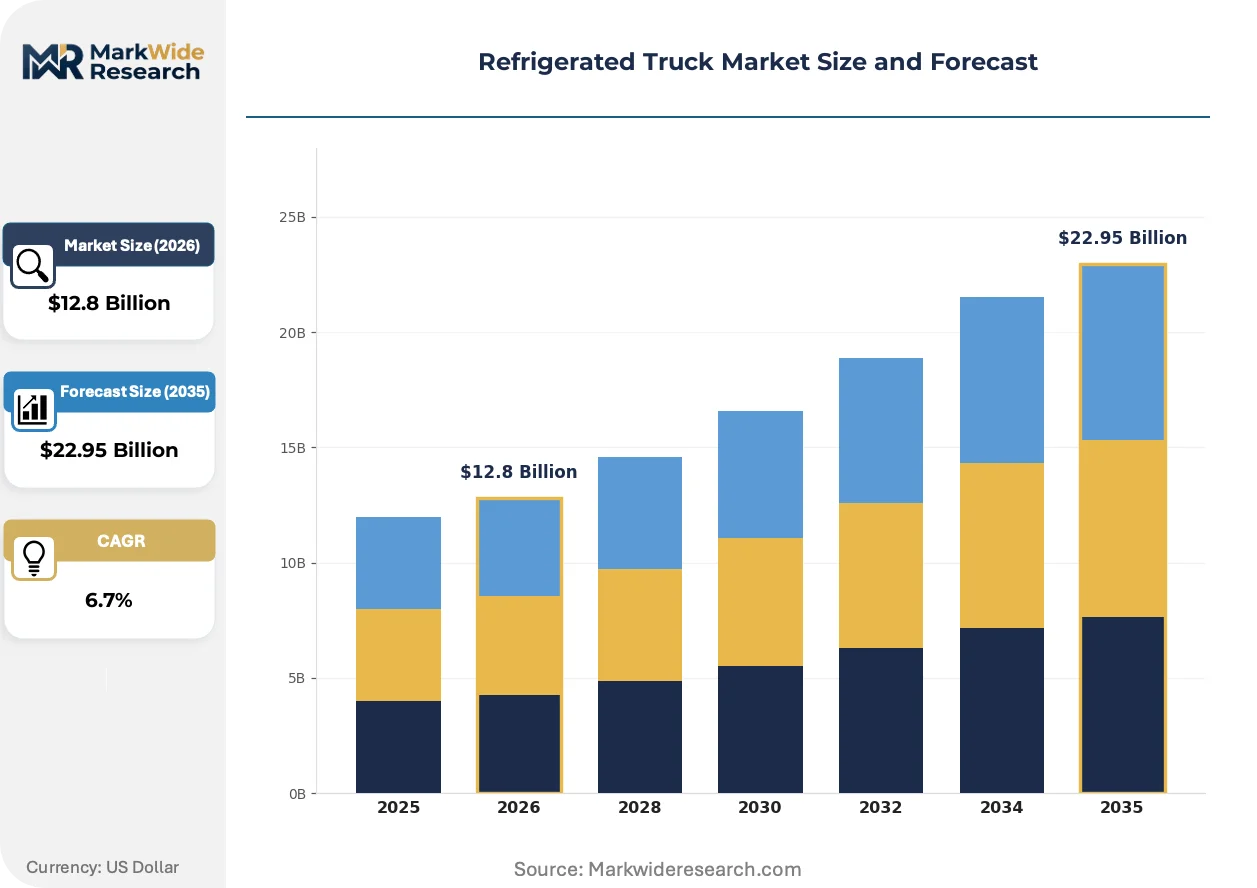
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Van, Trailer, Chassis, Box Truck Application: Food & Beverage, Pharmaceuticals, Flora, Chemicals End User: Food Distributors, Grocery Stores, Pharmacies, Logistics Providers Technology: Thermo King, Carrier Transicold, Daikin, Others |
| Companies Covered | Schmitz Cargobull, Utility Trailer Manufacturing Company, Thermo King, Kögel Trailer, Hyundai Translead, Carrier Transicold, Great Dane, Fahrzeugwerk Bernard Krone, Wabash National, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Truck Market Strategic Shifts
Transport refrigeration is pivoting from mechanical vapor-compression dominance toward hybrid-electric and cryogenic architectures, with fleet procurement criteria now weighting total cost of ownership over upfront capital expenditure.
CO2 transcritical refrigeration systems are supplanting traditional hydrofluorocarbon-based units in European trailer specifications. German food retailers are mandating CO2 systems in new procurement contracts to preempt F-Gas compliance exposure. This technology is supplanting conventional reciprocating compressor architectures across long-haul refrigerated trailer fleets, compressing service network requirements and technician training curricula.
The EU F-Gas Regulation mandates an eighty percent hydrofluorocarbon phase-down by 2030 against 2015 baseline levels. Original equipment manufacturers are redesigning unit architectures around natural refrigerants and electric compressors to maintain market access. German and French fleet operators are accelerating replacement cycles to avoid stranded asset risk from refrigerant servicing bans.
Third-party logistics providers are unbundling refrigerated transport from integrated cold chain contracts. Pharmaceutical shippers are contracting directly with specialized temperature-controlled carriers, bypassing general freight intermediaries. This channel disintermediation is most visible in Netherlands and Belgium hub corridors where dedicated pharma logistics clusters concentrate validated fleet capacity.
Refrigerated Truck Market Segmentation
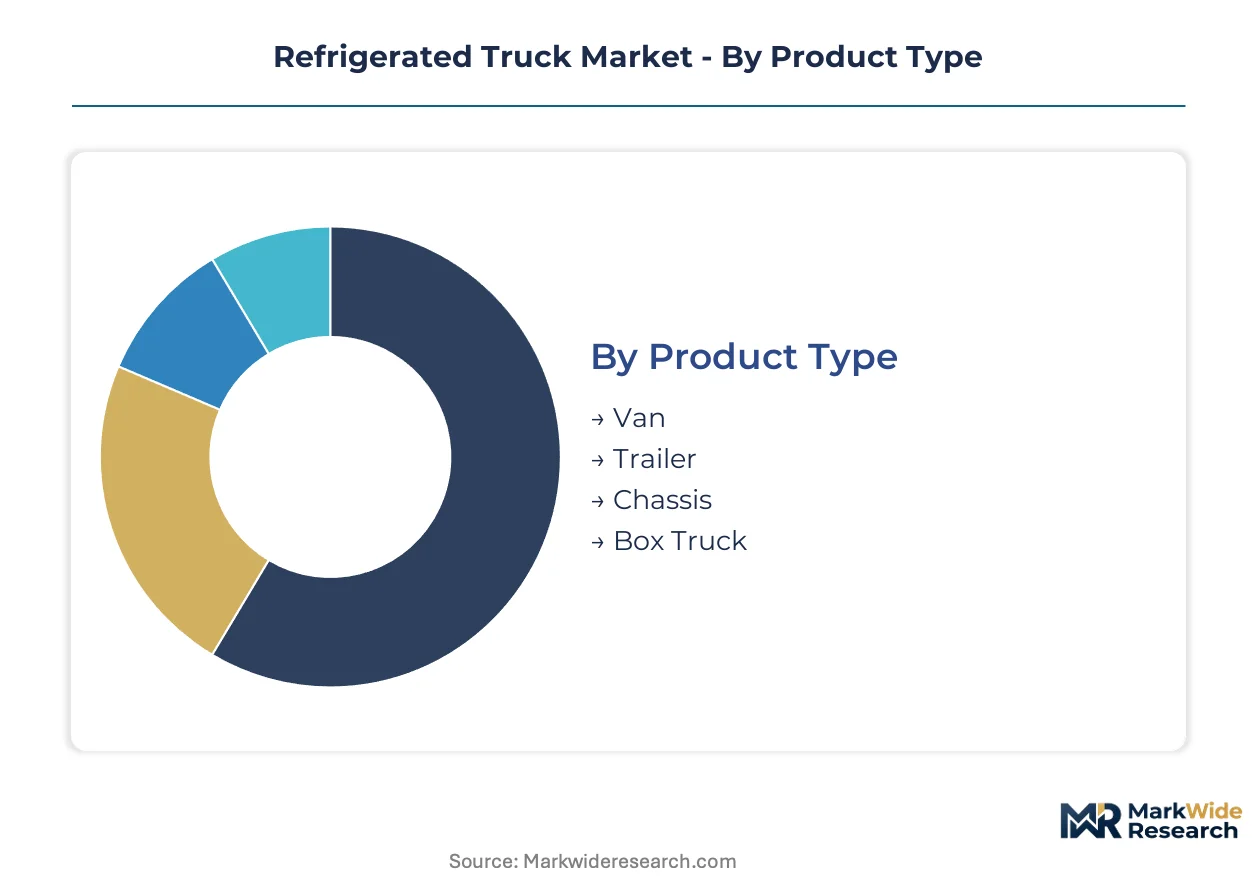
Refrigerated truck segmentation reflects divergent thermal performance requirements across distance bands and cargo sensitivity tiers. Fleet procurement strategies vary sharply between urban last-mile operators and long-haul pharmaceutical distributors.
Product Type:
Domestic fleet procurement concentrates on van and chassis configurations for dense urban corridors, while trailer demand tracks cross-border food export volumes from processing hubs.
- Van:Compact insulated bodies mounted on light commercial chassis with direct-drive refrigeration units rated for minus twenty degrees Celsius. German grocery chains and Dutch e-grocery platforms are expanding van fleets for metropolitan same-day delivery where trailer maneuverability is restricted.
- Trailer:Semi-trailer configurations with polyurethane foam insulation exceeding forty-five kilograms per cubic meter and multi-temperature zone partitioning. French and Spanish food exporters drive trailer procurement for cross-continental produce distribution under EU sanitary transport regulations.
- Chassis:Dedicated refrigerated chassis with integrated cooling circuits for pharmaceutical validation requirements.
- Box Truck:Rigid body trucks combining cargo box and chassis in single-unit configurations for mid-haul distribution.
Trailer holds the largest share; momentum sits with van configurations expanding most quickly.
Application:
Cost tier stratification separates commodity food transport from validated pharmaceutical cold chains requiring redundant temperature monitoring.
- Food & Beverage:Standard thermal maintenance between zero and four degrees Celsius for fresh produce, dairy, and protein distribution. German discount retailers and French hypermarket chains dominate fleet procurement with high-volume, low-margin contract structures.
- Pharmaceuticals:Validated cold chains demanding temperature mapping, redundant cooling circuits, and continuous data logging for regulatory compliance. Belgian and Dutch logistics corridors concentrate demand as cell and gene therapy distribution tightens tolerance bands below minus seventy degrees Celsius.
- Flora:Controlled atmosphere transport for ornamental plants and nursery stock requiring humidity management alongside temperature control.
- Chemicals:Hazardous material transport with explosion-proof refrigeration specifications for temperature-sensitive industrial compounds.
Food and beverage commands volume leadership; pharmaceuticals climbs the fastest on biologics distribution expansion.
End User:
Customer type fragmentation splits between integrated retail operators owning captive fleets and third-party logistics providers serving contract pharmaceutical distribution.
- Food Distributors:National and regional operators managing temperature-controlled networks from processing plants to retail backrooms.
- Grocery Stores:Omnichannel retailers operating hybrid fleets for warehouse replenishment and direct-to-consumer delivery.
- Pharmacies:Chain and independent dispensaries requiring validated last-mile transport for vaccines and biologics.
- Logistics Providers:Specialized temperature-controlled carriers with pharmaceutical certification and GDP compliance infrastructure.
Food distributors retain the largest fleet ownership; logistics providers gain share fastest on pharmaceutical outsourcing trends.
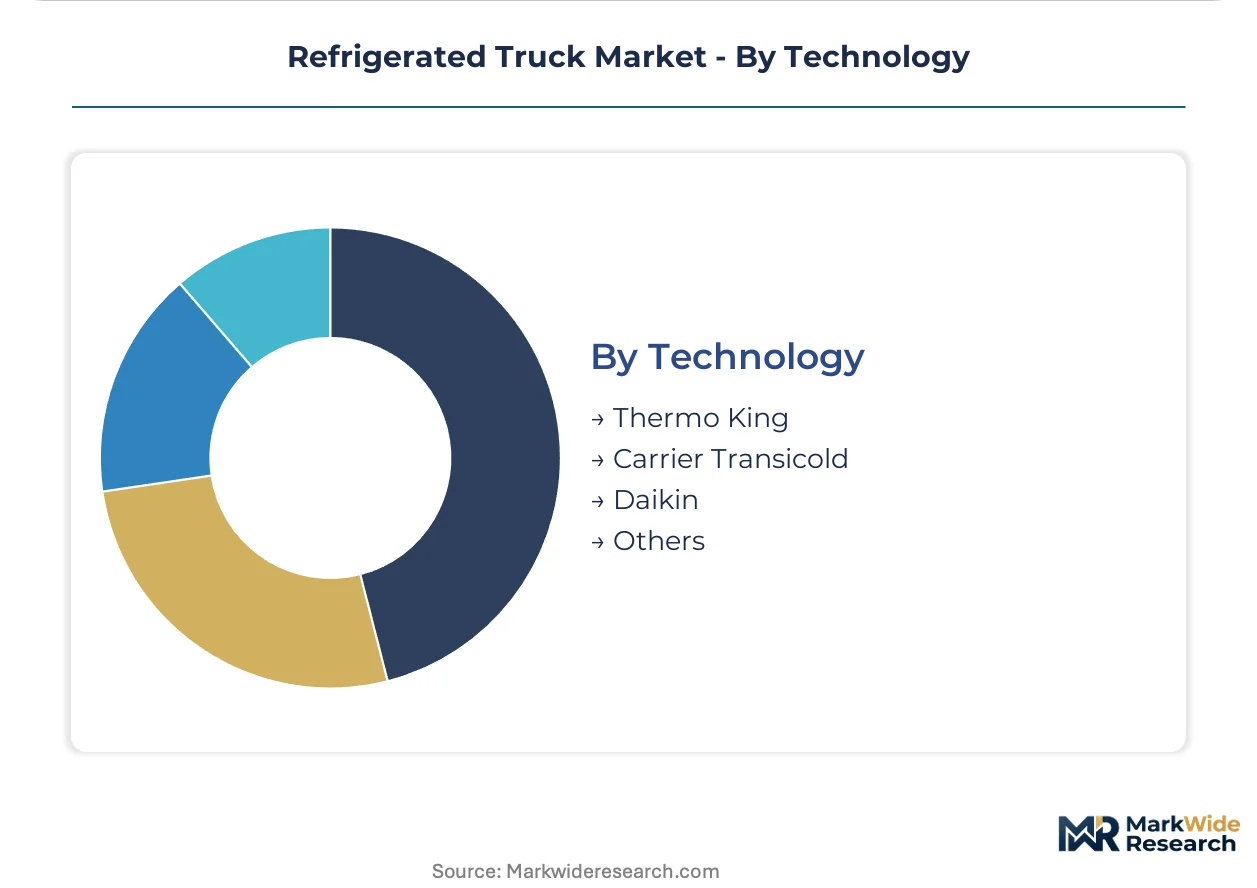
Technology:
Supply concentration among transport refrigeration unit manufacturers shapes equipment standardization and service network density.
- Thermo King:Integrated transport refrigeration ecosystem spanning electric and low-emission unit architectures with telematics-enabled predictive maintenance.
- Carrier Transicold:North American aftermarket service density and dealer network control anchoring fleet retrofit activity.
- Daikin:Natural refrigerant expertise and CO2 transcritical system development for European F-Gas compliance.
- Others:Regional specialists and emerging electric refrigeration unit developers.
Thermo King and Carrier Transicold hold combined technology leadership; Daikin gains traction on CO2 system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food distributors and pharmaceutical logistics providers concentrate procurement in Germany, the United States, and China, where cold chain infrastructure investment tracks perishable export volumes and biologics manufacturing expansion. Fleet operators in these markets face diverging regulatory timelines for refrigerant phase-downs and electrification mandates.
Germany
Discount grocery chains and pharmaceutical exporters drive refrigerated trailer demand through the Rhine-Ruhr and Bavarian food processing corridors. The EU F-Gas Regulation accelerates fleet replacement cycles as operators preempt hydrofluorocarbon servicing bans. CO2 transcritical systems dominate new procurement in the Stuttgart logistics cluster.
United States
Cross-border produce distribution and e-grocery fulfillment sustain chassis and van procurement across California's Central Valley and the Midwest meatpacking belt. The EPA's Clean Air Act Title II standards and California's Advanced Clean Trucks mandate push electrification timelines. Dallas-Fort Worth anchors aftermarket service density for transport refrigeration unit retrofits.
China
Fresh food e-commerce and vaccine distribution expansion multiply refrigerated van deployment in the Yangtze River Delta and Pearl River Delta. The country's dual carbon goals and NMPA temperature integrity requirements reshape equipment specifications. Shanghai's pharmaceutical logistics cluster concentrates demand for validated cold chain vehicles.
India
CDSCO enforcement of vaccine cold chain standards and organized retail expansion drive refrigerated truck adoption in Maharashtra and Gujarat. FSSAI food safety regulations tighten transport temperature monitoring requirements. The Mumbai-Pune pharmaceutical corridor sustains chassis-mounted system procurement for biologics distribution.
France
Hypermarket chains and agricultural exporters sustain trailer demand through the Île-de-France distribution hub and Rhône-Alpes food processing zone. EU F-Gas Regulation compliance pressures accelerate natural refrigerant adoption. Lyon and Lille logistics clusters concentrate multi-temperature zone fleet capacity for cross-border produce distribution.
Refrigerated Truck Market Competitive Environment
Player mix skews toward integrated transport refrigeration specialists and trailer manufacturers with captive cooling system partnerships. Market structure concentrates margin pools among three technology licensors and five chassis-body integrators serving distinct distance bands. Strategic archetypes separate electric refrigeration pioneers, CO2 system specialists, and aftermarket service network operators. Competitive moves center on refrigerant transition timing partnerships and telematics-enabled predictive maintenance bundling.
Among European trailer fabricators, Schmitz Cargobull and Kögel Trailer occupy positions within the lightweight chassis engineering tier, while Thermo King anchors the integrated transport refrigeration ecosystem. These entities exemplify divergent approaches to F-Gas compliance—trailer manufacturers emphasizing modular body configurations compatible with multiple cooling architectures, and refrigeration unit developers prioritizing electric and low-emission system roadmaps. Carrier Transicold represents the aftermarket service density archetype, with North American dealer network control supporting fleet retrofit activity.
| Leading Market Players |
|---|
| Schmitz Cargobull |
| Utility Trailer Manufacturing Company |
| Thermo King |
| Kögel Trailer |
| Hyundai Translead |
| Carrier Transicold |
| Great Dane |
| Fahrzeugwerk Bernard Krone |
| Wabash National |
| Others |
Value Chain & Pricing Dynamics
Chassis-mounted refrigeration unit production concentrates manufacturing scale among German and Italian compressor specialists, compressing margin pools at the component tier while elevating price floors for validated pharmaceutical configurations. Fleet operators face asymmetric bargaining power against this concentrated supplier base, particularly where EU F-Gas Regulation compliance timelines accelerate replacement demand.
Pricing Analysis
Cost-plus contracts with copper and aluminum indexation dominate original equipment manufacturer agreements with fleet operators. Three-tier pricing structure across premium pharmaceutical validation, standard food-grade compliance, and economy retrofit tiers separates margin capture by certification intensity. Pricing pressure stems from commodity input volatility and electric refrigeration unit development costs. Food distributors exhibit highest price sensitivity due to thin margin contract structures, while pharmaceutical logistics providers accept premium positioning for GDP-compliant redundancy.
Supply Chain Analysis
Inventory cycles for transport refrigeration units stretch sixteen to twenty-four weeks as compressor manufacturers balance capacity across industrial cooling and mobile applications. Manufacturing concentrates in Germany, Italy, and the United States, with polyurethane foam insulation sourcing from Belgian and Dutch chemical processors. Supply chain risk centers on single-source dependency for cryogenic cooling components. Distribution runs through captive dealer networks controlled by Thermo King and Carrier Transicold, limiting third-party service penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
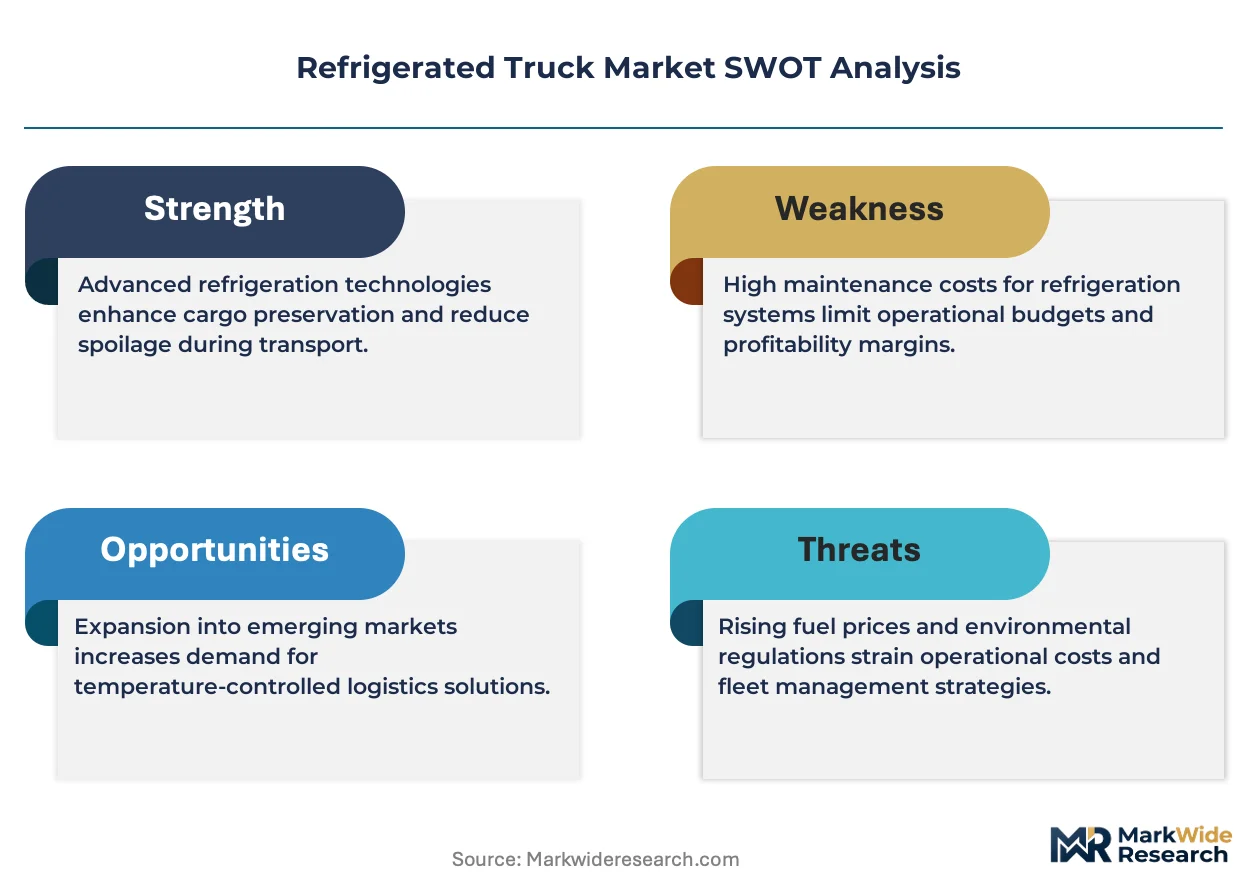
Refrigerated truck procurement is accelerating through a technology inflection as electric transport refrigeration units displace vapor-compression dominance under zero-emission fleet mandates. The EU F-Gas Regulation and California Advanced Clean Trucks mandate compress transition timelines, rewarding early capital deployment into alternative cooling architectures.
For Market Incumbents: Secure refrigerant transition partnerships with natural refrigerant specialists before hydrofluorocarbon servicing bans strand installed base assets. Deepen backward integration into electric compressor manufacturing to capture margin pools migrating from mechanical systems. Lock in multi-year service contracts with pharmaceutical logistics providers to defend against third-party logistics disintermediation.
For New Entrants and Emerging Players: Lead with CO2 transcritical system specialization targeting German and French fleet operators facing F-Gas compliance deadlines. Target Indian pharmaceutical corridors where CDSCO enforcement creates validated cold chain demand in historically ambient logistics environments. Pursue telematics-enabled predictive maintenance bundling to differentiate against incumbent hardware-centric positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electric refrigeration unit developers with established OEM integration pathways and natural refrigerant intellectual property portfolios. Long-term viability hinges on service network density and technician training infrastructure rather than manufacturing scale alone. Monitor California Advanced Clean Trucks mandate enforcement as inflection signal for electric refrigeration unit adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Transition Partnership | Secures market access under EU F-Gas Regulation phase-down timelines for German and French fleets. |
| Electric Compressor Manufacturing Scale-Up | Captures margin migration from mechanical systems as California zero-emission mandates tighten. |
| Pharmaceutical Validation Certification Investment | Enables GDP-compliant service contracts with Belgian and Dutch biologics distributors. |
| Predictive Maintenance Platform Integration | Fuses telematics data with refrigeration diagnostics for outcome-based pricing with logistics providers. |
| India Market Entry Through CDSCO Compliance | Addresses vaccine cold chain gaps in Maharashtra and Gujarat pharmaceutical corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU F-Gas implementation reports, and fleet operator procurement disclosures. Primary interviews covered transport refrigeration unit engineering directors, pharmaceutical logistics procurement managers, cold chain fleet maintenance heads, and aftermarket service network operators. Secondary validation drew from NHTSA fuel economy standards documentation, CDSCO vaccine distribution guidelines, and customs trade data for refrigerated vehicle imports. Bottom-up unit shipment analysis triangulates against top-down fleet replacement cycle modeling.
Segmentation dimensions modeled span product type, application sensitivity tier, end-user ownership structure, cooling technology architecture, and regional regulatory cluster across the projection horizon. CAGRs derive from replacement cycle acceleration under refrigerant phase-down mandates and electrification quotas. Forecast inputs incorporate copper and aluminum price trajectory assumptions and electric vehicle range degradation coefficients under auxiliary refrigeration load.
Underlying assumptions cover F-Gas Regulation enforcement consistency and battery energy density improvement curves, with deviation risk concentrated in electric range performance under multi-temperature zone operation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Tank Car Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Compact Utility Vehicles Market