
 Refrigerated Trailer Market | 2026-2036
Refrigerated Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Trailer Market Outlook
Pharmaceutical shippers are unwinding the historical dominance of food logistics in refrigerated trailer procurement. Wabash National Corporation leverages its composite panel technology to sustain pricing power in lightweight insulated trailer configurations. Schmitz Cargobull AG anchors European production with vertically integrated axle and refrigeration unit assembly. Great Dane Trailers competes through regional manufacturing density across the southeastern United States.
A refrigerated trailer is a thermally insulated semi-trailer equipped with integrated mechanical refrigeration or cryogenic cooling systems, typically maintaining cargo temperatures between minus 25 degrees Celsius and plus 25 degrees Celsius depending on payload requirements. These trailers employ polyurethane foam-in-place insulation bonded to fiberglass-reinforced polymer or aluminum skins to minimize thermal bridging and vapor infiltration during over-the-road transport. Multi-temp trailers now command the fastest growth trajectory as fleets consolidate pharmaceutical and fresh-produce loads within partitioned compartments on single routes. Thermal insulation technology leads in replacement demand as older foam formulations face phaseout under evolving chemical safety standards. IoT monitoring systems are capturing margin pools through recurring telematics subscriptions rather than hardware sales alone.
The EPA Phase 2 standards and the EU F-Gas Regulation are jointly tightening permissible refrigerant global warming potential and trailer thermal transmittance coefficients, forcing OEMs to redesign insulation cores and transition to hydrofluoroolefin-based cooling circuits. NHTSA overlap rules on trailer aerodynamics further shape product development priorities for domestic manufacturers. FDA food safety modernization requirements and EU Good Distribution Practice mandates for pharmaceuticals impose validated temperature documentation, expanding the addressable market for integrated data-logging hardware. Fleet operators must now decide whether to spec trailers for regulatory compliance minimums or to front-run anticipated Phase 3 stringency with advanced composite designs.
Market Dynamics
Pharmaceutical cold chain compliance mandates are compressing replacement cycles and forcing thermal performance upgrades ahead of regulatory deadlines. Fleet operators now face capital allocation decisions between incremental insulation improvements and full platform redesigns.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluoroolefin refrigerant adoption is accelerating trailer refrigeration unit retrofits across European pharmaceutical distribution networks.
- Multi-temp compartment demand:Fresh produce consolidators are specifying partitioned trailers to optimize lane density on mixed pharmaceutical-food routes.
- IoT telematics penetration:Recurring subscription revenue from temperature monitoring hardware is expanding OEM service margins beyond equipment sales.
Market Restraints
- Polyurethane feedstock volatility:Isocyanate and polyol price swings compress insulation panel margins during contract manufacturing cycles.
- Axle and refrigeration unit supply concentration:Dependence on German and Danish component suppliers creates vulnerability to regional production disruptions.
- Electrification infrastructure gaps:Grid-connected trailer standby power remains unavailable at most US distribution centers, limiting electric refrigeration adoption.
Strategic Opportunities
- India cold chain modernization:FSSAI enforcement of temperature-controlled food transport is opening trailer specification opportunities in a historically underpenetrated market.
- Last-mile pharmaceutical consolidation:Urban pharmacy delivery networks are creating demand for smaller refrigerated trailers below standard 53-foot configurations.
- EU Green Deal fleet decarbonization subsidies:Member state incentive programs for low-emission transport equipment are front-loading replacement demand in Germany and the Netherlands.
Industry Challenges
- Thermal engineer talent scarcity:Expertise in vapor barrier design and foam-in-place chemistry is concentrating among retiring specialists at established OEMs.
- Dual certification complexity:Simultaneous FDA food safety and EU GDP pharmaceutical validation extends trailer commissioning timelines.
- Legacy fleet integration friction:New telematics platforms require retrofit compatibility with 15-year-old refrigeration control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Trailer Market |
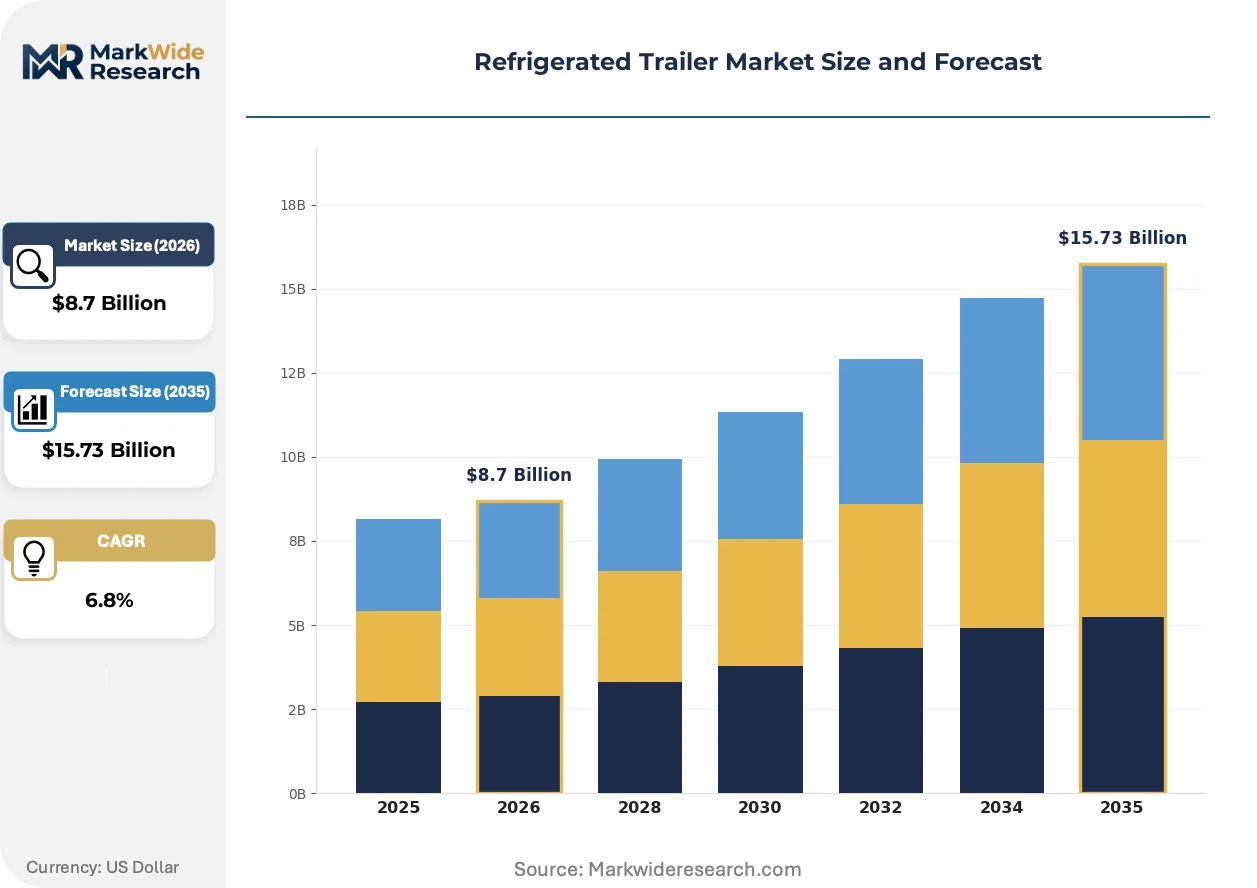
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Temp Trailers, Multi-Temp Trailers, Temperature-Controlled Vans, Refrigerated Containers Application: Food Transportation, Pharmaceutical Delivery, Floral Transport, Chemical Distribution End User: Logistics Companies, Retailers, Food Producers, Pharma Companies Technology: Thermal Insulation, Refrigeration Units, IoT Monitoring, Energy-Efficient Systems |
| Companies Covered | Wabash National Corporation, Schmitz Cargobull AG, Great Dane Trailers, Utility Trailer Manufacturing Company, CIMC Vehicles, Hyundai Translead, Fahrzeugwerk Bernard Krone GmbH, Kögel Trailer GmbH & Co. KG, Lamberet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Trailer Market Strategic Shifts
Refrigerated trailer engineering is bifurcating between lightweight composite platforms for long-haul efficiency and ruggedized configurations for urban pharmaceutical distribution. Material science advances and connectivity integration are reshaping competitive differentiation.
Vacuum insulation panel technology is fragmenting traditional foam-dominated thermal barrier specifications. Pharmaceutical fleets in Germany and Switzerland are specifying VIP cores for ultra-low-temperature lanes below minus 40 degrees Celsius. This material shift is fragmenting supplier relationships as composite panel specialists capture share from conventional trailer assemblers.
The EPA Phase 2 greenhouse gas standards are mandating reduced thermal transmittance coefficients for trailers operating in interstate commerce. Domestic manufacturers are redesigning door seal geometries and increasing insulation thickness to meet the 2027 compliance window. Food logistics operators with dense private fleets are absorbing the engineering costs faster than fragmented owner-operator segments.
Leasing structures are displacing outright purchase for pharmaceutical shippers seeking operational flexibility. Temperature-validated trailer pools managed by specialized lessors are capturing share from fleet-owned assets in the US Northeast corridor. This capital-light preference is most pronounced among mid-sized specialty pharmaceutical distributors expanding into cell and gene therapy logistics.
Refrigerated Trailer Market Segmentation
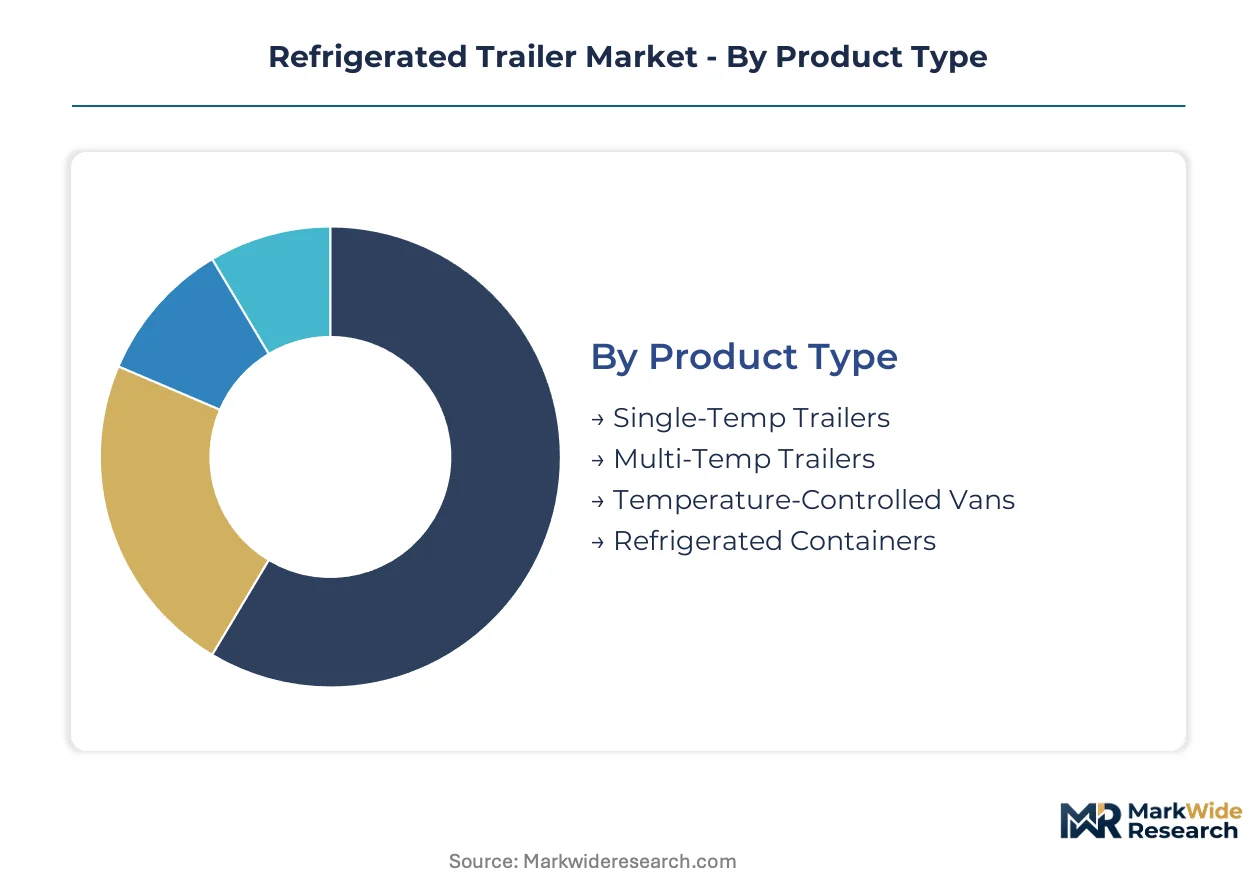
Segmentation in refrigerated trailers determines capital allocation priorities for fleet operators balancing regulatory compliance against payload flexibility. Product configuration choices lock in thermal performance ceilings and route economics for the full asset lifecycle. Understanding where substitution pressure concentrates helps OEMs defend specification positions against emerging alternatives.
Product Type:
Single-temp trailers face the strongest substitution pressure as multi-temp configurations capture consolidated pharmaceutical-food routes and eliminate deadhead miles.
- Single-Temp Trailers:These units maintain uniform temperature throughout the cargo bay using continuous foam-in-place polyurethane insulation bonded to aluminum or fiberglass-reinforced skins. Food logistics operators in Germany and the southeastern United States continue specifying single-temp platforms for dedicated produce lanes, though procurement volumes are flattening as lane consolidation accelerates.
- Multi-Temp Trailers:Partitioned compartments with independent refrigeration circuits enable simultaneous transport of frozen, chilled, and ambient pharmaceuticals alongside fresh produce. Swiss and German pharmaceutical distributors are driving specification demand for triple-compartment configurations serving mixed cold chain routes.
- Temperature-Controlled Vans:Smaller urban delivery vehicles below standard semi-trailer dimensions serve last-mile pharmacy networks and metropolitan food distribution.
- Refrigerated Containers:Intermodal units designed for rail and maritime transfer operate in pharmaceutical export corridors from the Netherlands and Belgium.
Single-temp trailers anchor the volume base while multi-temp configurations gain share at the steepest rate.
Application:
Application segmentation tracks where regulatory stringency is compressing replacement cycles and forcing thermal performance upgrades ahead of compliance deadlines.
- Food Transportation:Traditional fresh and frozen cargo moving through retail grocery and foodservice distribution networks. EPA Phase 2 thermal transmittance requirements are accelerating insulation retrofits among US private fleets with dense route structures.
- Pharmaceutical Delivery:Temperature-validated transport for vaccines, biologics, and cell therapies requiring continuous documentation. EU GDP mandates and FDA food safety modernization requirements are expanding specification demand for integrated data-logging hardware across German and Swiss distribution networks.
- Floral Transport:Humidity-controlled lanes for perishable horticultural products with narrow temperature bands.
- Chemical Distribution:Hazardous and temperature-sensitive industrial materials requiring specialized vapor barrier specifications.
Food transportation retains the largest installed base while pharmaceutical delivery commands the highest specification premiums.
End User:
End user segmentation reveals where capital deployment patterns are shifting between fleet ownership and third-party logistics outsourcing.
- Logistics Companies:Third-party cold chain operators managing asset-light networks for pharmaceutical and food shippers. Specialized lessors in the US Northeast corridor are capturing share from fleet-owned assets through temperature-validated trailer pools.
- Retailers:Grocery and pharmacy chains with private fleet operations. German supermarket chains are front-loading replacement demand through EU Green Deal decarbonization subsidies for low-emission transport equipment.
- Food Producers:Agricultural processors and packaged goods manufacturers with dedicated outbound logistics.
- Pharma Companies:Specialty pharmaceutical distributors expanding into cell and gene therapy logistics with validated cold chain requirements.
Logistics companies are expanding fleet share fastest while retailers defend the largest specification volume.
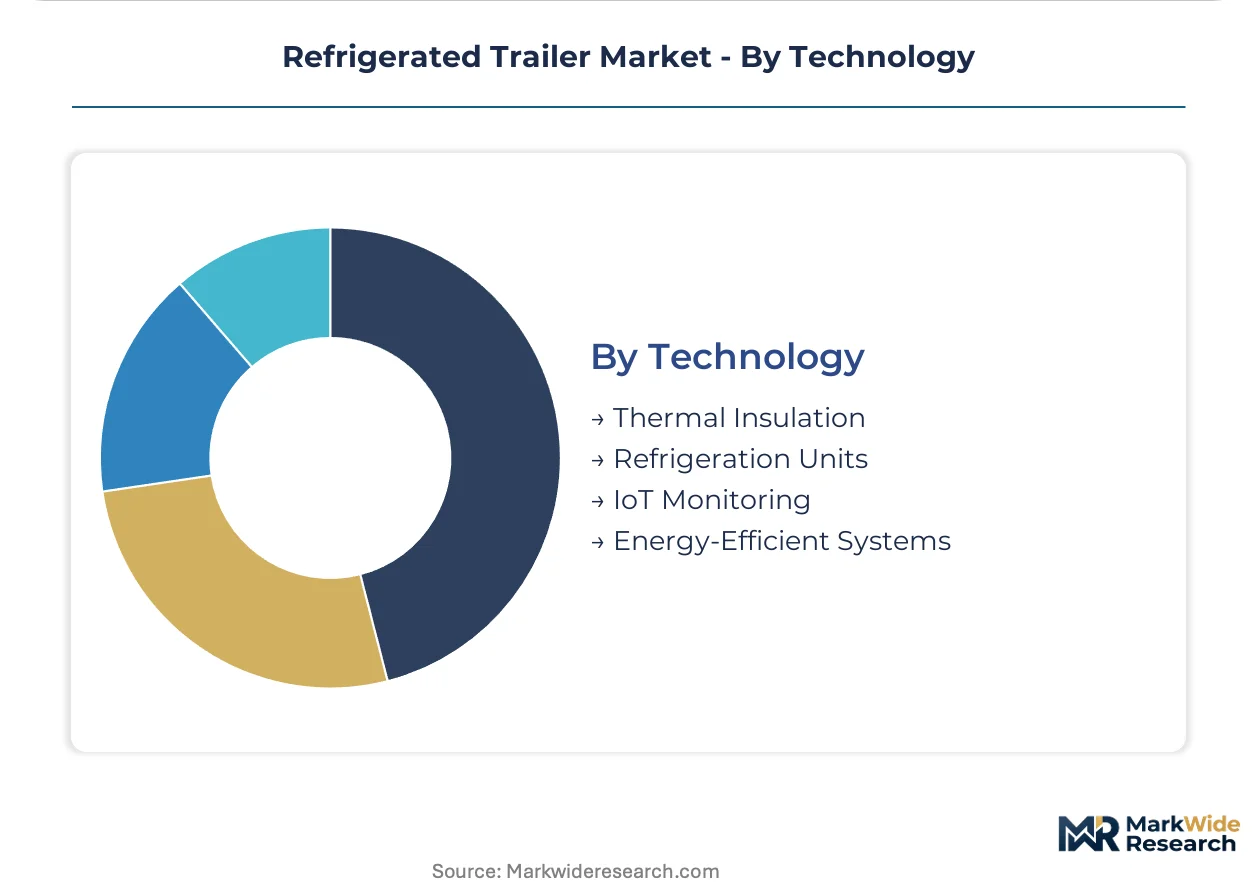
Technology:
Technology segmentation captures where component innovation is fragmenting traditional supplier relationships and shifting margin pools from hardware to recurring services.
- Thermal Insulation:Core barrier materials including polyurethane foam, vacuum insulation panels, and advanced composite formulations. VIP technology is fragmenting supplier relationships as composite panel specialists capture share from conventional trailer assemblers in German ultra-low-temperature lanes.
- Refrigeration Units:Mechanical compressor and cryogenic cooling systems. EU F-Gas Regulation phase-down is accelerating hydrofluoroolefin retrofits across European pharmaceutical distribution networks.
- IoT Monitoring:Connected temperature and location tracking hardware with telematics platforms. OEMs are capturing expanded service margins through recurring subscription revenue rather than equipment sales alone.
- Energy-Efficient Systems:Electric and hybrid refrigeration architectures with reduced carbon intensity.
Thermal insulation technology anchors replacement demand while IoT monitoring expands margin pools fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports refrigerated trailers across the Rhine-Alpine corridor into Switzerland and the Netherlands, anchoring European cold chain equipment flows. Pharmaceutical distribution networks in Basel and Rotterdam drive specification demand for multi-compartment units. Regulatory pressure from Brussels and Washington is fragmenting thermal performance standards across trade lanes.
United States
Food logistics operators in the Southeast are absorbing EPA Phase 2 thermal transmittance compliance costs faster than fragmented owner-operator segments. NHTSA aerodynamic overlap rules are reshaping door seal geometries and trailer skirt specifications. Dallas-Fort Worth anchors a dense cluster of fleet maintenance facilities retrofitting insulation cores ahead of the 2027 deadline.
Germany
Pan-European pharmaceutical routes are compressing replacement cycles as EU GDP mandates tighten temperature documentation requirements. The EU F-Gas Regulation is accelerating hydrofluoroolefin retrofits across distribution networks serving Swiss and Dutch borders. North Rhine-Westphalia hosts vertically integrated axle and refrigeration assembly operations that supply cold chain operators from Hamburg to Milan.
China
Domestic fresh produce consolidation is driving multi-temp trailer adoption along the Beijing-Shanghai corridor. GB standards for refrigerated transport are tightening foam-in-place chemical specifications under evolving environmental regulations. Qingdao anchors export-oriented manufacturing clusters supplying Southeast Asian cold chain infrastructure projects.
India
FSSAI enforcement of temperature-controlled food transport is opening specification opportunities in historically underpenetrated dairy and pharmaceutical lanes. The PLI scheme for logistics infrastructure is front-loading cold storage and trailer procurement in western and southern states. Maharashtra's Mumbai-Pune industrial belt is emerging as a fabrication hub for domestic pharmaceutical distribution equipment.
Switzerland
Ultra-low-temperature pharmaceutical lanes below minus 40 degrees Celsius are driving vacuum insulation panel adoption among Basel-based cell therapy distributors. Swissmedic validation requirements for gene therapy logistics are extending trailer commissioning timelines and documentation protocols. The Zurich-Basel corridor concentrates specialized lessors managing temperature-validated asset pools for European biotech exports.
Refrigerated Trailer Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base clusters around three strategic archetypes: vertically integrated European chassis manufacturers, North American composite panel specialists, and Asian scale fabricators serving export markets. Consolidation pressure concentrates among mid-tier assemblers lacking captive refrigeration unit supply. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs secure component supply amid feedstock volatility.
Within the integrated European tier, Schmitz Cargobull AG and Fahrzeugwerk Bernard Krone GmbH exemplify chassis-refrigeration coupling strategies. Wabash National Corporation occupies a position among North American composite specialists leveraging lightweight insulation configurations. CIMC Vehicles anchors the scale-driven export segment serving infrastructure buildouts across emerging cold chain markets.
| Leading Market Players |
|---|
| Wabash National Corporation |
| Schmitz Cargobull AG |
| Great Dane Trailers |
| Utility Trailer Manufacturing Company |
| CIMC Vehicles |
| Hyundai Translead |
| Fahrzeugwerk Bernard Krone GmbH |
| Kögel Trailer GmbH & Co. KG |
| Lamberet |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance certification gates both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb hydrofluoroolefin retrofit costs while pharmaceutical fleets pay premiums for validated thermal performance documentation.
Pricing Analysis
Next-generation vacuum insulation panel configurations command 40-60% premiums over conventional polyurethane foam platforms, while prior-generation trailers face accelerated depreciation under tightening EPA Phase 2 thermal transmittance coefficients. Three-tier pricing structure across premium VIP-specified, standard multi-temp, and economy single-temp levels stratifies by certification grade and after-sales telemetry bundling. Cost compression in economy single-temp tiers is intensifying because food logistics operators consolidate procurement volumes. Owner-operators exhibit highest price sensitivity, while Swiss pharmaceutical distributors demonstrate lowest sensitivity due to GDP-mandated validation requirements.
Supply Chain Analysis
Isocyanate feedstock transit through Rotterdam-Antwerp chemical corridors underwrites insulation panel cost stability for European OEMs. Component supply draws from Germany, Denmark, and China, with axle and refrigeration unit assembly concentrated in North Rhine-Westphalia and Copenhagen industrial zones. Raw material dependencies rest on polyol formulations, aluminum sheet, and fiberglass-reinforced polymer skins. Single-source vulnerability concentrates in German refrigeration unit suppliers serving pan-European pharmaceutical networks. Distribution runs through captive OEM service networks and specialized lessor fleet pools in the US Northeast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT telematics subscription layers are expanding faster than trailer hardware sales, transforming OEM economics toward recurring revenue models with 3-5 year service attach rates.
For Market Incumbents: Compound defensive positioning through backward integration into refrigeration unit assembly and captive axle production, countering emerging Asian scale fabricators entering European pharmaceutical specification tiers. Prioritize certification investment in EU GDP and FDA dual-validation capabilities to lock out mid-tier assemblers lacking documentation infrastructure. Capacity addition in Poland and Czech Republic manufacturing clusters captures EU Green Deal subsidy flows while insulating margin structures from German labor cost inflation.
For New Entrants and Emerging Players: Telematics platform interoperability gaps where incumbents under-serve legacy fleet retrofit requirements present immediate white-space opportunity. Target Indian pharmaceutical distribution networks in Maharashtra and Gujarat where FSSAI enforcement is accelerating specification demand without entrenched supplier relationships. Pursue joint-venture manufacturing with domestic fabricators to bypass capital-intensive greenfield assembly investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across composite panel specialization as vacuum insulation technology commoditizes, favoring asset-light telematics platform acquisitions over heavy manufacturing footprints. Long-term viability across the analysis window favors suppliers with recurring service revenue anchoring 40% of total customer lifetime value. Acquisition target archetype: mid-scale lessors with validated temperature-controlled asset pools in the Zurich-Basel corridor. Signal to monitor: EU Phase 3 refrigerant GWP thresholds advancing ahead of announced timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | OEMs capture recurring subscription margins from pharmaceutical fleet temperature monitoring mandates. |
| Vacuum Insulation Panel Manufacturing Scale-Up | Composite specialists displace conventional assemblers in Swiss ultra-low-temperature lane specifications. |
| EU Green Deal Certification Program | German and Dutch fleets front-load replacement demand through member state low-emission equipment subsidies. |
| Joint Venture with Indian Fabricators | Foreign OEMs bypass capital barriers in Maharashtra's emerging pharmaceutical distribution equipment hub. |
| Long-term Supply Agreement for HFO Refrigerants | Refrigeration unit suppliers lock in feedstock security ahead of EU F-Gas phase-down acceleration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across fleet procurement directors, thermal engineering specialists, pharmaceutical logistics compliance officers, and refrigerated trailer OEM product managers. Secondary validation incorporated EPA regulatory filings, EU F-Gas implementation reports, NHTSA aerodynamic standard documentation, and customs trade data for polyurethane feedstock flows. Bottom-up fleet inventory modeling triangulated against top-down cold chain infrastructure investment tracking.
Across the analysis window, forecasts segment by product configuration, application vertical, end-user ownership model, and technology tier including insulation material generation and connectivity integration status. CAGRs derive from replacement cycle compression analysis under regulatory deadline clustering and pharmaceutical lane expansion trajectories. Modeled inputs incorporate EPA Phase 2 thermal transmittance compliance cost absorption rates and EU GDP documentation hardware attach rates.
Forecasts assume regulatory continuity in EPA Phase 2/3 standards and EU F-Gas phase-down schedules; material policy shifts would require re-modeling thermal performance upgrade timelines and refrigerant retrofit demand curves. Practitioners should keep alternative scenarios live as EU Green Deal subsidy allocation patterns and Indian PLI scheme disbursement velocities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market