
 Modular Trailer Market | 2026-2036
Modular Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Trailer Market Analysis
Dealer-direct and fleet-lease distribution channels for heavy-haul equipment is fragmenting as rental-service intermediaries capture share from traditional ownership models. Doepker Industries leverages its western Canadian manufacturing footprint to dominate prairie province energy corridors. XL Specialized Trailers sustains engineering leadership in multi-axle hydraulic configurations for overweight-permit cargo. Trail King Industries anchors its position through backward integration into frame fabrication, reducing lead times for custom deck specifications.
A modular trailer constitutes a transport platform built from standardized, interchangeable subassemblies—decks, axles, suspension modules, and coupling systems—permitting rapid reconfiguration between flatbed, lowboy, or drop deck geometries without complete vehicle replacement. Steel or aluminum frame construction typically supports gross combination weights exceeding standard highway limits, with hydraulic or mechanical gooseneck detachment enabling front-loading of immobile equipment. Flatbed configurations occupy the largest installed base due to versatility across construction and general freight applications, while lowboy variants command premium positioning for inertial loads exceeding legal height restrictions. Curtain side modules represent the fastest-growing product type as just-in-time manufacturing supply chains require weather-protected, side-accessible cargo handling without dedicated van assets.
The US Federal Motor Carrier Safety Administration governs commercial vehicle dimensions and weight through federal bridge formula standards, while state-level permitting authorities impose variable axle-spacing requirements that directly influence modular axle-line purchasing decisions. Transport Canada enforces National Safety Code standards harmonized with US regulations, enabling cross-border fleet standardization for operators serving integrated North American logistics networks. Stakeholders must monitor evolving emissions compliance timelines for heavy-duty tractor powertrains, as zero-emission mandates in California and forthcoming federal standards will reshape total cost-of-ownership calculations for fleet replacement cycles.
Market Dynamics
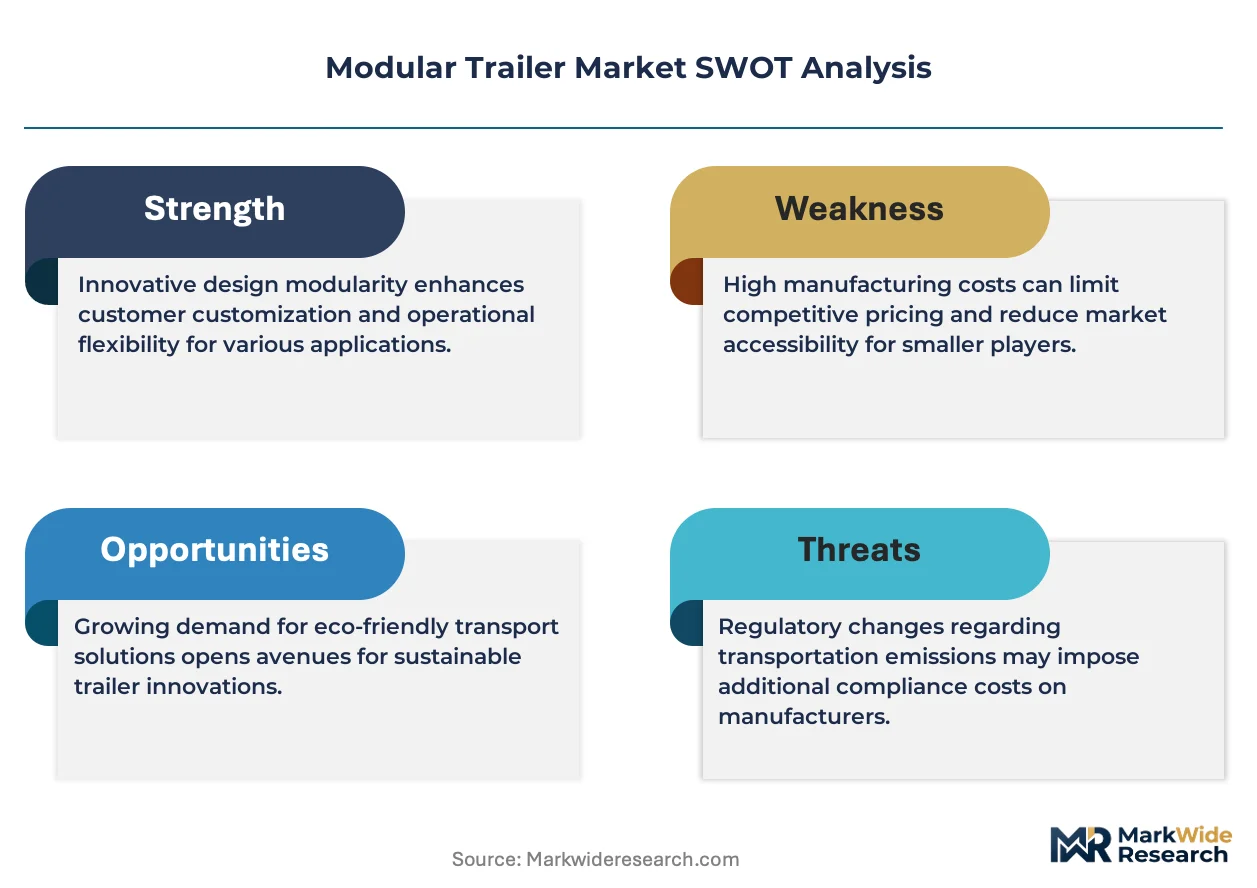
Bridge formula enforcement by the US Department of Transportation is compressing axle-spacing tolerances and forcing rapid redesign cycles across frame fabrication workflows. This regulatory compression cascades through specification chains, rewarding manufacturers with captive engineering capacity.
Growth Catalysts
- Zero-emission tractor mandates:California Air Resources Board timelines are accelerating fleet replacement cycles, creating pull-through demand for compatible platform configurations.
- Permian Basin infrastructure density:Oilfield services contractors in west Texas and southeast New Mexico require rapid deck reconfiguration between equipment and pipe hauls.
- REACH-aligned aluminum sourcing:European scrap-recovery standards are improving material traceability for lightweight frame construction.
Market Restraints
- High-grade steel volatility:Quenched-and-tempered plate prices swing with blast furnace capacity in the Ruhr industrial cluster.
- Hydraulic component concentration:Precision valve assemblies for multi-axle steering depend on a narrow supplier base in southern Germany.
- Bridge formula state variance:Permitting authorities in Texas, Louisiana, and Oklahoma impose incompatible axle-spacing calculations.
Strategic Opportunities
- Curtain side module penetration:Just-in-time manufacturing supply chains in automotive assembly corridors require weather-protected, side-accessible cargo handling.
- Cross-border fleet standardization:Transport Canada National Safety Code harmonization enables unified specifications for operators serving integrated US-Canada logistics networks.
- Telematics-embedded suspension:Real-time load monitoring converges with predictive maintenance platforms to create subscription revenue streams.
Industry Challenges
- Welding technician scarcity:Certified aluminum TIG specialists command premium wages in prairie province manufacturing zones.
- Homologation timeline compression:Updated Federal Motor Carrier Safety Administration brake testing protocols extend certification cycles for new axle configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Trailer Market |
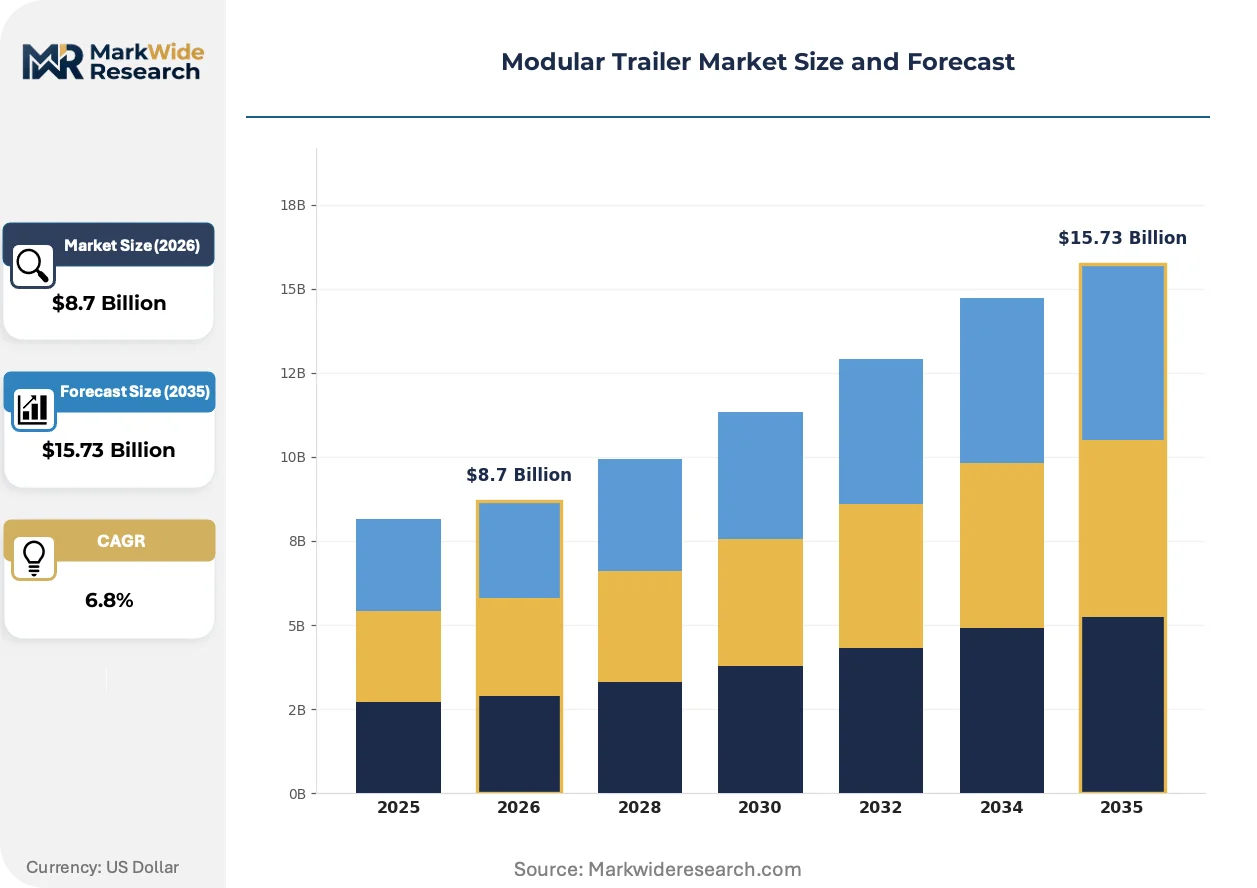
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Lowboy, Curtain Side, Drop Deck Application: Construction, Logistics, Agriculture, Military End User: Transport Companies, Construction Firms, Government Agencies, Rental Services Size: Standard, Compact, Heavy-Duty, Oversized |
| Companies Covered | Doepker Industries, Manac, XL Specialized Trailers, Stoughton Trailers, Hyundai Translead, Trail King Industries, Heil Trailer International, Felling Trailers, Fontaine Trailer Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Trailer Market Emerging Trajectories
Lightweighting imperatives and digital integration are reshaping how transport platforms are specified, financed, and deployed across heavy-haul corridors. These shifts compress traditional equipment lifecycles while opening new service revenue models.
Carbon-fiber-reinforced polymer decking is rendering obsolete traditional steel plate construction in weight-sensitive applications. Aerospace-grade prepreg manufacturing techniques are migrating into commercial trailer fabrication, with energy sector fleets in the Permian Basin adopting hybrid steel-composite platforms for repetitive overweight-permit operations. This material transition is compressing tare weight by fifteen to twenty percent, enabling additional payload capacity within existing bridge formula limits.
California Air Resources Board zero-emission mandates are restructuring total cost-of-ownership calculations for fleet replacement cycles. Heavy-haul operators must now synchronize platform specifications with electric and hydrogen tractor powertrain weight distributions, axle torque limits, and charging infrastructure placement. The state's South Coast Air Quality Management District is accelerating compliance timelines for drayage and regional haul segments.
Asset-light procurement models are displacing traditional dealer-direct ownership in construction and oilfield services verticals. Rental-service intermediaries capture share from fleet-lease channels by offering rapid reconfiguration services and bundled maintenance. This shift concentrates most visibly in the Permian Basin corridor, where project-based contracting demands variable capacity without fixed asset exposure.
Modular Trailer Market Segmentation
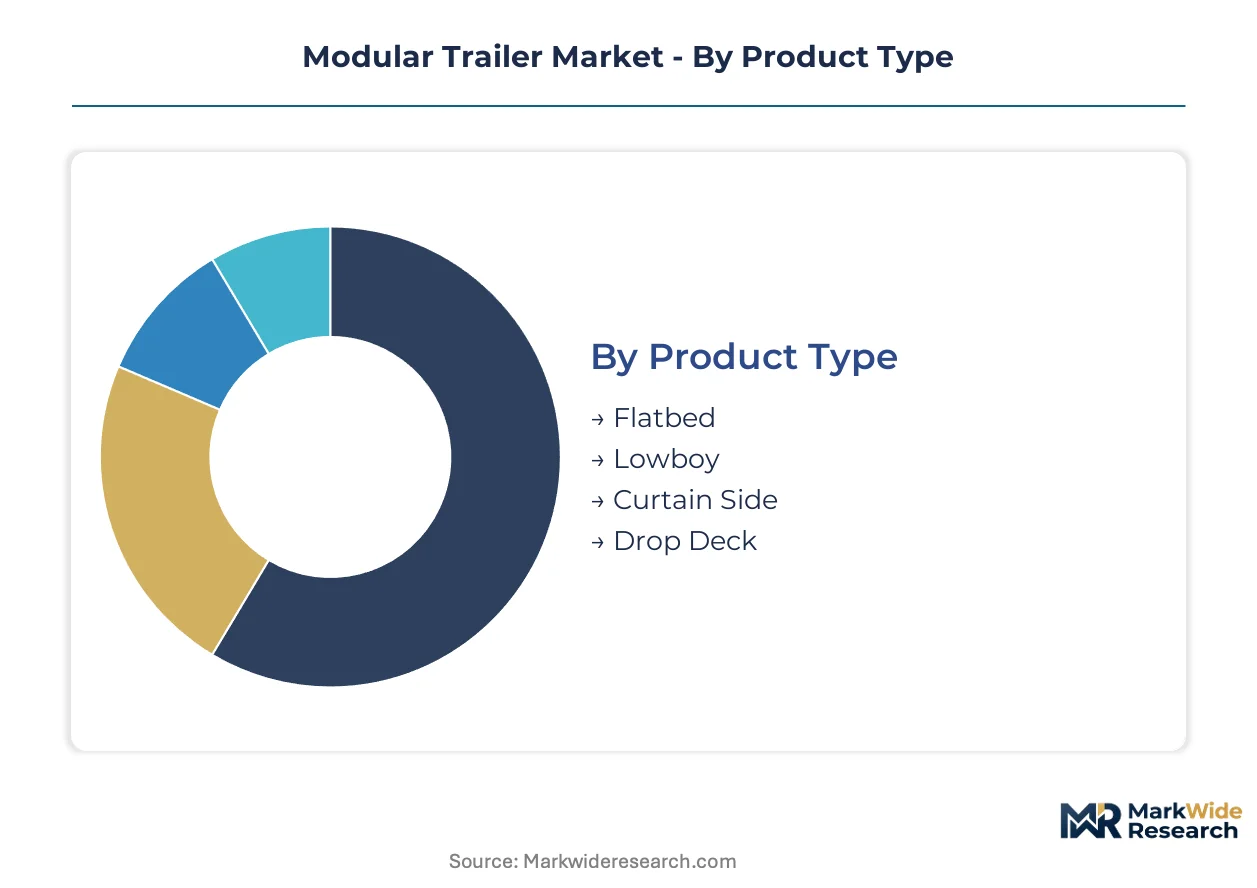
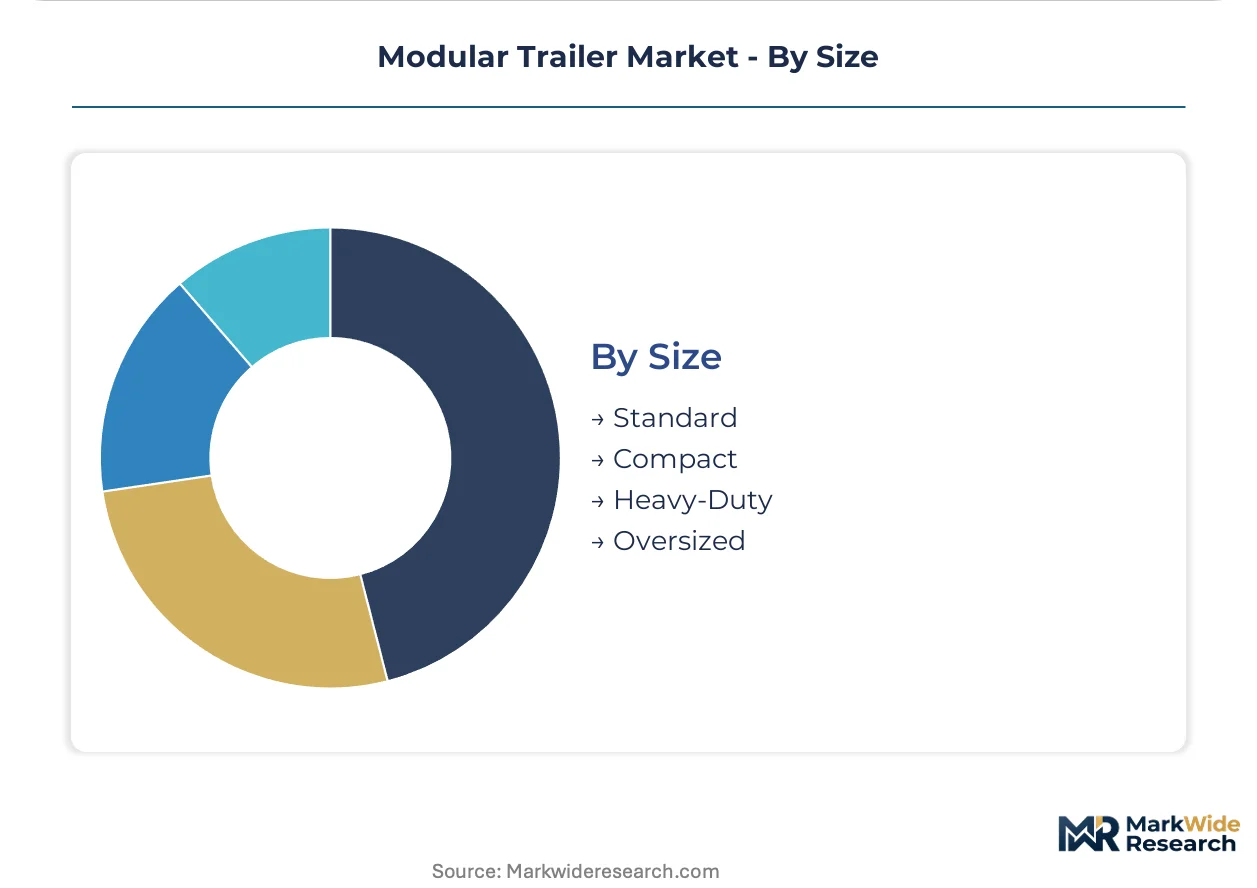
Modular trailer specification chains fragment across four independent dimensions. Fleet procurement decisions hinge on matching platform geometry to cargo inertial loads, duty cycles to axle configurations, and ownership models to project duration.
Product Type:
Platform geometry determines loading mechanics, deck height clearance, and weather protection capabilities across transport corridors.
- Flatbed:Open-deck construction with standardized stake pockets and rub rails accommodates general freight, construction materials, and containerized loads. Demand concentrates in Texas interstate corridors serving Permian Basin logistics networks, where rapid load turnover favors unobstructed deck access.
- Curtain Side:Tautliner fabric panels mounted on retractable roof systems provide side-accessible cargo handling without dedicated van assets. Automotive assembly supply chains in Michigan and Ohio are adopting these configurations for just-in-time component delivery requiring weather protection.
- Lowboy:Detachable gooseneck designs enable front-loading of immobile heavy equipment.
- Drop Deck:Step-frame geometry bridges height-restricted and standard deck zones.
Flatbed commands the established base. The steepest expansion runs through Curtain Side.
Application:
End-use verticals impose distinct duty cycles, payload spectrums, and regulatory exposure on platform specifications.
- Construction:Haul cycles demand rapid reconfiguration between aggregate, equipment, and prefabricated structural elements. Infrastructure stimulus programs in Florida and California are accelerating fleet turnover for contractors serving urban density projects.
- Logistics:Line-haul and drayage operations prioritize tare weight minimization and intermodal compatibility. E-commerce fulfillment networks in Pennsylvania and Illinois are specifying lightweight aluminum platforms for regional distribution loops.
- Agriculture:Seasonal harvest windows require high-volume grain and equipment transport.
- Military:Tactical mobility specifications demand air-transportable and rail-interoperable configurations.
Construction anchors volume concentration. Logistics is climbing the fastest as asset-light rental penetration reshapes procurement.
End User:
Ownership structure and fleet scale determine specification authority and maintenance integration strategies.
- Rental Services:Intermediary fleet operators bundle rapid reconfiguration capabilities with short-term deployment contracts. Oilfield services contractors in New Mexico and west Texas favor this model for project-based capacity without fixed asset exposure.
- Transport Companies:Asset-heavy carriers with dedicated maintenance infrastructure specify for lifecycle durability and residual value retention.
- Construction Firms:Captive fleet operations align platform configurations with proprietary equipment portfolios.
- Government Agencies:Public procurement protocols prioritize domestic content requirements and standardized interoperability.
Transport Companies retain the largest installed base. Rental Services is gaining share fastest as project-based contracting displaces traditional ownership.
Size:
Gross combination weight ratings and dimensional envelopes segment manufacturing workflows and regulatory compliance pathways.
- Heavy-Duty:Multi-axle hydraulic configurations support gross weights exceeding standard federal bridge formula limits. Overweight-permit operations in Louisiana and Oklahoma energy corridors specify these platforms for repetitive superload movements.
- Standard:Single and tandem axle designs serve general freight within federal dimension regulations.
- Compact:Reduced wheelbase platforms navigate urban delivery constraints and tight site access.
- Oversized:Modular axle-line systems permit incremental capacity expansion for project cargo.
Standard dimensions dominate unit volume. Heavy-Duty is expanding most quickly as energy infrastructure density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors while Mexican assembly zones compete on throughput velocity. This asymmetry shapes procurement patterns across integrated North American logistics networks. Fleet operators synchronize specifications to exploit these divergent cost structures.
United States
Permian Basin oilfield services contractors drive heavy-duty multi-axle demand for repetitive overweight-permit operations. The Federal Motor Carrier Safety Administration's updated brake testing protocols extend certification cycles for new axle configurations. West Texas and southeast New Mexico logistics clusters favor rapid deck reconfiguration between equipment and pipe hauls.
Germany
Precision valve assemblies for multi-axle steering systems anchor supplier concentration in southern industrial zones. The Kraftfahrt-Bundesamt enforces axle-spacing harmonization with EU directive 96/53/EC for cross-border fleet interoperability. Ruhr industrial cluster blast furnace capacity swings quenched-and-tempered plate prices affecting frame fabrication costs.
Canada
Prairie province energy corridors sustain demand for western manufacturing footprints serving oil sands and conventional drilling operations. Transport Canada National Safety Code standards enable cross-border fleet standardization with US operators. Alberta and Saskatchewan fabrication zones face certified aluminum TIG specialist wage premiums.
Mexico
Nearshoring manufacturing supply chains accelerate demand for curtain side configurations serving automotive assembly corridors. The Secretariat of Economy's automotive sector incentives attract component logistics investment. Nuevo León and Bajío Region transport hubs specify lightweight aluminum platforms for regional distribution loops.
China
Domestic infrastructure stimulus programs expand heavy-haul fleet procurement for construction and energy verticals. The Ministry of Industry and Information Technology enforces GB standards for commercial vehicle dimensions affecting modular specification chains. Yangtze River Delta manufacturing clusters integrate carbon-fiber-reinforced polymer decking into weight-sensitive platform designs.
Modular Trailer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hydraulic assemblies and precision-machined axle modules. The vendor base organizes around three strategic archetypes: captive engineering houses with backward integration into frame fabrication, regional fabricators serving corridor-specific permit regimes, and rental-service intermediaries bundling reconfiguration with short-term deployment. Consolidation pressure concentrates among multi-axle hydraulic specialists as bridge formula compression rewards rapid redesign capacity. Geographic expansion and technology licensing represent the dominant competitive vectors as manufacturers seek regulatory arbitrage across state and national jurisdictions.
Within the North American platform tier, Doepker Industries and XL Specialized Trailers exemplify divergent geographic anchoring strategies. Doepker leverages its western Canadian manufacturing footprint to dominate prairie province energy corridors. XL Specialized Trailers occupies a position in multi-axle hydraulic configuration engineering for overweight-permit cargo. Trail King Industries represents backward integration into frame fabrication, reducing lead times for custom deck specifications. These three anchors illustrate how regional manufacturing concentration, engineering specialization, and supply chain control define competitive positioning.
| Leading Market Players |
|---|
| Doepker Industries |
| Manac |
| XL Specialized Trailers |
| Stoughton Trailers |
| Hyundai Translead |
| Trail King Industries |
| Heil Trailer International |
| Felling Trailers |
| Fontaine Trailer Company |
| Others |
Supply Flow & Price Mechanics
The Permian Basin corridor's overweight-permit operations create a cost dynamic where hydraulic axle-line engineering premiums diverge sharply from standard flatbed configurations, concentrating pricing power with manufacturers holding captive design capacity while squeezing regional fabricators on commodity frame orders.
Pricing Analysis
The customization-premium spread between configured-to-order multi-axle hydraulic platforms and standard flatbed configurations runs wide, with price differentiation anchored in bridge-formula compliance engineering and certified welding labor scarcity. Contract-based long-term offtake structures dominate fleet procurement, though rental-service intermediaries are introducing subscription-tiered models with bundled maintenance. Price erosion runs through standard deck specifications as Mexican assembly zones compete on throughput velocity, while heavy-duty configurations retain pricing resilience. Logistics operators show highest price sensitivity; energy sector contractors prioritize payload optimization over unit cost.
Supply Chain Analysis
Export-control regimes on precision-machined hydraulic valve assemblies constrain flows from southern German industrial zones, forcing North American platform integrators to qualify secondary sourcing channels. Frame fabrication draws from Ruhr industrial cluster steel capacity and Yangtze River Delta aluminum processing, with carbon-fiber-reinforced polymer decking emerging from aerospace supply chain migration. Single-source vulnerability concentrates in multi-axle steering hydraulics. Distribution runs through dealer-direct channels fragmenting as rental-service intermediaries capture project-based contracting demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular trailer specification chains are approaching a platform-economics inflection where telematics-embedded suspension ecosystems and cross-border fleet standardization create winner-take-most dynamics for interoperability leaders.
For Market Incumbents: Insulate engineering leadership through backward integration into precision axle fabrication, reducing exposure to German hydraulic component concentration. Prioritize captive certification capacity for accelerated Federal Motor Carrier Safety Administration brake testing protocols. California zero-emission tractor mandates threaten fleet replacement cycle synchronization; anchor platform specifications to electric powertrain weight distributions before compatibility standards crystallize.
For New Entrants and Emerging Players: Mexico's Bajío Region automotive assembly corridors present underpenetrated demand for curtain side configurations serving just-in-time component logistics. Target nearshoring supply chain investment zones with lightweight aluminum platform offerings bundled with rapid reconfiguration services. A rental-service intermediary model bypasses capital-intensive manufacturing entry barriers while capturing asset-light procurement shifts.
For Investors and Strategic Acquirers: Regional fabricators with established permit-regime relationships in Texas, Louisiana, and Oklahoma represent acquisition targets as bridge-formula state variance rewards localized regulatory arbitrage expertise. Long-term viability hinges on telematics integration capabilities transforming hardware margins into subscription revenue streams. Monitor California Air Resources Board zero-emission compliance timeline acceleration as fleet replacement pull-through demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Embedded Suspension Development | Real-time load monitoring from XL Specialized Trailers converges with predictive maintenance platforms to create recurring revenue streams. |
| Cross-Border Fleet Standardization | Transport Canada National Safety Code harmonization enables unified specifications for integrated US-Canada logistics network operators. |
| Carbon-Fiber Decking Manufacturing Scale-Up | Hybrid steel-composite platforms from Yangtze River Delta clusters compress tare weight for Permian Basin overweight-permit operations. |
| Rental-Service Intermediary Expansion | Asset-light procurement models in New Mexico and west Texas displace traditional dealer-direct ownership for project-based oilfield contractors. |
| Precision Axle Fabrication Backward Integration | Trail King Industries demonstrates how in-house frame production reduces lead times for custom deck specifications in energy corridors. |
Methodological Framework
A standing panel of fleet operations directors, oilfield services procurement managers, heavy-haul maintenance supervisors, and trailer dealership principals provided ongoing calibration across primary interview cycles. Secondary validation drew from Federal Motor Carrier Safety Administration brake testing protocol filings, Transport Canada National Safety Code regulatory updates, US Department of Transportation bridge formula enforcement records, and American Trucking Associations fleet composition surveys. Bottom-up unit shipment modeling triangulated against top-down gross combination weight rating capacity estimates.
Scenario-bracketing framed analytical construction across the projection horizon, with segmentation dimensions spanning platform geometry, axle configuration, ownership model, and gross weight rating tier. CAGRs derived from logistic curve fitting to historical replacement cycle patterns and infrastructure stimulus program deployment schedules. California Air Resources Board zero-emission mandate compliance timelines and Permian Basin drilling activity indices served as industry-specific forecast inputs.
Practitioners should monitor quenched-and-tempered steel price volatility from Ruhr blast furnace capacity and hydraulic component supplier concentration in southern Germany for early signals warranting forecast revision. Cross-checking against American Trucking Associations quarterly fleet age and composition reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Robotic Haul Trucks Market