
 Flatbed Semi-Trailer Market | 2026-2036
Flatbed Semi-Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Flatbed Semi-Trailer Market Analysis
Aluminum is broadening its share of flatbed semi-trailer decks as fleets seek payload recovery and fuel economy gains. Schmitz Cargobull AG leverages its European manufacturing footprint to sustain aluminum-intensive designs for cross-border freight operators. Wabash National Corp. anchors North American production with advanced composite panel systems that reduce tare weight. China International Marine Containers (Group) Ltd. dominates volume manufacturing through integrated steel supply chains serving domestic and export markets.
A flatbed semi-trailer is an open-deck freight-hauling platform, typically constructed with steel or aluminum frame rails, hardwood or composite decking, and rated for loads between 40,000 and 80,000 pounds depending on axle configuration. Drop deck variants command premium positioning in the product type category because their lowered rear deck accommodates taller cargo without exceeding bridge clearance laws. Steel retains volume leadership in the material segment due to lower upfront cost and repair familiarity, though composite adoption is accelerating in fleets with dedicated lightweighting targets.
The EPA, NHTSA, and ISO 9001 quality frameworks collectively govern flatbed semi-trailer design, emissions compliance, and manufacturing consistency across the United States. EPA Phase 2 standards pressure OEMs to reduce tractor-trailer combination weights, which redirects procurement toward aluminum and composite material specifications. Stakeholders must monitor how pending revisions to federal bridge formula regulations could redefine permissible axle configurations and deck lengths.
Market Dynamics
EPA Phase 2 greenhouse gas standards for heavy-duty vehicles are compressing tractor-trailer combination weights, forcing fleet operators to recalculate total cost of ownership around tare weight reduction. This regulatory pressure is redistributing procurement budgets toward aluminum and composite material specifications.
Growth Catalysts
- Construction sector expansion:Infrastructure stimulus across Sun Belt states is generating sustained demand for heavy-haul flatbed capacity. Project pipelines in Texas, Florida, and Arizona are absorbing record equipment deployment.
- EPA Phase 2 compliance pathways:Regulatory pressure on tractor-trailer combinations is redirecting OEM engineering resources toward lightweight deck materials. Fleets recover payload capacity through specification changes rather than tractor replacement.
- Cross-border freight density:North American freight corridors are consolidating volume on aluminum-intensive equipment to maximize cubic efficiency per dispatched mile.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs swing with energy pricing and smelter curtailments, compressing margin predictability for deck manufacturers.
- Steel supply chain concentration:Domestic steel rail and frame component sourcing clusters in legacy industrial regions, creating geographic vulnerability to localized disruptions.
- Repair infrastructure limitation:Composite panel damage requires specialized technician certification and equipment absent from most independent service networks.
Strategic Opportunities
- Drop deck underpenetration:Lowered rear deck variants command premium positioning for taller cargo segments, with adoption concentrated in specialized heavy-haul niches.
- Telematics convergence:Integration of deck-mounted sensor arrays with fleet management platforms creates new recurring revenue streams for OEMs.
- IRA clean commercial vehicle credits:Federal incentives for zero-emission tractors indirectly benefit lightweight trailer specifications that extend electric range.
Industry Challenges
- Welding technician scarcity:Aluminum deck fabrication requires specialized certification programs that community colleges have not scaled to match replacement demand.
- Composite repair standardization delays:Absence of unified collision repair protocols forces insurers to apply conservative total-loss thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatbed Semi-Trailer Market |
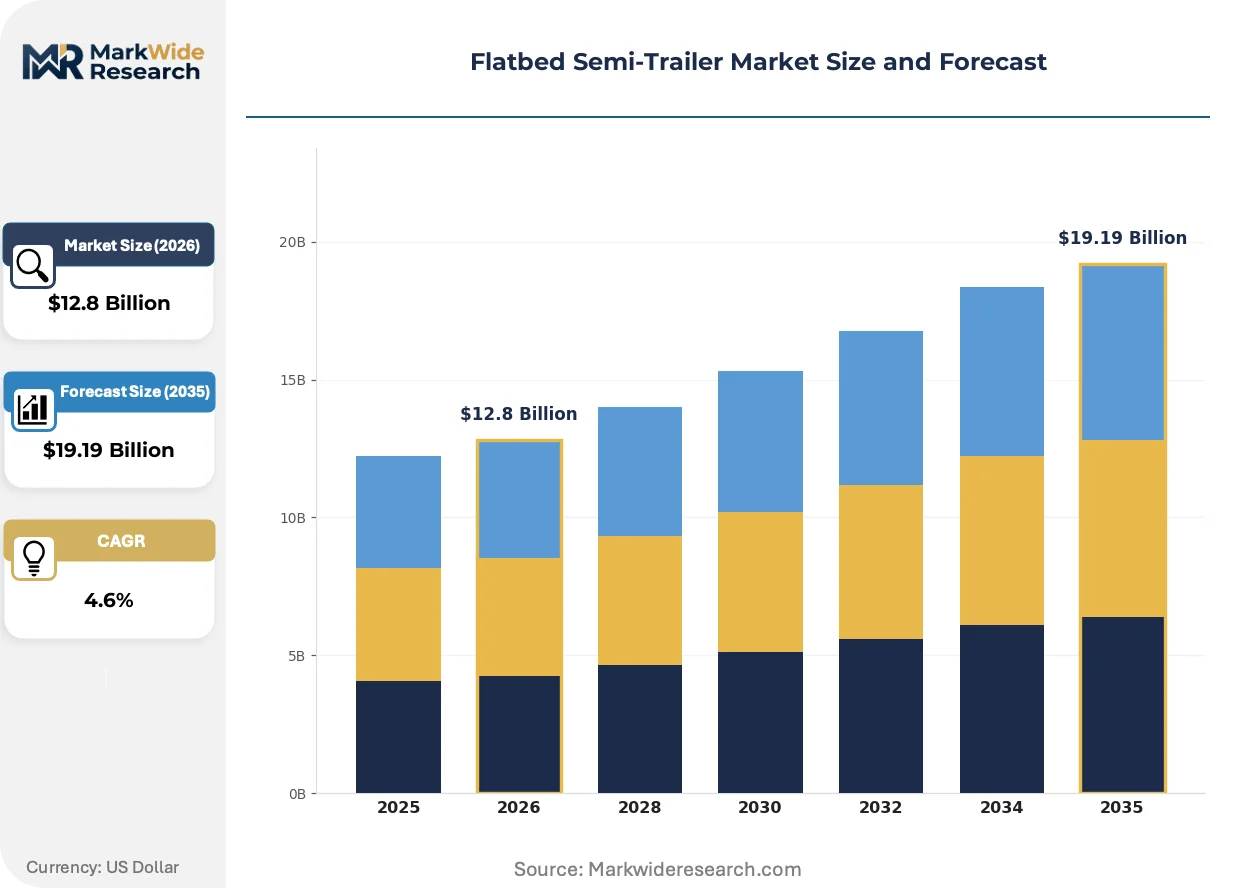
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lowboy, Drop Deck, Step Deck, Standard Flatbed Material: Aluminum, Steel, Composite, Wood End User: Construction, Agriculture, Transportation, Mining Size: 14 ft, 16 ft, 20 ft, 24 ft |
| Companies Covered | Featherlite Trailer Manufacturing LLC, Schmitz Cargobull AG, China International Marine Containers (Group) Ltd., Wabash National Corp., Utility Trailer Manufacturing Co., East Manufacturing Corp., Great Dane LLC, Alum Line Trailers, FAHRZEUGWERK BERNARD KRONE GMBH & CO. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatbed Semi-Trailer Market Emerging Trajectories
Lightweighting imperatives are restructuring material hierarchies across flatbed specification sheets. Three concurrent developments are compressing traditional steel-dominant procurement patterns.
Aluminum decking is overtaking hardwood and steel plate in long-haul fleet specifications. Aluminum extrusions deliver 40-50% weight reduction against comparable steel configurations. Mega-fleets with dedicated lightweighting targets are mandating aluminum decks on new orders, compressing payback calculations for smaller operators who face residual value risk on steel-heavy equipment.
EPA Phase 2 standards are forcing OEMs to document tractor-trailer combination efficiency as a system rather than isolated components. Trailer manufacturers must certify aerodynamic and weight contributions to combined vehicle performance. This integration requirement is accelerating engineering collaboration between tractor and trailer engineering teams previously siloed by procurement conventions.
Leasing structures are displacing outright purchase for mid-size fleets seeking to transfer residual value risk. Equipment finance providers are absorbing technology obsolescence exposure as material specifications shift. This channel migration is most visible in the 50-200 unit fleet segment, where capital constraints meet uncertainty about composite repair network maturation timelines.
Flatbed Semi-Trailer Market Segmentation
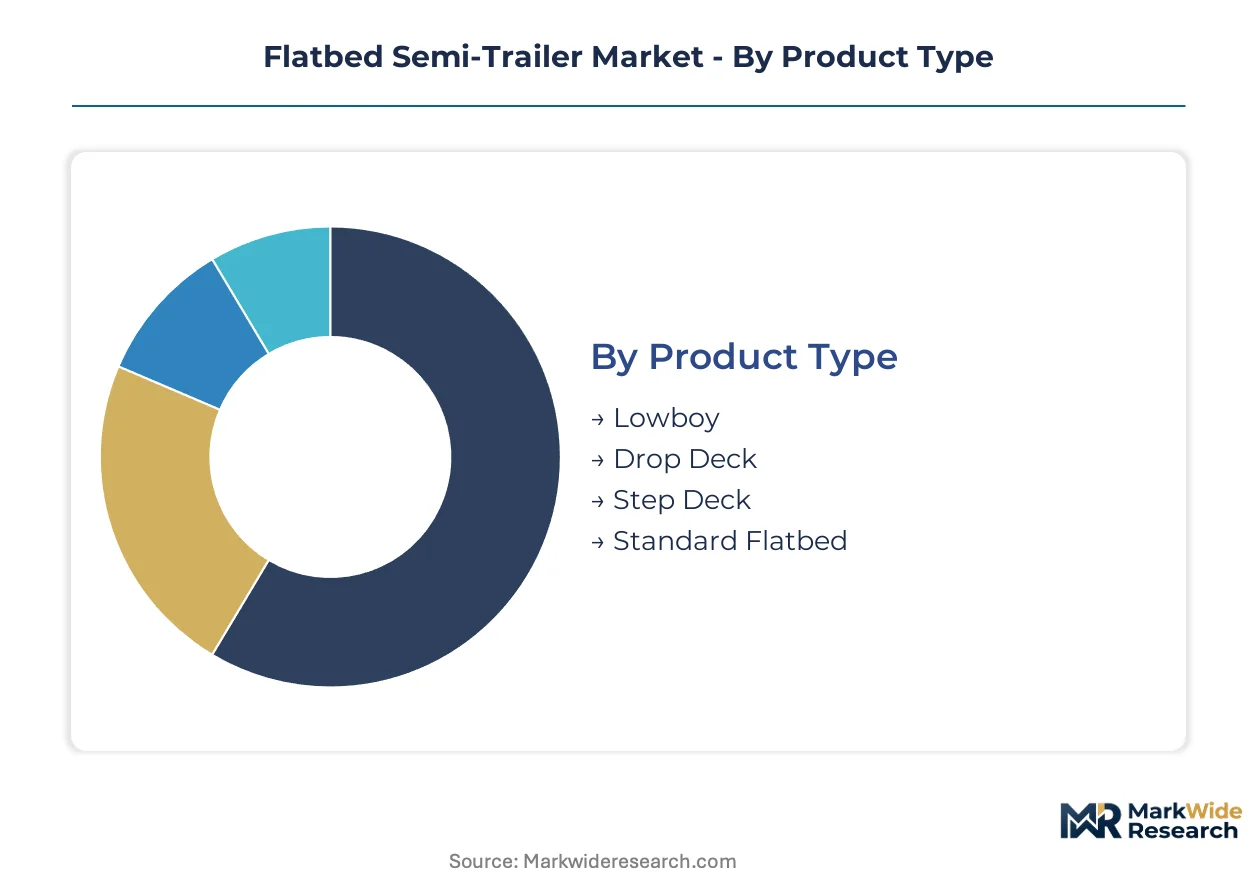
Flatbed semi-trailer procurement hinges on matching deck architecture to cargo dimensions, axle regulations, and payload economics. Fleet operators segment specifications across four dimensions that collectively determine total cost of ownership and route flexibility.
Product Type:
Fleet managers select deck geometry based on cargo height restrictions and loading efficiency requirements across their contracted lanes.
- Drop Deck:Features a lowered rear platform that accommodates cargo up to 10 feet tall without violating federal bridge clearance laws. Demand concentrates in heavy-haul operations serving Texas and Arizona energy corridors where oversized equipment dominates freight flows.
- Standard Flatbed:Maintains uniform deck height across the full length, optimized for palletized loads and crane-accessible cargo. Construction material distributors in Florida specify this type for lumber and prefabricated panel delivery where height flexibility matters less than loading speed.
- Lowboy:Designed with minimal deck height for extreme heavy-haul applications requiring concentrated weight distribution.
- Step Deck:Combines upper and lower deck levels for mixed-height cargo configurations in specialized freight niches.
Standard Flatbed leads on scale; Drop Deck leads on momentum as infrastructure projects expand.
Material:
Material selection trades upfront capital outlay against lifetime fuel savings and payload recovery potential.
- Steel:Retains dominant specification share due to lower acquisition cost and universal repair infrastructure. Independent owner-operators and small fleets in legacy industrial regions favor steel frames for collision repair accessibility and parts availability.
- Aluminum:Extruded deck systems deliver substantial tare weight reduction against steel equivalents. Mega-fleets with dedicated lightweighting mandates specify aluminum to recover payload capacity under EPA Phase 2 combination weight pressures.
- Composite:Advanced panel systems from specialized manufacturers reduce weight beyond aluminum capabilities but require certified repair networks.
- Wood:Traditional hardwood decking persists in short-haul agricultural applications where moisture resistance and replaceability outweigh weight considerations.
Steel dominates volume; Aluminum gains share fastest as regulatory pressure intensifies.
End User:
Industry-specific cargo patterns dictate axle configurations, deck lengths, and durability requirements.
- Construction:Absorbs the largest equipment deployment as infrastructure stimulus across Sun Belt states generates sustained demand for heavy-haul capacity. Project pipelines in Texas, Florida, and Arizona drive specification toward drop deck and extended-length configurations.
- Transportation:Third-party logistics providers prioritize versatile standard flatbeds with rapid turnaround specifications for cross-border freight density along North American corridors.
- Agriculture:Seasonal harvest patterns favor shorter deck lengths and wood-composite hybrid constructions for equipment and commodity transport.
- Mining:Extreme duty cycles require reinforced steel framing and specialized lowboy configurations for excavator and haul truck component movement.
Construction anchors absolute demand; Transportation shows the steepest expansion trajectory as freight intermediaries consolidate equipment pools.
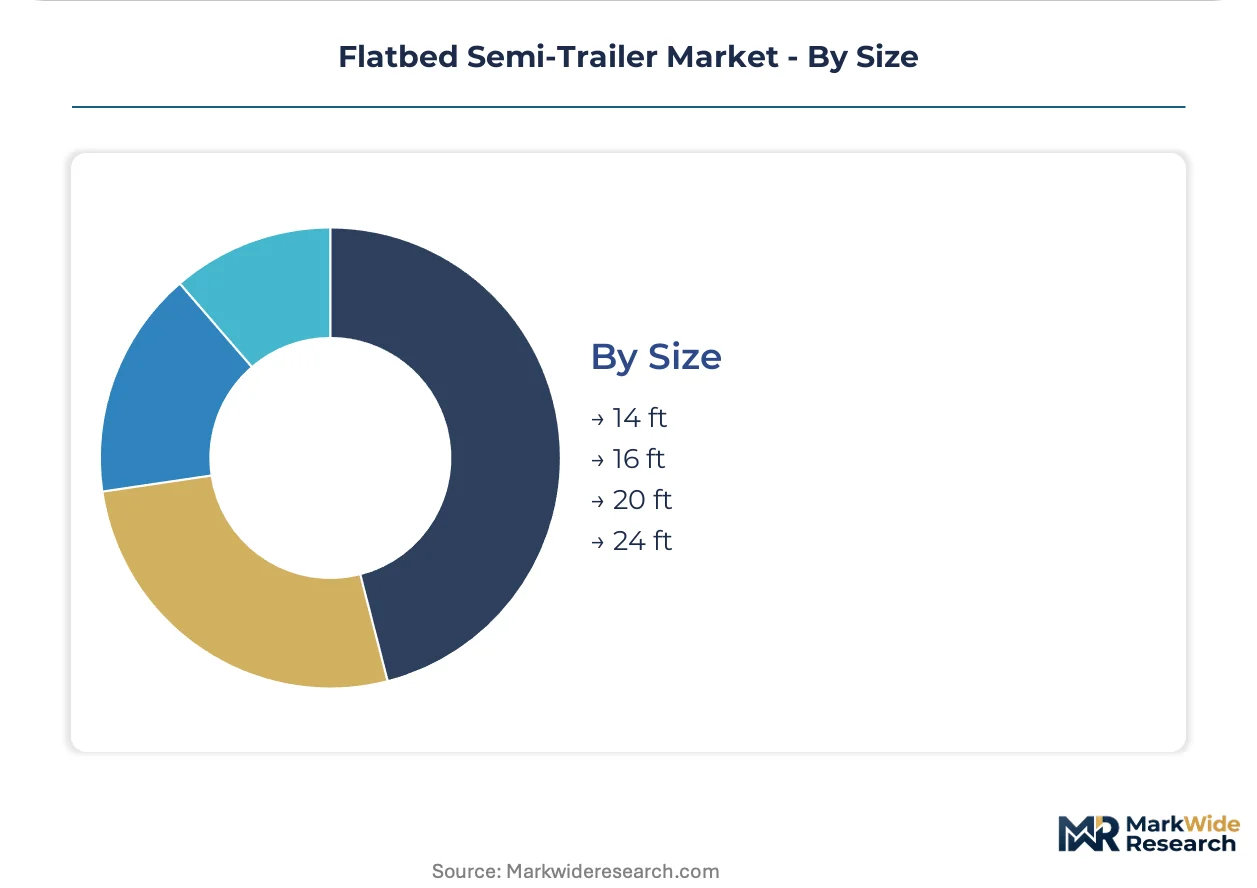
Size:
Deck length selection balances cubic capacity against state-level length regulations and terminal maneuverability constraints.
- 20 ft:Represents the versatile midpoint specification accommodating standard container lengths and palletized building materials. Distribution fleets serving urban construction sites favor this length for compliance with municipal access restrictions.
- 24 ft:Maximizes cubic efficiency for long-haul operators with dedicated lane structures and minimal urban delivery requirements.
- 14 ft:Configured for specialized short-haul and urban delivery applications with severe turning radius constraints.
- 16 ft:Serves regional agricultural and light construction markets requiring moderate payload without full-length deck investment.
20 ft configurations lead on scale; 24 ft specifications lead on momentum as long-haul freight density concentrates on high-efficiency equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt freight corridor anchors flatbed semi-trailer deployment intensity, with infrastructure stimulus and cross-border logistics concentrating equipment procurement in specific national markets.
United States
Texas, Florida, and Arizona absorb record equipment deployment through energy corridor heavy-haul and construction material distribution. EPA Phase 2 standards pressure fleet operators toward aluminum specifications to recover payload capacity. Dallas-Fort Worth and Houston anchor manufacturing and fleet headquarters concentration for drop deck configurations.
Germany
Cross-border freight density along Rhine-Alpine corridors sustains aluminum-intensive trailer specifications for cubic efficiency per dispatched mile. KBA vehicle type approval frameworks govern weight and dimension compliance for international operators. Baden-Württemberg and North Rhine-Westphalia host engineering clusters advancing composite panel integration.
China
Domestic infrastructure investment and export manufacturing sustain volume manufacturing through integrated steel supply chains. MIIT fuel consumption standards for commercial vehicles redirect engineering resources toward lightweight frame designs. Shandong and Jiangsu provinces concentrate production capacity serving both domestic and Southeast Asian export markets.
Canada
Transcontinental freight corridors connecting Vancouver and Toronto prioritize aerodynamic and weight-optimized equipment for long-haul efficiency. Transport Canada vehicle safety regulations align with US EPA frameworks for cross-border fleet interoperability. Ontario and Alberta anchor equipment distribution networks serving resource extraction and intermodal logistics.
Mexico
Nearshoring manufacturing expansion and USMCA trade corridors generate demand for versatile standard flatbed configurations. NOM vehicle safety standards govern axle configuration and dimensional compliance for international operators. Nuevo León and Baja California concentrate fleet operations serving automotive and electronics supply chains.
Flatbed Semi-Trailer Market Vendor Landscape
Global majors compete with regional champions across material specification and repair network coverage. The vendor base organizes around three strategic tiers: integrated steel manufacturers serving price-sensitive volume segments, aluminum specialists capturing regulatory-driven lightweighting demand, and composite technology developers addressing premium fleet specifications. Market structure rewards backward integration into aluminum extrusion and captive control over hardwood decking supply. Consolidation pressure concentrates among mid-scale fabricators lacking certified repair network partnerships.
Among European-based fabricators, Schmitz Cargobull AG and FAHRZEUGWERK BERNARD KRONE GMBH & CO. KG occupy positions within the aluminum-specialist archetype, while Wabash National Corp. anchors North American representation of the composite-integrated tier. These three exemplify divergent geographic and technological positioning strategies visible across the competitive landscape.
| Leading Market Players |
|---|
| Featherlite Trailer Manufacturing LLC |
| Schmitz Cargobull AG |
| China International Marine Containers (Group) Ltd. |
| Wabash National Corp. |
| Utility Trailer Manufacturing Co. |
| East Manufacturing Corp. |
| Great Dane LLC |
| Alum Line Trailers |
| FAHRZEUGWERK BERNARD KRONE GMBH & CO. KG |
| Others |
Supply Flow & Price Mechanics
Backward integration into aluminum extrusion operations anchors both supply security and pricing power for flatbed semi-trailer manufacturers serving EPA Phase 2 compliance-driven fleets. Captive control over primary metal inputs insulates producers from LME price volatility while enabling pass-through negotiation leverage with steel-dependent competitors.
Pricing Analysis
Primary aluminum and steel coil pass-through clauses dominate contract structures, with three-tier pricing stratification across premium aluminum-composite, mid-grade aluminum-steel hybrid, and economy steel-only specifications. Price differentiation centers on ISO 9001 certification tier and fleet volume scale, with mega-fleets extracting 12-18 point discounts against owner-operator spot purchases. Cost compression in the steel tier intensifies because of scrap price linkage and energy surcharge volatility. Independent owner-operators exhibit highest price sensitivity due to residual value uncertainty on steel-heavy equipment.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 fleet operators mandate qualified suppliers across both domestic and Mexican steel rail producers, compressing single-source dependency risk. Raw material feeds draw from integrated Chinese steel mills, German aluminum smelters, and domestic hardwood decking suppliers. Tariff exposure on Chinese steel components creates margin vulnerability for non-integrated fabricators. Distribution runs through OEM-direct fleet contracts, independent dealer networks, and equipment finance leasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flatbed semi-trailer demand functions as a stable compounder, with infrastructure stimulus across Sun Belt states generating replacement-cycle visibility that smooths cyclical exposure.
For Market Incumbents: Acquire certified aluminum welding training capacity to preempt technician scarcity bottlenecks threatening production expansion. Consolidate repair network partnerships in Texas and Arizona energy corridors to defend service attach rates against emerging composite specialists. Anchor defensive positioning through backward integration into hardwood decking supply. For New Entrants and Emerging Players: Equipment finance providers represent the most accessible channel partner type for mid-size fleet penetration without legacy dealer relationships. Target the 50-200 unit fleet segment with leasing-structured aluminum specifications, where capital constraints meet uncertainty about composite repair maturation. Penetrate through telematics-bundled offerings that create recurring revenue differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fabricators lack certified repair network partnerships and face technology obsolescence exposure from material specification shifts. Long-term viability favors aluminum-specialist archetypes with captive extrusion capacity and Sun Belt geographic density. Monitor EPA bridge formula revision timelines as the signal indicating inflection in axle configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply from Shandong and domestic smelters insulates margin from LME volatility. |
| Composite Panel Repair Network Certification | Specialized technician programs address insurer total-loss threshold conservatism. |
| Telematics Platform Integration | Deck-mounted sensor arrays generate recurring revenue from fleet management subscriptions. |
| Drop Deck Capacity Expansion | Extended-length configurations capture infrastructure stimulus in Texas and Arizona corridors. |
| Cross-Border Service Partnership | Mexican repair alignment supports USMCA corridor fleet interoperability requirements. |
Methodological Framework
Bottom-up fleet operator modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, maintenance supervisors, equipment finance underwriters, and aluminum extrusion procurement managers combined with secondary validation from EPA certification databases, NHTSA vehicle registration files, and ATRI freight cost indices. Trade flow analysis from customs records and steel mill shipment reports anchored supply-side triangulation.
Input-output matrices mapped deck material specifications against axle configurations and end-use industry demand across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user industry, deck length, and regional freight corridor density. CAGRs derived from replacement cycle analysis, fleet expansion pipelines, and regulatory compliance cost amortization schedules. Forecast inputs incorporated EPA Phase 2 penetration curves and infrastructure appropriation disbursement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum price volatility and composite repair network maturation rates. Deviation in federal bridge formula revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market