
 Commercial Vehicle Transmission Market | 2026-2036
Commercial Vehicle Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Transmission Market Analytics
Chinese heavy-duty transmission manufacturing is consolidating as domestic producers scale automated production lines and foreign incumbents reposition supply chains. ZF Friedrichshafen leverages its integrated mechatronics portfolio to anchor premium automated transmission supply for European and North American OEMs. Allison Transmission sustains dominant positions in refuse and urban bus applications through purpose-built fully automatic architectures. Eaton Corporation competes aggressively in North American Class 8 segments with its proprietary overdrive manual and automated manual platforms.
A commercial vehicle transmission translates engine torque to the drivetrain through synchronized gear sets, with torque ratings spanning 300 Nm to over 3,000 Nm depending on vehicle class and duty cycle. These systems govern fuel efficiency, drivability, and component longevity across freight haulage, construction, and municipal service applications. Automatic transmissions command premium positioning in urban delivery and public transportation where stop-start frequency punishes manual clutch wear. Hydraulic actuation retains cost advantages in emerging markets while electric actuation architectures gain traction in electrified powertrain integration. Manual transmissions still dominate agricultural and developing-market construction segments where capital constraints override operator comfort priorities.
EPA Phase 3 standards, Euro VII limits, and China's MIIT fuel consumption regulations collectively tighten emission and efficiency benchmarks that transmission architectures must satisfy. NHTSA and the EU's F-Gas Regulation further constrain refrigerant and lubricant choices in thermal management systems paired with advanced transmissions. Fleet operators and OEM procurement teams must monitor electrified powertrain coupling standards and software-defined shift calibration capabilities as these dimensions separate next-generation supplier winners from legacy hardware providers.
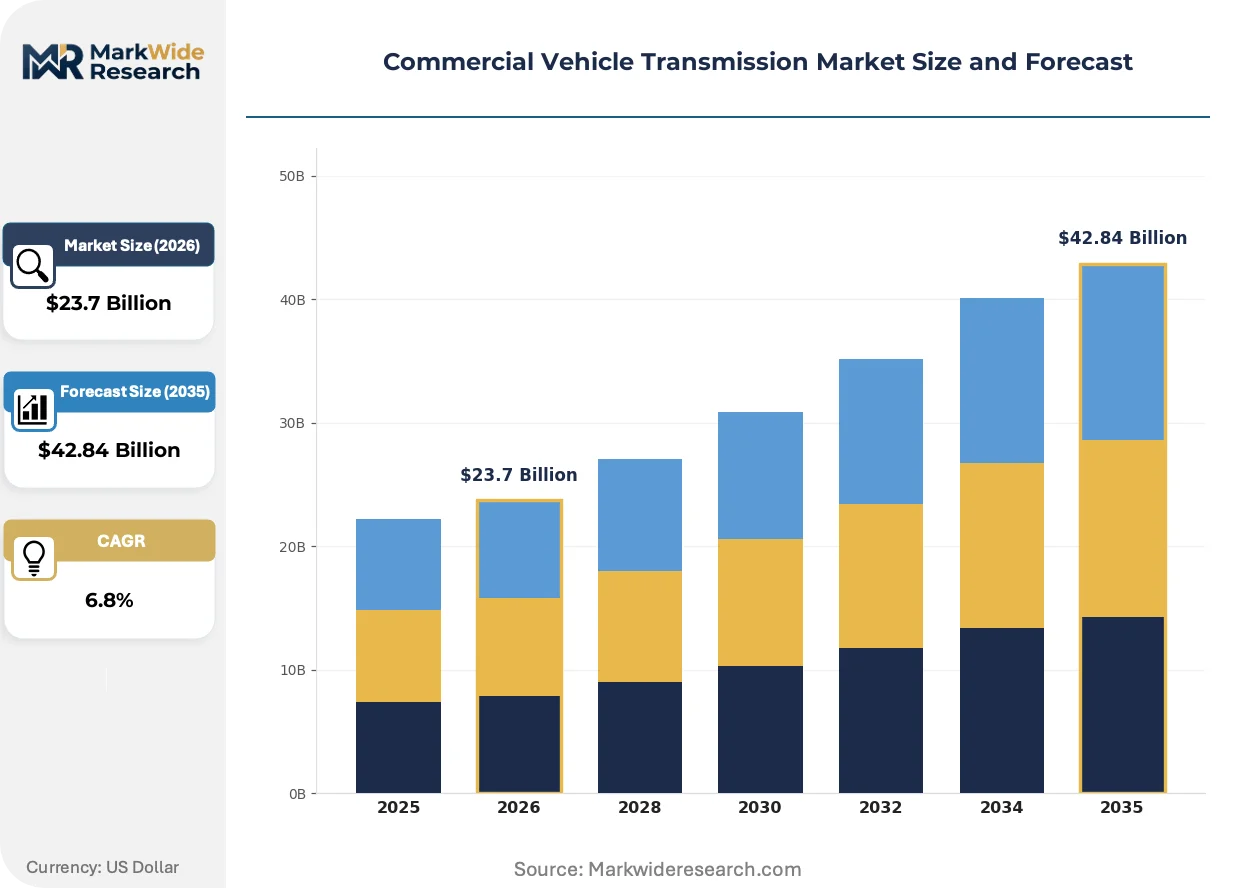
Market Dynamics
Electrified powertrain coupling standards are fragmenting transmission architectures as OEMs balance dual-clutch efficiency against dedicated hybrid transmission integration for heavy-duty cycles. EPA Phase 3 and Euro VII timelines compress development windows while software-defined calibration capabilities separate contract winners from hardware-only suppliers.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Fleet operators in North American long-haul freight accelerate automated manual transmission procurement to meet tightening efficiency benchmarks without full powertrain redesign.
- Urban bus electrification:Municipal transit authorities in China and India specify integrated electric drive units with multi-speed reduction gearboxes for hill-start torque management.
- Dual-clutch automation:European construction equipment OEMs adopt wet-clutch architectures for loader and articulated hauler applications where stop-start frequency degrades conventional manual synchronizers.
Market Restraints
- Rare earth magnet cost volatility:Permanent magnet materials for electric motor-transmission coupling face supply concentration risk from Chinese processing facilities, inflating hybrid system bill-of-materials unpredictably.
- Torque converter inertia:Traditional hydraulic coupling architectures impose efficiency penalties exceeding eight percentage points versus lock-up clutches, constraining their deployment in long-haul freight despite durability advantages.
- Euro VII certification friction:Proposed real-driving emission testing protocols for heavy-duty vehicles extend validation timelines by fourteen to eighteen months, freezing transmission-ECU calibration release schedules.
Strategic Opportunities
- Indian medium-duty retrofit:State transport corporation tender volumes for bus fleet modernization create aftermarket demand for automated manual conversion kits compatible with existing axle ratios.
- Battery-electric refuse truck integration:Two-speed e-axle architectures enable single-motor designs to replace dual-motor layouts, reducing power electronics cost while maintaining curb-to-curb acceleration targets.
- ISO 26262 functional safety:ASIL-D certification for transmission control modules opens premium positioning in autonomous truck pilot programs where shift-actuator fault tolerance is non-negotiable.
Industry Challenges
- Mechatronics calibration talent scarcity:Control algorithm development for clutch-to-clutch torque transfer requires expertise spanning tribology, real-time embedded systems, and thermal modeling that few engineering programs integrate.
- Legacy fleet software interoperability:Telematics retrofit for ten-to-fifteen-year-old vehicles demands backward-compatible CAN bus protocols that constrain shift-schedule optimization in mixed-age fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Transmission Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Semi-Automatic, Continuously Variable End User: Fleet Operators, OEMs, Aftermarket Providers, Vehicle Assemblers Application: Construction, Freight Transport, Public Transportation, Agriculture Technology: Hydraulic, Electric, Mechanical, Pneumatic |
| Companies Covered | Allison Transmission, Aisin Seiki, ZF Friedrichshafen, Chongqing Tsingshan, SAIC, Eaton Corporation, HYUNDAI TRANSYS, Zhejiang Wanliyang, Borgwarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Transmission Market Evolving Landscape
Software-defined shift calibration is absorbing development resources as transmission suppliers differentiate through predictive terrain-based gear selection rather than hardware torque capacity claims. Actuation electrification and thermal management integration now determine competitive positioning more than gear-count expansion.
Electric motor-transmission coupling architectures are absorbing thermal management complexity as integrated cooling circuits replace discrete oil-to-water heat exchangers. European OEMs in the premium coach segment specify these consolidated thermal systems for continuous-grade descent braking. The structural consequence is absorbing service margin from independent workshops into captive dealer networks equipped with specialized filling and bleeding equipment.
EPA Phase 3 and Euro VII emission limits are compressing hardware development cycles while expanding software validation scope for transmission control modules. Powertrain engineers must demonstrate CO2 reduction across standardized drive cycles that penalize shift-hunting behavior. Long-haul fleet procurement teams now require open-access calibration interfaces as contract terms, preventing supplier lock-in for route-specific shift mapping.
Fleet procurement teams are consolidating transmission supplier relationships to secure volume pricing and dedicated engineering support for route-specific calibration. Direct OEM-fleet negotiations displace traditional distributor networks in North American Class 8 segments. This concentration is most visible in dedicated contract carriage operations where single-source agreements cover five-to-seven-year replacement cycles.
Commercial Vehicle Transmission Market Segmentation
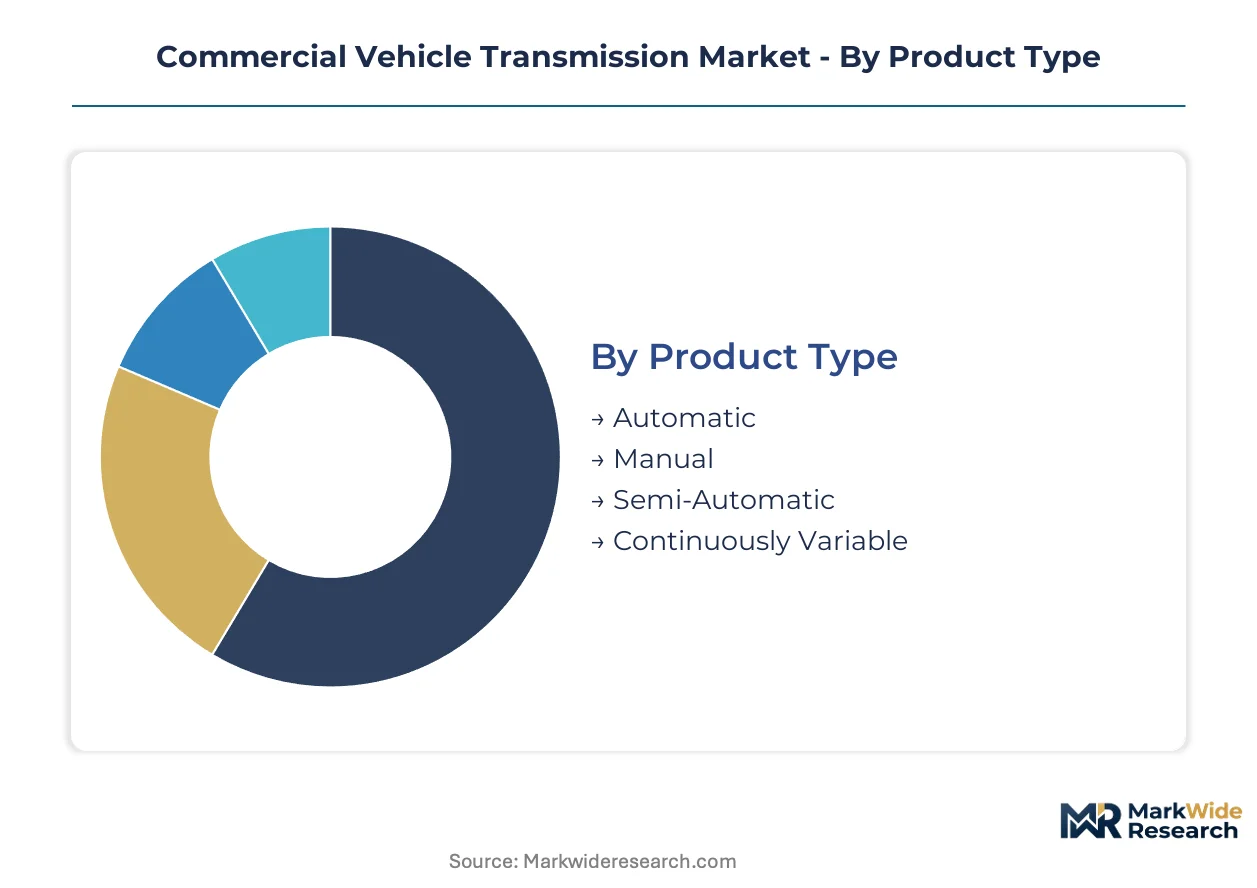
Transmission procurement patterns diverge sharply between capital-constrained operators prioritizing acquisition cost and fleet managers optimizing total cost of ownership through fuel efficiency and durability. Segmentation reveals how duty cycle intensity, electrification readiness, and service infrastructure density reshape supplier competitive boundaries across vehicle classes.
Product Type:
Volume concentration favors manual architectures in emerging markets, while premium positioning clusters around automated variants with integrated mechatronics.
- Automatic:Torque converter and planetary gear sets deliver seamless ratio changes under severe stop-start cycles. Demand concentrates in US municipal bus fleets and refuse collection where NHTSA safety mandates and union operator agreements eliminate manual transmission options.
- Manual:Synchronized mesh designs with mechanical clutch actuation dominate Indian and Chinese medium-duty construction segments. Procurement decisions here prioritize field serviceability and spare parts availability over shift comfort.
- Semi-Automatic:Automated manual architectures with electronic clutch actuation bridge cost and efficiency for European long-haul freight operators facing EU Green Deal emission reduction timelines.
- Continuously Variable:Pulley-based ratio modulation serves niche agricultural and specialty vehicle applications requiring infinite speed control for PTO-driven implements.
Mature deployment sits with Manual transmissions. Newer deployment is concentrated in Semi-Automatic architectures.
End User:
Procurement authority is fragmenting as direct OEM-fleet partnerships displace traditional distributor intermediaries in high-volume segments.
- Fleet Operators:Dedicated contract carriage and for-hire trucking companies negotiate multi-year transmission supply agreements with open-access calibration interfaces. These operators specify route-optimized shift maps for terrain-specific fuel efficiency.
- OEMs:Vehicle manufacturers integrate transmission development into platform engineering for electrified powertrain compatibility. Powertrain coupling standards and thermal management integration now determine supplier selection.
- Aftermarket Providers:Independent remanufacturers and retrofit specialists serve legacy fleet segments with automated manual conversion kits. Indian state transport corporation tenders drive substantial volume for bus fleet modernization.
- Vehicle Assemblers:Contract manufacturers and knock-down assembly operations in developing markets source transmission systems through CKD supply arrangements with technology licensing provisions.
Procurement consolidation is most visible among Fleet Operators. Aftermarket Providers are gaining share fastest in electrification retrofit applications.
Application:
Duty cycle severity and annual mileage intensity create divergent technical requirements across use cases.
- Freight Transport:Long-haul Class 8 tractors and regional delivery trucks specify high-torque-capacity automated manuals with predictive terrain-based shifting. EPA Phase 3 compliance pressures accelerate adoption of efficiency-optimized architectures.
- Construction:Articulated haulers and wheel loaders demand wet-clutch automated systems resisting thermal degradation under repeated high-torque launches. European OEMs lead specification of dual-clutch architectures for this segment.
- Public Transportation:Urban transit buses and motor coaches integrate electric drive units with multi-speed reduction gearboxes. Chinese and Indian municipal authorities specify these systems for hill-start torque management in battery-electric platforms.
- Agriculture:Tractors and harvesters retain manual and powershift architectures where capital constraints override automation benefits. PTO compatibility and field serviceability dominate procurement criteria.
Technology refresh is accelerating in Public Transportation. Agricultural applications maintain the longest replacement cycles.
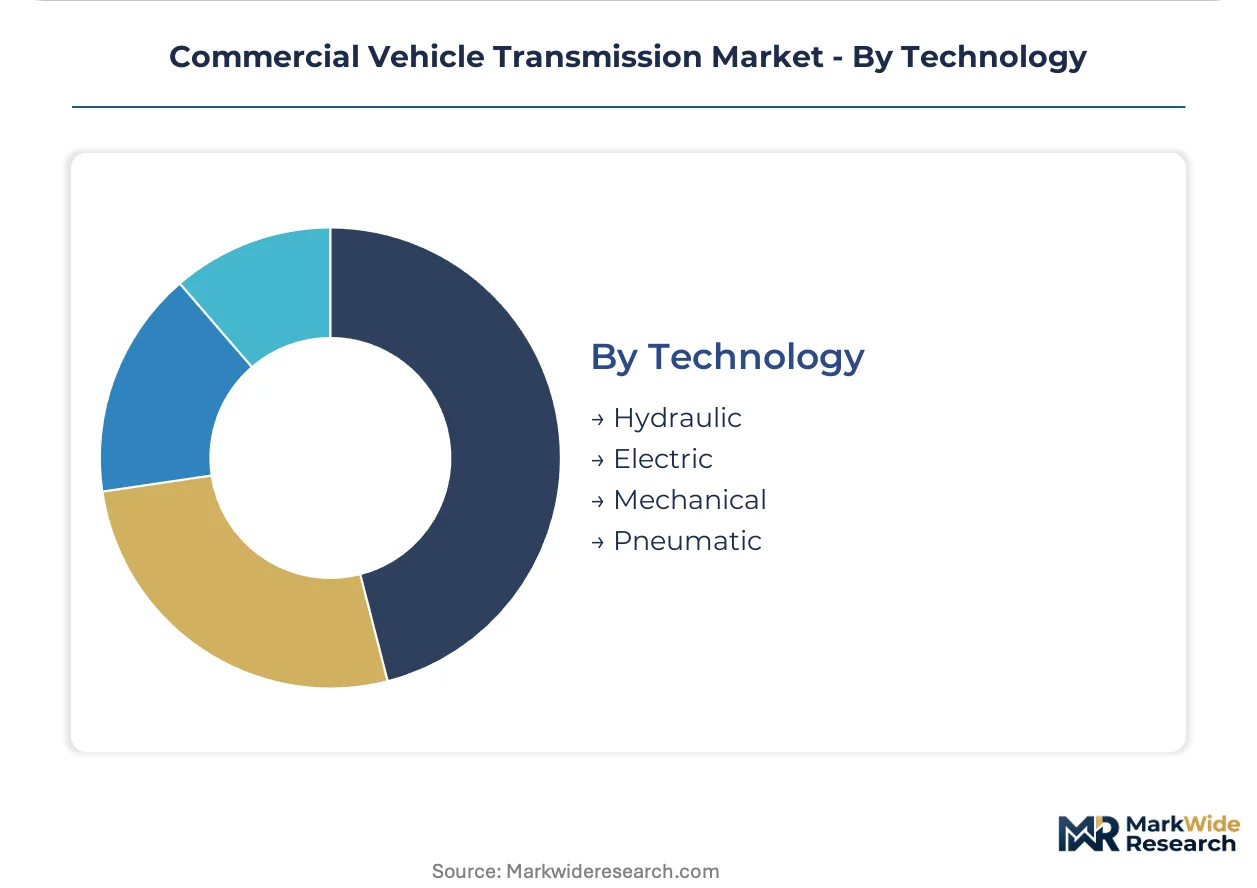
Technology:
Actuation mechanism selection determines electrification readiness and thermal management integration depth.
- Hydraulic:Conventional fluid power actuation retains cost advantages in price-sensitive developing markets. Torque converter architectures persist in severe-duty applications where durability outweighs efficiency penalties.
- Electric:Servo motor and ball-screw actuation enables precise clutch-to-clutch torque transfer for hybrid powertrain integration. This architecture dominates new platform development for EPA Phase 3 and Euro VII compliance.
- Mechanical:Cable and linkage systems persist in legacy manual transmissions and agricultural equipment where electronic complexity introduces field reliability risks.
- Pneumatic:Compressed air actuation serves heavy-duty commercial vehicle segments with existing air brake infrastructure, particularly in European and Latin American truck specifications.
Installed base concentration remains with Hydraulic systems. Electric actuation is climbing the fastest in new platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in Jiangxi Province supplies permanent magnet materials for electric motor-transmission coupling, anchoring Asia-Pacific supply chain concentration. Steel forging clusters in the Ruhr Valley and Great Lakes basin shape torque converter housing availability. Lubricant additive formulation expertise concentrates in the US Gulf Coast and Rotterdam-Antwerp corridor.
United States
Long-haul freight fleet operators in the Midwest and Southeast accelerate automated manual transmission procurement to meet EPA Phase 3 greenhouse gas standards. NHTSA safety mandates for heavy-duty vehicle braking integration constrain transmission control module architecture choices. Manufacturing concentration in Michigan and Indiana supplies torque capacity ratings spanning 1,800 to 3,000 Nm for Class 8 tractor applications.
Germany
Premium coach OEMs in Bavaria and Baden-Württemberg specify integrated thermal management systems for continuous-grade descent braking. KBA type-approval protocols for Euro VII real-driving emission testing extend transmission-ECU calibration validation timelines. The Stuttgart industrial corridor anchors wet-clutch dual-clutch development for European construction equipment specifications.
China
MIIT fuel consumption regulations tighten efficiency benchmarks for medium-duty freight vehicles operating between Yangtze River Delta manufacturing hubs. State transport corporations in Sichuan and Shandong provinces tender automated manual conversion kits for bus fleet modernization. Chongqing and Shanghai transmission manufacturing clusters scale automated production lines for domestic heavy-duty platforms.
India
State transport corporation tender volumes in Maharashtra and Karnataka drive aftermarket demand for automated manual retrofit kits compatible with existing axle ratios. BIS certification requirements for commercial vehicle component safety influence clutch actuator specification standards. The Chennai-Bangalore industrial corridor concentrates manual transmission production for price-sensitive construction vehicle segments.
Japan
METI technology roadmaps for commercial vehicle electrification guide integrated electric drive unit development for urban delivery applications. JIS standards for transmission durability testing shape quality benchmarks exported throughout Southeast Asian markets. The Nagoya industrial zone maintains precision gear machining capacity for compact multi-speed reduction gearboxes in battery-electric platforms.
Commercial Vehicle Transmission Market Competitive Landscape
Global majors compete with regional champions across electrified powertrain coupling standards and software-defined calibration capabilities. Market structure shows tiered consolidation with integrated mechatronics suppliers occupying premium positions and regional fabricators serving cost-sensitive emerging markets. Three archetypes dominate: full-system integrators with thermal management portfolios, specialized clutch-actuation developers, and scale-driven manual transmission producers. Competitive moves center on strategic partnerships for electrified platform compatibility and geographic expansion through CKD licensing arrangements.
Within the full-system integrator tier, ZF Friedrichshafen and Eaton Corporation represent European and North American anchoring positions for automated transmission supply. Allison Transmission exemplifies the purpose-built architecture specialist archetype in severe-duty applications. Among Asia-Pacific-based producers, Aisin Seiki and HYUNDAI TRANSYS occupy positions spanning manual through fully automatic portfolio breadth, while Chongqing Tsingshan and Zhejiang Wanliyang exemplify regional champions scaling domestic capacity for medium-duty specifications. Borgwarner represents the component-to-system transition archetype through power electronics integration capabilities.
| Leading Market Players |
|---|
| Allison Transmission |
| Aisin Seiki |
| ZF Friedrichshafen |
| Chongqing Tsingshan |
| SAIC |
| Eaton Corporation |
| HYUNDAI TRANSYS |
| Zhejiang Wanliyang |
| Borgwarner |
| Others |
Value Network & Pricing Analysis
Electric actuation architectures replacing hydraulic systems across new platform development simultaneously compress component costs and concentrate supplier relationships around certified mechatronics integrators. This dual transformation reshapes procurement economics as OEMs trade field serviceability for factory-sealed precision.
Pricing Analysis
Warranty and calibration-service bundling separates premium automated transmission suppliers from hardware-only vendors competing on unit cost. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 26262 ASIL-D certification status and predictive shift-software maturity. Pricing pressure stems from Chinese domestic producers scaling automated production lines for medium-duty specifications. Fleet operators exhibit highest price sensitivity in retrofit conversion kit procurement, while OEM platform engineering tolerates premium positioning for electrified powertrain compatibility.
Supply Chain Analysis
ISO 26262 functional safety certification gates access to autonomous truck pilot programs and European premium coach specifications, filtering supplier tiers. Manufacturing concentrates in China, Germany, and the United States, with permanent magnet materials drawing from Jiangxi Province processing facilities. Steel forgings, electronic control modules, and specialized lubricant additives constitute critical input dependencies. Single-source vulnerability sits with rare earth magnet supply concentration. Distribution runs through captive dealer networks equipped with specialized thermal management servicing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around electrified powertrain coupling standards as EPA Phase 3 and Euro VII timelines eliminate hardware-only suppliers lacking software-defined calibration capabilities.
For Market Incumbents: To counter Chinese domestic producers scaling automated production lines, deepen backward integration into permanent magnet material sourcing and secure ASIL-D certification for transmission control modules. Prioritize open-access calibration interfaces in OEM contracts to prevent fleet operator lock-in defection. For New Entrants and Emerging Players: The price-point gap between ZF Friedrichshafen premium positioning and Indian regional manual transmission producers creates white-space opportunity in automated manual conversion kits for state transport corporation tenders. Target Maharashtra and Karnataka bus fleet modernization programs with axle-ratio-compatible retrofit architectures. Pursue CKD licensing arrangements with technology transfer provisions to bypass capital-intensive greenfield manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-system integrators seeking electrified platform capabilities. Five-to-ten-year viability favors suppliers with demonstrated EPA Phase 3 and Euro VII calibration validation timelines. Target acquisition archetype: specialized clutch-actuation developers with embedded control algorithm expertise. Watch for inflection in fleet operator consolidation toward single-source transmission agreements covering full replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Opens premium positioning in autonomous truck pilot programs where shift-actuator fault tolerance is mandatory. |
| Backward Integration into Magnet Supply | Reduces exposure to Chinese rare earth processing volatility for hybrid powertrain bill-of-materials. |
| Open-Access Calibration Interface Development | Prevents fleet operator defection to competitors offering route-specific shift map customization. |
| CKD Licensing Arrangement Expansion | Enables technology transfer revenue from developing-market vehicle assemblers without capital-intensive manufacturing. |
| Integrated Thermal Management System Launch | Captures service margin from independent workshops into captive dealer networks for European premium coach OEMs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, fleet procurement directors, aftermarket service heads, and Tier 1 supplier technical leads. EPA Phase 3 regulatory dockets, Euro VII KBA type-approval documentation, MIIT fuel consumption filings, and NHTSA safety mandate records provided policy calibration benchmarks. Bottom-up vehicle production forecasts triangulated against top-down freight transport demand modeling.
Granularity-level modeling tracked transmission architecture by actuation mechanism, torque capacity rating, and electrification readiness across vehicle class and duty cycle intensity. Segmentation dimensions included product type, end-user procurement authority, application severity, and technology platform. CAGRs derived from fitted growth curves against historical adoption patterns for automated manual transmission penetration. Forecast inputs incorporated fleet operator replacement cycle timing and state transport corporation tender pipeline visibility.
Inputs from regulatory agencies and trade associations were available through the study window; gaps in real-time fleet operator procurement intention data introduce uncertainty bands around replacement cycle acceleration scenarios. Forecasts reflect documented assumptions regarding EPA Phase 3 compliance timeline adherence and rare earth magnet supply stability. A model refresh is warranted upon material change in Euro VII real-driving emission testing protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Spain Light Commercial Vehicles Market