
 Europe Light Commercial Vehicle (LCV) Market | 2026-2036
Europe Light Commercial Vehicle (LCV) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Light Commercial Vehicle (LCV) Market Insights
Urban logistics procurement is shifting toward zero-emission capable vans as municipal access rules tighten across European city centers. Renault Group leverages its Kangoo E-Tech platform to anchor electric van share in France and Benelux corridors. Stellantis N.V. sustains multi-brand production scale across Italy and Poland through shared underpinnings. Mercedes-Benz Group AG differentiates in the premium segment with advanced driver-assistance suites and modular battery architectures.
A light commercial vehicle is a motor vehicle with a gross vehicle weight rating between 3.5 and 7.5 tonnes, engineered for cargo transport or passenger carriage with a driver-focused cabin and flat-load or box-body rear configuration; diesel powertrains historically dominated European LCV fleets due to torque delivery and refueling infrastructure density. The fuel type segment shows electric variants capturing fleet renewal cycles as total cost of ownership parity approaches diesel benchmarks in high-utilization duty cycles. The payload capacity segment sees medium-duty configurations retaining margin strength in construction and trade applications where tool weight and material transport requirements resist downsizing.
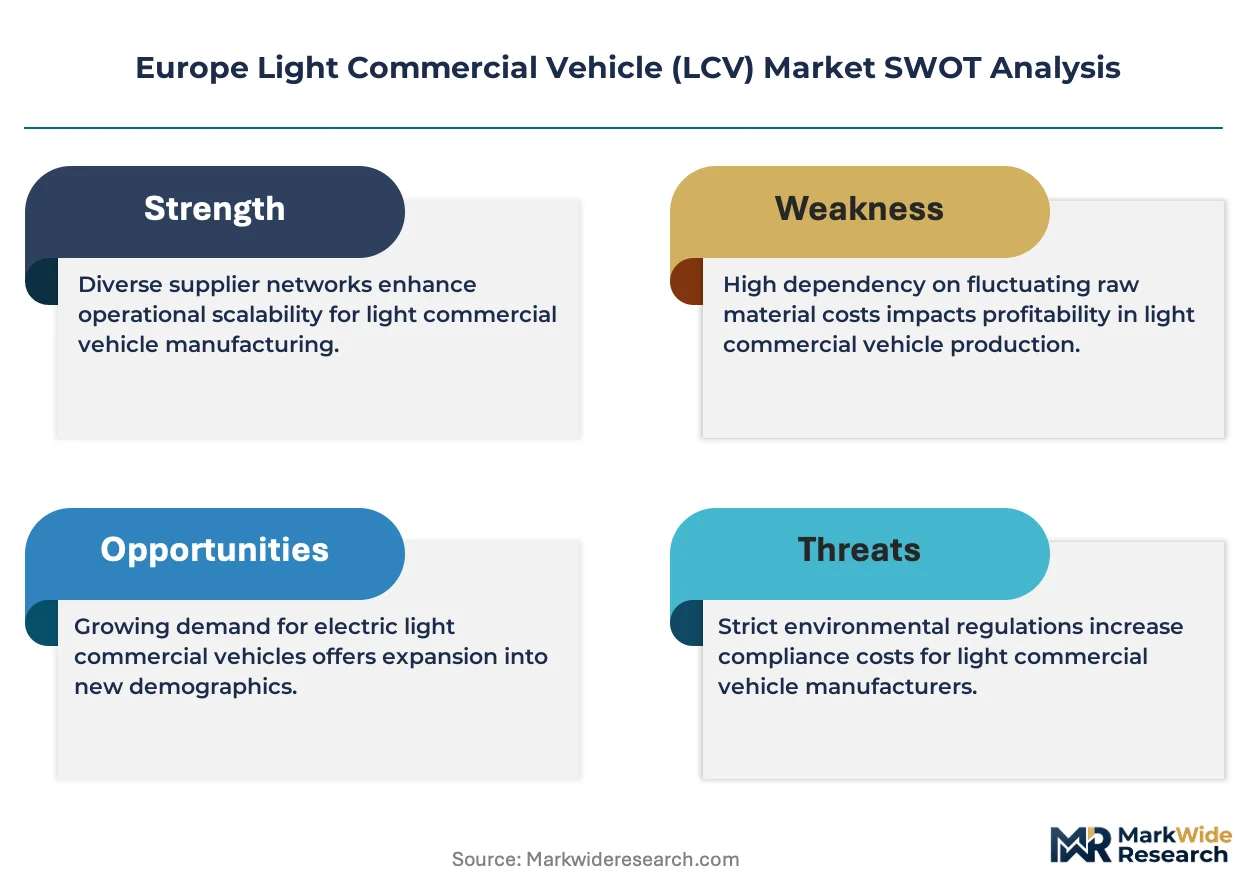
The EU Green Deal and Euro 7 standards from the European Commission are forcing powertrain diversification timelines shorter than previous regulatory cycles. ECHA chemical compliance and REACH material declarations add supply chain certification burdens for battery cell imports and recycled content claims. Fleet operators and manufacturers must monitor subsidy phase-out schedules and charging infrastructure build rates to synchronize electrification capex with operational readiness.
Market Dynamics
EU Green Deal mandates and Euro 7 emissions standards are compressing diesel powertrain timelines across European LCV fleets, forcing manufacturers to reconfigure production lines and supply chains before regulatory deadlines lock in.
Growth Catalysts
- Urban Low-Emission Zones:Municipal access restrictions in Paris, London, and Amsterdam are mandating zero-emission vehicle entry, pulling fleet operators toward electric van procurement.
- Total Cost of Ownership Parity:Battery electric vans in high-utilization last-mile delivery cycles now match diesel operating economics when factoring in fuel savings and maintenance reduction.
- EU Green Deal Investment Flows:The European Commission's sustainable mobility funding mechanisms are subsidizing charging infrastructure buildout and fleet electrification capex across member states.
Market Restraints
- Battery Cell Supply Concentration:European LCV manufacturers depend on Asian cell suppliers for lithium-ion packs, exposing production schedules to shipping bottlenecks and raw material price swings.
- Charging Infrastructure Gaps:Depot charging installation timelines and grid connection approvals in Germany and France lag behind fleet electrification procurement cycles.
- Euro 7 Compliance Costs:The European Commission's proposed emission limits for internal combustion engines are forcing costly after-treatment system redesigns with uncertain certification timelines.
Strategic Opportunities
- Eastern European Fleet Renewal:Poland and Romania's aging commercial van parc presents conversion potential as EU cohesion funds channel toward sustainable transport.
- Vehicle-to-Grid Integration:Bidirectional charging capabilities in electric LCVs open revenue streams from grid services in markets with dynamic electricity pricing.
- Modular Battery Architectures:Swappable and scalable battery packs enable payload-range trade-offs for construction and trade applications resisting full electrification.
Industry Challenges
- High-Voltage Technician Shortages:European service networks lack certified personnel for battery system diagnostics and repair, extending vehicle downtime.
- REACH Compliance Complexity:ECHA chemical reporting requirements for battery materials and recycled content claims add documentation burdens across multi-tier supply chains.
- Legacy Fleet Integration:Mixed diesel-electric operations complicate route optimization software and driver training programs for diversified national fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Light Commercial Vehicle (LCV) Market |
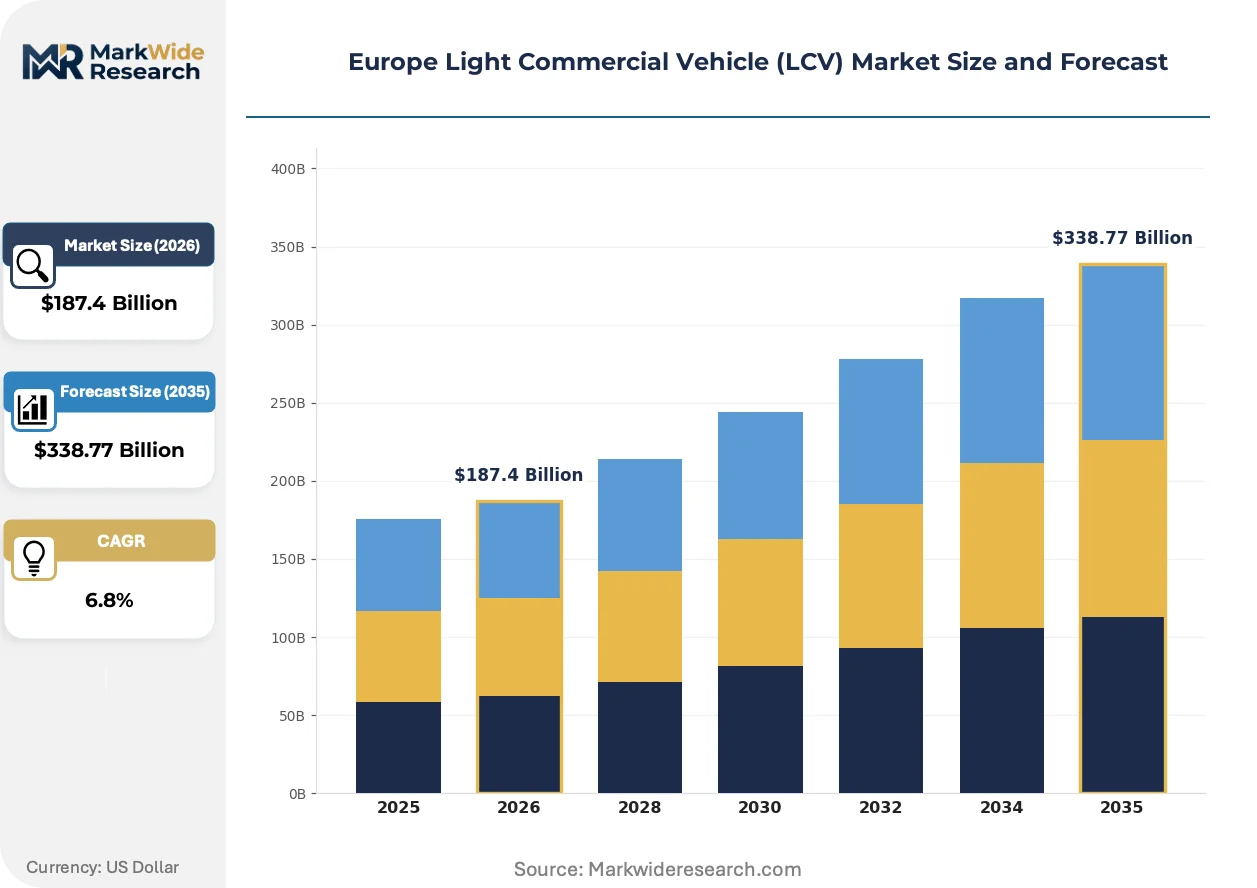
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Van, Minibus, Pickup Truck, Chassis Cab Fuel Type: Diesel, Electric, Gasoline, Hybrid Payload Capacity: Light, Medium, Heavy, Ultra Light End User: Retail, Logistics, Construction, Delivery Services |
| Companies Covered | Renault Group, Toyota Motor Corporation, Stellantis N.V., Nissan Motor Co. Ltd., Iveco Group N.V., Volkswagen AG, Mercedes-Benz Group AG, Volvo Group, Ford Motor Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Light Commercial Vehicle (LCV) Market Trends and Innovations
Powertrain electrification is restructuring European LCV competitive dynamics, with software-defined vehicle architectures and energy management systems emerging as differentiation vectors beyond hardware specifications.
Modular skateboard platforms are consolidating electric van development economics across Stellantis and Renault Group production networks. Shared underpinnings spanning cargo vans, passenger shuttles, and chassis cab variants reduce engineering overhead per model. This consolidation is compressing variant proliferation while enabling faster regional specification adjustments.
REACH and EU Green Deal reporting requirements are mandating supply chain transparency for battery cell provenance and carbon footprint declarations. Manufacturers must document recycled content percentages and responsible mining certifications for lithium, cobalt, and nickel inputs. The Benelux corridor's municipal procurement rules now embed these declarations as mandatory bid criteria.
Fleet operators are unbundling vehicle acquisition from energy and maintenance services, favoring full-service leasing with guaranteed uptime clauses over traditional ownership. Logistics providers in the Netherlands and Germany are contracting total mobility solutions where manufacturers assume residual value risk and charging infrastructure responsibility. This shift concentrates purchasing power with large fleet management companies and squeezes independent dealer margins.
Europe Light Commercial Vehicle (LCV) Market Segmentation
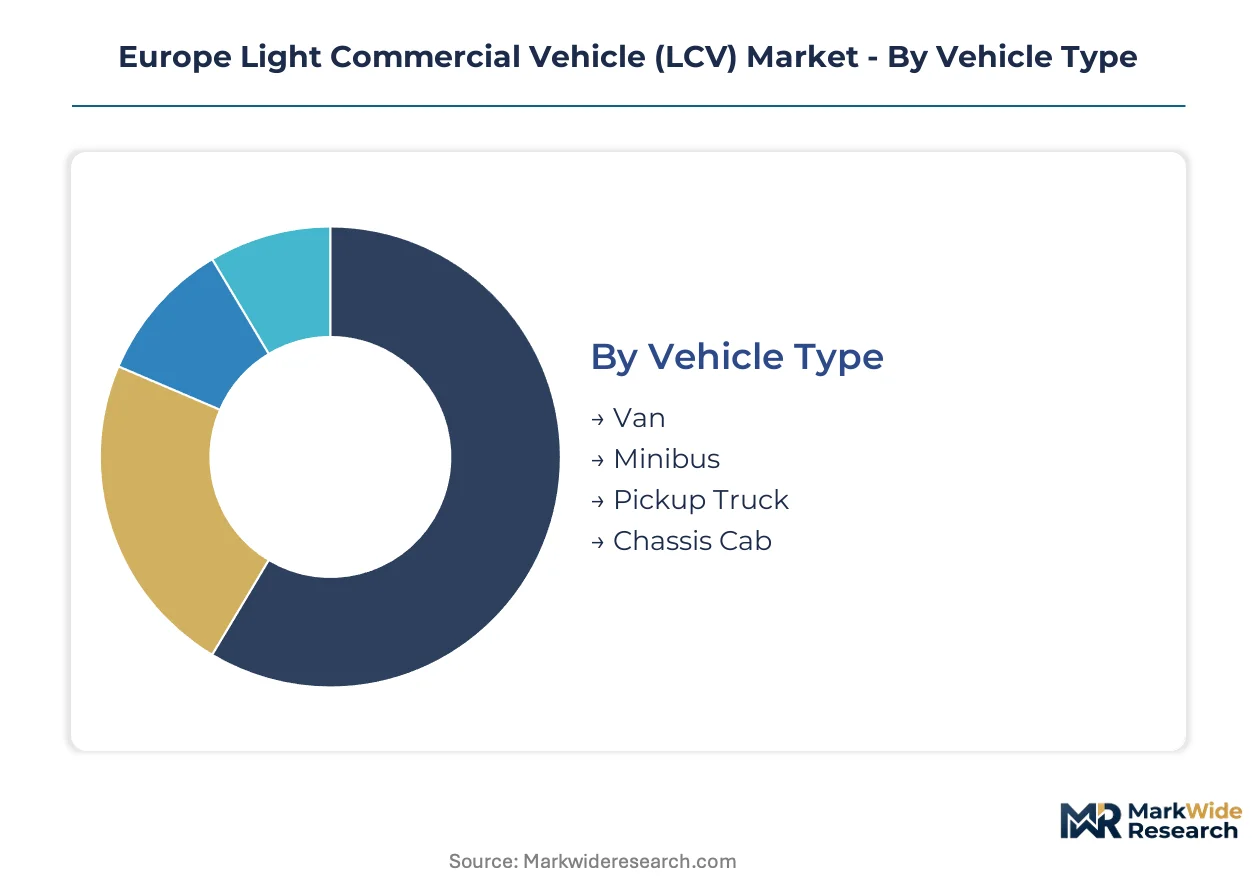
Segmentation in the Europe LCV market reveals how regulatory pressure and duty-cycle economics split procurement decisions across fleet operators. Understanding these divides exposes where electrification capex concentrates and where diesel retention persists.
Vehicle Type:
Volume concentration sits with urban delivery formats, while premium margins attach to specialized configurations serving trade and passenger sectors.
- Van:Box-bodied configurations dominate last-mile logistics across German and Dutch urban corridors. Parcel carriers in Rotterdam and Berlin are electrifying these fleets fastest as municipal low-emission zones harden entry rules.
- Minibus:Passenger-carrying derivatives serve hotel shuttles and rural transit concessions. French regional operators favor these for routes where rail connectivity gaps persist in Brittany and Normandy.
- Pickup Truck:Open-bed configurations retain diesel loyalty in Polish and Romanian construction markets where terrain resistance and towing demands resist battery range compromises.
- Chassis Cab:Bare-frame platforms enable aftermarket bodybuilder specialization for refrigerated and tipper applications. Italian refrigeration specialists in Emilia-Romagna customize these for fresh produce distribution.
Today's leader: Van. Tomorrow's challenger: Chassis Cab.
Fuel Type:
Cost tier stratification separates legacy powertrains from emerging alternatives, with subsidy eligibility and TCO horizons determining fleet commitment timing.
- Diesel:Compression-ignition engines retain installed base dominance in high-mileage interstate haulage. Euro 7 compliance costs from the European Commission are compressing production timelines for these powertrains.
- Electric:Battery-electric vans match diesel operating economics in high-utilization urban cycles. Benelux logistics providers are contracting these through full-service leases with guaranteed uptime clauses.
- Gasoline:Spark-ignition variants serve low-mileage owner-operators in Southern Europe where fuel price differentials favor lighter duty cycles.
- Hybrid:Dual-powertrain configurations bridge range anxiety for mixed urban-interstate operations. German mid-size fleets trial these where charging infrastructure gaps persist in Eastern federal states.
Electric configurations are gaining share fastest where grid connection approvals synchronize with fleet renewal cycles.
Payload Capacity:
Application-driven segmentation shows construction and trade demand resisting downsizing where tool weight and material density mandate structural capacity.
- Light:Sub-1.5-tonne ratings serve florist and courier trades with frequent stop-start patterns. Parisian artisan fleets favor these for narrow street access in historic districts.
- Medium:Mid-range ratings retain margin strength in HVAC and electrical contractor segments. Dutch installation firms specify these for equipment transport between Rotterdam and The Hague corridors.
- Heavy:Upper-range capacities serve building material distributors where aggregate weight resists electrification. Polish construction supply chains depend on these for rural site deliveries.
- Ultra Light:Compact ratings address micromobility substitution and urban parking constraints. Lisbon and Barcelona last-mile operators deploy these for dense historic center penetration.
Medium capacity holds the revenue core. Heavy capacity faces the steepest electrification headwinds.
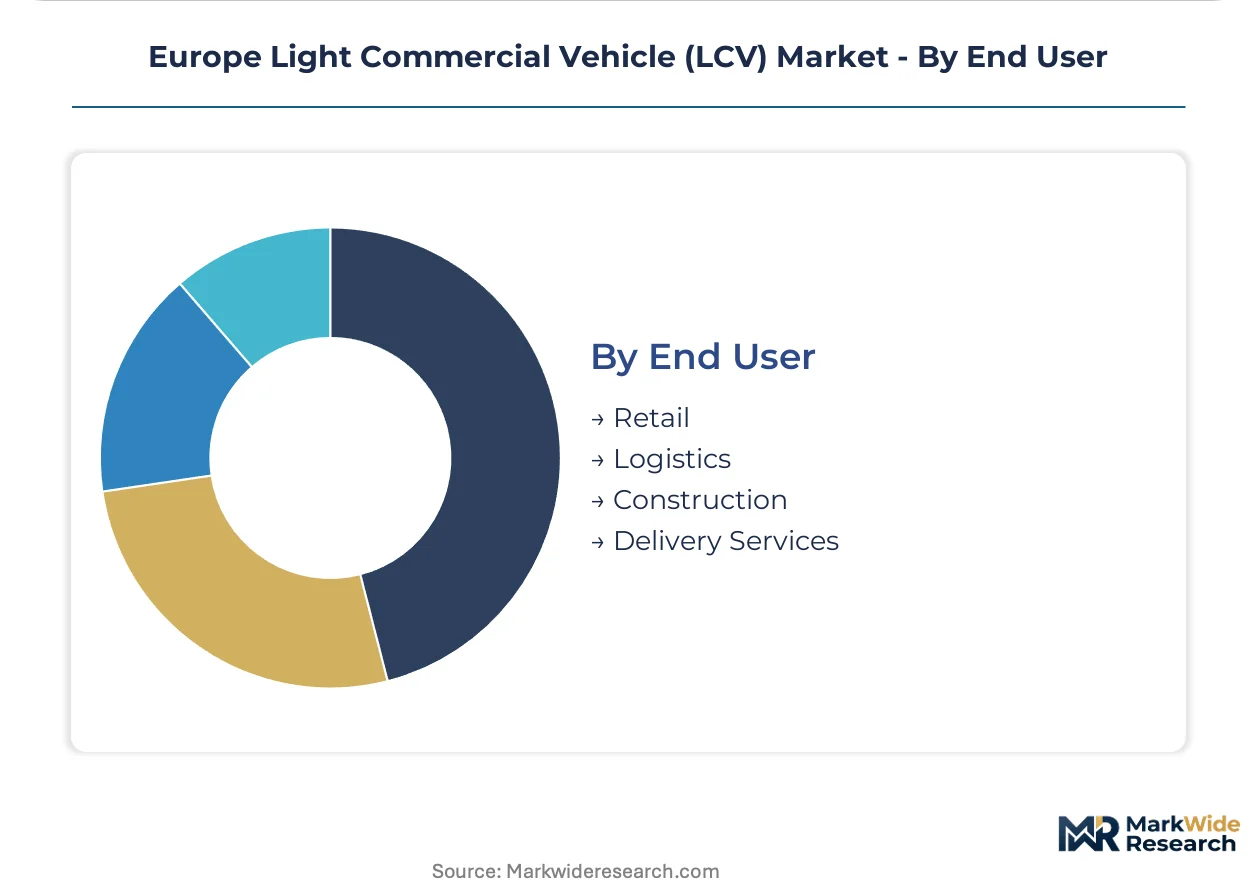
End User:
Customer-type concentration determines contract structure, with logistics providers unbundling ownership from energy services while trade operators retain traditional purchase patterns.
- Logistics:Parcel and freight operators drive fleet-scale electrification through manufacturer partnerships. DHL and DPD contracting models in Germany shift residual value risk to OEMs.
- Delivery Services:Food and grocery platforms prioritize vehicle availability over specification flexibility. British quick-commerce startups specify these through short-term rental pools.
- Construction:Building trades demand durability and payload certainty over technology novelty. French masonry and roofing cooperatives in Occitanie retain diesel loyalty for site access reliability.
- Retail:Branded fleet operators balance corporate sustainability targets with branch-level autonomy. IKEA and Leroy Merlin operations in France and Belgium electrify urban delivery while maintaining diesel for ex-urban stores.
Logistics commands procurement scale. Construction maintains technology inertia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European LCV production capacity and fleet electrification velocity. National regulatory frameworks and municipal access rules fragment procurement patterns across member states. Industrial clustering concentrates battery assembly and powertrain engineering in specific sub-regional corridors.
Germany
DHL and Deutsche Post electrify last-mile depots in Berlin and Hamburg under fleet-scale contracts. The KBA enforces Euro 7 certification timelines that compress diesel production schedules. Bavaria's Munich-Stuttgart corridor hosts Mercedes-Benz Group AG and Volkswagen AG engineering centers developing modular electric platforms.
France
Renault Group dominates domestic electric van share through Kangoo E-Tech deployments with La Poste and Chronopost. The EU Green Deal channels recovery funding toward charging infrastructure in Île-de-France logistics zones. The Auvergne-Rhône-Alpes cluster around Lyon specializes in hydrogen fuel cell conversions for heavy-duty chassis cab variants.
Netherlands
Amsterdam and Rotterdam municipal zero-emission zones mandate electric van entry for parcel carriers from 2025. ANSM chemical compliance rules govern battery recycling facility permits at Moerdijk port complexes. Dutch fleet operators contract full-service leases with guaranteed uptime clauses through Randstad financial services hubs.
Italy
Stellantis N.V. sustains multi-brand production scale at Pomigliano d'Arco and Melfi plants through shared electric underpinnings. Italian refrigeration specialists in Emilia-Romagna customize chassis cab platforms for fresh produce distribution. Southern European trade operators retain diesel loyalty where charging infrastructure gaps persist in Calabria and Sicily corridors.
Poland
Aging commercial van parc in Warsaw and Kraków corridors presents conversion potential as EU cohesion funds channel toward sustainable transport. Polish construction supply chains depend on heavy payload diesel configurations for rural site deliveries. The Silesian industrial basin attracts battery cell assembly investments serving Eastern European fleet renewal cycles.
Europe Light Commercial Vehicle (LCV) Market Competitive Landscape
Platform consolidation dominates the current landscape as manufacturers compress engineering overhead through shared electric architectures. The vendor structure concentrates around three legacy automotive groups with integrated powertrain capabilities and two emerging specialists in commercial vehicle electrification. Strategic archetypes separate scale-driven full-line producers, premium technology differentiators, and regional fleet service integrators. M&A activity and strategic partnerships constitute the dominant competitive moves as firms secure battery supply agreements and charging network access.
Among European-based automotive groups, Renault Group, Stellantis N.V., and Mercedes-Benz Group AG occupy distinct positioning tiers. Renault Group exemplifies the volume-focused electric van specialist with established last-mile logistics partnerships. Stellantis N.V. represents the multi-brand scale archetype leveraging shared underpinnings across cargo van, passenger shuttle, and chassis cab variants. Mercedes-Benz Group AG anchors the premium tier through advanced driver-assistance integration and modular battery architectures serving high-visibility fleet operators.
| Leading Market Players |
|---|
| Renault Group |
| Toyota Motor Corporation |
| Stellantis N.V. |
| Nissan Motor Co. Ltd. |
| Iveco Group N.V. |
| Volkswagen AG |
| Mercedes-Benz Group AG |
| Volvo Group |
| Ford Motor Company |
| Others |
Pricing and Supply Chain Analysis
Skateboard platform standardization across Stellantis and Renault Group production networks compresses per-unit engineering costs while concentrating battery procurement leverage with Asian cell suppliers. This manufacturing transition simultaneously flattens variant pricing tiers and exposes European LCV builders to lithium-ion supply bottlenecks from South Korean and Chinese producers.
Pricing Analysis
Input-cost pass-through from lithium, cobalt, and nickel price volatility dominates pricing dynamics for electric van configurations. Three-tier pricing structure across premium, standard, and economy levels separates Mercedes-Benz driver-assistance suites from Renault volume platforms and Stellantis multi-brand entries. Price differentiation hinges on battery capacity grades and after-sales service bundling. Pricing pressure stems from Euro 7 compliance costs for residual diesel production compressing margins in legacy powertrains. Fleet operators in the Netherlands exhibit highest price sensitivity through full-service lease negotiations, while German premium logistics providers absorb specification premiums for uptime guarantees.
Supply Chain Analysis
EU Green Deal local-content mandates and REACH recycled-content declarations are reshaping sourcing decisions for battery cell provenance documentation. European LCV manufacturing draws from South Korea, China, and Japan for lithium-ion cell supply, with Poland and Hungary emerging as pack assembly locations. Raw material dependencies center on Chilean lithium, Indonesian nickel, and DRC cobalt supply chains. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through Randstad financial services hubs for Dutch fleet leasing, German OEM captive finance arms, and French postal service procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe LCV market functions as a stable compounder anchored by regulatory-mandated fleet renewal cycles that synchronize with municipal zero-emission zone implementation.
For Market Incumbents: Acquire battery cell supply commitments through long-term offtake agreements with South Korean producers to lock in cathode material access ahead of EU Green Deal content requirements. Secure charging infrastructure partnerships with Dutch grid operators to embed guaranteed uptime clauses in fleet service contracts. Defend against emerging Chinese electric van entrants by accelerating modular platform rollouts across Italian and Polish production hubs. Prioritize certification investment in ECHA REACH documentation systems to streamline recycled-content claims for Benelux municipal procurement. For New Entrants and Emerging Players: Capture Eastern European fleet renewal cycles in Poland and Romania where EU cohesion funds subsidize sustainable transport conversions and incumbent service networks remain underdeveloped. Target chassis cab electrification for Italian refrigeration bodybuilders seeking zero-emission fresh produce distribution solutions. Penetrate through vehicle-to-grid integration software that unlocks grid services revenue for Dutch logistics operators with dynamic electricity pricing exposure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier battery pack assemblers with Polish manufacturing footprints and established OEM qualification pathways. Long-term viability across the analysis window rests on regulatory durability of municipal low-emission zones and charging infrastructure buildout velocity. Target acquisition archetype: Tier 2 power electronics specialists with high-voltage inverter capabilities serving Stellantis and Renault Group platform sharing. Watch subsidy phase-out schedules in Germany and France as the inflection signal for fleet electrification capex synchronization.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium-ion cell access for Renault Group Kangoo E-Tech scale production. |
| Platform Standardization | Enables Stellantis shared underpinnings across cargo van and chassis cab variants. |
| Charging Infrastructure Partnership | Secures grid connection priority for DHL depot electrification in Berlin corridors. |
| Software-Defined Vehicle Investment | Differentiates Mercedes-Benz driver-assistance suites in premium fleet segments. |
| Geographic Manufacturing Footprint | Positions Polish assembly hubs for Eastern European EU cohesion fund access. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet management company operations directors, and municipal transport authority planners grounded this analysis in operational reality. Secondary validation drew from KBA vehicle registration databases, European Commission Euro 7 regulatory filings, IHS Markit production forecasts, and ECHA REACH substance registration data. Bottom-up and top-down triangulation cross-checked segment assumptions against national fleet parc renewal rates and charging infrastructure deployment timelines.
Bottom-up modeling built from individual country-level fleet procurement patterns and powertrain mix trajectories, while top-down constraints applied EU Green Deal investment flow assumptions and Euro 7 compliance cost estimates across the projection horizon. Segmentation dimensions included vehicle type, fuel architecture, payload capacity tier, and end-user procurement structure. CAGRs derived from logistic curve adoption modeling for electric van penetration rates, calibrated to municipal low-emission zone implementation schedules and total cost of ownership parity thresholds.
Battery cell supply disruptions, Euro 7 certification timeline delays, and charging infrastructure grid connection bottlenecks are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market