
 Waste or Garbage Collection Vehicle Market | 2026-2036
Waste or Garbage Collection Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Waste or Garbage Collection Vehicle Market Outlook
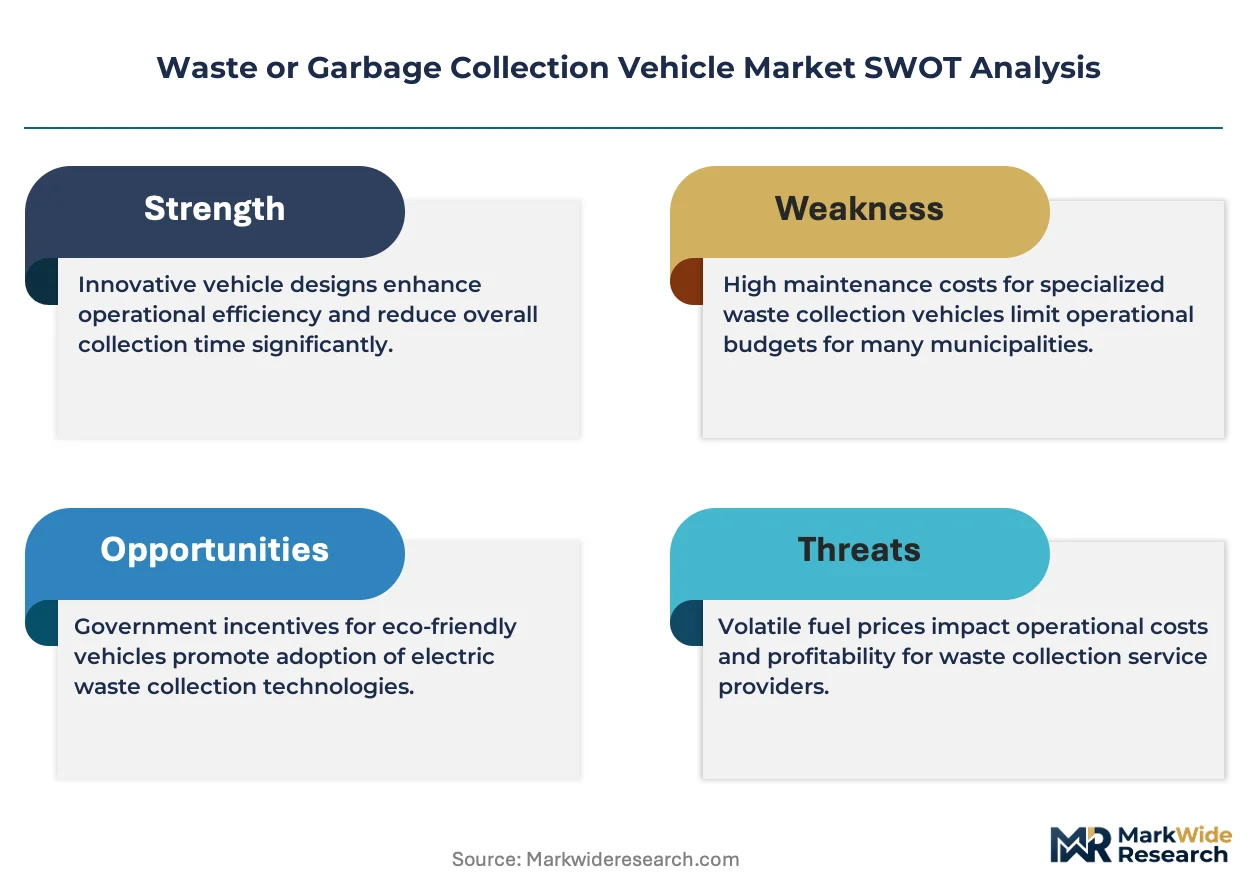
The EU Green Deal is expanding procurement requirements for zero-emission municipal fleets across member states. Scania AB leverages its modular electric chassis architecture to compete in Nordic and Central European tenders. Heil Co. anchors North American demand through its refuse body specialization and dealer network density. Volvo Trucks Corporation differentiates via integrated telematics and connected fleet management systems.
Waste or garbage collection vehicles are purpose-built trucks designed to transport municipal solid waste from collection points to disposal or processing facilities, typically incorporating compaction mechanisms with payload capacities ranging from 10 to 32 cubic yards and hydraulic lift systems for automated bin handling. Rear-loading configurations dominate mature urban markets where manual collection persists, while automated side-loading units capture margin pools in suburban municipalities seeking labor reduction. Electric fuel type segments accelerate fastest where overnight depot charging infrastructure exists, though heavy-duty routes still rely on compressed natural gas in regions with established biomethane supply chains.
EPA emissions standards in the United States, EU F-Gas Regulation governing refrigerants in cab climate systems, and REACH compliance for material composition collectively elevate engineering costs and certification timelines for manufacturers. Municipal buyers increasingly embed ESG scoring into procurement evaluation, favoring suppliers with documented lifecycle carbon assessments. Fleet operators must monitor battery degradation warranties and residual value guarantees as electrification commitments extend across multiple budget cycles.
Market Dynamics
Fleet electrification is compressing diesel powertrain demand as municipal sanitation departments face binding EU Green Deal mandates and parallel EPA emissions tightening. Battery-electric chassis integration is reshaping procurement specifications, depot infrastructure requirements, and residual value calculations across urban route applications.
Growth Catalysts
- EU Green Deal procurement mandates:Binding zero-emission fleet targets for municipal sanitation departments in Germany, France, and the Netherlands are accelerating tender specifications for battery-electric refuse vehicles.
- Biomethane corridor development:Compressed natural gas powertrains capture heavy-duty rural routes in Sweden and Italy where anaerobic digestion infrastructure supplies renewable fuel at scale.
- Automated side-loading technology:Labor cost pressures in suburban US municipalities are displacing rear-loading configurations with single-operator automated lift systems.
Market Restraints
- Battery cell supply concentration:Lithium-ion cathode production concentrates in China, exposing European and North American chassis manufacturers to raw material price volatility and export licensing risk.
- Depot charging infrastructure capex:Grid upgrade requirements for overnight fleet charging impose capital burdens on municipal budgets that diesel refueling never required.
- F-Gas Regulation compliance friction:EU-mandated refrigerant phase-down in cab climate systems forces redesign cycles and certification delays for body builders serving Nordic markets.
Strategic Opportunities
- India urban municipal expansion:Smart Cities Mission funding is creating tender pipelines for compact electric refuse vehicles in Bangalore, Pune, and Ahmedabad where narrow street grids favor small-footprint chassis.
- Telematics-as-a-service convergence:Fleet management platforms integrating route optimization with predictive maintenance are opening recurring revenue streams for chassis OEMs.
- US Inflation Reduction Act commercial vehicle credits:Federal tax incentives for battery-electric trucks are expanding addressable demand beyond municipal fleets into private waste haulers.
Industry Challenges
- Battery degradation warranty modeling:Fleet operators lack standardized protocols for assessing residual capacity in second-life applications, complicating multi-cycle procurement planning.
- Legacy hydraulic system integration:Electric chassis architectures require redesigned power take-off units for refuse body compaction mechanisms, extending engineering validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste or Garbage Collection Vehicle Market |
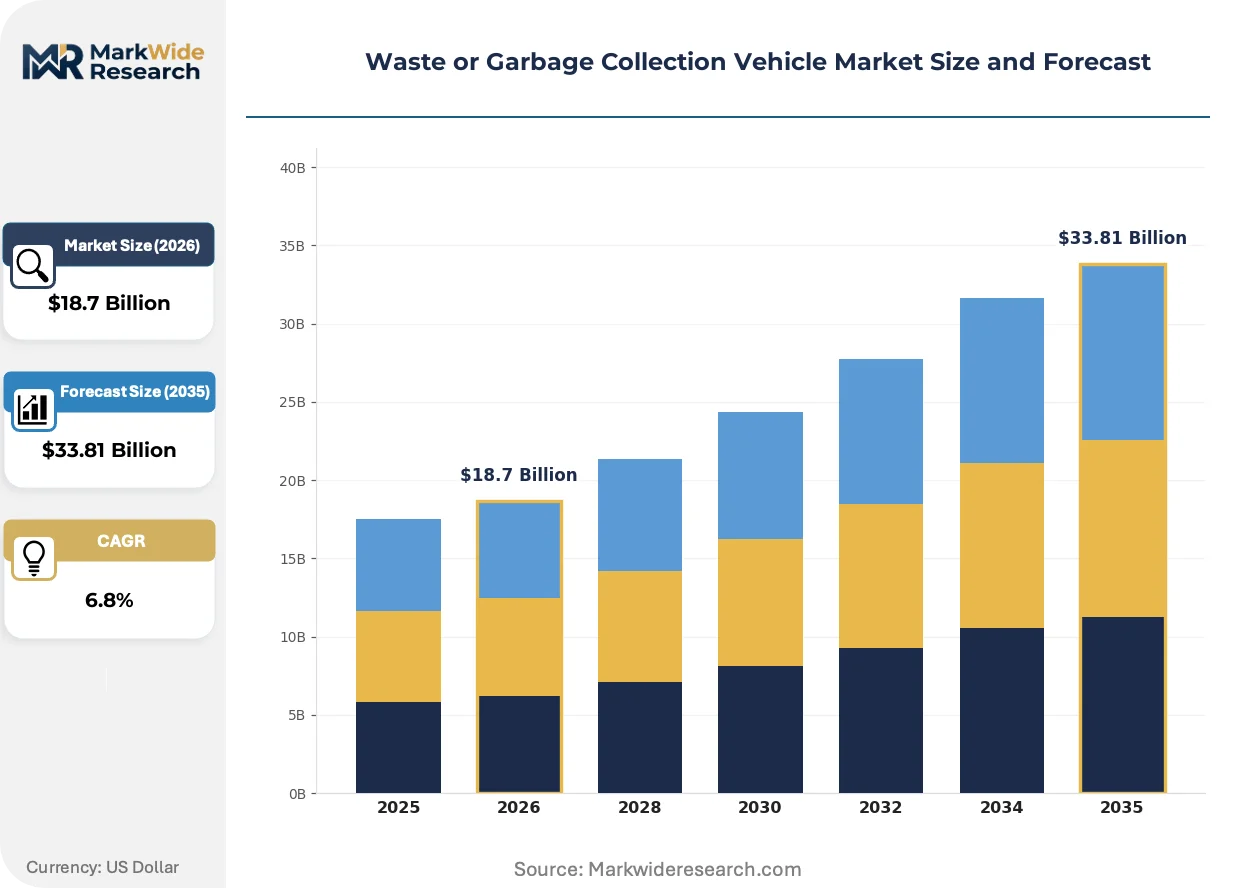
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Rear-Loading, Front-Loading, Side-Loading, Automated Fuel Type: Diesel, CNG, Electric, Hybrid Size: Light-Duty, Medium-Duty, Heavy-Duty, Super Duty End User: Municipalities, Private Contractors, Waste Management Firms, Government Agencies |
| Companies Covered | Scania AB, Heil Co., Volvo Trucks Corporation, New Way Trucks, McNeilus Companies, Daimler Truck AG, Mack Trucks Inc., Dongfeng Motor Corporation, Iveco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste or Garbage Collection Vehicle Market Strategic Shifts
Digitalization of fleet operations is converging with powertrain electrification to redefine competitive advantage. Municipal buyers now evaluate total cost of ownership across energy, maintenance, and data analytics rather than upfront chassis price alone.
Regenerative braking systems are integrating with route topography data to extend effective range in hilly urban environments. San Francisco and Lisbon municipal fleets are adopting predictive gradient mapping to optimize energy recovery on descent segments. This technology is integrating dynamic range estimation into dispatch software, compressing the operational penalty of battery-electric configurations versus diesel baseline.
REACH compliance for material composition is forcing substitution of legacy hydraulic fluids and cab interior plastics. ECHA substance restriction timelines are accelerating reformulation programs for seal compounds and wire insulation. Heavy-duty compaction mechanisms face the tightest certification windows, with German and Austrian body builders advancing bio-based hydraulic alternatives ahead of 2026 evaluation deadlines.
Lifecycle service contracting is displacing transactional chassis sales in Nordic municipal procurement. Copenhagen and Oslo sanitation departments now specify performance-based agreements covering energy, maintenance, and residual value risk. Dutch fleet operators pioneered this structure, and the model is propagating through Belgian and Danish tender templates as budget certainty outweighs capital ownership preferences.
Waste or Garbage Collection Vehicle Market Segmentation
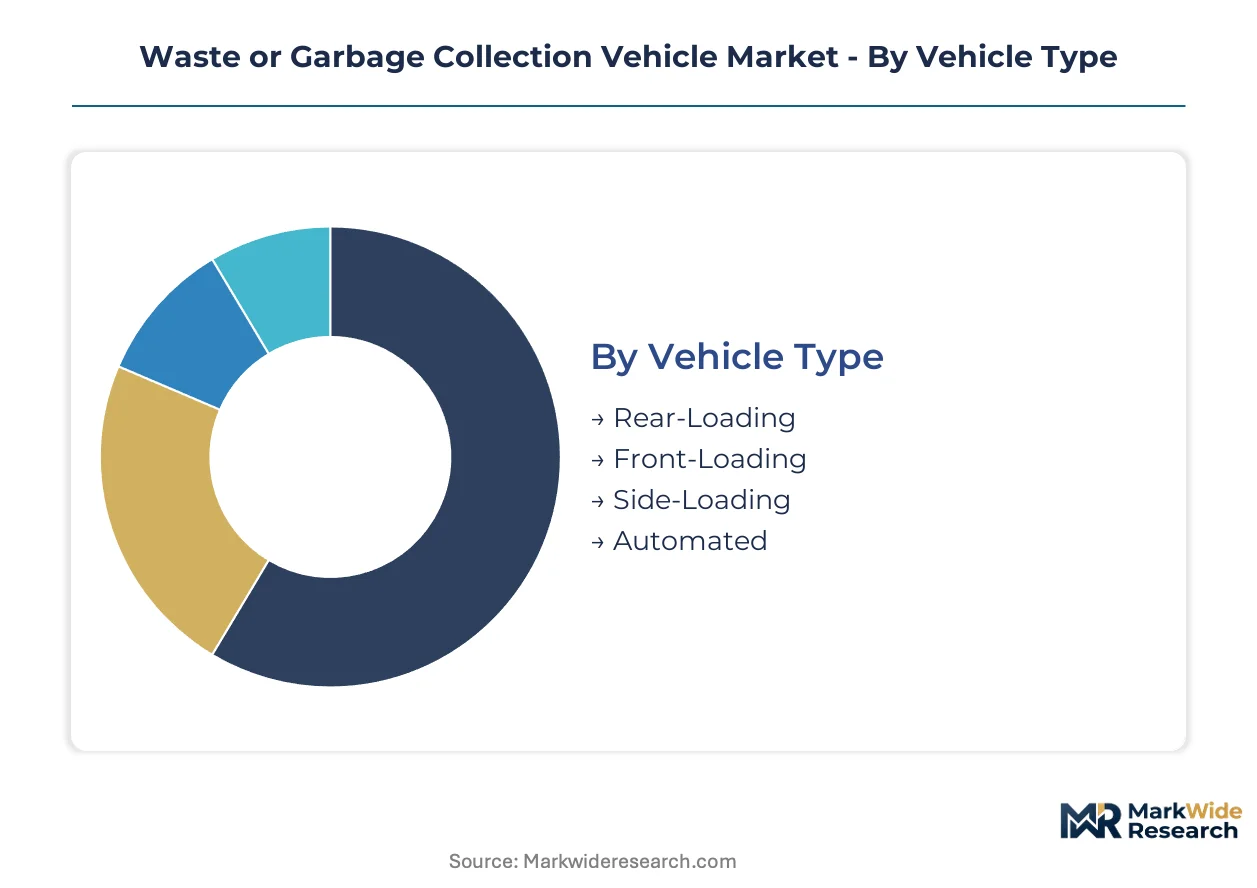
Segmentation in waste collection vehicles determines procurement specifications, infrastructure requirements, and total cost of ownership calculations. Municipal buyers prioritize payload capacity and route compatibility over upfront chassis price. Powertrain selection now dictates depot investment, maintenance protocols, and residual value risk across multi-year fleet cycles.
Vehicle Type:
Mechanical loading configurations define crew requirements, compaction density, and street accessibility for municipal sanitation departments.
- Rear-Loading:Manual bag or bin tipping into hopper openings at vehicle rear dominates dense urban cores where narrow alleys and parked cars restrict automated equipment deployment. Copenhagen and Berlin municipal fleets specify rear-loading units for historic districts with cobblestone constraints and weight-restricted bridges.
- Front-Loading:Hydraulic arms lift commercial dumpsters over cab roofs, concentrating demand among private waste haulers serving retail parks and industrial estates. US Sun Belt municipalities favor front-loading configurations for commercial route consolidation where single-operator efficiency offsets higher chassis cost.
- Side-Loading:Curbside bin grab mechanisms enable one-person collection crews, penetrating suburban municipalities facing labor shortage pressures.
- Automated:Robotic arm systems with RFID bin identification optimize pickup sequencing and contamination tracking in premium municipal contracts.
Rear-loading leads on scale; automated leads on momentum.
Fuel Type:
Powertrain selection hinges on route distance, depot infrastructure, and regulatory compliance timelines across municipal procurement cycles.
- Electric:Battery-electric chassis with overnight depot charging displace diesel in urban routes under EU Green Deal mandates and EPA emissions tightening. Oslo and Amsterdam sanitation departments have completed full fleet conversions, while California Air Resources Board rules accelerate California municipal adoption.
- CNG:Compressed natural gas powertrains capture heavy-duty rural routes in Sweden and Italy where anaerobic digestion infrastructure supplies renewable biomethane at scale.
- Diesel:Legacy powertrain retains residual demand in emerging markets and remote municipalities lacking grid capacity for fleet electrification.
- Hybrid:Dual-power architectures bridge infrastructure gaps where partial electrification supports stop-start urban duty cycles without full depot overhaul.
Electric climbs the fastest; diesel retains installed base dominance.
Size:
Payload classification determines chassis specification, compaction mechanism sizing, and street weight limit compliance.
- Heavy-Duty:25-32 cubic yard compaction bodies with reinforced frames serve high-volume commercial corridors and transfer station shuttles. German and French waste authorities specify heavy-duty units for metropolitan regional hubs where route consolidation maximizes tonnage per labor hour.
- Medium-Duty:16-24 cubic yard configurations balance maneuverability with payload for typical municipal residential routes.
- Light-Duty:Compact 10-15 cubic yard chassis penetrate historic city centers and narrow street grids where turning radius and axle weight restrictions apply.
- Super Duty:Specialized high-capacity variants exceed standard heavy-duty ratings for landfill direct-haul and industrial waste applications.
Heavy-duty leads on scale; light-duty leads on momentum.
End User:
Procurement authority and budget structure differentiate municipal from commercial fleet specifications and contract terms.
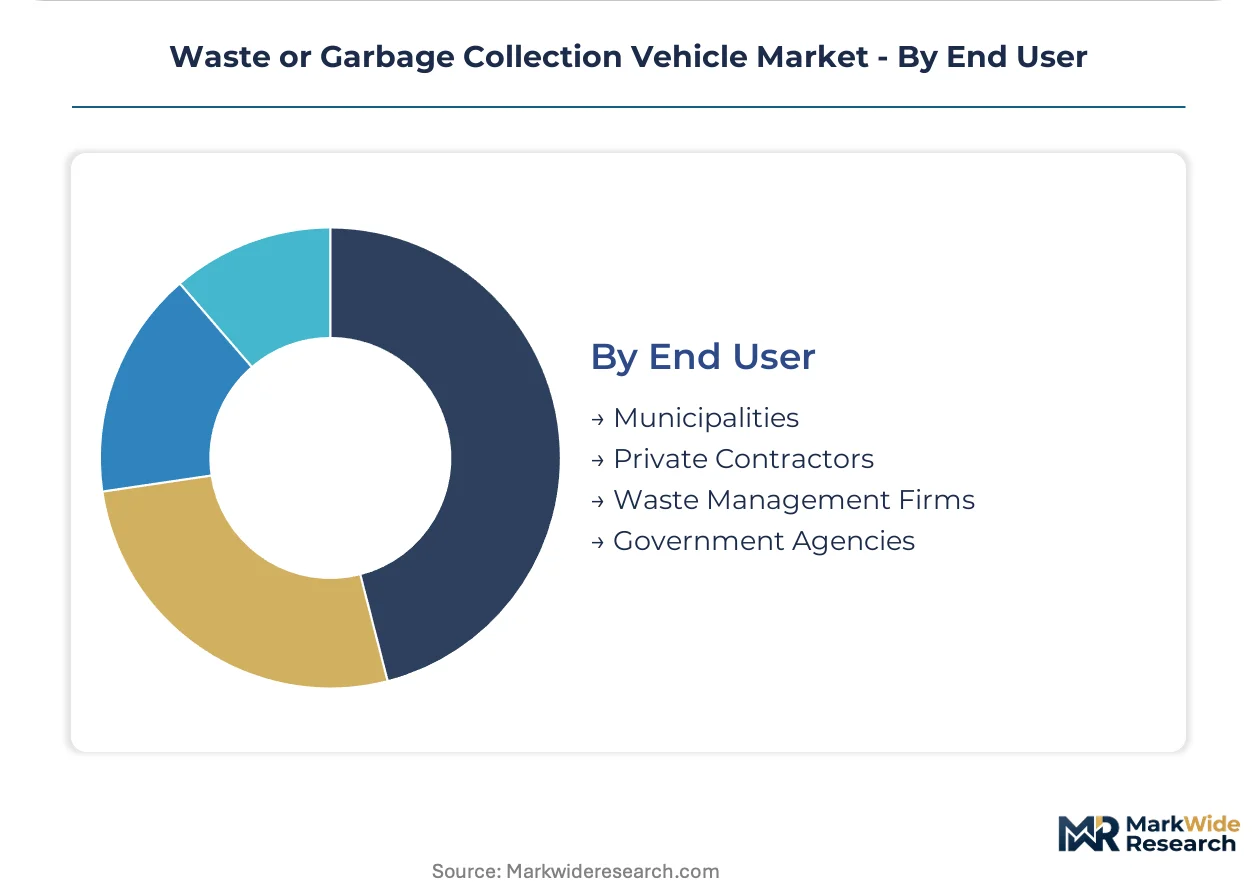
- Municipalities:City and county sanitation departments with multi-year capital budgets prioritize total cost of ownership and ESG compliance scoring. Dutch and Danish municipal procurement templates now embed performance-based service contracting with energy and maintenance risk transfer to suppliers.
- Private Contractors:Commercial waste haulers optimize asset utilization across diversified customer portfolios with shorter payback horizons.
- Waste Management Firms:Integrated environmental services companies specify standardized fleet architectures for cross-regional maintenance efficiency.
- Government Agencies:Federal, state, and provincial entities with specialized mandates operate smaller fleets for institutional and defense facility servicing.
Municipalities lead on scale; private contractors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered mechanized waste collection vehicle production during post-war municipal modernization. The industry subsequently diffused through Nordic environmental policy leadership and North American urban density patterns. Current procurement concentrates where regulatory mandates intersect with established manufacturing ecosystems.
Germany
Municipal fleet electrification tenders dominate demand as sanitation departments replace diesel chassis under EU Green Deal binding targets. The KBA enforces type-approval standards for electric commercial vehicles that compress certification timelines. Manufacturing clusters in Bavaria and Baden-Württemberg host body builders integrating battery-electric powertrains from Scania AB and Daimler Truck AG.
United States
Private waste haulers and municipal departments split procurement between automated side-loading units and conventional rear-loading configurations. EPA emissions tightening and California Air Resources Board zero-emission mandates accelerate battery-electric adoption in coastal states. McNeilus Companies and Heil Co. anchor production in the Midwest, serving Sun Belt municipalities with labor-saving automated lift systems.
China
Urban municipal expansion under Smart Cities Mission funding creates tender pipelines for compact electric refuse vehicles. MIIT national standards for new energy commercial vehicles shape chassis specifications. Dongfeng Motor Corporation leverages manufacturing scale in Wuhan to supply narrow-street configurations for historic districts in Hangzhou and Suzhou.
Sweden
Biomethane corridor infrastructure supports compressed natural gas powertrains for heavy-duty rural routes connecting anaerobic digestion facilities. The Swedish Transport Agency administers fleet conversion subsidies that favor renewable fuel pathways. Scania AB integrates CNG and electric variants from its Södertälje engineering center, serving Nordic municipal consortia with lifecycle service contracting.
India
Smart Cities Mission funding channels capital toward compact electric refuse vehicles in dense urban cores with narrow street grids. The Ministry of Housing and Urban Affairs sets procurement guidelines favoring domestic chassis assembly. Bangalore and Pune municipal corporations issue tenders specifying small-footprint configurations suited to informal settlement access constraints.
Waste or Garbage Collection Vehicle Market Competitive Environment
Capital-heavy chassis manufacturers compete with specialized body builders for control of refuse vehicle value chains. The market structures around three tiers: integrated OEMs with electric platform architectures, dedicated refuse body specialists with dealer network density, and regional fabricators serving price-sensitive emerging markets. Strategic moves concentrate on telematics integration for recurring revenue and lifecycle service contracting to transfer residual value risk.
Within the integrated OEM tier, Scania AB and Volvo Trucks Corporation occupy positions defined by modular electric chassis platforms and connected fleet management systems. Heil Co. exemplifies the refuse body specialist archetype, anchoring North American demand through dealer network coverage and compaction mechanism engineering. Dongfeng Motor Corporation represents scale-driven regional fabrication, leveraging domestic supply chain proximity for cost-positioned municipal tenders in Asia-Pacific markets.
| Leading Market Players |
|---|
| Scania AB |
| Heil Co. |
| Volvo Trucks Corporation |
| New Way Trucks |
| McNeilus Companies |
| Daimler Truck AG |
| Mack Trucks Inc. |
| Dongfeng Motor Corporation |
| Iveco Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU F-Gas compliant chassis and legacy configurations splits procurement budgets across municipal tenders, with premium tier units commanding higher upfront capital while commodity-tier imports from regional fabricators compete on stripped-down specifications and deferred compliance timelines. This bifurcation concentrates margin capture among integrated OEMs with in-house electric platform certification, while supply chain routing favors established manufacturing clusters with KBA and EPA type-approval infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs municipal procurement, with differentiation driven by telematics bundling and battery warranty duration. Cost compression in economy-tier diesel configurations is intensifying because of EU Green Deal procurement mandates redirecting volume toward electric alternatives. Municipal sanitation departments exhibit lowest price sensitivity where lifecycle service contracting transfers residual value risk, while private waste haulers in emerging markets prioritize acquisition cost over total cost of ownership metrics.
Supply Chain Analysis
Freight cost escalation on battery cell imports from China and South Korea is reshaping chassis manufacturer sourcing strategies, with European body builders seeking regional cathode supply agreements to mitigate exposure. Lithium-ion cells, electric power take-off units, and bio-based hydraulic fluids anchor component dependencies. Single-source vulnerability concentrates in Chinese cathode production, threatening production continuity under export licensing shifts. Distribution runs through municipal procurement consortia and dealer networks serving private hauler fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waste collection vehicle market functions as a regulatory compounder where EU Green Deal binding targets and EPA emissions tightening create irreversible demand inflection for zero-emission powertrains.
For Market Incumbents: Deepen backward integration into battery pack assembly to secure cell allocation priority as cathode supply concentrates in China. Expand KBA-certified engineering capacity in Baden-Württemberg to compress tender response timelines for German municipal electrification programs. Lock in lifecycle service contracting templates with Dutch and Danish sanitation departments to transfer residual value risk before competitors replicate the structure. For New Entrants and Emerging Players: Enter via compact electric chassis specialization for Indian Smart Cities Mission tenders in Bangalore and Pune, where narrow street grids and domestic assembly requirements exclude established Western OEMs. Target private waste hauler segments in US Sun Belt states leveraging IRA commercial vehicle credits, positioning automated side-loading configurations against labor shortage pressures. Pursue telematics-as-a-service partnerships rather than asset-heavy manufacturing to bypass capital barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where body builders lack electric chassis integration capability and face F-Gas compliance redesign costs without OEM platform access. Long-term viability favors suppliers with certified electric architectures and municipal service contracting expertise. Acquisition target archetype: regional body builders with established dealer density but stranded diesel-engineering assets requiring electric platform partnerships. Signal to watch: battery degradation warranty standardization enabling residual value securitization.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Standardization | Scania AB and Volvo Trucks leverage modular architectures to compress KBA certification timelines for municipal tenders. |
| Battery Supply Agreement | Chassis OEMs secure cathode allocation priority with Chinese cell producers to hedge against export licensing volatility. |
| Telematics Integration Investment | Connected fleet management systems open recurring revenue streams beyond transactional chassis sales. |
| Lifecycle Service Contracting | Oslo and Copenhagen sanitation departments transfer energy and maintenance risk to suppliers under performance-based agreements. |
| Charging Infrastructure Partnership | Depot grid upgrade collaborations with utilities reduce municipal capital barriers to fleet electrification commitments. |
Study Parameters
Coverage spans Germany, the United States, China, Sweden, and India, with primary inputs from each market combining structured interviews with municipal procurement officers, fleet operations managers at private waste haulers, chassis OEM platform engineers, refuse body builder technical directors, and aftermarket service heads with secondary validation. Trade data from EU customs filings, EPA certification databases, MIIT new energy vehicle registrations, and municipal tender documentation provided demand-side triangulation against bottom-up production estimates from manufacturing clusters.
Rate-of-change decomposition across vehicle type, fuel type, size classification, and end-user procurement authority segments enabled projection construction over the analysis window. CAGRs derived from segment-level volume build-ups incorporating EU Green Deal mandate timelines, IRA credit phase-in schedules, and Smart Cities Mission funding disbursement patterns. Electric powertrain adoption curves modeled against depot charging infrastructure deployment rates and battery cost trajectories.
The model holds under sustained regulatory enforcement of EU F-Gas and EPA emissions standards; deviation in biomethane corridor development pace or lithium export licensing restrictions would shift powertrain mix assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Van Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market