
 Global Commercial Vehicle Fuel Tank Market | 2026-2036
Global Commercial Vehicle Fuel Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Vehicle Fuel Tank Market Analysis
Advanced corrosion-resistant coating specifications is bifurcating the competitive landscape between premium system integrators and commodity producers. TI Fluid Systems leverages its blow-molding expertise to anchor positions in plastic tank architectures across European OEM supply chains. YAPP Automotive Systems specializes in high-volume steel tank production, sustaining cost advantages through captive stamping operations in China. Futaba dominates precision aluminum fuel cell applications, extending its technical leadership into hydrogen-adjacent storage formats.
A commercial vehicle fuel tank is a sealed containment vessel engineered from stamped steel, extruded aluminum, or multi-layer polymer composites, typically rated for pressures between 0.3 and 0.7 bar, designed to store and deliver liquid or gaseous fuel to internal combustion or alternative-powertrain engines under dynamic load conditions. Composite material configurations are capturing margin pools in above-200-liter capacity segments where weight reduction directly improves freight economics. Installation below the frame rails remains the largest category by unit volume, though side-mount configurations are accelerating in electric-hybrid retrofit platforms where battery packaging constrains legacy positioning.
The EPA and NHTSA jointly enforce greenhouse gas standards that compel tank weight reductions across US heavy-duty fleets, while the EU Green Deal and F-Gas Regulation pressure European manufacturers toward lower-emission material cycles. China's MIIT imposes GB standards on fuel system integrity that favor domestic composite suppliers with localized testing certification. Stakeholders must monitor how divergent crash-test protocols between NHTSA rollover requirements and ECE R34 harmonization timelines reshape cross-border product qualification costs.
Market Dynamics
Lightweight composite architectures are compressing traditional steel tank margins as freight operators face escalating fuel efficiency mandates across major automotive production clusters.
Growth Catalysts
- EPA-NHTSA Phase 2 Standards:US heavy-duty fleet operators must achieve measurable weight reductions, forcing tank specification upgrades that favor advanced material configurations.
- EU Green Deal material cycles:European manufacturers face binding lower-emission production requirements that accelerate composite adoption in long-haul tractor platforms.
- China GB standards certification:Domestic composite suppliers with localized testing infrastructure capture preferential positioning in the world's largest commercial vehicle production base.
Market Restraints
- Aluminum price volatility:Extruded aluminum feedstock costs fluctuate with energy-intensive smelting economics, compressing margin predictability for precision tank fabricators.
- Supplier concentration in East Asian polymer feedstock:Multi-layer composite substrate production clusters heavily in specific coastal Chinese provinces, creating geographic single-point vulnerability.
- Hydrogen storage format substitution:Fuel cell commercial vehicle platforms eliminate conventional liquid fuel containment entirely, threatening addressable volume in specific long-haul segments.
Strategic Opportunities
- Indian heavy-duty fleet electrification lag:Extended diesel dependency in commercial transport creates extended demand runway for advanced conventional tank architectures.
- Brazil biofuel blending infrastructure:Flex-fuel commercial vehicle specifications require corrosion-resistant tank modifications that open retrofit service revenue pools.
- ISO 19014-2 harmonization:Emerging global crash-test protocol alignment reduces cross-border qualification duplication costs for system integrators serving multiple OEM supply chains.
Industry Challenges
- Composite welding technician scarcity:Multi-layer polymer fusion processes require specialized certification programs that outpace current vocational training throughput in European manufacturing clusters.
- ECE R34-NHTSA rollover test divergence:Non-harmonized impact simulation protocols force redundant engineering validation cycles, extending product development timelines.
- Legacy frame rail integration complexity:Electric-hybrid retrofit platforms demand side-mount tank configurations that conflict with established below-rail assembly line tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Vehicle Fuel Tank Market |
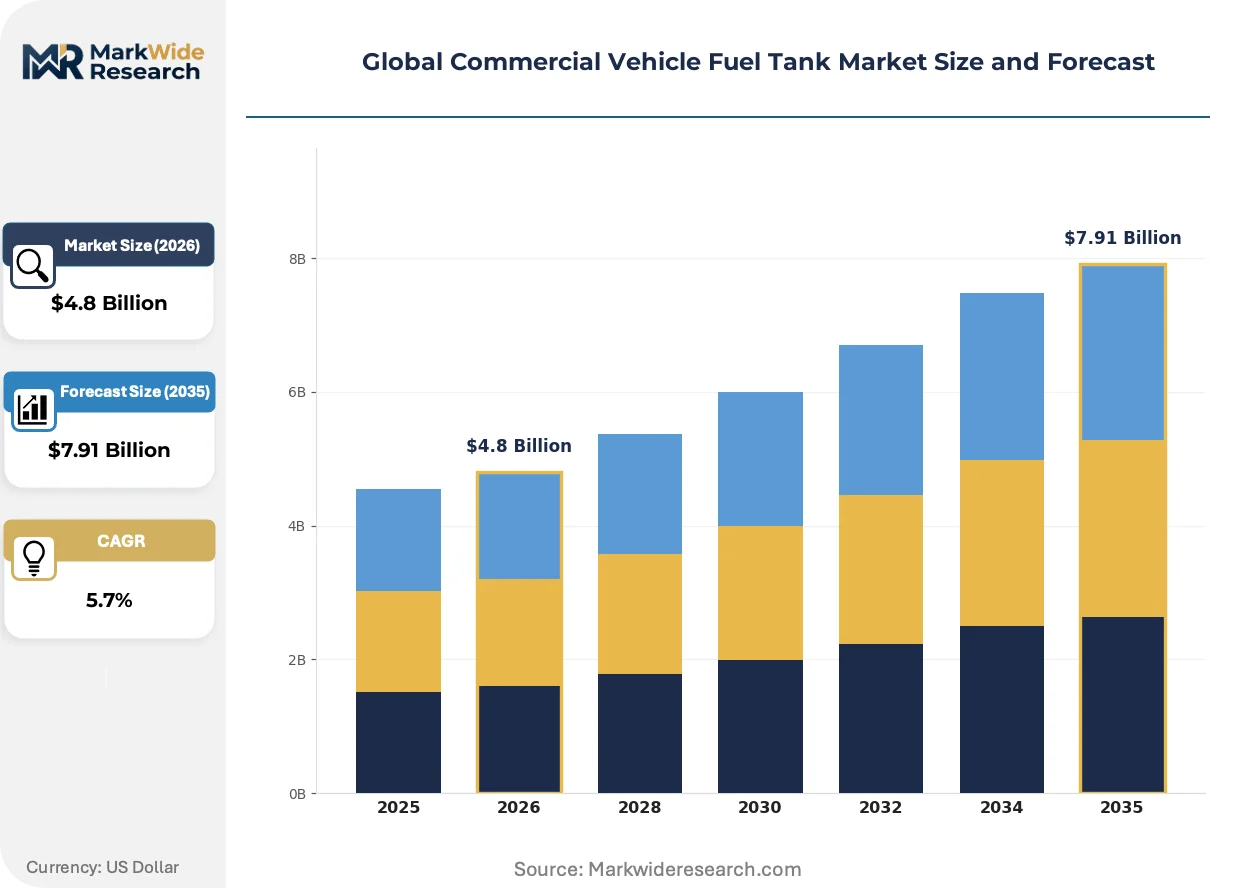
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Steel, Aluminum, Composite, Plastic Capacity: Below 50 Liters, 50-100 Liters, 100-200 Liters, Above 200 Liters Installation: Above Frame, Below Frame, Side Mount, Inside Frame End User: Logistics Providers, Fleet Operators, Public Transport, Construction Companies |
| Companies Covered | Textron Kautex, TI Fluid Systems, Magna International, Yachiyo Industry, YAPP Automotive Systems, Hwashin, Futaba, Plastic Omnium, FTS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Vehicle Fuel Tank Market Emerging Trajectories
Material science breakthroughs and regulatory calibration protocols are reconfiguring how fuel containment systems integrate with evolving powertrain architectures across commercial vehicle classes.
Multi-layer co-extruded polymer barrier technology is miniaturizing wall thickness specifications while maintaining permeation resistance. Long-haul fleet operators in Germany and the United States are specifying these configurations for above-300-liter capacities where freight-weight economics dominate procurement criteria. The technology is miniaturizing the physical footprint of high-capacity tanks, freeing frame rail space for battery packaging in hybrid platforms.
The EU F-Gas Regulation is tightening material cycle accountability for fluorinated polymer components used in barrier layers. Tank system integrators serving European OEM supply chains must now document full lifecycle emission profiles, adding qualification overhead that favors larger suppliers with dedicated compliance infrastructure. Heavy-duty segments in Germany and France face the steepest documentation requirements.
Leasing companies are consolidating procurement authority previously dispersed across individual fleet operators. Tier-1 tank suppliers now negotiate directly with major rental and finance entities in the United States and China, compressing price discovery cycles and standardizing specification requirements across multi-brand vehicle portfolios. This concentration is most visible in North American sleeper cab segments where lease penetration exceeds ownership rates.
Global Commercial Vehicle Fuel Tank Market Segmentation
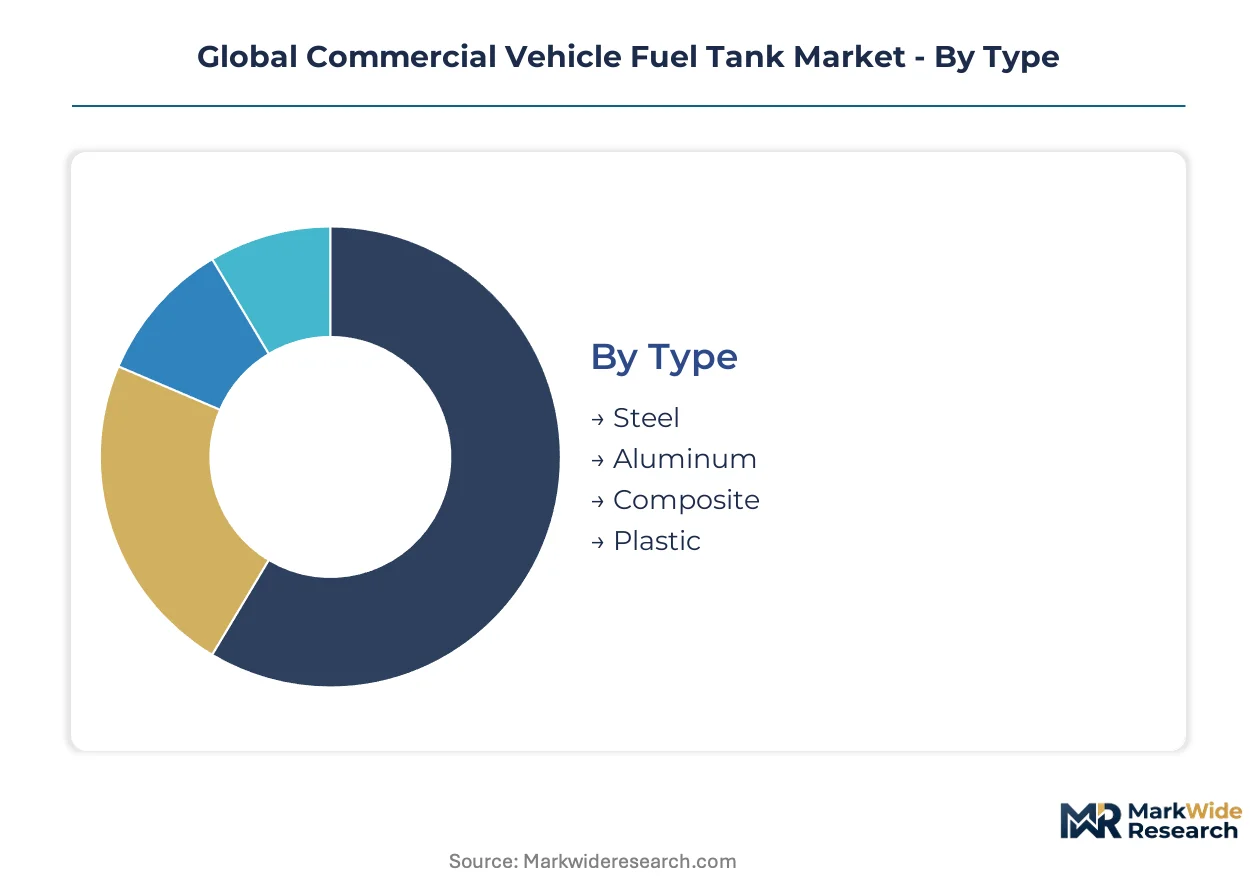
Material composition, capacity scaling, and mounting configurations define procurement patterns across heavy-duty, medium-duty, and light commercial vehicle platforms. Tank specification decisions cascade directly into freight economics, crash-test compliance costs, and powertrain integration feasibility.
Type:
Steel dominates domestic supply chains in China and India where stamping infrastructure saturates regional manufacturing clusters. Aluminum and composite configurations concentrate in export-oriented production serving European and North American OEMs.
- Steel:Cold-rolled stamped construction with corrosion-resistant coating systems remains the default specification for cost-sensitive fleet procurement in India and Brazil. Chinese OEMs source predominantly from captive YAPP Automotive stamping operations to maintain margin control.
- Aluminum:Extruded 5xxx and 6xxx series alloys deliver weight reductions while maintaining structural integrity under NHTSA rollover protocols. German and US long-haul operators specify these configurations where fuel efficiency mandates justify material cost premiums.
- Composite:Multi-layer co-extruded polymer barrier technology from European suppliers serves hybrid platforms requiring frame rail space optimization.
- Plastic:Blow-molded high-density polyethylene configurations anchor light commercial and urban delivery segments in France and Italy.
Steel holds the largest share; momentum sits with aluminum as EPA-NHTSA Phase 2 standards tighten.
Capacity:
Volume thresholds segment procurement authority between fleet operators optimizing for range economics and urban logistics prioritizing payload flexibility.
- Below 50 Liters:Compact plastic tanks serve last-mile delivery vans in dense European urban centers where refueling infrastructure penetration eliminates range anxiety.
- 50-100 Liters:Standard specification for regional distribution trucks across Japanese and South Korean commercial vehicle production.
- 100-200 Liters:Dominant configuration for medium-duty freight corridors connecting Chinese manufacturing hubs to coastal ports.
- Above 200 Liters:Dual-chamber steel or aluminum architectures support sleeper cab tractors operating US interstate routes where fuel station spacing demands extended range.
100-200 liter configurations anchor unit volume; above-200 liter segments are climbing the fastest as long-haul electrification delays extend diesel dependency.
Installation:
Mounting position determines crash-test validation pathways and assembly line tooling requirements across OEM manufacturing footprints.
- Above Frame:Legacy positioning for cab-over-engine trucks in European markets where ground clearance regulations permit elevated tank placement.
- Below Frame:Dominant US heavy-duty specification protecting tanks from side-impact collision energy while preserving frame rail space for battery modules in hybrid retrofits.
- Side Mount:Accelerating adoption in electric-hybrid platforms where battery packaging constraints force relocation from below-rail positions.
- Inside Frame:Niche configuration for specialized vocational vehicles requiring maximum ground clearance in Australian mining and Canadian forestry applications.
Below-frame installation commands the largest share; side-mount configurations are expanding most quickly as powertrain electrification reshapes packaging constraints.
End User:
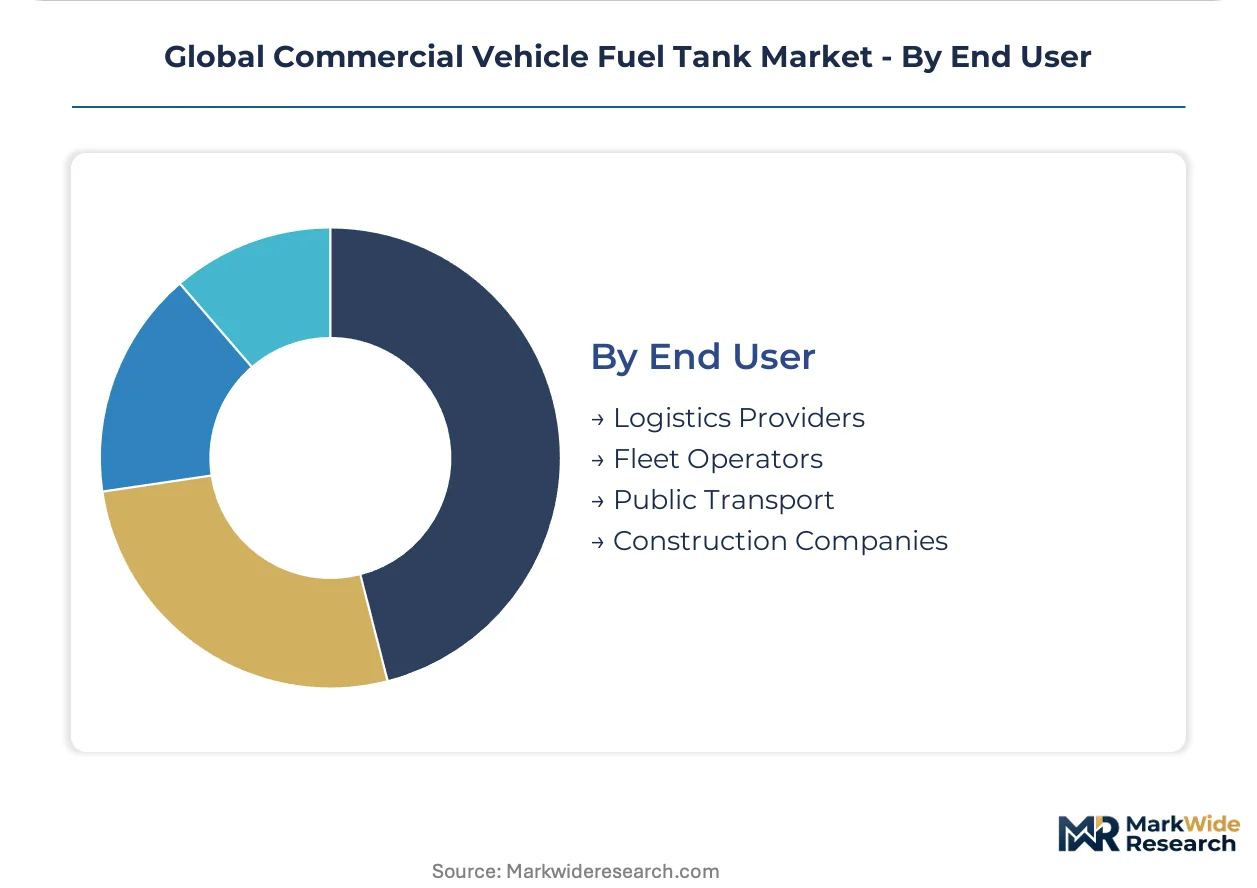
Procurement centralization varies sharply across user categories, with leasing companies consolidating specification authority previously dispersed across fragmented fleet operators.
- Logistics Providers:Global 3PL operators standardize tank specifications across multi-brand tractor portfolios to simplify maintenance protocols and parts inventory.
- Fleet Operators:US and German long-haul fleets negotiate directly with TI Fluid Systems and comparable Tier-1 suppliers, bypassing traditional OEM captive sourcing.
- Public Transport:Municipal bus operators in France and Japan specify corrosion-resistant configurations for high-frequency stop-start duty cycles with extended idle periods.
- Construction Companies:Vocational truck users in Brazil and Australia prioritize impact-resistant steel tanks for unimproved site access conditions.
Fleet operators represent the largest addressable base; logistics providers are gaining share fastest as procurement authority concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stamping and extrusion capacity clusters heavily in specific manufacturing corridors across four major automotive production bases. Each geography imposes distinct regulatory pressures that reshape tank specification requirements and supplier qualification pathways.
United States
EPA-NHTSA Phase 2 standards compel weight reduction across heavy-duty sleeper cab fleets. The NHTSA enforces rollover crash-test protocols that favor below-frame aluminum configurations. Manufacturing concentrates in Michigan and Ohio stamping corridors serving Detroit-based OEM supply chains.
Germany
Long-haul freight operators prioritize fuel efficiency economics in above-300-liter tank procurement. The EU F-Gas Regulation mandates lifecycle emission documentation for fluorinated polymer barrier components. Production gravity sits in Baden-Württemberg and Lower Saxony where system integrators serve premium tractor platforms.
China
Domestic commercial vehicle output dominates global unit volume with concentrated demand in 100-200 liter configurations. MIIT imposes GB standards on fuel system integrity that favor localized composite testing certification. Manufacturing clusters in Yangtze River Delta provinces where YAPP Automotive maintains captive stamping operations.
India
Extended diesel dependency in heavy-duty freight creates sustained demand for corrosion-resistant steel tank architectures. The Bureau of Indian Standards enforces automotive component certification that lags composite adoption timelines. Production concentrates in Maharashtra and Gujarat where cost-sensitive fleet procurement sustains conventional material specifications.
Brazil
Biofuel blending infrastructure necessitates flex-fuel tank modifications across commercial vehicle retrofit segments. ANVISA regulates automotive component safety alongside environmental agency emission protocols. Manufacturing activity centers in São Paulo and Minas Gerais states serving Mercosur distribution corridors.
Global Commercial Vehicle Fuel Tank Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across material categories. The vendor base separates into three functional tiers: premium system integrators with blow-molding and composite expertise, high-volume steel stampers with captive manufacturing assets, and precision aluminum fabricators serving fuel-cell-adjacent applications. Dominant competitive moves include backward integration into polymer feedstock operations and geographic expansion through localized testing certification infrastructure.
Among European-based system integrators, TI Fluid Systems and Plastic Omnium occupy positions in plastic tank architectures and multi-layer barrier technology respectively. YAPP Automotive Systems exemplifies the scale-driven steel stamping archetype with China-centric production footprints. These three anchors represent divergent strategic postures across material technology vectors without overlapping core competencies.
| Leading Market Players |
|---|
| Textron Kautex |
| TI Fluid Systems |
| Magna International |
| Yachiyo Industry |
| YAPP Automotive Systems |
| Hwashin |
| Futaba |
| Plastic Omnium |
| FTS |
| Others |
Supply Flow & Price Mechanics
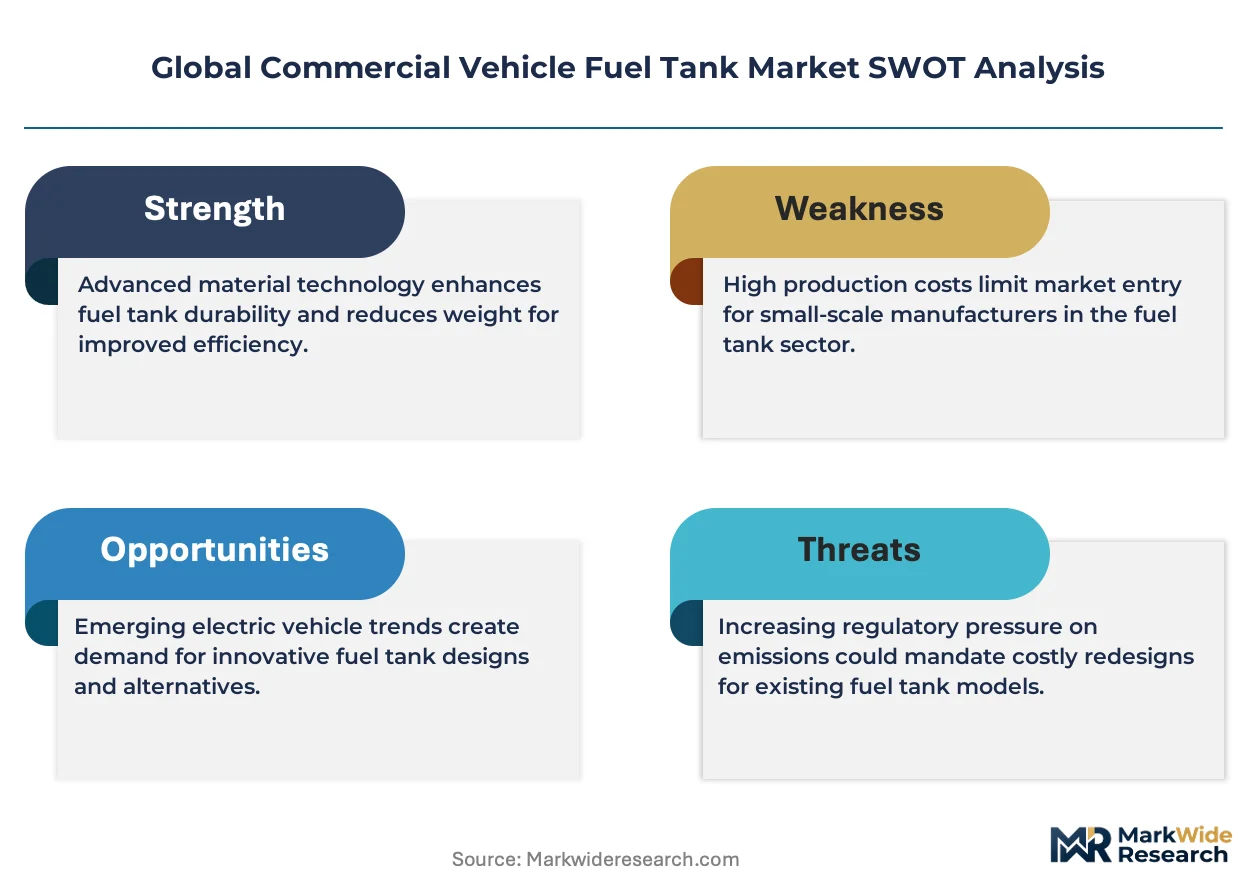
Composite polymer substitution for stamped steel is simultaneously redrawing manufacturing geography toward Yangtze River Delta provinces and compressing margin pools for legacy metal fabricators serving cost-sensitive procurement in India and Brazil. This material transition hands pricing power to suppliers with captive multi-layer co-extrusion capability while forcing commodity steel stampers into volume-driven defensive positions.
Pricing Analysis
EPA-NHTSA Phase 2 standards dictate the pricing tier structure across North American heavy-duty procurement, separating premium aluminum configurations from standard steel specifications based on weight-reduction certification levels. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, crash-test validation tier, and geographic delivery cost from manufacturing clusters in Michigan and Ohio. Cost compression in standard steel tiers is intensifying because Chinese OEMs leverage YAPP Automotive's captive stamping operations to undercut export pricing. Fleet operators in India and Brazil exhibit the highest price sensitivity, while German long-haul logistics providers absorb material premiums for fuel efficiency gains.
Supply Chain Analysis
China, Germany, and the United States anchor commercial vehicle fuel tank fabrication, with each geography specializing in distinct material categories aligned to regional regulatory pressures. Multi-layer polymer substrates draw from concentrated coastal Chinese petrochemical operations, while extruded aluminum feedstock hinges on energy-intensive smelting economics in Germany and the US Gulf Coast. Single-source vulnerability clusters in East Asian polymer barrier layer production, where fluorinated component supply faces tightening EU F-Gas Regulation documentation requirements. Distribution runs through OEM captive supply chains in China and tier-1 system integrator networks serving European and North American tractor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified composite welding technicians remain scarce across European manufacturing clusters, creating a bottleneck that constrains capacity expansion for barrier-layer tank architectures and inflates labor costs for system integrators competing on fuel cell-adjacent storage formats.
For Market Incumbents: Consolidate backward integration into polymer feedstock operations to secure margin control as fluorinated barrier layer costs face EU F-Gas Regulation documentation overhead. Lock in localized testing certification infrastructure across Yangtze River Delta provinces to defend against emerging Chinese composite suppliers with MIIT GB standards preferential positioning. Capacity addition in Baden-Württemberg serves premium European OEM supply chains where fuel efficiency mandates justify material cost premiums. For New Entrants and Emerging Players: Aftermarket retrofit service for flex-fuel corrosion-resistant tank modifications in Brazil offers the most penetrable white-space target, where ANVISA safety protocols and biofuel blending infrastructure create specification complexity incumbents under-serve. Side-mount tank configurations for electric-hybrid retrofit platforms represent a second entry vector, as battery packaging constraints force relocation from below-rail positions and legacy assembly line tooling conflicts delay incumbent response. Go-to-market through direct leasing company procurement channels bypasses fragmented fleet operator sales cycles concentrated in North American sleeper cab segments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed steel stamping operations in India and Brazil where extended diesel dependency sustains conventional tank demand but electrification timelines threaten terminal value erosion. Mid-cap composite specialists with EU F-Gas Regulation compliance infrastructure and hydrogen storage format adjacency present the strongest acquisition profile for long-haul viability across the next decade. The signal to watch is NHTSA-ECE R34 rollover test harmonization progress, which would eliminate redundant engineering validation cycles and reshape cross-border product qualification economics for system integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive supply of multi-layer barrier substrates insulates margin pools from East Asian petrochemical price volatility. |
| Localized Testing Certification Infrastructure | MIIT GB standards compliance in Yangtze River Delta provinces unlocks preferential positioning in China's commercial vehicle production base. |
| Composite Welding Technician Training Programs | Vocational certification throughput in European manufacturing clusters addresses capacity constraints for hybrid platform tank architectures. |
| Side-Mount Tank Configuration Development | Frame rail space optimization serves electric-hybrid retrofit platforms where battery packaging constrains legacy below-rail positioning. |
| Hydrogen Storage Format Adjacency Investment | Precision aluminum fabrication capability extends technical leadership into fuel cell commercial vehicle applications threatening conventional liquid fuel containment. |
Methodological Framework
Operator-level perspectives from fleet procurement managers, Tier-1 supplier engineering directors, OEM platform integration teams, and aftermarket service operators anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT GB standards documentation. Bottom-up capacity modeling across material type and installation configuration triangulated against top-down freight economics analysis.
Sensitivity analysis tested forecast outputs against alternative electrification penetration scenarios and regulatory harmonization timelines across the projection horizon. Segmentation dimensions modeled include material composition, capacity tier, mounting configuration, vehicle class, and regional production cluster. CAGRs were derived from installed base turnover rates and specification upgrade cycles. Industry-specific forecast inputs incorporated EPA-NHTSA Phase 2 compliance deadlines and EU F-Gas Regulation material cycle accountability phase-ins.
Underlying assumptions cover diesel dependency persistence in Indian and Brazilian heavy-duty freight, hydrogen storage format substitution timelines in long-haul segments, and composite welding technician training program expansion rates, with deviation risk concentrated in NHTSA-ECE R34 harmonization delays and aluminum smelting energy cost volatility. Recalibration cycles align with material shifts in regulatory enforcement calendars and powertrain electrification platform launches.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Hopper Car Market