
 Mexico Refrigerated Truck Market | 2026-2036
Mexico Refrigerated Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Refrigerated Truck Market Insights
Supermarket retail chain procurement is recalibrating Mexico's refrigerated truck demand as national grocery banners consolidate their direct-to-store delivery networks. Thermo King Corporation leverages its compressor technology leadership to anchor premium fleet contracts across central Mexico. Carrier Global Corporation competes through integrated telematics platforms that sustain fleet uptime guarantees for pharmaceutical distributors. Wabash National Corporation specializes in lightweight composite refrigerated bodies that extend payload capacity for long-haul produce routes.
A refrigerated truck is a commercial vehicle equipped with a mechanical refrigeration unit, insulated cargo box with polyurethane foam cores, and temperature monitoring systems maintaining set points from -25°C to +25°C for transporting perishable and temperature-sensitive commodities. Multi-temperature configurations now lead product type demand as logistics providers consolidate mixed loads of frozen, chilled, and ambient goods into single trips. The food and beverage application dominates current fleet deployment, while pharmaceutical transport commands the strongest margin pools due to GDP-validated cold-chain requirements and specialized documentation protocols.
Mexico's Secretariat of Energy enforces NOM-022-ENER efficiency standards that shape refrigeration unit specifications and operating cost calculations for fleet operators. The Federal Commission for the Protection against Sanitary Risk (COFEPRIS) mandates cold-chain integrity documentation for pharmaceutical distribution, directly influencing truck monitoring system investments. Stakeholders must weigh diesel-to-electric refrigeration transition timelines against charging infrastructure readiness and total cost of ownership trajectories before committing to fleet renewal cycles.
Market Dynamics
Supermarket retail chain consolidation is restructuring Mexico's refrigerated truck procurement, as national grocery banners internalize direct-to-store delivery networks and impose fleet uptime guarantees on logistics providers.
Growth Catalysts
- NOM-022-ENER standards:Mexico's Secretariat of Energy enforces efficiency mandates that accelerate diesel-to-electric refrigeration unit replacement cycles among fleet operators.
- Pharmaceutical distribution:COFEPRIS cold-chain integrity requirements drive investment in GDP-validated monitoring systems for temperature-sensitive drug transport.
- Central Mexico corridor:Concentrated demand across Mexico City, Querétaro, and Guadalajara creates economies of scale for multi-temperature fleet configurations serving overlapping food and pharma networks.
Market Restraints
- Electric charging infrastructure:Sparse fast-charging networks along long-haul produce routes from Sinaloa and Veracruz delay electric refrigeration unit adoption despite total cost of ownership advantages.
- Polyurethane foam supply:Insulated cargo box manufacturing depends on imported chemical inputs subject to price volatility and customs processing delays at Lázaro Cárdenas port.
- Compressor technology concentration:Premium refrigeration unit sourcing concentrates among North American suppliers, exposing fleet operators to currency fluctuation risks and extended lead times.
Strategic Opportunities
- Last-mile pharmaceutical delivery:Hospital and clinic networks in Monterrey and Tijuana lack GDP-validated cold-chain coverage, creating openings for specialized regional fleet operators.
- Biogas refrigeration units:Convergence of anaerobic digester infrastructure expansion and NOM emissions standards enables alternative fuel adoption for agricultural transport corridors.
- Telematics-integrated service contracts:Predictive maintenance platforms that guarantee temperature compliance are displacing traditional break-fix service models among pharmaceutical distributors.
Industry Challenges
- Refrigeration technician certification:COFEPRIS and SCT requirements for specialized handling of pharmaceutical cargo exceed current vocational training program output in states outside Mexico City.
- Multi-temperature system integration:Fleet operators struggle to calibrate zone controls for mixed loads of frozen seafood, chilled dairy, and ambient produce within single routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Refrigerated Truck Market |
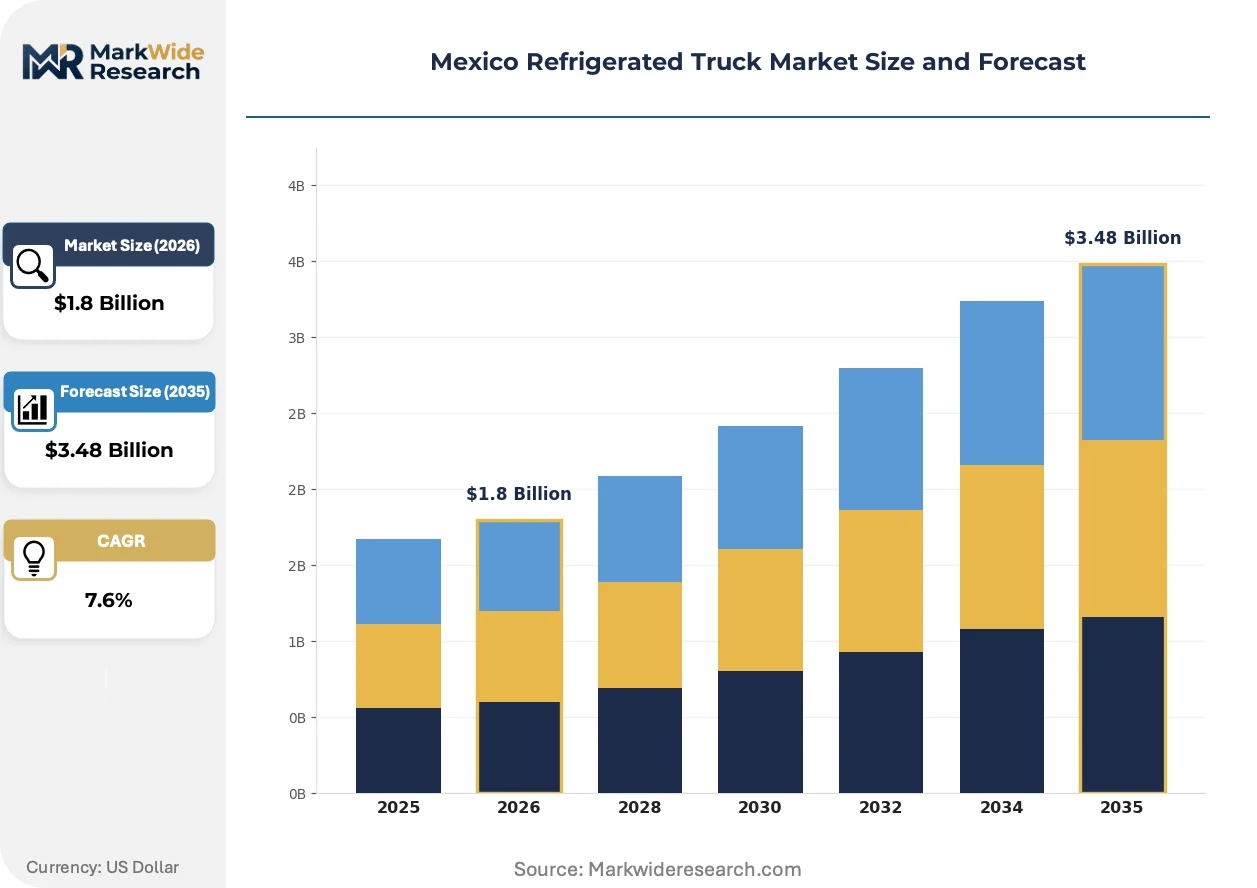
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Temperature, Multi-Temperature, Insulated, Refrigerated Vans Application: Food and Beverage, Pharmaceuticals, Chemicals, Fresh Produce Size: Small, Medium, Large, Extra Large End User: Retail Chains, Logistics Providers, Distributors, Restaurants |
| Companies Covered | Thermo King Corporation, Utility Trailer Manufacturing Company LLC, Wabash National Corporation, Hyundai Translead, Inc., Carrier Global Corporation, Great Dane Trailers Inc., STI Holdings Inc., Ford Motor Company, Vanguard National Trailer Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Refrigerated Truck Market Trends and Innovations
Refrigerated transport technology is converging with digital monitoring platforms and alternative powertrains, compressing operational margins for asset-light brokers while rewarding integrated fleet operators.
Telematics-enabled temperature logging is automating compliance documentation for pharmaceutical shipments. Logistics providers serving COFEPRIS-regulated distributors are adopting real-time data transmission to eliminate manual record-keeping. This compression of administrative overhead is shifting competitive advantage toward operators with captive IT development capabilities.
NOM-022-ENER efficiency standards are forcing refrigeration unit specification changes across Mexican fleet procurement. The Secretariat of Energy mandates are elevating electric and hybrid systems over conventional diesel-powered units in new vehicle registrations. Pharmaceutical transport segments are absorbing these cost premiums fastest due to margin structures that validate cold-chain technology investments.
Consolidated procurement by national supermarket banners is displacing fragmented third-party logistics relationships. Direct fleet ownership models are replacing broker-mediated capacity sourcing for fresh and frozen goods distribution. This concentration is most visible in the central Mexico corridor where retail chain distribution centers anchor scheduled route density.
Mexico Refrigerated Truck Market Segmentation
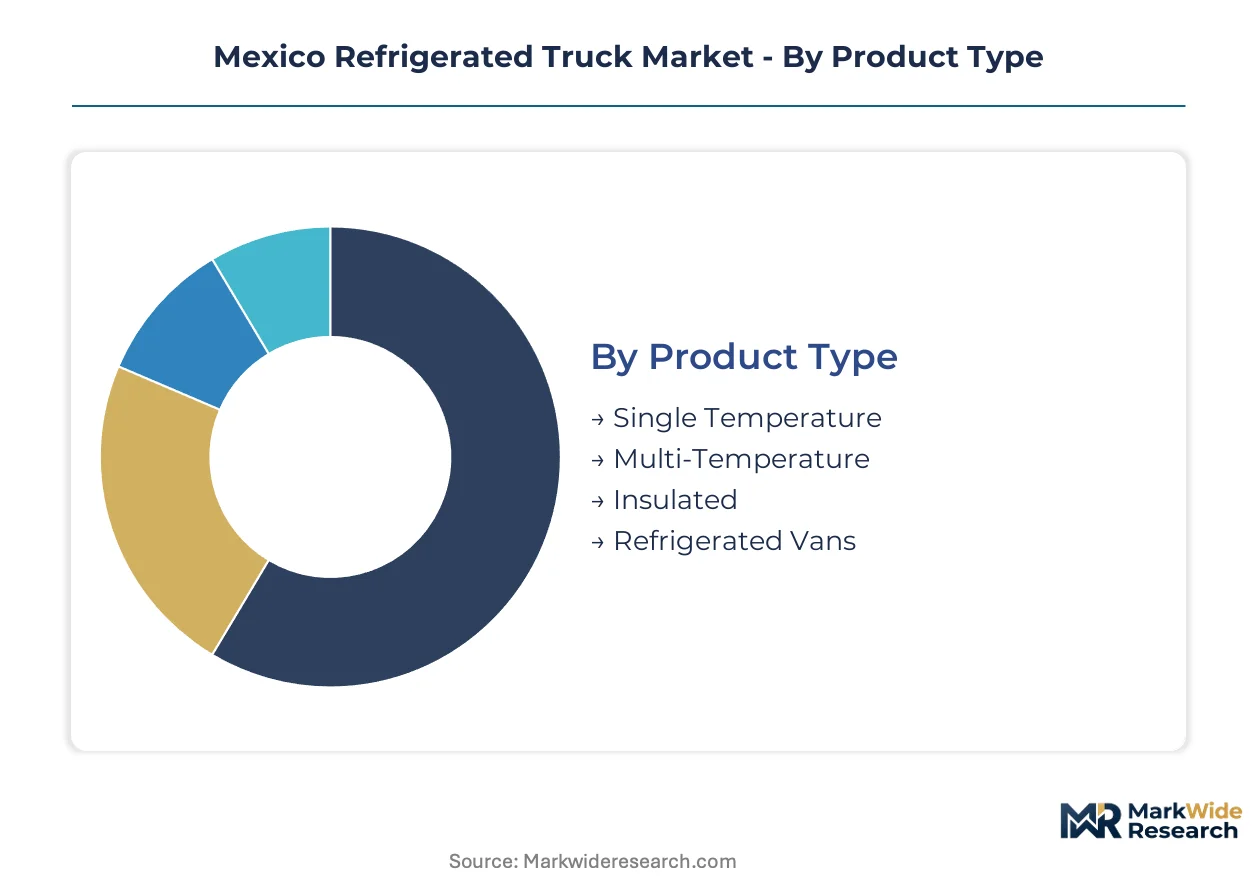
Mexico's refrigerated truck market fragments across temperature control sophistication, cargo scale, and customer procurement power. Fleet operators align specifications with route economics, regulatory compliance burdens, and cargo value density.
Product Type:
Buyers differentiate by thermal zone complexity and fuel system integration requirements.
- Multi-Temperature:Configured with partitioned cargo compartments maintaining distinct set points from -25°C to +15°C simultaneously. Demand concentrates among third-party logistics providers serving central Mexico corridor retail consolidation, where single-trip mixed loads of frozen seafood, chilled dairy, and ambient produce maximize asset utilization against diesel cost pressures.
- Single Temperature:Uniform thermal control throughout the cargo box using direct-drive or diesel-powered refrigeration units. Frozen food distributors across Sinaloa-to-Mexico City produce routes dominate procurement, prioritizing payload capacity and mechanical simplicity over flexibility.
- Insulated:Passive thermal retention without active mechanical cooling, relying on pre-cooled cargo and rapid transit. Short-haul bakery and floral distributors in Guadalajara metropolitan area deploy these for cost-sensitive last-mile routes under four hours.
- Refrigerated Vans:Light-duty chassis with integrated refrigeration for urban delivery. Pharmacy chains in Monterrey and Tijuana utilize these for COFEPRIS-compliant last-mile pharmaceutical distribution where maneuverability trumps cargo volume.
Volume sits with Single Temperature configurations; growth tilts toward Multi-Temperature as route consolidation accelerates.
Application:
Margin structures and regulatory intensity separate cargo categories.
- Food and Beverage:Dominant deployment segment spanning frozen processed foods, chilled dairy, and fresh meat distribution. Supermarket retail chains internalizing direct-to-store networks in Mexico City-Querétaro-Guadalajara triangle drive specification standardization around NOM-022-ENER efficiency compliance.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and insulin requiring GDP-validated cold chain with continuous monitoring documentation. COFEPRIS mandates for distribution integrity push fleet operators toward telematics-integrated units despite 40-60% cost premiums over standard refrigeration.
- Chemicals:Industrial adhesives, specialty coatings, and temperature-sensitive reagents. Chemical distributors in Veracruz port corridor utilize medium-duty refrigerated trucks for hazmat-compliant transport where thermal stability prevents polymerization or separation.
- Fresh Produce:Avocado, berry, and tomato exports from Michoacán and Jalisco to US border crossings. Grower cooperatives prioritize lightweight composite bodies and fuel-efficient refrigeration to maximize export payload against cross-border logistics costs.
Food and Beverage captures current fleet deployment; Pharmaceuticals commands steepest expansion trajectory on cold-chain integrity investments.
Size:
Chassis classification aligns with route distance and cargo density economics.
- Large:Class 7-8 heavy-duty tractors with 48-53 foot refrigerated trailers. Long-haul produce movements from Sinaloa and Baja California to central Mexico distribution centers concentrate demand, where fuel efficiency and driver hour regulations dominate procurement criteria.
- Medium:Class 5-6 straight trucks with 20-26 foot cargo boxes. Regional distributors serving overlapping retail and foodservice accounts in Puebla and León metropolitan areas favor this flexibility point between urban maneuverability and cargo volume.
- Small:Class 3-4 chassis with 14-18 foot bodies. Independent produce wholesalers and specialty food distributors utilize these for multi-stop routes in dense urban cores where parking constraints and toll costs penalize larger vehicles.
- Extra Large:Specialized heavy-haul configurations exceeding standard trailer dimensions. Limited deployment for bulk frozen commodity movements from Lázaro Cárdenas port to inland cold storage facilities, constrained by federal weight enforcement and bridge clearance limitations.
Medium trucks anchor current fleet composition; Large configurations gain share fastest on retail distribution center consolidation.
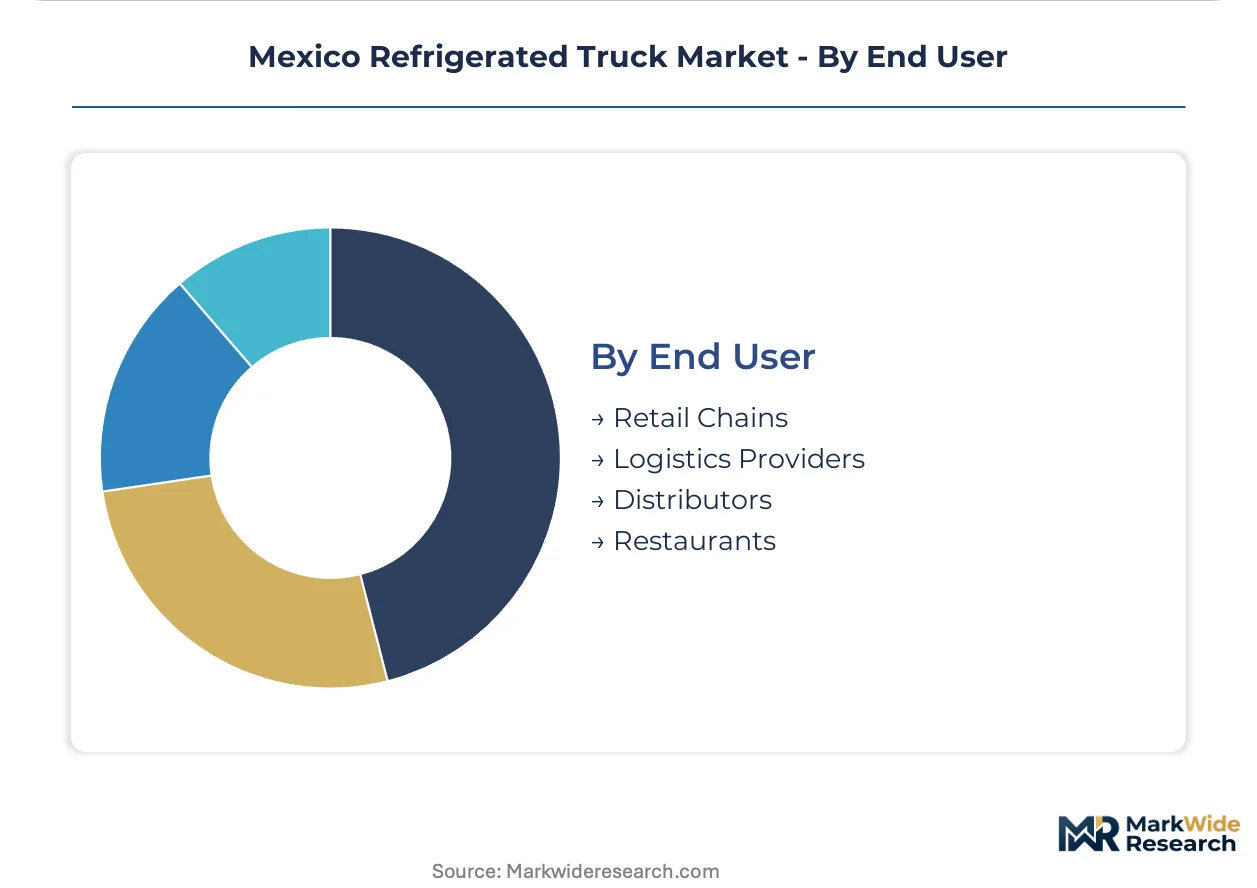
End User:
Procurement sophistication and fleet ownership models diverge sharply.
- Retail Chains:National supermarket banners with captive fleet operations or stringent carrier qualification programs. Their direct-to-store network internalization in central Mexico corridor imposes uptime guarantees and real-time visibility requirements on logistics partners.
- Logistics Providers:Third-party operators serving multiple shipper accounts with asset-heavy or asset-light models. Multi-temperature capabilities and cross-dock integration separate competitive tiers as broker-mediated capacity loses share to dedicated fleet contracts.
- Distributors:Independent operators with specialized territorial focus or commodity expertise. Pharmaceutical and chemical distributors in Monterrey and Tijuana markets maintain GDP-validated and hazmat-certified fleets as competitive moats against integrated logistics entrants.
- Restaurants:Chain and independent foodservice operators with limited fleet ownership. Their procurement concentrates on outsourced delivery from broadline distributors, though large quick-service chains in Mexico City metropolitan area deploy captive vans for high-frequency protein and dairy resupply.
Retail Chains concentrate current premium specification demand; Logistics Providers face steepest capability investment requirements to defend contract renewals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for refrigerated trucks concentrates in Mexico's central corridor, where pharmaceutical distribution networks and perishable food supply chains converge on Mexico City, Querétaro, and Guadalajara. Fleet procurement patterns diverge sharply across sub-regions based on export proximity, retail consolidation intensity, and regulatory enforcement capacity.
Mexico City Metro
Pharmaceutical distributors and national supermarket banners anchor fleet deployment in the capital region. COFEPRIS cold-chain integrity mandates drive investment in GDP-validated monitoring systems for temperature-sensitive drug transport. The Toluca-Mexico City-Querétaro logistics triangle hosts the densest concentration of multi-temperature configurations serving overlapping retail and pharma networks.
Nuevo León
Monterrey's industrial base generates specialized demand for chemical and pharmaceutical transport with hazmat compliance requirements. The state's manufacturing corridor lacks sufficient GDP-validated cold-chain coverage for hospital and clinic networks, creating openings for regional fleet operators. NOM-022-ENER efficiency standards are accelerating diesel-to-electric refrigeration transitions among captive industrial fleets.
Jalisco
Guadalajara anchors produce export logistics for avocado and berry shipments to US border crossings. Grower cooperatives prioritize lightweight composite refrigerated bodies to maximize payload capacity against cross-border logistics costs. The state's anaerobic digester infrastructure expansion enables biogas refrigeration unit adoption for agricultural transport corridors.
Bajío Region
León and Querétaro metropolitan areas host regional distributors serving overlapping retail and foodservice accounts with medium-duty straight trucks. The Querétaro pharmaceutical manufacturing cluster generates consistent demand for temperature-controlled distribution to Mexico City and Guadalajara. Fleet operators here struggle with refrigeration technician certification gaps relative to COFEPRIS and SCT requirements.
Northern Border States
Tijuana and Ciudad Juárez function as transshipment nodes for cross-border produce and pharmaceutical flows. Sparse fast-charging networks along long-haul routes from Sinaloa delay electric refrigeration adoption despite total cost of ownership advantages. Customs processing delays at Lázaro Cárdenas port disrupt polyurethane foam supply for insulated cargo box manufacturing serving this corridor.
Mexico Refrigerated Truck Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telematics-integrated service contracts and alternative fuel configurations. The vendor base stratifies across three tiers: integrated refrigeration-chassis providers, specialized trailer fabricators, and component technology suppliers. Strategic archetypes include compressor technology leaders, lightweight composite body specialists, and fleet uptime guarantors. Competitive moves concentrate on M&A for route density expansion and strategic partnerships for charging infrastructure pre-positioning.
Within the integrated systems tier, Thermo King Corporation and Carrier Global Corporation exemplify divergent positioning strategies. Thermo King anchors premium fleet contracts through compressor technology leadership across central Mexico corridor deployments. Carrier occupies a position defined by integrated telematics platforms that sustain pharmaceutical distributor uptime guarantees. Wabash National Corporation represents the lightweight composite specialization vector, extending payload capacity for long-haul produce routes from Michoacán and Jalisco to US border crossings.
| Leading Market Players |
|---|
| Thermo King Corporation |
| Utility Trailer Manufacturing Company LLC |
| Wabash National Corporation |
| Hyundai Translead, Inc. |
| Carrier Global Corporation |
| Great Dane Trailers Inc. |
| STI Holdings Inc. |
| Ford Motor Company |
| Vanguard National Trailer Corp. |
| Others |
Pricing and Supply Chain Analysis
Refrigeration technician certification gaps across Mexico's Bajío and Northern Border states widen pricing-tier spreads between premium GDP-validated fleet operators and standard food-transport providers. Labor-cost differentials between Mexico City metropolitan certification hubs and peripheral states compress margins for mid-tier operators while rewarding incumbents with captive training infrastructure.
Pricing Analysis
Volume concentrates in single-temperature diesel configurations for Sinaloa produce routes; margins accrue to multi-temperature electric-hybrid units serving pharmaceutical distributors. Price differentiation hinges on COFEPRIS GDP validation tier and NOM-022-ENER efficiency certification grade. Cost compression in standard food-transport tiers is intensifying as supermarket chains consolidate procurement volumes. Quick-service restaurant distributors exhibit highest price sensitivity; biologics logistics providers absorb premium pricing for guaranteed uptime.
Supply Chain Analysis
Direct-to-fleet channels handle national retail banner procurement; dealer networks serve independent distributors across secondary cities. Manufacturing concentrates in the United States for compressor technology, China for telematics hardware, and domestic Mexican facilities for insulated body fabrication. Polyurethane foam chemical inputs draw from Asian petrochemical suppliers subject to Lázaro Cárdenas port processing delays. Single-source vulnerability in North American compressor sourcing exposes fleet operators to currency fluctuation risks. Distribution runs through OEM-integrated channels for premium configurations and regional body builders for customized specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fleet operators with integrated telematics capabilities; NOM-022-ENER compliance deadlines are forcing asset-light brokers toward exit or acquisition.
For Market Incumbents: Acquire captive biogas fueling infrastructure along Jalisco agricultural corridors to lock in alternative-powertrain route density. Defend pharmaceutical contracts through predictive maintenance platform investments that guarantee COFEPRIS-compliant uptime. Compressor technology leadership at Thermo King and telematics integration at Carrier represent the primary competitive moats requiring continuous reinforcement against emerging electric-refrigeration specialists. For New Entrants and Emerging Players: Telematics-first service contracts offer the clearest wedge against incumbent break-fix models. Monterrey and Tijuana hospital networks present underpenetrated GDP-validated cold-chain white space. Target last-mile pharmaceutical delivery with refrigerated van deployments where maneuverability constraints exclude larger fleet entrants. Biogas refrigeration unit retrofit partnerships with Jalisco anaerobic digester operators provide a geographic-specific go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regional fleet operators possessing COFEPRIS certification infrastructure given pharmaceutical distribution margin expansion. Long-term viability favors asset-heavy operators with cross-dock integration capabilities over broker-mediated capacity models. Monitor electric charging infrastructure deployment velocity along Sinaloa-Mexico City corridors as the primary inflection indicator for diesel-to-electric transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Automates COFEPRIS compliance documentation for pharmaceutical distributors eliminating manual record-keeping overhead. |
| Biogas Refrigeration Unit Deployment | Captures NOM-022-ENER efficiency incentives across Jalisco agricultural transport corridors with existing digester infrastructure. |
| Multi-Temperature Fleet Configuration | Enables single-trip consolidation of frozen, chilled, and ambient loads for central Mexico retail distribution networks. |
| Refrigeration Technician Certification Program | Addresses COFEPRIS and SCT compliance gaps in Bajío and Northern Border states through captive training infrastructure. |
| Lightweight Composite Body Adoption | Extends payload capacity for Michoacán and Jalisco produce exports to US border crossings against cross-border logistics costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet operations managers, pharmaceutical logistics directors, supermarket procurement leads, and refrigeration unit service technicians combined with COFEPRIS enforcement documentation and SCT certification databases. Bottom-up triangulation across vehicle registration records and top-down validation against refrigerated transport capacity estimates established market sizing boundaries.
Granularity-level modeling addressed product type, application, chassis size, and end-user procurement sophistication across the analysis window. Segment-level CAGRs derived from route density projections, retail consolidation timelines, and NOM-022-ENER compliance adoption curves. Forecast inputs incorporated electric charging infrastructure build-out assumptions and biogas digester capacity expansion in agricultural corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated electric vehicle subsidy revisions or extended Lázaro Cárdenas port congestion. Projections reflect assumptions regarding NOM-022-ENER enforcement consistency and COFEPRIS pharmaceutical distribution mandate expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market