
 Iraq Trailer Market | 2026-2036
Iraq Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Trailer Market Insights
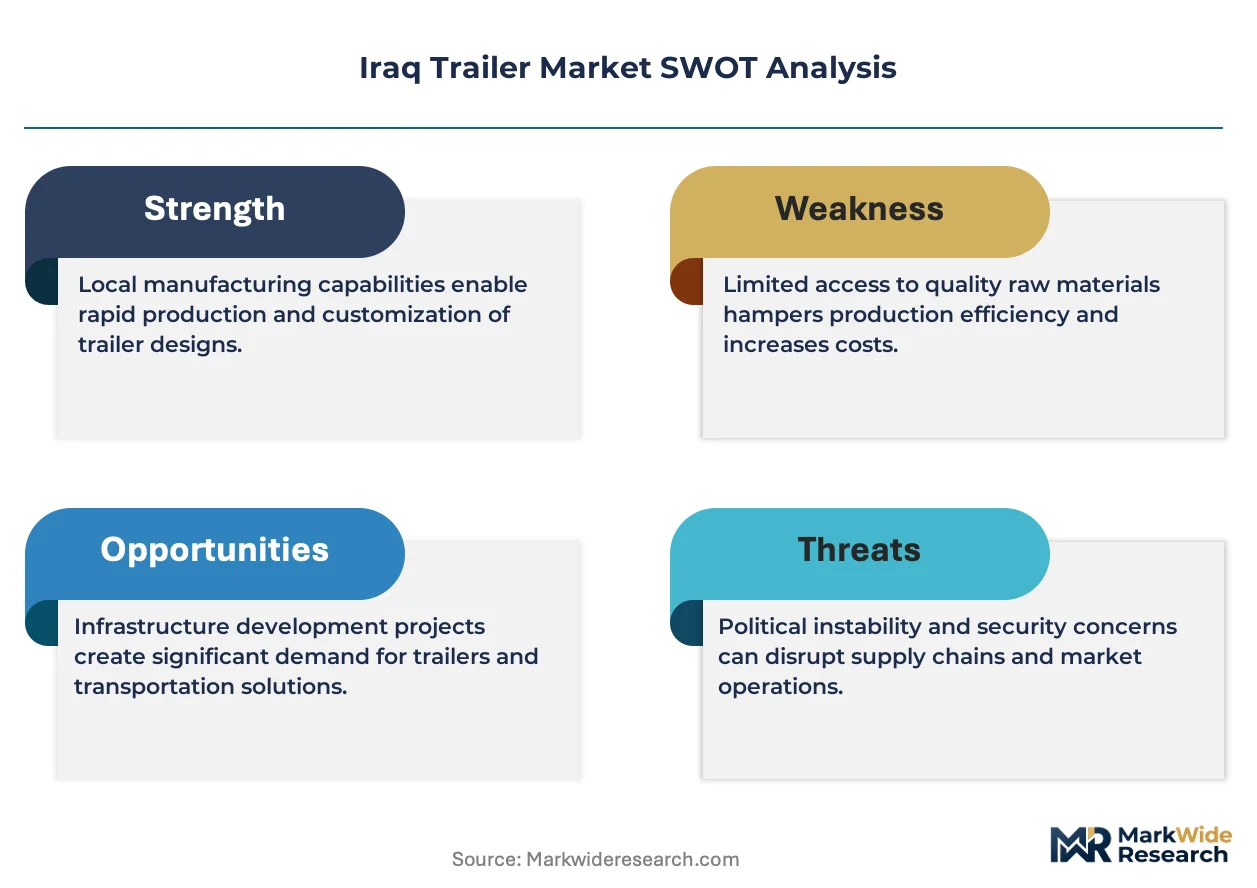
The gap between premium aluminum-bodied trailers and commodity steel models is expanding across Iraq's commercial fleet channels. Hyundai Motor Company leverages its regional assembly partnerships to anchor distribution in Kurdish provinces. Wabash National Corporation sustains technology leadership through advanced suspension systems for heavy-haul routes. Al-Fahd Auto competes on localized service networks and spare-parts availability.
An Iraq trailer is a non-powered wheeled vehicle designed for cargo transport, typically fabricated from steel or aluminum with rated payload capacities from 20 to 80 tons, and engineered to withstand desert climate extremes including sand abrasion and thermal cycling. Flatbed trailers dominate volume sales for construction material haulage, while tank trailers command premium margins serving the oil and gas sector's refined-product distribution. Enclosed trailers remain a nascent category as cold-chain logistics develop slowly outside Baghdad.
Iraq's General Company for Automotive Industry and Ministry of Transportation enforce chassis homologation rules that favor manufacturers with Gulf Cooperation Council certification alignment. The Central Organization for Standardization and Quality Control mandates periodic load-testing protocols that accelerate replacement cycles for aging steel fleets. Stakeholders must monitor how federal infrastructure spending and provincial customs harmonization reshape procurement priorities across the Tigris-Euphrates freight basin.
Market Dynamics
Iraq's trailer market pivots on federal axle-load harmonization with Gulf Cooperation Council standards, which is accelerating fleet replacement cycles and redrawing procurement specifications across the Baghdad-Basra freight corridor.
Growth Catalysts
- Gulf Standards Alignment:Iraq's Ministry of Transportation updated axle-load regulations to match GCC certification requirements, forcing importers to source homologated chassis and expanding addressable demand for certified manufacturers.
- Oil Sector Distribution:Tank trailers serving refined-product logistics from Basra refineries command sustained replacement demand as downstream infrastructure expands across southern provinces.
- Steel-Aluminum Material Divergence:Premium aluminum-bodied trailers are capturing share in long-haul routes where payload optimization outweighs upfront cost sensitivity among construction material haulers.
Market Restraints
- Steel Price Volatility:Commodity steel trailer production faces margin compression from fluctuating hot-rolled coil input costs, squeezing domestic fabricators lacking long-term supply contracts.
- Import Concentration Risk:Chassis and suspension component supply clusters in Turkish and UAE manufacturing hubs, exposing Iraqi fleet operators to customs delays and currency fluctuation pass-through.
- Desert Climate Degradation:Thermal cycling and sand abrasion accelerate structural fatigue in standard protective coatings, shortening replacement intervals beyond depreciation schedules.
Strategic Opportunities
- Kurdistan Regional Penetration:Erbil and Sulaymaniyah logistics corridors remain undersupplied with authorized service networks, creating first-mover advantage for localized parts distribution.
- Cold-Chain Infrastructure:Refrigerated enclosed trailers face minimal competition outside Baghdad as pharmaceutical and perishable food distribution networks expand into secondary cities.
- Digital Load Monitoring:Integration of telematics with axle-weight sensors is enabling real-time compliance documentation for Ministry of Transportation inspection protocols.
Industry Challenges
- Welding Certification Bottlenecks:Iraq's Central Organization for Standardization and Quality Control mandates periodic load-testing protocols that require certified inspection personnel, creating queue delays at approved facilities.
- Spare Parts Inventory Synchronization:Mismatched component specifications between GCC-certified and legacy steel fleets force distributors to carry duplicate inventory lines, tying up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Trailer Market |
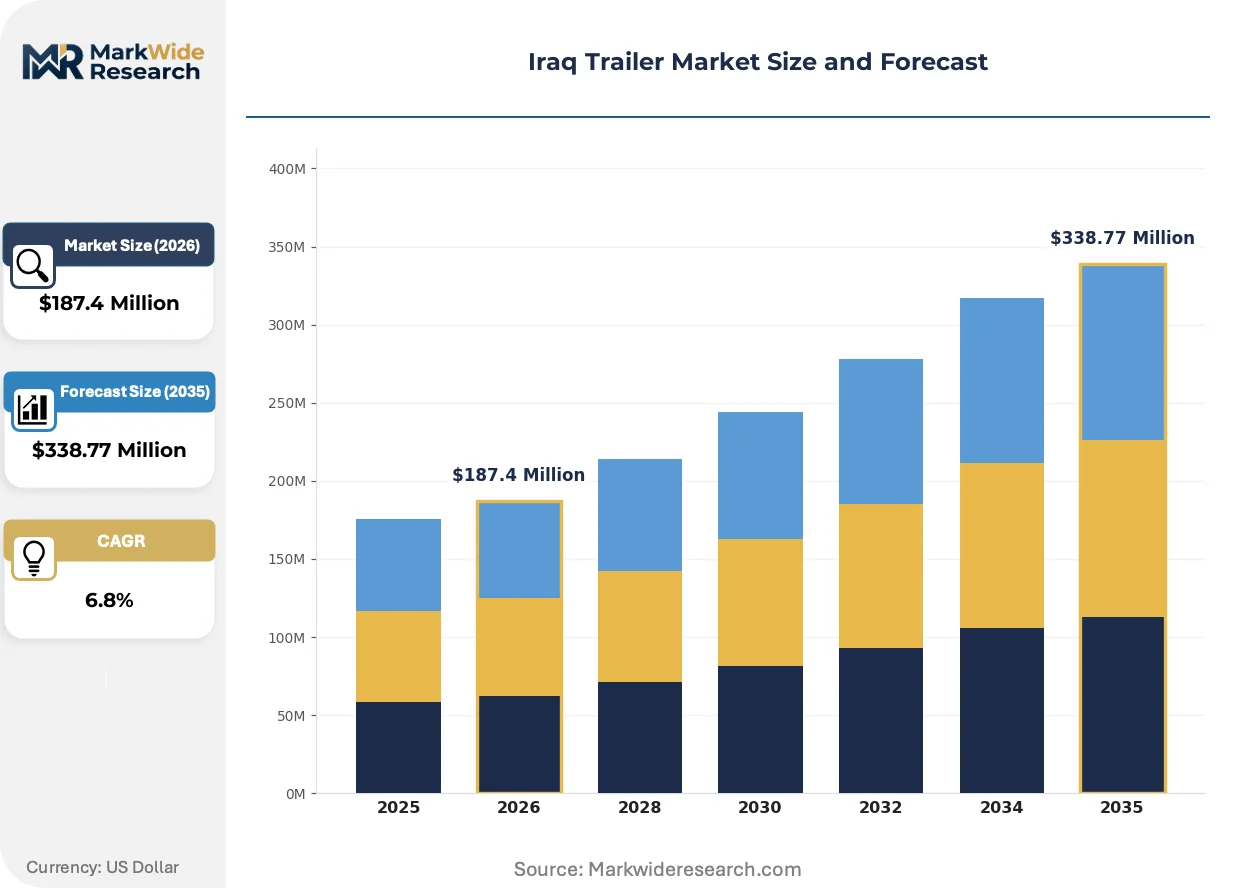
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Trailers, Drop Deck Trailers, Tank Trailers, Enclosed Trailers End User: Transportation Companies, Construction Firms, Oil & Gas Sector, Logistics Providers Size: Lightweight Trailers, Medium-weight Trailers, Heavy-duty Trailers, Specialized Trailers Material: Steel, Aluminum, Composite, Carbon Fiber |
| Companies Covered | Hyundai Motor Company, China International Marine Containers (Group) Ltd., Wabash National Corporation, Great Dane LLC, Utility Trailer Manufacturing Company, MANAC Inc., Al-Fahd Auto, Al-Rashed United Shipping Services, Crown Logistics Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Trailer Market Trends and Innovations
Telematics integration and material science advances are reconfiguring how Iraqi fleet operators manage asset utilization and regulatory compliance across extreme climate conditions.
Air-ride suspension systems are decentralizing maintenance scheduling across heavy-haul operators serving the Tigris-Euphrates basin. Construction firms operating 40-ton payload flatbeds are retrofitting existing steel chassis with pneumatic alternatives to reduce cargo damage on deteriorated road segments. This technology shift is compressing the traditional replacement cycle by enabling modular upgrades rather than full chassis retirement.
Iraq's Ministry of Transportation axle-load enforcement protocols now require documented weight compliance at provincial checkpoints. The regulation is forcing importers to spec load-cell integration at the factory level rather than retrofitting domestically. Tank trailer operators serving Basra's refined-product terminals face the steepest compliance costs, driving consolidation toward larger fleet operators with in-house calibration capabilities.
Leasing arrangements are displacing direct ownership among mid-size construction contractors in southern provinces. Equipment financiers are bundling maintenance and inspection services to offset buyer uncertainty about GCC certification longevity. This pattern concentrates most visibly in Najaf and Karbala, where pilgrimage-driven infrastructure projects demand rapid fleet scaling without balance-sheet commitment.
Iraq Trailer Market Segmentation
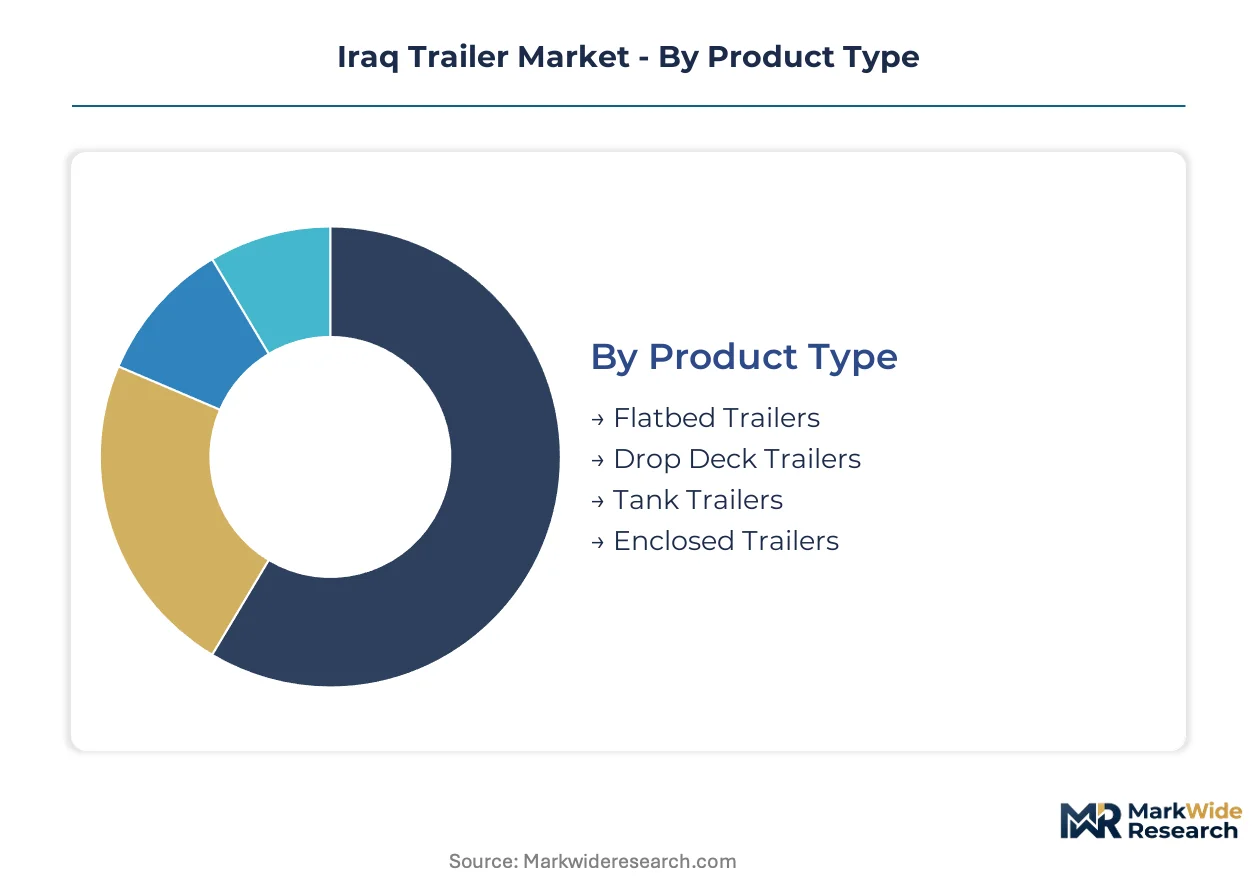
Segmentation reveals how procurement patterns diverge across Iraq's freight corridors. Construction material haulers prioritize payload optimization while oil sector operators demand specialized tank configurations. Understanding these splits clarifies where certified manufacturers can defend margin positions against commodity competitors.
Product Type:
Standalone trailers dominate fleet purchases where chassis flexibility matters, while embedded configurations concentrate in integrated logistics contracts.
- Flatbed Trailers:Open-deck steel or aluminum platforms rated for 20-40 ton payloads serve construction material haulage across the Baghdad-Basra corridor. Demand concentrates with mid-size contractors in Najaf and Karbala where pilgrimage infrastructure projects require rapid fleet scaling without long-term ownership commitment.
- Tank Trailers:Cylindrical vessels with baffled compartments transport refined petroleum products from Basra refineries to distribution terminals. Basra's downstream expansion sustains replacement cycles as downstream operators face steep Ministry of Transportation compliance costs for load-cell integration.
- Drop Deck Trailers:Lower deck height accommodates oversized machinery with reduced center of gravity for stability on deteriorated road segments.
- Enclosed Trailers:Insulated box configurations remain nascent outside Baghdad as cold-chain logistics for pharmaceuticals and perishables develop slowly in secondary cities.
Flatbed trailers lead volumes today; tank trailers are gaining share fastest.
End User:
Cost-tier stratification separates fleet operators with in-house calibration capabilities from contractors dependent on bundled leasing services.
- Construction Firms:Material haulers operating across southern provinces favor aluminum-bodied flatbeds where payload optimization outweighs upfront cost sensitivity. Erbil and Sulaymaniyah logistics corridors remain undersupplied with authorized service networks.
- Oil & Gas Sector:Downstream operators command premium margins through specialized tank trailer fleets serving refined-product distribution from Basra terminals. Thermal cycling and sand abrasion accelerate structural fatigue beyond standard depreciation schedules.
- Transportation Companies:General freight operators face margin compression from steel price volatility and import concentration risk in Turkish and UAE manufacturing hubs.
- Logistics Providers:Third-party operators are integrating telematics with axle-weight sensors to enable real-time compliance documentation for provincial checkpoint protocols.
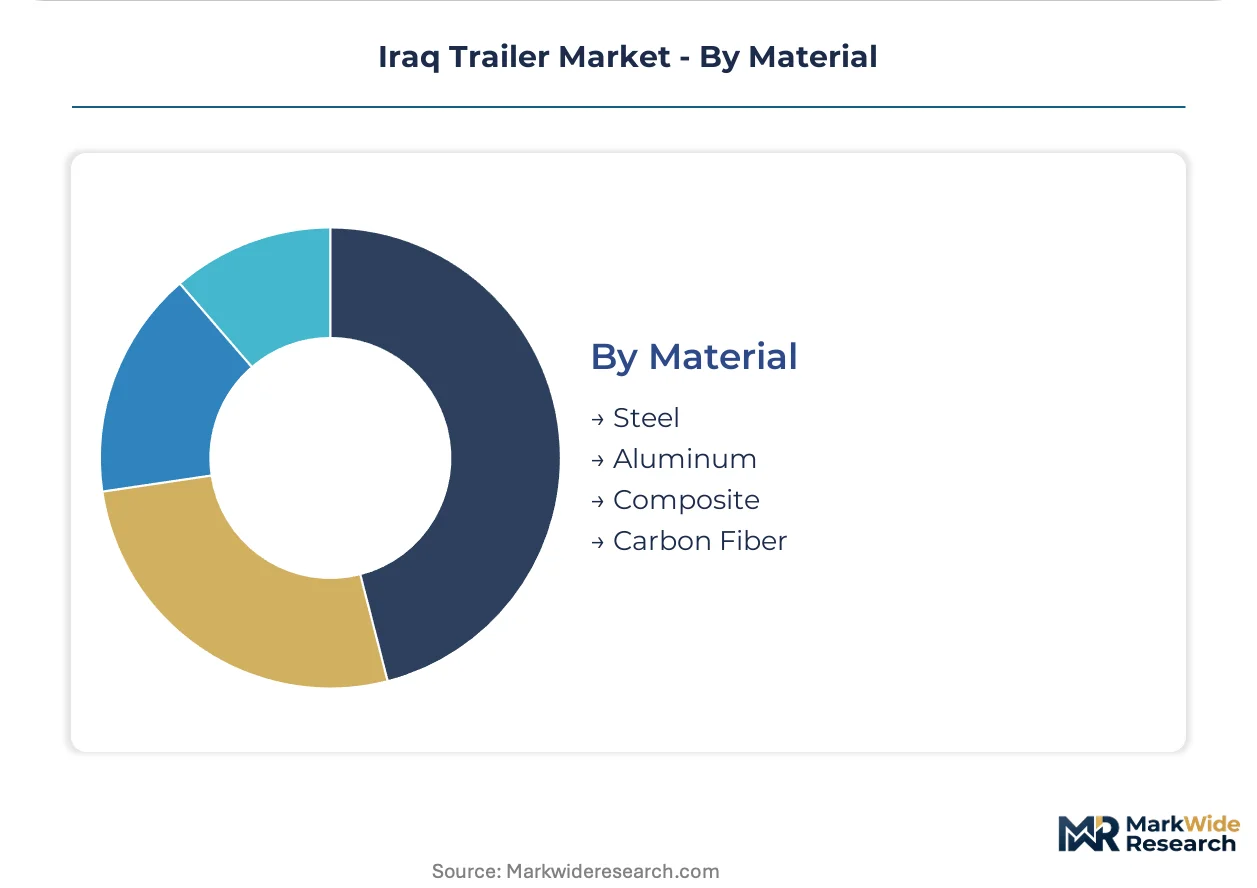
Construction firms anchor procurement volumes today; logistics providers are expanding fleet share fastest.
Size:
Volume distribution skews toward heavy configurations where axle-load harmonization with Gulf Cooperation Council standards has forced chassis homologation upgrades.
- Heavy-duty Trailers:40-80 ton rated chassis serve mining and infrastructure haulage across desert terrain with reinforced suspension systems. Air-ride retrofits are compressing replacement cycles by enabling modular upgrades rather than full chassis retirement.
- Medium-weight Trailers:20-40 ton configurations balance payload capacity with fuel efficiency for regional distribution networks.
- Lightweight Trailers:Sub-20 ton units serve urban last-mile delivery where maneuverability constraints dominate specification requirements.
- Specialized Trailers:Custom-engineered configurations address project-specific dimensional and weight requirements for oversized cargo.
Heavy-duty trailers dominate revenue today; medium-weight configurations are climbing the fastest.
Material:
Margin structure separates premium aluminum suppliers from commodity steel fabricators lacking long-term supply contracts.
- Steel:Hot-rolled coil construction dominates entry-level fleet purchases where upfront cost sensitivity overrides lifecycle economics. Domestic fabricators face working capital strain from duplicate inventory lines forced by mismatched component specifications between GCC-certified and legacy fleets.
- Aluminum:Alloy construction reduces tare weight for payload optimization on long-haul routes where fuel costs and axle-load compliance intersect. Kurdish province distributors are capturing first-mover advantage with localized parts networks.
- Composite:Fiberglass-reinforced panels offer corrosion resistance in coastal humidity conditions around Basra terminals.
- Carbon Fiber:Ultra-lightweight construction remains confined to specialized aerospace and military logistics applications with limited commercial penetration.
Steel retains volume leadership today; aluminum is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welding technicians and certified inspection personnel concentrate in the Tigris-Euphrates freight basin, anchoring trailer fabrication and maintenance capacity across Iraq's logistics corridors. This workforce distribution shapes where fleet operators source equipment and where distributors establish service networks.
Baghdad Governorate
Construction material haulers drive flatbed procurement for pilgrimage infrastructure projects in Najaf and Karbala corridors. The Ministry of Transportation enforces axle-load compliance protocols at provincial checkpoints. Sadr City industrial zones host steel fabrication workshops serving mid-size contractors with legacy fleet maintenance.
Basra Governorate
Downstream oil operators command tank trailer replacement cycles serving refined-product distribution terminals. The Central Organization for Standardization and Quality Control mandates load-testing protocols that accelerate retirement of aging steel fleets. Umm Qasr port logistics clusters concentrate chassis import handling and customs clearance operations.
Erbil Governorate
Kurdish logistics corridors remain undersupplied with authorized service networks, creating first-mover opportunities for parts distributors. Regional government procurement guidelines favor suppliers with localized maintenance capabilities. Kawergosk industrial zone anchors assembly partnerships for regional distribution into Sulaymaniyah.
Anbar Governorate
Cross-border freight operators face customs harmonization delays at Trebil and Al-Qaim border crossings with Jordan and Syria. Federal infrastructure spending prioritizes highway rehabilitation along the Baghdad-Amman corridor. Ramadi commercial districts concentrate used trailer trading and informal refurbishment workshops.
Dhi Qar Governorate
Agricultural cooperatives generate emerging demand for lightweight trailers serving date palm and grain distribution networks. Provincial transport authorities coordinate with federal regulators on GCC certification alignment timelines. Nasiriyah logistics hubs develop cold-chain pilot programs for perishable crop exports.
Iraq Trailer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Iraq's trailer procurement channels. Steel fabricators with in-house rolling mills and coating facilities anchor the commodity tier, while aluminum specialists and technology integrators occupy premium positioning. The vendor base fragments across Turkish manufacturing partnerships, Gulf-certified assemblers, and domestic refurbishment workshops. Three archetypes dominate: regional brand licensors leveraging GCC certification, localized service network operators, and integrated logistics providers bundling fleet financing with maintenance. Competitive moves concentrate on distribution partnerships with provincial contractors and backward integration into suspension component supply.
Among Korea-based manufacturers, Hyundai Motor Company exemplifies the regional brand licensor archetype through assembly partnerships in Kurdish provinces. Wabash National Corporation represents North American technology leadership in advanced suspension systems for heavy-haul routes. Al-Fahd Auto anchors the localized service network tier with spare-parts distribution capabilities across southern provinces. These three players occupy distinct competitive positions without direct overlap in procurement channels or geographic coverage.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| China International Marine Containers (Group) Ltd. |
| Wabash National Corporation |
| Great Dane LLC |
| Utility Trailer Manufacturing Company |
| MANAC Inc. |
| Al-Fahd Auto |
| Al-Rashed United Shipping Services |
| Crown Logistics Ltd. |
| Others |
Pricing and Supply Chain Analysis
Skilled welding technicians and certified inspection personnel concentrated in the Tigris-Euphrates freight basin anchor labor-cost differentials that widen pricing-tier spreads between premium aluminum-bodied trailers and commodity steel models across Iraq's commercial fleet channels.
Pricing Analysis
Bundled leasing services with maintenance and inspection packages separate from unbundled direct-ownership transactions across southern provinces. Three-tier pricing structure across premium aluminum, certified steel, and economy legacy steel levels reflects GCC certification alignment and payload optimization capabilities. Pricing pressure stems from hot-rolled coil input cost volatility squeezing domestic fabricators lacking long-term supply contracts. Mid-size construction contractors in Najaf and Karbala exhibit highest price sensitivity due to pilgrimage-project fleet scaling demands without balance-sheet commitment.
Supply Chain Analysis
Workforce availability constraints in Turkish and UAE manufacturing hubs tether chassis and suspension component supply to extended lead times for Iraqi fleet operators. Production draws from Turkish rolling mills, UAE coating facilities, and Korean assembly partnerships for regional distribution. Hot-rolled coil, aluminum alloy sheet, and pneumatic suspension systems constitute critical input dependencies. Single-source vulnerability in GCC-certified chassis homologation creates customs delay exposure at Umm Qasr port. Distribution runs through provincial contractor networks with authorized service capabilities in Baghdad-Basra corridor and Kurdish provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's trailer market reads as a late-cycle quality story where construction firms and oil sector operators are shifting procurement toward GCC-certified aluminum configurations that optimize payload capacity against axle-load compliance costs.
For Market Incumbents: Anchor defensive positioning through backward integration into suspension component supply and captive coating facilities to offset steel price volatility. Hyundai Motor Company and Wabash National Corporation should deepen GCC certification investment to capture replacement cycles accelerated by Ministry of Transportation load-testing protocols. Threat concentration lies in leasing-financier bundling models that displace direct ownership among mid-size contractors. For New Entrants and Emerging Players: Enter via authorized service network gaps in Erbil and Sulaymaniyah logistics corridors where Kurdish regional procurement guidelines favor localized maintenance capabilities. Cold-chain infrastructure for refrigerated enclosed trailers outside Baghdad presents the most penetrable white-space as pharmaceutical distribution networks expand. A parts-distribution-first go-to-market angle reduces upfront capital requirements while building contractor relationships. For Investors and Strategic Acquirers: Integrated logistics providers with fleet financing and maintenance bundling capabilities are the most active acquirer in this space, consolidating mid-size operators facing steep compliance costs. Long-term viability hinges on exposure to federal infrastructure spending trajectories and provincial customs harmonization timelines. Acquisition targets should display aluminum trailer specialization with established GCC certification pathways. The signal to watch is Ministry of Transportation enforcement intensity at provincial checkpoints as inflection indicator for certified fleet replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Suspension Components | Captive supply of air-ride systems reduces dependency on Turkish manufacturing hubs and customs exposure. |
| GCC Certification Investment | Alignment with Iraq's Ministry of Transportation axle-load regulations unlocks federal and provincial procurement channels. |
| Authorized Service Network Expansion | Localized parts distribution in Kurdish provinces addresses undersupply gaps and captures regional government contracts. |
| Telematics Integration Partnership | Load-cell sensor bundling enables real-time compliance documentation for provincial checkpoint protocols. |
| Leasing-Financier Alliance Formation | Equipment financing with maintenance services targets mid-size contractors seeking rapid fleet scaling without ownership commitment. |
Research Methodology
Multiple input streams — fleet operator interviews, distributor channel assessments, regulatory documentation, and trade flow analysis — were reconciled to construct market estimates for Iraq's trailer sector. Primary engagement with maintenance directors at construction firms, procurement leads at oil sector downstream operators, aftermarket service heads, and Ministry of Transportation officials provided operational validation. Secondary sources included customs records for chassis imports, Central Organization for Standardization and Quality Control certification databases, and federal infrastructure budget disclosures. Bottom-up unit economics and top-down sectoral expenditure patterns were triangulated to anchor volume and value outputs.
Data-stream reconciliation across product type, end-user vertical, material composition, and regional governorates shaped the analytical framework over the projection horizon. CAGRs were derived from fitted trend analysis against historical replacement cycles and regulatory enforcement intensity. Modeled segmentation incorporated payload capacity tiers, GCC certification status, and service network density as industry-specific forecast inputs.
Inputs from Ministry of Transportation officials and certified inspection facilities were available through the study window; gaps in provincial customs harmonization timelines and federal infrastructure disbursement schedules introduce uncertainty bands around fleet replacement velocity assumptions. Forecasts reflect documented enforcement protocols and spending authorization trajectories. Material deviation in axle-load regulation implementation or steel input cost volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market