
 Europe Van Market | 2026-2036
Europe Van Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Van Market Foresight
Dealer and direct-fleet sales channels across Europe is fragmenting as manufacturer-owned subscription platforms and B2B digital marketplaces capture growing volume. Stellantis NV leverages its multi-brand van portfolio to sustain dominant share in southern European markets. Renault Group anchors its position through the Kangoo and Master nameplates with strong traction among French utility fleets. Volkswagen AG competes aggressively in the electric van segment with dedicated MEB-platform variants targeting German corporate buyers.
A van is a rigid-body commercial vehicle with unibody or ladder-frame construction, gross vehicle weight ratings spanning 2.8 to 5.0 tonnes, designed for cargo transport or passenger shuttle duty with a single enclosed volume behind the cab. Panel-sided configurations dominate European streets, though glazed passenger derivatives serve airport and hotel shuttle routes. Light Commercial Van products carry the largest revenue pool given their density in urban logistics and tradesman service fleets, while Electric technology segments expand fastest as battery energy density improvements and charging infrastructure density reduce range anxiety for daily-route operators. Chassis Cab variants retain structural importance for upfitters serving ambulance, refrigerated transport, and mobile workshop specializations.
The European Commission enforces CO2 performance standards for light commercial vehicles through binding fleet-average targets administered by the European Environment Agency, while ECHA manages REACH compliance for materials used in battery packs and interior components. CE marking requirements govern whole-vehicle type approval, creating compliance cost barriers for non-European manufacturers seeking market entry. Fleet managers and van lessors must monitor battery residual-value trajectories and charging-depot capital requirements as total-cost-of-ownership calculations displace upfront price in procurement decisions.
Market Dynamics
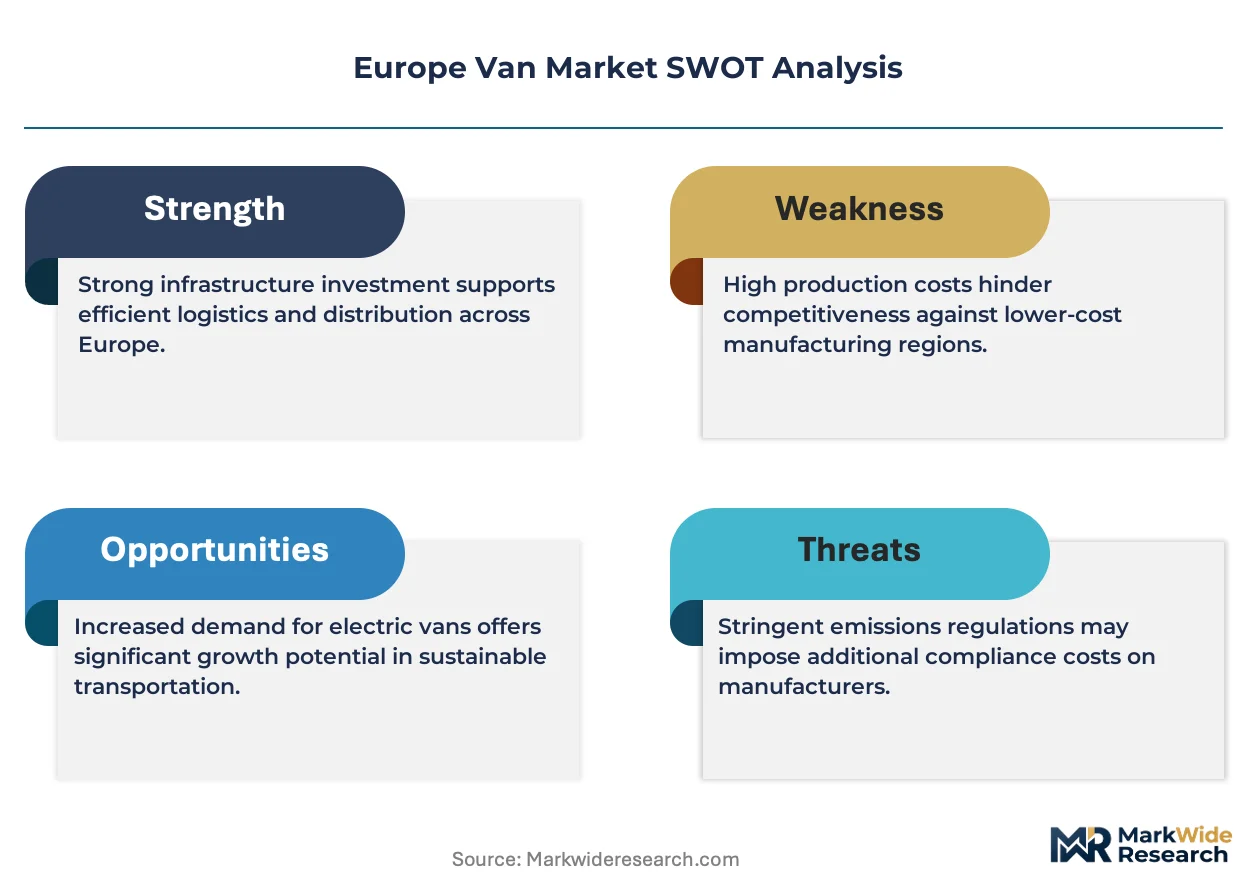
EU Green Deal CO2 performance standards for light commercial vehicles are compressing fleet renewal cycles and forcing powertrain electrification decisions across urban logistics operators before 2030 compliance deadlines bite.
Growth Catalysts
- Urban Low-Emission Zones:Municipal LEZ expansions in Berlin, Paris, and London are mandating zero-emission vehicle entry for commercial operators, pulling forward electric van procurement timelines.
- Last-Mile E-Commerce Density:Parcel volume concentration in dense metropolitan cores is shortening route distances and neutralizing range limitations that previously blocked battery-electric adoption.
- EU Green Deal Fleet Standards:Binding CO2 reduction targets administered by the European Environment Agency are converting manufacturer compliance obligations into subsidized lease rates for fleet buyers.
Market Restraints
- Battery Raw Material Concentration:Cathode active material processing concentrates in China, exposing European van assemblers to supply interruption risks and price volatility for lithium-ion cells.
- Charging Depot Capital Intensity:Fleet electrification requires depot-level DC fast-charging infrastructure investment that compresses operating margins for small and mid-sized logistics contractors.
- Payload-Energy Tradeoff:Current battery energy density forces cargo volume reductions versus diesel equivalents, disqualifying electric vans from certain refrigerated and heavy-goods routes.
Strategic Opportunities
- Polish and Romanian Fleet Markets:Eastern European commercial vehicle penetration lags Western benchmarks, creating first-mover advantage for electric van lessors offering total-cost-of-ownership financing.
- Vehicle-to-Grid Integration:Bidirectional charging capability convergence with smart grid infrastructure positions parked delivery fleets as distributed energy storage assets.
- Subscription Platform Expansion:Manufacturer-owned flexible lease platforms are capturing fleet buyers who prioritize uptime guarantees over asset ownership, bypassing traditional dealer networks.
Industry Challenges
- High-Voltage Technician Scarcity:Electric powertrain maintenance requires certified specialists that vocational training pipelines have not yet produced at fleet-scale volumes.
- Residual Value Uncertainty:Battery degradation curves and second-life market immaturity complicate lease-end valuation models for van lessors underwriting multi-year contracts.
- CE Marking Compliance Timelines:Whole-vehicle type approval processes for new electric variants extend launch windows, delaying model-year competitiveness against established internal-combustion portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Van Market |
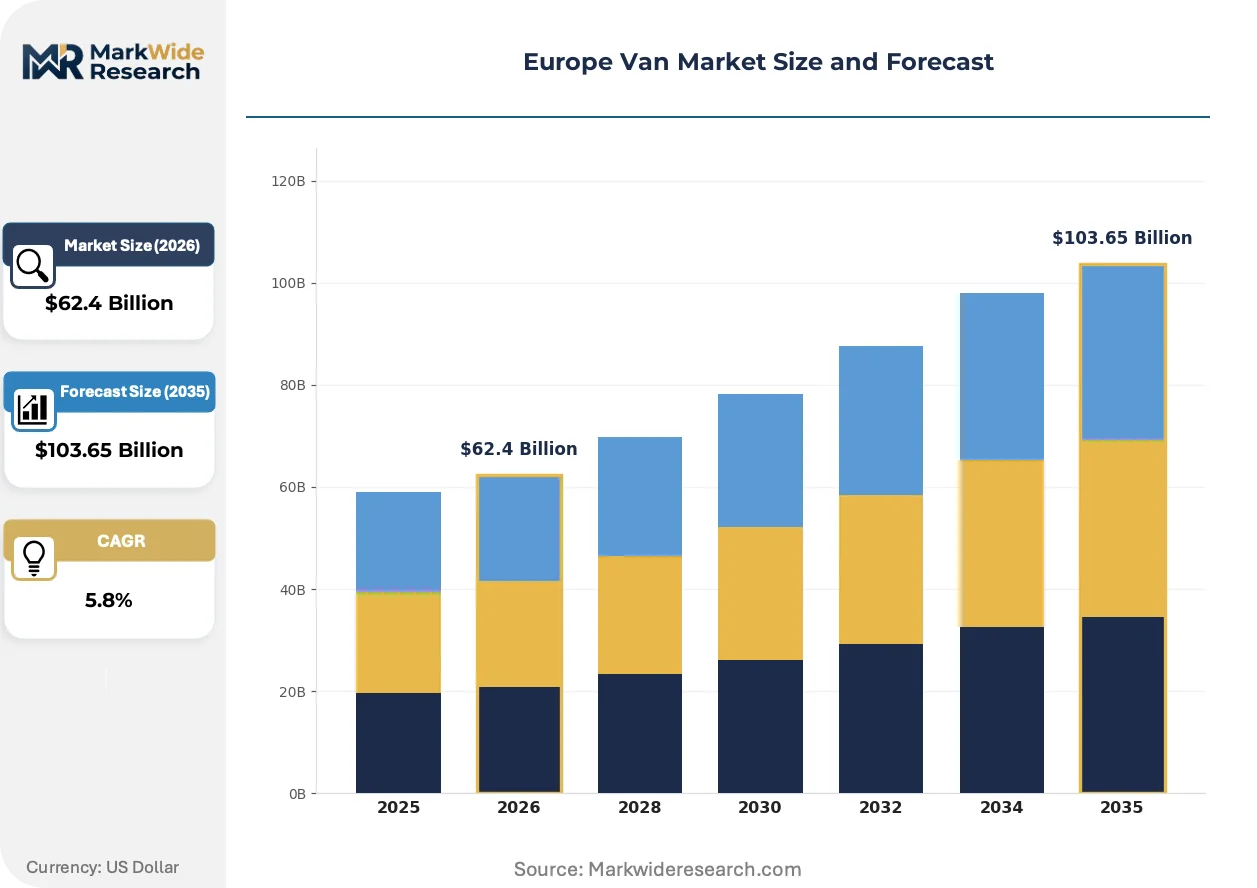
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Commercial Van, Heavy Commercial Van, Chassis Cab, Passenger Van End User: Logistics Providers, Tradesmen, Corporate Fleets, Rental Services Technology: ICE, Hybrid, Electric, Fuel Cell Size: Compact, Midi, Full-size, Long-wheelbase |
| Companies Covered | Ford Motor Company, IVECO Group NV, Stellantis NV, Vauxhall Motors Limited, Daimler AG, Mercedes-Benz Group AG, Renault Group, Arrival Electric Group Limited, Volkswagen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Van Market Shifts & Advancements
Digital fleet management platforms are virtualizing operational control layers, while regulatory pressure and procurement model innovation restructure how commercial vehicles are specified, financed, and maintained across European logistics networks.
Telematics-integrated route optimization software is virtualizing dispatch decisions that previously required human planners. German parcel carriers and French grocery delivery fleets are deploying these systems at scale, compressing miles-per-stop metrics and enabling smaller battery configurations without range anxiety penalties. The technology is virtualizing the traditional tradeoff between vehicle specification and route efficiency.
REACH compliance administered by ECHA is tightening material disclosure requirements for battery packs and interior cabin components. Van manufacturers must now document full substance inventories through supply chains, adding certification overhead that favors larger assemblers with dedicated compliance teams. Light commercial electric variants face the steepest documentation burden due to cell chemistry complexity.
Fleet managers are unbundling maintenance from vehicle acquisition, preferring per-mile service contracts that transfer uptime risk to manufacturers or third-party providers. This displacement of traditional dealer service departments concentrates in the United Kingdom and Netherlands, where logistics operators prioritize balance-sheet flexibility over asset ownership. The shift rewards OEMs with captive service networks and real-time diagnostic capability.
Europe Van Market Segmentation
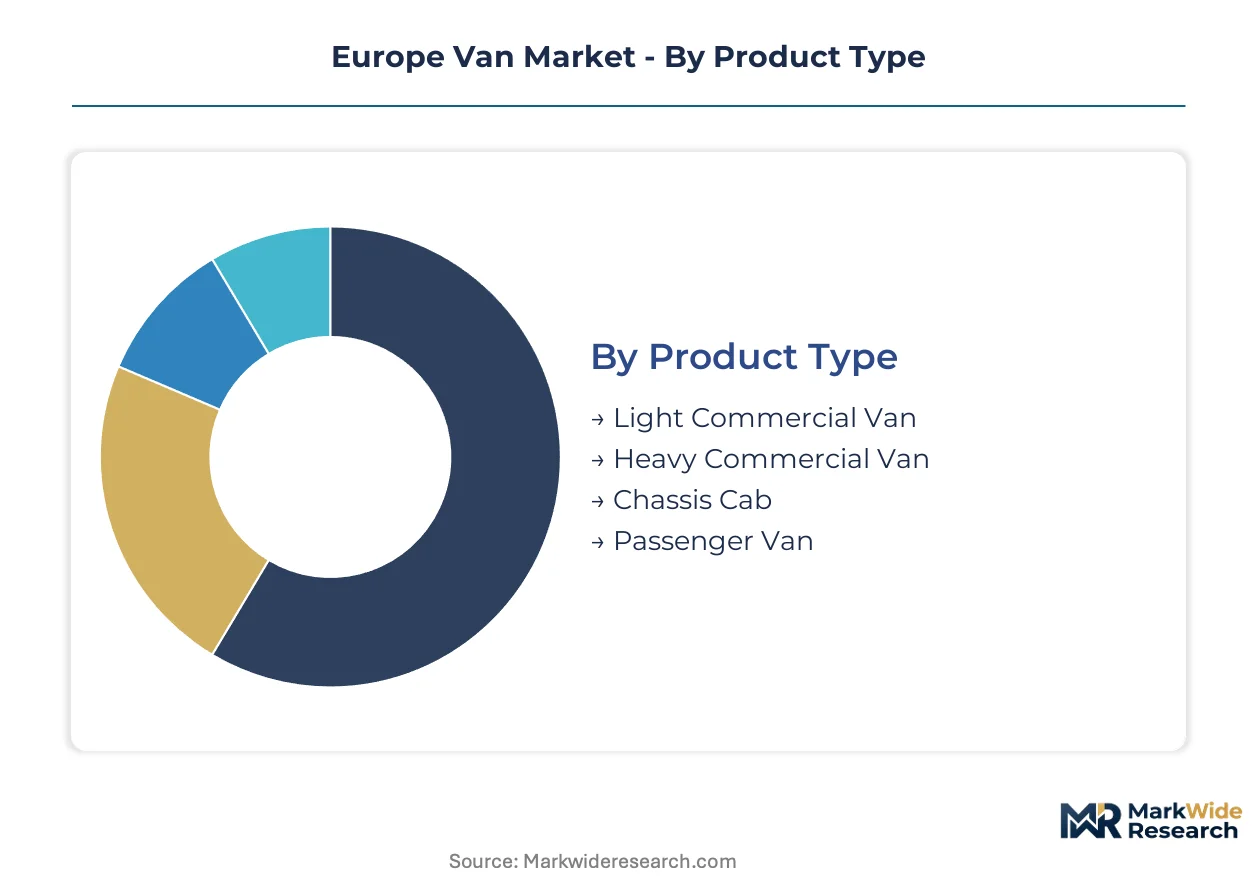
European van procurement patterns fragment sharply across duty cycles and ownership models. Fleet managers specify vehicles differently for high-mileage logistics routes versus intermittent tradesman use, while electrification timelines vary by payload class and depot infrastructure availability.
Product Type:
Light Commercial Vans turn over fastest at 3-4 year cycles in express delivery fleets, while Chassis Cab platforms persist 7-10 years through successive upfit configurations.
- Light Commercial Van:Unibody construction with 2.8-3.5 tonne GVWR dominates urban parcel density in Germany and the Netherlands. Battery-electric variants from Volkswagen and Renault capture German corporate fleet tenders as LEZ deadlines compress replacement schedules.
- Heavy Commercial Van:Ladder-frame architecture spanning 3.5-5.0 tonnes GVWR serves construction material transport and mobile workshop applications. French utility fleets favor these platforms for rural service territories where payload requirements exceed electric range capabilities.
- Chassis Cab:Incomplete vehicle architecture enables ambulance, refrigerated box, and crane body upfitting. Specialist converters in Poland and Italy source these platforms for extended production runs.
- Passenger Van:Glazed derivatives with 9-16 seat configurations serve airport shuttle contracts and hotel transfer services. Spanish tourism corridors generate concentrated demand for mid-size configurations.
Light Commercial Van anchors the volume base while Electric technology variants gain share at the steepest rate across all product types.
End User:
Procurement sophistication separates large-scale fleet lessors from owner-operator tradesmen, with divergent priorities on total-cost-of-ownership versus upfront capital constraints.
- Logistics Providers:Parcel integrators and e-commerce fulfillment operators specify vehicles through centralized procurement functions with telematics integration mandates. DHL and Amazon-linked contractors in the United Kingdom deploy electric vans at depot-scale density.
- Tradesmen:Electricians, plumbers, and HVAC technicians prioritize cargo accessibility and tool storage over fuel economy. Italian and Spanish construction recovery is pulling compact diesel van demand.
- Corporate Fleets:Utility companies and telecommunications operators standardize specifications across national service territories. EDF and BT Group electrification commitments are converting van fleet composition.
- Rental Services:Short-term commercial vehicle lessors emphasize residual value predictability and rapid turnaround capability. Sixt and Europcar flexible lease platforms are expanding electric van availability.
Logistics Providers command the largest contract values while Corporate Fleets expand electric adoption most aggressively.
Technology:
Powertrain selection now hinges on depot charging infrastructure maturity rather than vehicle economics alone, compressing technology transition timelines in Northern Europe.
- ICE:Compression-ignition diesel engines retain dominance in long-distance routes and markets with sparse charging infrastructure. Eastern European corridors still rely on these platforms for cross-border freight.
- Hybrid:Mild-hybrid and full-hybrid architectures bridge range anxiety gaps for mixed urban-highway duty cycles. United Kingdom fleet trials are evaluating these configurations for rural postal routes.
- Electric:Battery-electric powertrains with 200-400 km range are capturing last-mile delivery specifications. Renault Kangoo E-Tech and Fiat E-Ducato lead French and Italian municipal fleet tenders.
- Fuel Cell:Hydrogen fuel cell variants remain demonstration-scale for heavy-duty routes exceeding battery range. German government funding supports pilot fleets in Baden-Württemberg industrial corridors.
ICE retains the installed base while Electric climbs the fastest across new registrations.
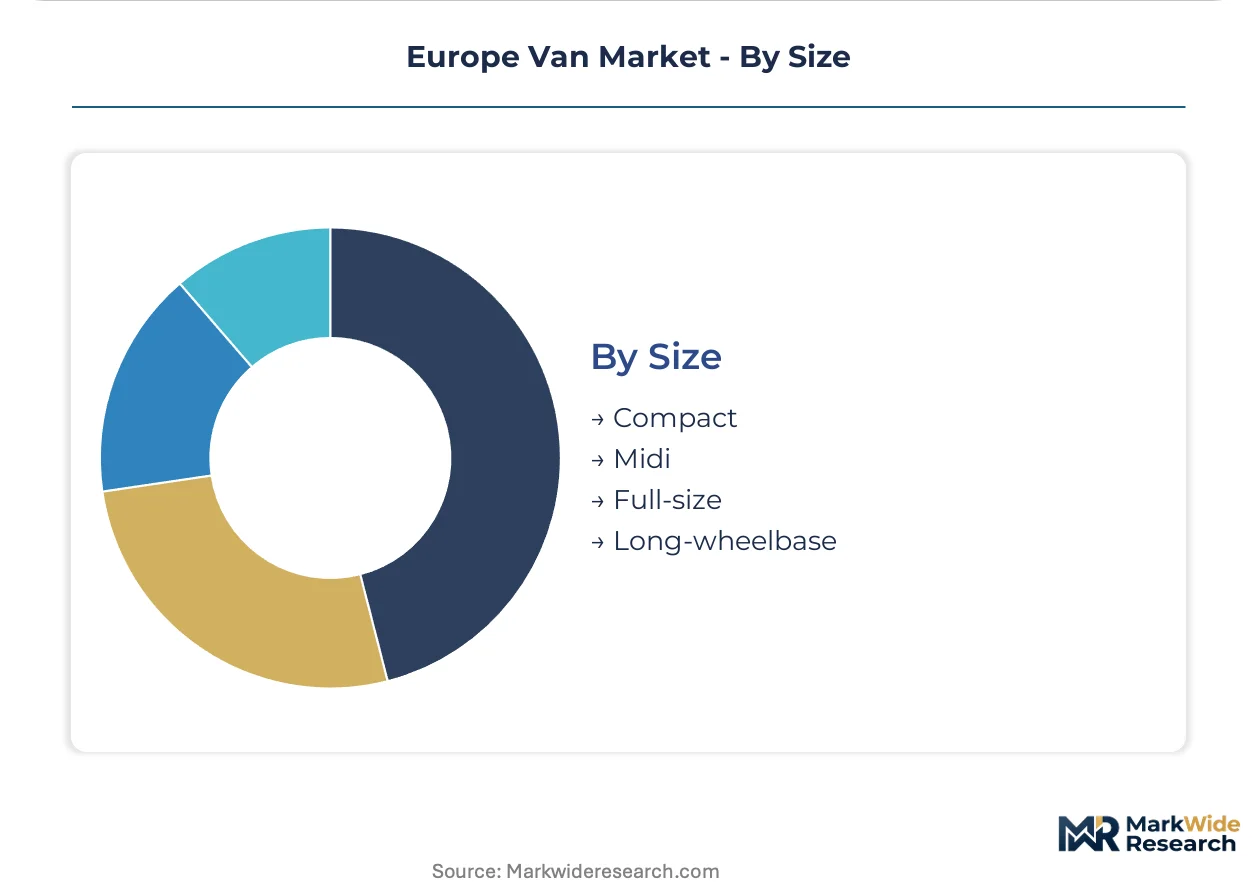
Size:
Urban access regulations and parking scarcity are compressing size specifications in core metropolitan markets while long-wheelbase variants expand in suburban logistics hubs.
- Compact:Sub-4.5 metre length with 600-800 kg payload serves dense city centers with parking constraints. Paris and London congestion charging exemptions favor these configurations.
- Midi:Mid-size platforms balance cargo volume with maneuverability for multi-stop routes. German mid-sized cities specify these for municipal service fleets.
- Full-size:Maximum cargo volume within standard driving license categories dominates express delivery trunk routes. Benelux corridor operators standardize on these for hub-to-depot transfers.
- Long-wheelbase:Extended rear overhang configurations maximize floor space for bulky goods transport. Scandinavian furniture delivery fleets favor these specifications.
Compact sizes dominate urban registrations while Long-wheelbase variants expand fastest in regional distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network and Rotterdam-Antwerp port complex underwrite Northwestern Europe's van logistics density, while Mediterranean container gateways feed Southern European distribution networks.
Germany
Industrial logistics clusters along the Ruhr and Baden-Württemberg automotive corridors generate concentrated van demand from component suppliers. The KBA enforces EU Green Deal CO2 standards through fleet registration audits, accelerating electric van adoption timelines. Berlin's expanding low-emission zone now covers the S-Bahn ring, forcing last-mile operators to electrify or face daily access charges.
France
Parisian congestion charging and the Grand Paris Express construction program sustain high van turnover in Île-de-France logistics. ANSM and environmental prefectures coordinate LEZ enforcement with national CO2 bonus-malus schemes. Renault's Flins and Maubeuge assembly plants anchor domestic van production, with Kangoo E-Tech output prioritizing French municipal fleet tenders.
United Kingdom
E-commerce fulfillment density in the Midlands logistics golden triangle and Greater London last-mile corridors drives replacement demand. The Department for Transport administers zero-emission vehicle mandates through the Office for Zero Emission Vehicles grant programs. Birmingham's clean air zone and Manchester's pending CAZ implementation are compressing diesel van residual values ahead of 2025 deadlines.
Netherlands
Rotterdam port logistics and Amsterdam-Schiphol air freight corridors create high-cycle van utilization patterns. The Dutch Human Environment and Transport Inspectorate enforces EU CO2 performance standards through RDW vehicle approval processes. Eindhoven's Brainport automotive cluster hosts fleet electrification pilot programs linking OEMs with charging infrastructure providers.
Italy
Northern industrial districts in Lombardy and Emilia-Romagna sustain tradesman van demand from machinery and ceramics exporters. The Ministry of Infrastructure and Transport implements EU vehicle type approval through the Motorizzazione Civile. Turin's Mirafiori complex and Atessa plant in Abruzzo concentrate Stellantis van assembly, with E-Ducato output targeting Southern European municipal conversions.
Europe Van Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on battery cells and electric drivetrain modules. The European van market exhibits oligopolistic concentration among legacy automotive groups with captive van architectures, while electric entrants fragment the technology transition layer. Three archetypes dominate: multi-brand conglomerates leveraging shared platforms, national champions defending domestic fleet relationships, and venture-backed electric specialists targeting urban logistics niches. Competitive dynamics center on electrification pace and fleet financing innovation rather than manufacturing scale alone.
Among the established automotive groups, Stellantis NV, Renault Group, and Volkswagen AG exemplify divergent strategic postures. Stellantis occupies a position as the multi-brand platform aggregator, stretching its van portfolio across Fiat, Peugeot, Citroën, and Opel nameplates. Renault anchors the French domestic market through long-standing utility fleet relationships. Volkswagen represents the premium-tier electrification vector, targeting German corporate buyers with dedicated EV architectures.
| Leading Market Players |
|---|
| Ford Motor Company |
| IVECO Group NV |
| Stellantis NV |
| Vauxhall Motors Limited |
| Daimler AG |
| Mercedes-Benz Group AG |
| Renault Group |
| Arrival Electric Group Limited |
| Volkswagen AG |
| Others |
Supply & Pricing Matrix
Cathode active material processing concentrates in China, anchoring lithium-ion cell pricing power with Asian chemical conglomerates while European van assemblers absorb volatility through long-term offtake contracts. Battery pack costs dominate electric van bill-of-materials, compressing downstream margin pools for vehicle integrators and shifting value capture toward cell manufacturers and raw material processors.
Pricing Analysis
Volume-discount tiering structures separate large fleet lessors from owner-operator tradesmen, with DHL-scale procurement commanding standard-economy spreads against single-vehicle retail. Price differentiation hinges on telematics bundling and charging infrastructure inclusion, not hardware alone. Cost compression in the compact van segment is intensifying because Stellantis multi-brand platform economics force competitive matching. Small logistics contractors exhibit highest price sensitivity, while corporate utility fleets prioritize total-cost-of-ownership over upfront capital.
Supply Chain Analysis
Extended payment terms from European OEMs to Tier 1 suppliers now stretch 90-120 days, with supply-chain finance facilities bridging working capital gaps for mid-tier component vendors. Cell manufacturing concentrates in China, South Korea, and Japan, drawing from lithium brine operations in Chile and Australia and cobalt feedstock from the DRC. Single-source vulnerability for high-nickel cathode chemistries exposes assemblers to export restriction risk. Distribution runs through manufacturer-owned subscription platforms and captive finance arms, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's van market constitutes a defensive-moat opportunity where regulatory entrenchment through CE marking and EU Green Deal compliance creates structural barriers against non-European entrants. Fleet relationships and charging infrastructure integration generate switching costs that protect incumbent positions.
For Market Incumbents: Insulate platform economics by backward integration into battery pack assembly and software-defined vehicle architectures. Stellantis and Renault must deepen captive charging infrastructure partnerships before 2030 compliance deadlines harden. Vertical integration into cell module production defends margin position against Asian chemical suppliers.
For New Entrants and Emerging Players: Pursue Polish and Romanian fleet markets where electric van penetration lags Western benchmarks and total-cost-of-ownership financing remains underdeveloped. Arrival-style microfactory approaches suit Eastern European municipal tenders. Subscription platform partnerships with charging network operators offer the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward vehicle-to-grid technology developers and bidirectional charging hardware specialists that monetize parked fleet assets. Long-term viability centers on software-layer differentiation rather than manufacturing scale. Watch battery residual value trajectory data from early European electric van lease returns as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell chemistry partnerships with LG Energy Solution or CATL secure capacity for MEB-platform variants targeting German corporate tenders. |
| Platform Standardization | Stellantis multi-brand architectures spread development costs across Fiat, Peugeot, Citroën, and Opel nameplates. |
| Charging Infrastructure Partnership | Depot-scale DC fast-charging collaborations with Ionity or Fastned reduce fleet operator capital barriers. |
| Software-Defined Vehicle Investment | Over-the-air update capability and telematics integration enable per-mile service contract monetization. |
| Geographic Manufacturing Footprint | Eastern European assembly expansion captures Polish and Romanian fleet growth while hedging Western labor costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at DHL and Amazon-linked contractors, platform engineering leads at Stellantis and Renault, charging infrastructure developers at Ionity, and regulatory affairs specialists at the European Environment Agency. Secondary validation drew from KBA registration databases, ANSM fleet incentive filings, RDW vehicle approval records, and EU Green Deal compliance documentation. Bottom-up triangulation across vehicle production volumes and top-down reconciliation against macroeconomic freight indicators anchored value estimates.
Calibration against historical registration trajectories in Germany, France, and the United Kingdom informed annual growth rate derivation across the projection horizon. Segmentation modeling spanned product type, powertrain architecture, GVWR class, and fleet ownership structure. Forecast inputs incorporated LEZ expansion schedules, battery energy density improvement curves, and charging infrastructure deployment pipelines without specifying timeline years.
Sensitivities concentrate around battery raw material price volatility and high-voltage technician training pipeline throughput. Forecasts reflect documented assumptions on EU CO2 standard stringency and subsidy continuity. Macroeconomic contraction, regulatory delay, or solid-state battery breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Chile Commercial Vehicle Market