
 Electric Truck Market | 2026-2036
Electric Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Truck Market Intelligence
Chinese battery-cell manufacturing is consolidating around CATL and BYD supply bases. Tesla leverages its Nevada gigafactory footprint to anchor North American semi-truck production. Volvo Trucks competes through its VNR Electric platform and European dealer density. BYD dominates commercial vehicle electrification across Shenzhen's port logistics corridor.
An electric truck is a battery-electric or fuel-cell-electric commercial vehicle with a gross vehicle weight rating exceeding 3.5 tonnes, powered by electric motors drawing energy from lithium-ion or solid-state battery packs with typical capacities of 200–600 kWh, designed for freight hauling, urban distribution, and vocational duty cycles. Heavy-duty configurations command the steepest capital outlays but carry the largest fuel-cost arbitrage potential against diesel equivalents. Battery swapping infrastructure is gaining traction in logistics corridors where uptime economics outweigh overnight depot charging. Solid-state chemistry remains pre-commercial but holds the highest energy density promise for long-haul routes.
The EPA Phase 3 standards, California's Advanced Clean Trucks regulation, and the EU's CO2 performance standards for heavy-duty vehicles collectively mandate zero-emission sales quotas that force OEM portfolio restructuring. China's MIIT new-energy vehicle credit system and GB/T charging protocols shape product certification and interoperability requirements for market entry. Stakeholders must weigh battery chemistry roadmaps against charging infrastructure buildout timelines when committing capital to fleet conversion programs.
Market Dynamics
The EPA Phase 3 greenhouse gas standards are compressing diesel truck production timelines while battery swapping infrastructure rewrites uptime economics for fleet operators in high-frequency logistics corridors.
Growth Catalysts
- EPA Phase 3 Standards:The US heavy-duty vehicle emissions framework mandates escalating zero-emission sales quotas through 2032, forcing OEMs to accelerate electric platform development and pre-selling compliance credits.
- Last-Mile Logistics Electrification:E-commerce fulfillment networks in urban cores are procuring battery-electric box trucks to circumvent diesel bans in city centers and reduce per-mile operating costs.
- Lithium-Iron-Phosphate Chemistry:CATL and BYD cell architectures are displacing nickel-cobalt-manganese formulations in commercial vehicle packs, improving cycle life and thermal stability for vocational duty cycles.
Market Restraints
- Lithium Price Volatility:Spodumene concentrate contract fluctuations from Australian hard-rock mines inject uncertainty into battery pack cost modeling for fleet procurement teams.
- Charging Infrastructure Gaps:Highway corridor DC fast-charging deployment lags behind vehicle homologation schedules, stranding long-haul electric trucks on depot-only routes.
- Grid Interconnection Queues:Utility upgrade timelines for megawatt-scale fleet charging depots extend 18-36 months in constrained transmission zones, delaying conversion programs.
Strategic Opportunities
- Battery Swapping Networks:Standardized pack formats and automated exchange stations are emerging along Shenzhen-Guangzhou freight corridors, eliminating charging downtime for container drayage operators.
- Vocational Electrification:Refuse collection, concrete mixing, and utility service trucks represent underpenetrated segments where stop-and-go duty cycles maximize regenerative braking returns.
- California Advanced Clean Trucks:The state's manufacturer sales mandate creates guaranteed demand pull for zero-emission medium- and heavy-duty vehicles through 2035, anchoring West Coast production commitments.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance departments lack certified electricians capable of servicing 800-volt architectures, forcing reliance on OEM service networks and extending repair timelines.
- Residual Value Uncertainty:Secondary market buyers hesitate to price used electric trucks without standardized battery health reporting protocols, compressing lease residual assumptions and raising financing costs.
- Software Integration Complexity:Telematics platforms must reconcile legacy fleet management systems with new electric powertrain data streams, requiring custom API development for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Truck Market |
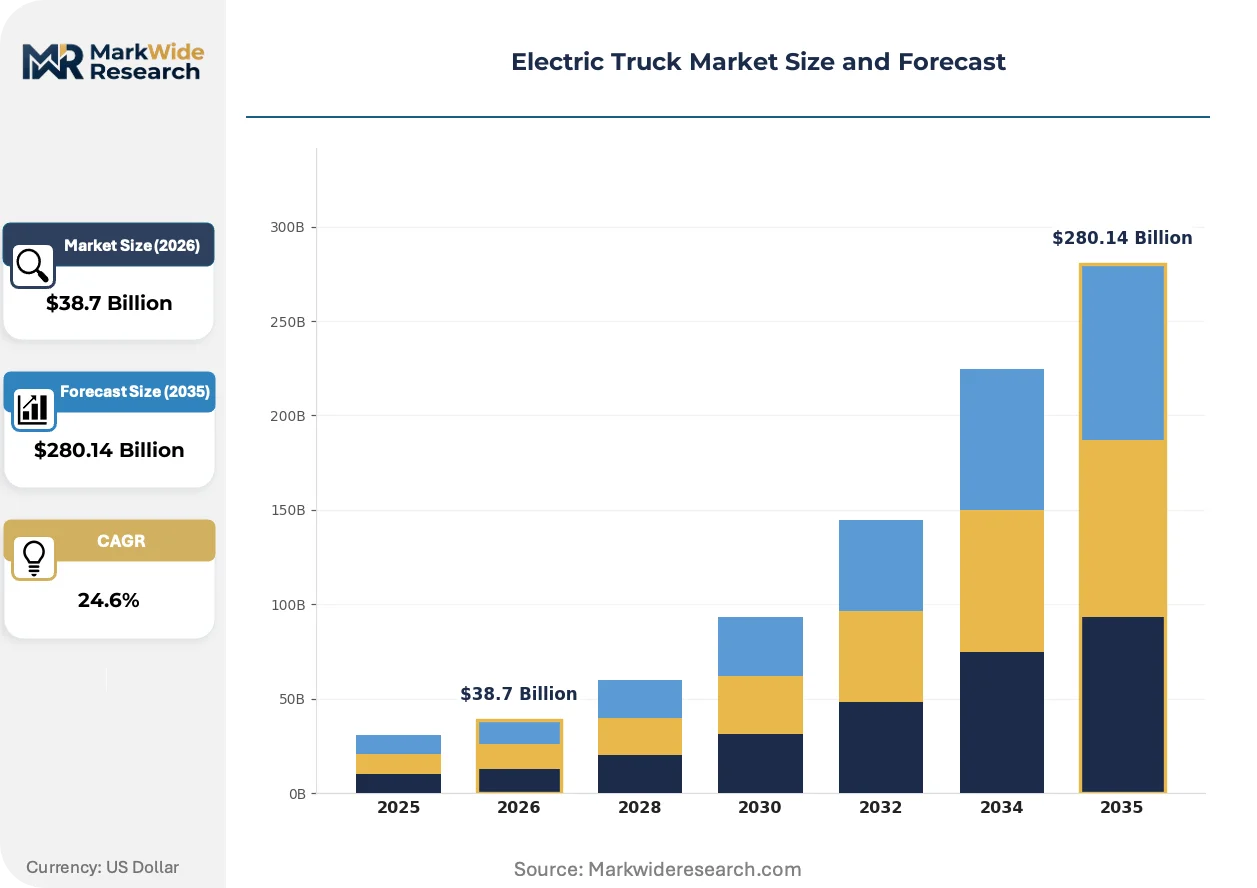
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Medium-Duty, Light-Duty, Commercial Battery Technology: Lithium-Ion, Solid-State, Nickel-Cobalt, Lead-Acid End User: Logistics, Public Transport, Construction, Agriculture Charging Infrastructure: Fast Charging, Ultra-Fast Charging, Standard Charging, Battery Swapping |
| Companies Covered | Tesla, Rivian Automotive, BYD, Volvo Trucks, Daimler AG, PACCAR, Scania AB, Nikola Corporation, Ford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Truck Market Strategic Shifts & Innovations
Solid-state battery prototyping and automated battery swapping are converging to reshape long-haul viability, while regulatory compliance frameworks fragment across major automotive markets.
Silicon-anode lithium-ion cells are rewriting energy density benchmarks for commercial vehicle applications. Daimler Truck and Volvo Group are validating 400 Wh/kg prototypes for 2026 platform integration. This chemistry is compressing pack mass penalties and extending single-charge range thresholds for regional haul routes.
EU CO2 performance standards for heavy-duty vehicles now impose binding fleet-average emissions limits with penalty structures exceeding €4,000 per non-compliant vehicle. The regulation is forcing European OEMs to pool zero-emission sales credits and accelerate electric truck homologation ahead of 2025 compliance checkpoints. Battery-electric tractors are capturing disproportionate engineering resources as the fastest path to fleet-average compliance.
Power purchase agreements for renewable electricity are displacing conventional fuel hedging in fleet procurement decisions. Large logistics operators in California and Germany are signing 10-year solar and wind contracts to lock in per-mile energy costs below diesel volatility bands. This financial structuring is most advanced among parcel carriers operating fixed-route networks with predictable annual mileage.
Electric Truck Market Segmentation
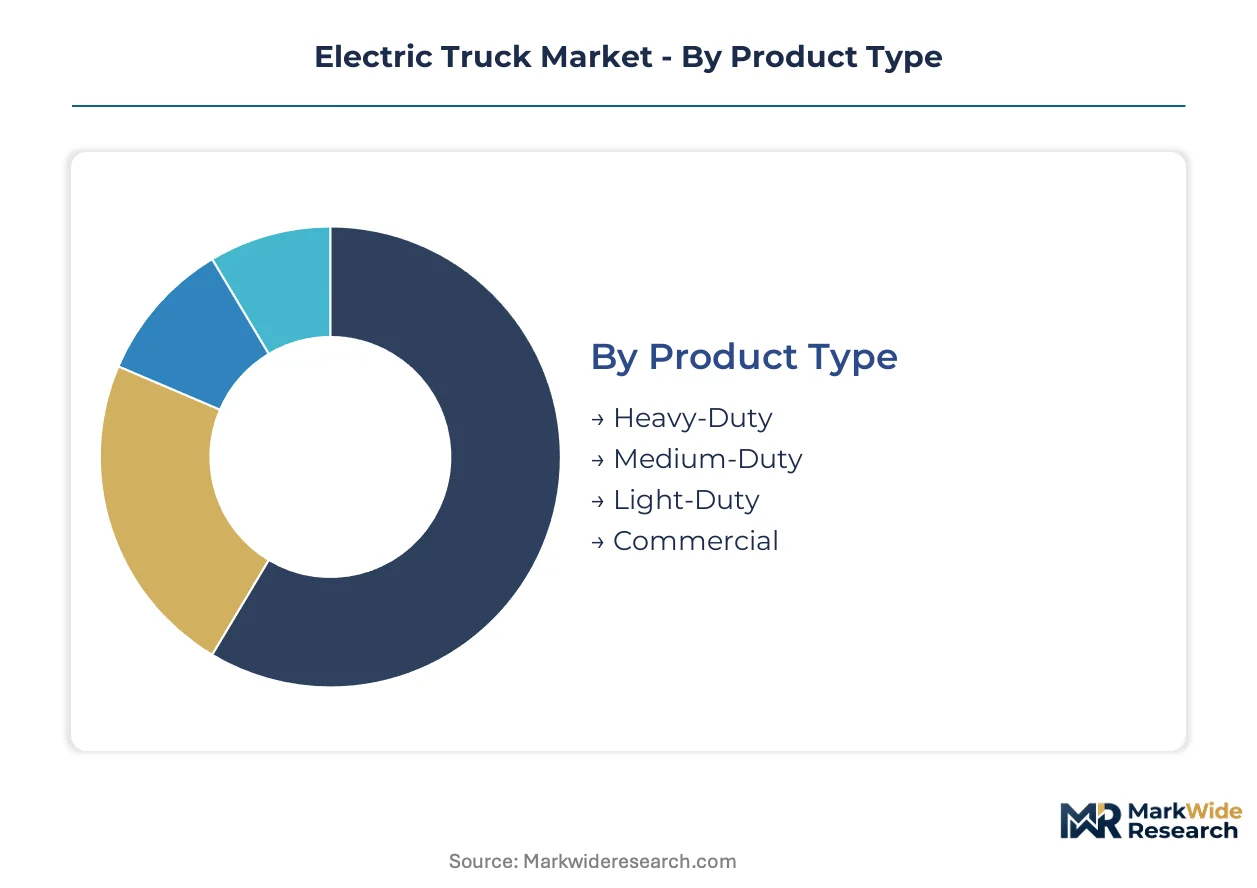
Electric truck segmentation reveals how duty-cycle requirements dictate powertrain architecture and infrastructure pairing. Fleet operators select configurations based on route predictability, payload demands, and depot charging feasibility.
Product Type:
Integration depth varies sharply: heavy-duty platforms function as standalone freight systems, while light-duty units embed within mixed-fleet logistics networks.
- Heavy-Duty:Gross vehicle weight ratings exceed 15 tonnes with battery capacities ranging 400–600 kWh. Long-haul freight operators in Germany's Rhine-Ruhr corridor deploy these for hub-to-spoke distribution where diesel parity calculations favor high-mileage utilization.
- Medium-Duty:Urban delivery chassis with 200–400 kWh packs dominate last-mile fulfillment. Amazon's European logistics subsidiaries have standardized on this segment for city-center access where congestion charges penalize diesel entry.
- Light-Duty:Compact urban vans with sub-200 kWh configurations serve parcel final-mile routing. Postal operators in France prioritize these for residential density zones with 80–150 km daily duty cycles.
- Commercial:Vocational variants include refuse compactors and utility bucket trucks. Stop-and-go duty cycles in Japan's municipal fleets maximize regenerative braking returns for sanitation applications.
Medium-duty leads volumes today; heavy-duty is gaining share fastest as battery energy density climbs.
Battery Technology:
Cost tiering separates proven chemistries from pre-commercial alternatives, with thermal stability and cycle life driving fleet procurement decisions.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate architectures constitute the installed base. CATL's cell-to-pack designs dominate Chinese OEM supply agreements where procurement teams prioritize proven degradation curves.
- Solid-State:Pre-commercial prototypes promise 400+ Wh/kg density with reduced thermal runaway risk. Toyota and QuantumScape validation programs target 2027–2028 homologation for long-haul routes where weight reduction extends single-charge range.
- Nickel-Cobalt:High-energy formulations persist in premium European tractors. Volvo Trucks specifies these for refrigerated haulage where pack volume constraints limit alternatives.
- Lead-Acid:Limited to auxiliary power and low-speed yard tractors. Airport ground support equipment in India retains this chemistry for cost-sensitive baggage handling applications.
Lithium-ion dominates procurement today; solid-state is expanding most quickly as pilot fleets validate durability.
End User:
Application-specific duty cycles determine powertrain sizing and charging infrastructure investment intensity.
- Logistics:E-commerce fulfillment networks and parcel carriers operate the largest deployed fleets. DHL's German hub network has electrified 60% of urban delivery routes with depot-fast-charge combinations.
- Public Transport:Municipal waste collection and street-sweeping vehicles represent captive-route electrification. Barcelona's metropolitan authority has standardized battery-electric refuse trucks for fixed-collection scheduling.
- Construction:Vocational trucks face payload penalties from battery mass. Cement mixers in South Korea's Seoul-Incheon corridor are testing swapping stations to eliminate charging downtime during continuous pour schedules.
- Agriculture:Low-mileage seasonal use cases delay electrification economics. Vineyard service trucks in Italy's Piedmont region trial small-battery configurations for harvest-period spraying and transport.
Logistics leads volumes today; construction is climbing the fastest as swapping infrastructure matures.
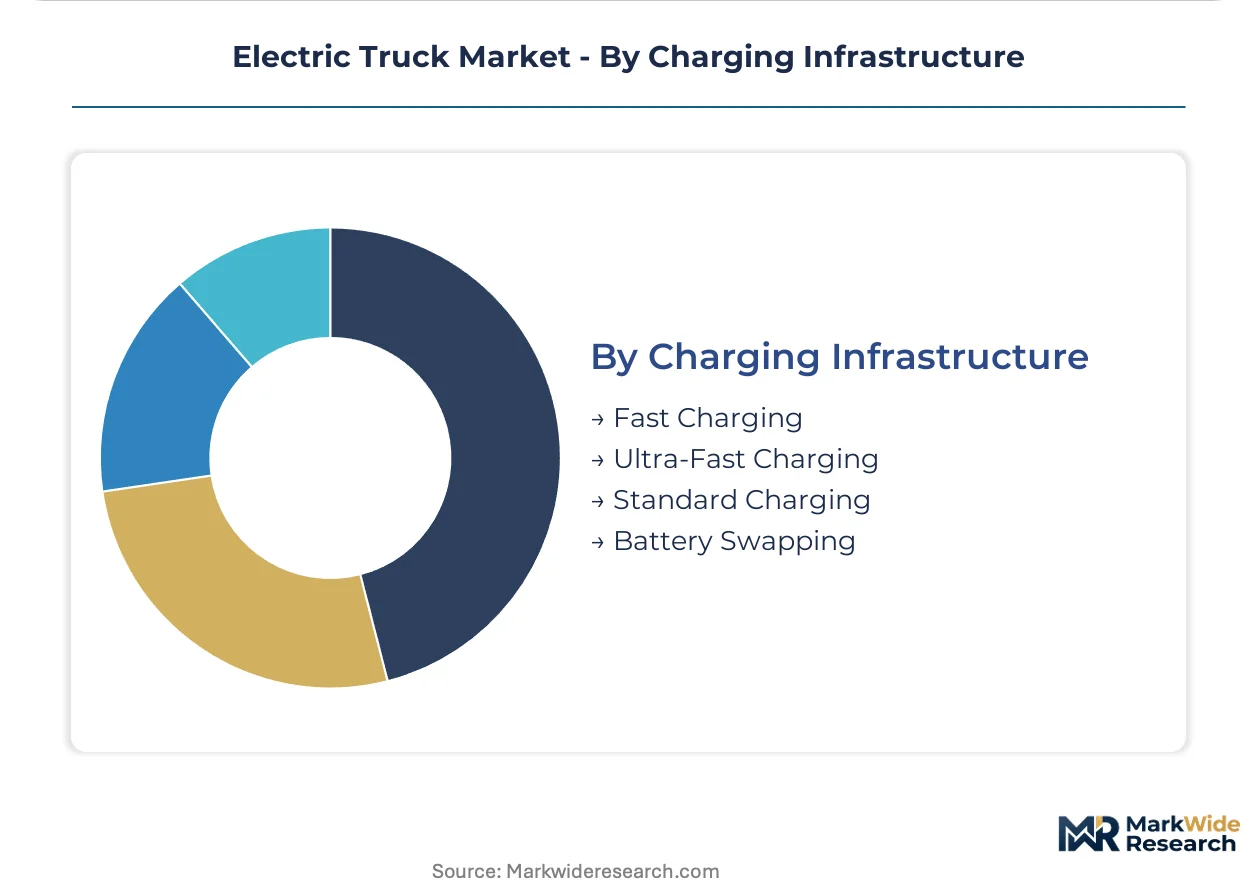
Charging Infrastructure:
Customer type stratification separates fleet operators with predictable depot access from those requiring public corridor coverage.
- Fast Charging:150–350 kW DC systems enable mid-route replenishment for regional haul. Pilot corridors along California's I-5 freight spine validate 30-minute charge windows for 400 km range extensions.
- Ultra-Fast Charging:1 MW+ megawatt systems target 15-minute charge targets for long-haul tractors. Daimler Truck and BlackRock's joint venture is deploying these at German autobahn service areas.
- Standard Charging:50–150 kW AC/DC depot installations serve overnight fleet replenishment. UPS's London hub operates 120-bay standard charging for last-mile van return-to-base operations.
- Battery Swapping:Automated pack exchange eliminates charging downtime entirely. NIO and CATL partnerships are standardizing swap stations across Shenzhen's container drayage network for 24/7 port logistics.
Standard charging leads volumes today; battery swapping is gaining share fastest in high-uptime corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting electric truck production toward jurisdictions with the widest cost-of-compliance gaps between diesel and zero-emission alternatives. Fleet operators and OEMs are relocating assembly and procurement decisions based on subsidy intensity, emissions enforcement timelines, and charging infrastructure deployment schedules.
United States
EPA Phase 3 standards mandate escalating zero-emission sales quotas through 2032, compressing diesel production timelines. California's Advanced Clean Trucks regulation creates guaranteed demand pull for medium- and heavy-duty vehicles through 2035. The Central Valley freight corridor hosts pilot deployments of battery-electric tractors for agricultural distribution networks.
China
MIIT's new-energy vehicle credit system shapes product certification and interoperability requirements for commercial vehicle entry. Shenzhen and Beijing operate the world's largest electric freight corridors with standardized battery swapping infrastructure. The Pearl River Delta concentration anchors CATL and BYD supply bases serving port logistics and urban distribution fleets.
Germany
EU CO2 performance standards for heavy-duty vehicles impose binding fleet-average emissions limits with penalty structures exceeding €4,000 per non-compliant vehicle. The autobahn service area network is deploying megawatt-scale charging through Daimler Truck and BlackRock joint ventures. The Rhine-Ruhr corridor hosts hub-to-spoke distribution pilots for battery-electric long-haul tractors.
Sweden
Volvo Trucks leverages domestic dealer density and VNR Electric platform development to anchor European commercial vehicle electrification. The country's carbon taxation framework accelerates fleet conversion economics against diesel alternatives. Gothenburg's manufacturing cluster integrates silicon-anode cell validation programs targeting 2026 platform integration.
Japan
METI funding programs support solid-state battery prototyping for commercial vehicle applications with 2027–2028 homologation targets. Toyota's validation programs focus on long-haul routes where weight reduction extends single-charge range. The Nagoya industrial corridor concentrates vocational truck electrification for stop-and-go municipal duty cycles.
Electric Truck Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in vocational electrification and swapping infrastructure. The market structures around three tiers: legacy OEMs with dealer networks and service infrastructure, battery-cell specialists backward-integrating into vehicle assembly, and technology entrants leveraging software-defined powertrain architectures. Dominant competitive moves include capacity expansion in cell-to-pack manufacturing and strategic partnerships for charging corridor deployment.
Within the integrated-tier archetype, BYD and Tesla exemplify contrasting geographic anchoring strategies. BYD occupies a position reflecting Shenzhen-based supply chain concentration and port logistics specialization. Tesla represents North American production gravity through Nevada gigafactory footprinting for semi-truck assembly. Volvo Trucks sits within the European legacy tier, leveraging Scandinavian engineering credibility and dealer density across freight corridors.
| Leading Market Players |
|---|
| Tesla |
| Rivian Automotive |
| BYD |
| Volvo Trucks |
| Daimler AG |
| PACCAR |
| Scania AB |
| Nikola Corporation |
| Ford |
| Others |
Cost & Logistics Intelligence
High-voltage battery technician scarcity in Germany's industrial corridor widens pricing-tier spreads between premium OEM service contracts and standard third-party maintenance agreements. Labor-cost differentials between certified 800-volt specialists and conventional diesel mechanics compress margins for fleet operators choosing economy-tier procurement.
Pricing Analysis
Dealer margin layers absorb 12-18 points between factory gate and fleet procurement. Contract-based long-term offtake dominates heavy-duty tractor sales where Daimler Truck and Volvo Group bundle charging infrastructure with vehicle leases. Price differentiation separates refrigerated haulage configurations with nickel-cobalt battery premiums from urban delivery lithium-iron-phosphate standards. Cost compression in medium-duty segments intensifies as CATL cell-to-pack designs displace premium European cell sourcing. Last-mile logistics operators exhibit highest price sensitivity; long-haul freight carriers prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Workforce-availability constraints in Nevada's gigafactory zone and Hungary's battery assembly corridor extend commissioning timelines for new capacity. Cell manufacturing concentrates in China, South Korea, and Japan where CATL, LG Energy Solution, and Panasonic anchor cathode active material supply. Raw material dependencies center on Australian spodumene concentrate, Chilean lithium brine, and Indonesian nickel laterite. Single-source vulnerability in cathode precursor processing creates chokepoint exposure for European OEMs. Distribution runs through captive OEM service networks for high-voltage maintenance, with independent channels limited to light-duty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric truck market functions as a stable compounder where regulatory compliance mandates create inelastic demand pull across fleet replacement cycles.
For Market Incumbents: Anchor service network density in California's Central Valley and Germany's Rhine-Ruhr corridor to defend against battery-swapping entrants rewriting uptime economics. Deepen backward integration into silicon-anode cell production through joint ventures with QuantumScape and Solid Power to secure chemistry roadmaps. Certification investment in EPA Phase 3 compliance credits pre-sells regulatory positioning before 2032 quota acceleration. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms bypass legacy dealer networks for vocational electrification in refuse collection and concrete mixing segments. Target Japan's municipal sanitation authorities where stop-and-go duty cycles maximize regenerative braking returns and incumbent service infrastructure remains thin. Software-defined powertrain architectures with over-the-air update capabilities differentiate against hardware-locked legacy platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among battery-swapping infrastructure operators with standardized pack formats and automated exchange station deployments. Long-term viability over a decade horizon rests on regulatory enforcement durability rather than technology cost curves alone. Watch California Air Resources Board credit pricing as the inflection signal for West Coast demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL's cell-to-pack contracts with Daimler Truck lock in lithium-iron-phosphate capacity for European VAN platforms. |
| Charging Infrastructure Partnership | Daimler Truck and BlackRock's megawatt-scale autobahn deployment anchors German long-haul electrification. |
| Platform Standardization | BYD's Shenzhen port logistics corridor validates interchangeable battery formats across container drayage operators. |
| Software-Defined Vehicle Investment | Tesla's over-the-air powertrain updates compress recall cycles and extend fleet management subscription revenue. |
| Geographic Manufacturing Footprint | Volvo Trucks' Gothenburg cluster integrates silicon-anode validation with VNR Electric platform engineering. |
Research Approach
Bottom-up fleet procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with fleet operations directors, OEM platform engineers, charging infrastructure developers, and utility interconnection planners cross-validated secondary sources including EPA Phase 3 regulatory filings, California Air Resources Board credit transaction databases, and EU CO2 performance standard compliance reports. Customs data on lithium carbonate and spodumene concentrate trade flows triangulated against cell manufacturer capacity announcements.
Input-output matrices map battery energy density improvements and charging infrastructure deployment schedules against fleet replacement cycles across the projection horizon. Segmentation dimensions span vehicle class, battery chemistry, end-use application, and regional regulatory cluster. CAGRs derive from regression analysis of historical fleet electrification penetration correlated with diesel-electric total-cost-of-ownership parity thresholds. Forecast inputs incorporate MIIT new-energy vehicle credit pricing and utility upgrade queue timelines for megawatt-scale depot installations.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for long-haul heavy-duty segments. Forecasts reflect assumptions around EPA enforcement consistency and lithium price volatility bands. Material deviation in California credit pricing or Chinese export licensing protocols warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Van Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Spain Light Commercial Vehicles Market