
 Canada Commercial Vehicles Market | 2026-2036
Canada Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Commercial Vehicles Market Outlook
Fleet operators are reorganizing procurement priorities toward electrified and alternative-fuel platforms for urban delivery routes. Volvo Trucks North America leverages its electric powertrain development to anchor zero-emission segments in Ontario and Quebec corridors. Ford Motor Company sustains dominant positioning in light-duty fleet sales through dealership density and commercial financing structures. Kenworth Truck Company specializes in heavy-duty natural gas configurations for long-haul operators serving Alberta's energy sector.
Canada commercial vehicles encompass motorized transport equipment engineered for goods carriage and passenger transit exceeding personal-use thresholds, typically rated above 4,500 kg gross vehicle weight with chassis architectures designed for vocational modification. Diesel powertrains retain structural dominance in heavy-duty applications due to torque density and refueling infrastructure, though electric segments are capturing share in last-mile delivery where range requirements align with battery economics. Light duty trucks lead volume by unit count, reflecting e-commerce fulfillment expansion and contractor fleet renewal, while hybrid configurations represent the fastest-growing fuel category as operators navigate capital constraints during electrification transitions. Logistics companies constitute the deepest end-user margin pool, driven by contract renewal cycles tied to fuel surcharge mechanisms.
Transport Canada enforces Motor Vehicle Safety Standards under the Motor Vehicle Safety Act, mandating crashworthiness and emissions compliance that shape manufacturer product planning. Environment and Climate Change Canada administers greenhouse gas regulations for heavy-duty vehicles, creating compliance cost structures that favor investment in electric and hydrogen platforms. Health Canada and PMRA coordinate on occupational exposure standards affecting cab material specifications and driver environment requirements. Stakeholders must monitor regulatory timing on zero-emission vehicle mandates and cross-border EPA alignment decisions that determine powertrain portfolio viability across the North American production footprint.
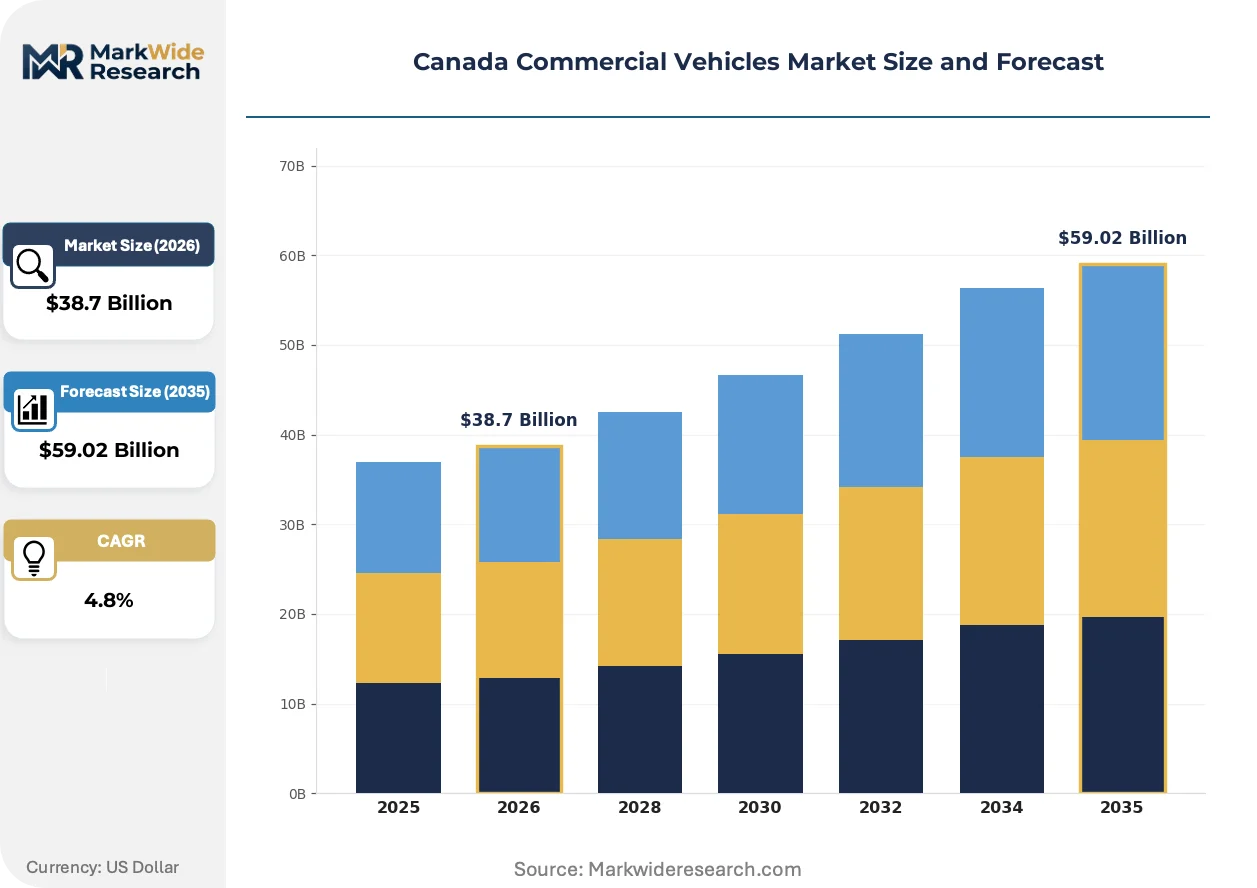
Market Dynamics
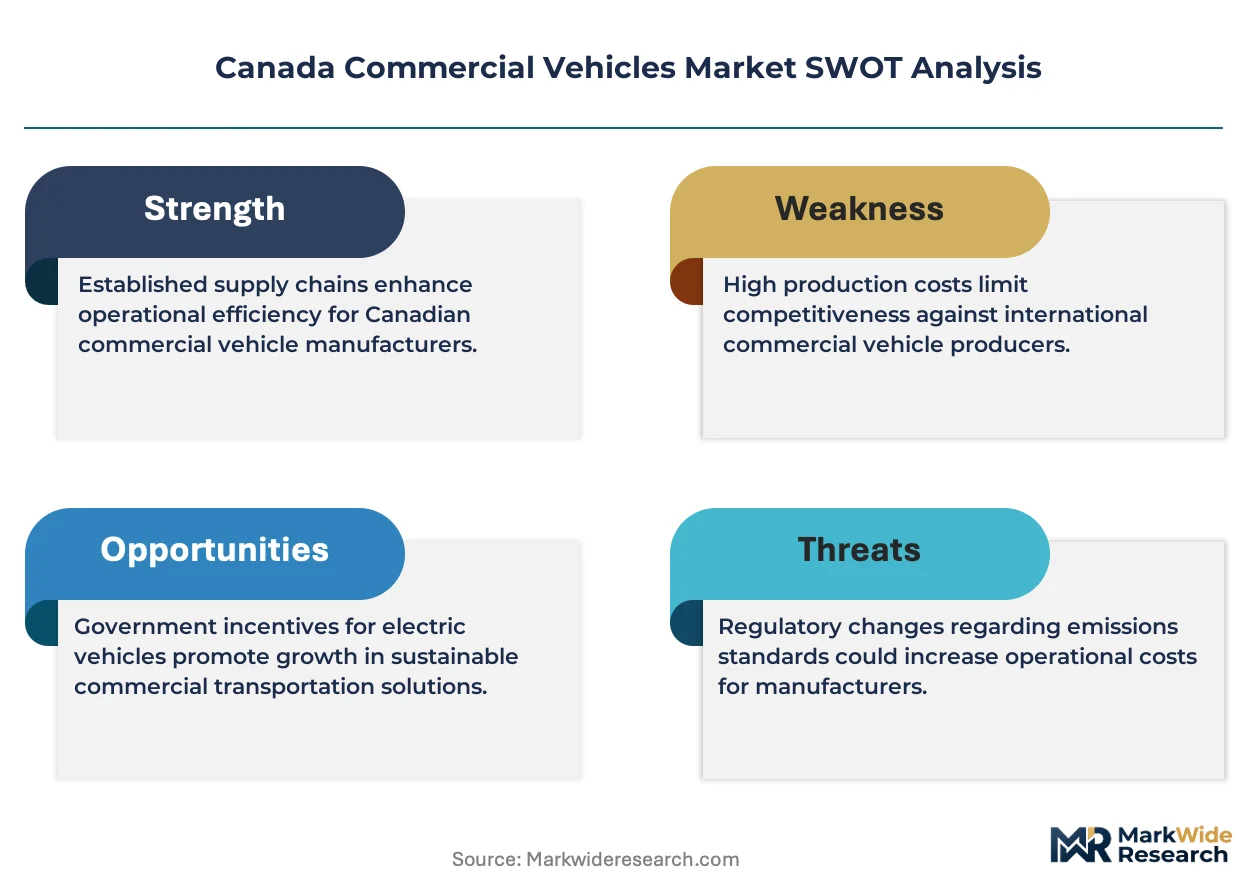
Transport Canada's updated emissions standards under the Canadian Environmental Protection Act are forcing fleet operators to accelerate powertrain diversification across heavy-duty and medium-duty segments, compressing replacement cycles and reshaping procurement priorities toward electrified platforms.
Growth Catalysts
- Alberta Oil Sands Logistics:Fleet operators across this energy corridor are expanding procurement of heavy-duty units to serve expanding extraction operations and pipeline construction schedules.
- Canadian Environmental Protection Act Standards:Transport Canada's regulatory updates create compliance-driven demand for alternative-fuel powertrains and zero-emission vehicle investments.
- Ontario Golden Horseshoe Warehousing Density:Cross-border freight volumes and e-commerce fulfillment centers generate sustained replacement cycles for light-duty commercial fleets.
Market Restraints
- Battery Cost Volatility:Lithium and cobalt price swings compress margins for electric commercial vehicle deployments, particularly affecting medium-duty delivery operators with thin capital reserves.
- Charging Infrastructure Gaps:Sparse high-power charging networks along Trans-Canada Highway corridors limit long-haul electrification feasibility for prairie and mountain routes.
- Diesel Powertrain Entrenchment:Established refueling infrastructure and torque density advantages create substitution resistance among Alberta heavy-haul operators.
Strategic Opportunities
- Quebec Low-Carbon Fuel Standard:Provincial incentives for hydrogen and electric commercial vehicles create procurement advantages for fleet operators with cross-provincial routes.
- Last-Mile Electrification:Urban delivery segments in Toronto and Vancouver present white-space demand where battery economics align with sub-200km daily range requirements.
- Vehicle-to-Grid Integration:Bidirectional charging technology convergence with utility demand-response programs opens revenue streams for fleet asset utilization.
Industry Challenges
- Technician Certification Bottlenecks:High-voltage powertrain repair qualifications require specialized training programs that Canadian technical colleges are scaling too slowly to match fleet electrification timelines.
- Cross-Border EPA Alignment Uncertainty:Divergence between Transport Canada and EPA certification timelines creates product planning friction for manufacturers with integrated North American production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Commercial Vehicles Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Vans, Buses Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Logistics Companies, Construction Firms, Government Agencies, Agriculture Sales Channel: Direct Sales, Dealerships, Online Platforms, Auctions |
| Companies Covered | Toyota Motor Corporation, Volvo Trucks North America, Ford Motor Company, Peterbilt Motors Company, Ram Trucking, Inc., General Motors Company, Honda Motor Co. Ltd., Kenworth Truck Company, Stellantis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Commercial Vehicles Market Strategic Shifts
Powertrain electrification is actively compressing traditional diesel dominance while regulatory compliance timelines and procurement model evolution reshape competitive positioning across Canadian commercial vehicle segments.
Battery-electric powertrains for medium-duty urban delivery applications are supplanting diesel configurations in Ontario and Quebec corridors. Last-mile logistics operators with predictable route profiles are adopting these platforms at accelerating pace. This transition is compressing residual value calculations for conventional diesel assets and forcing leasing companies to restructure contract terms.
Environment and Climate Change Canada's greenhouse gas regulations for heavy-duty vehicles mandate fleet-average emissions reductions that intensify compliance cost structures. Manufacturers are responding with accelerated electric and hydrogen platform investments. Heavy-duty segments serving Alberta's energy sector face the steepest compliance burden due to high annual mileage and payload requirements.
Fleet operators are consolidating vendor relationships and demanding integrated service packages spanning vehicles, charging infrastructure, and energy management. Traditional equipment-only sales models are losing ground to full-lifecycle contracts. This pattern concentrates most visibly among national logistics companies operating across Ontario's manufacturing corridor and British Columbia's port-linked distribution networks.
Canada Commercial Vehicles Market Segmentation
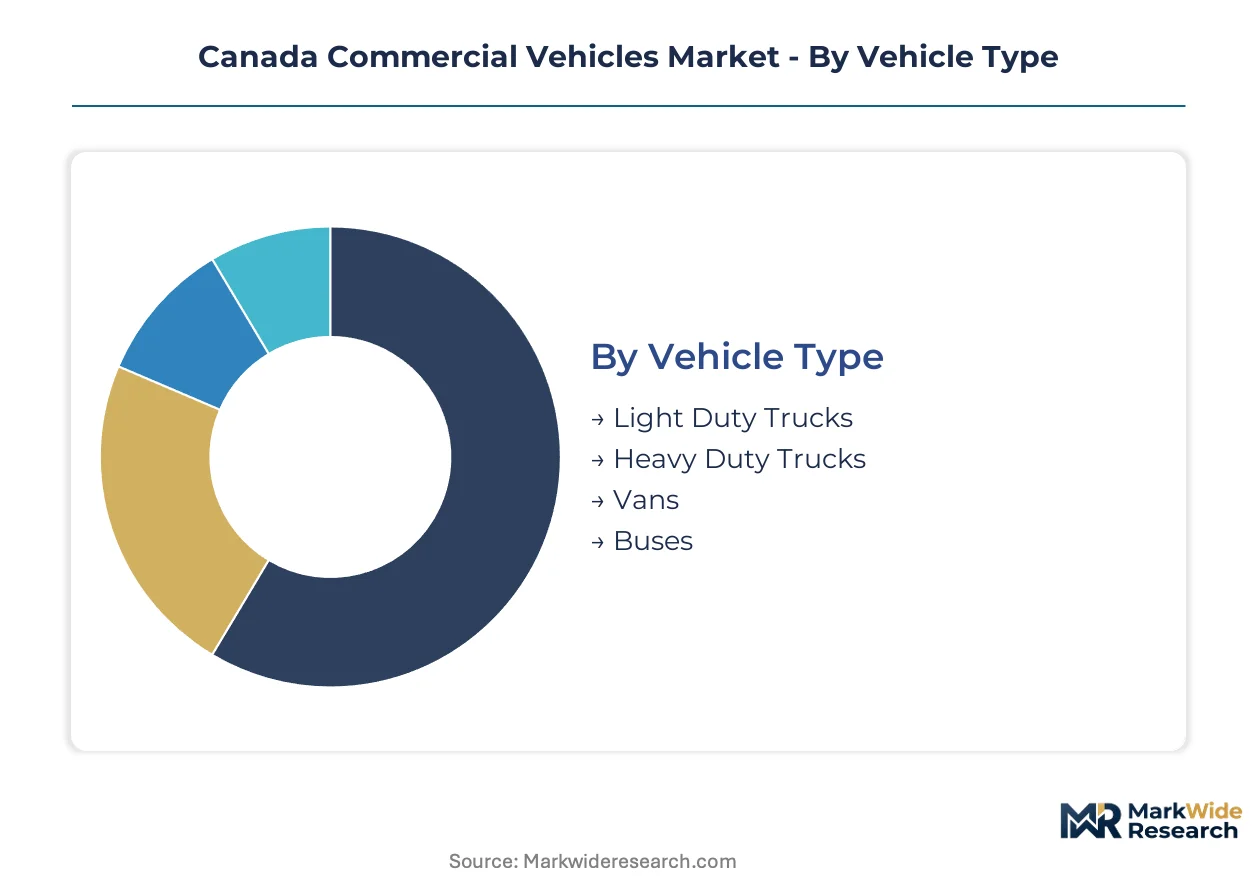
Segmentation clarity enables fleet operators and manufacturers to align procurement strategies with regulatory compliance timelines and route-specific powertrain economics. Each dimension reveals distinct demand patterns across Canada's provincial regulatory environments and industrial corridors.
Vehicle Type:
Domestic demand concentrates in configurations serving Ontario's manufacturing density and Alberta's resource logistics, while export-oriented production from Canadian assembly plants supplies cross-border fleet operators.
- Light Duty Trucks:Configurations rated between 4,500 kg and 8,500 kg gross vehicle weight dominate unit volumes through e-commerce fulfillment expansion and contractor fleet renewal in Toronto and Vancouver corridors. Urban delivery operators with sub-200km daily routes are accelerating electrification within this segment as battery economics align with operational requirements.
- Heavy Duty Trucks:Powertrains exceeding 15,000 kg gross vehicle weight serve Alberta oil sands logistics and cross-border long-haul freight along the Trans-Canada Highway. Transport Canada's emissions standards under the Canadian Environmental Protection Act are compressing replacement cycles and forcing powertrain diversification toward natural gas and electric platforms.
- Vans:Compact urban delivery configurations capture last-mile demand from postal services and food distribution networks in Montreal and Calgary metropolitan areas.
- Buses:Transit and intercity passenger configurations face procurement pressure from municipal zero-emission mandates in Vancouver and Toronto.
Light duty trucks hold the largest share; momentum sits with heavy duty trucks as Alberta energy logistics drive fleet expansion.
Fuel Type:
Cost tier differentiation separates established diesel infrastructure from emerging electric platforms requiring capital-intensive charging investments and technician retraining.
- Diesel:Compression-ignition powertrains retain structural dominance in heavy-duty applications due to torque density and established refueling infrastructure across prairie corridors. Alberta heavy-haul operators exhibit substitution resistance despite Environment and Climate Change Canada greenhouse gas regulations intensifying compliance cost structures.
- Electric:Battery-electric configurations are capturing share in last-mile delivery segments where predictable route profiles align with charging depot economics. Quebec's low-carbon fuel standard creates procurement advantages for fleet operators deploying electric platforms on cross-provincial routes.
- Gasoline:Spark-ignition powertrains retain position in light-duty contractor fleets with intermittent utilization patterns where diesel premium economics fail.
- Hybrid:Dual-powertrain configurations represent the fastest-growing fuel category as operators navigate capital constraints during electrification transitions, particularly among medium-duty delivery fleets in Ontario's Golden Horseshoe.
Diesel retains volume leadership; hybrid platforms are expanding most quickly as transitional capital solutions.
End User:
Application intensity varies by sector, with logistics operators driving replacement cycles through fuel surcharge mechanisms and construction firms responding to infrastructure project timing.
- Logistics Companies:National and regional freight operators constitute the deepest margin pool, consolidating vendor relationships and demanding integrated service packages spanning vehicles, charging infrastructure, and energy management. Contract renewal cycles tie directly to fuel surcharge mechanisms that accelerate fleet modernization decisions.
- Construction Firms:Vocational chassis configurations serve infrastructure and residential development projects across British Columbia and Ontario, with procurement timing synchronized to municipal contract awards and federal infrastructure spending.
- Government Agencies:Municipal and provincial fleet operators face zero-emission procurement mandates that reshape competitive bidding requirements in Toronto, Vancouver, and Montreal.
- Agriculture:Seasonal utilization patterns in Prairie provinces favor durable configurations with extended service intervals and rural service network access.
Logistics companies anchor revenue concentration; government agencies are gaining share fastest through electrification mandates.
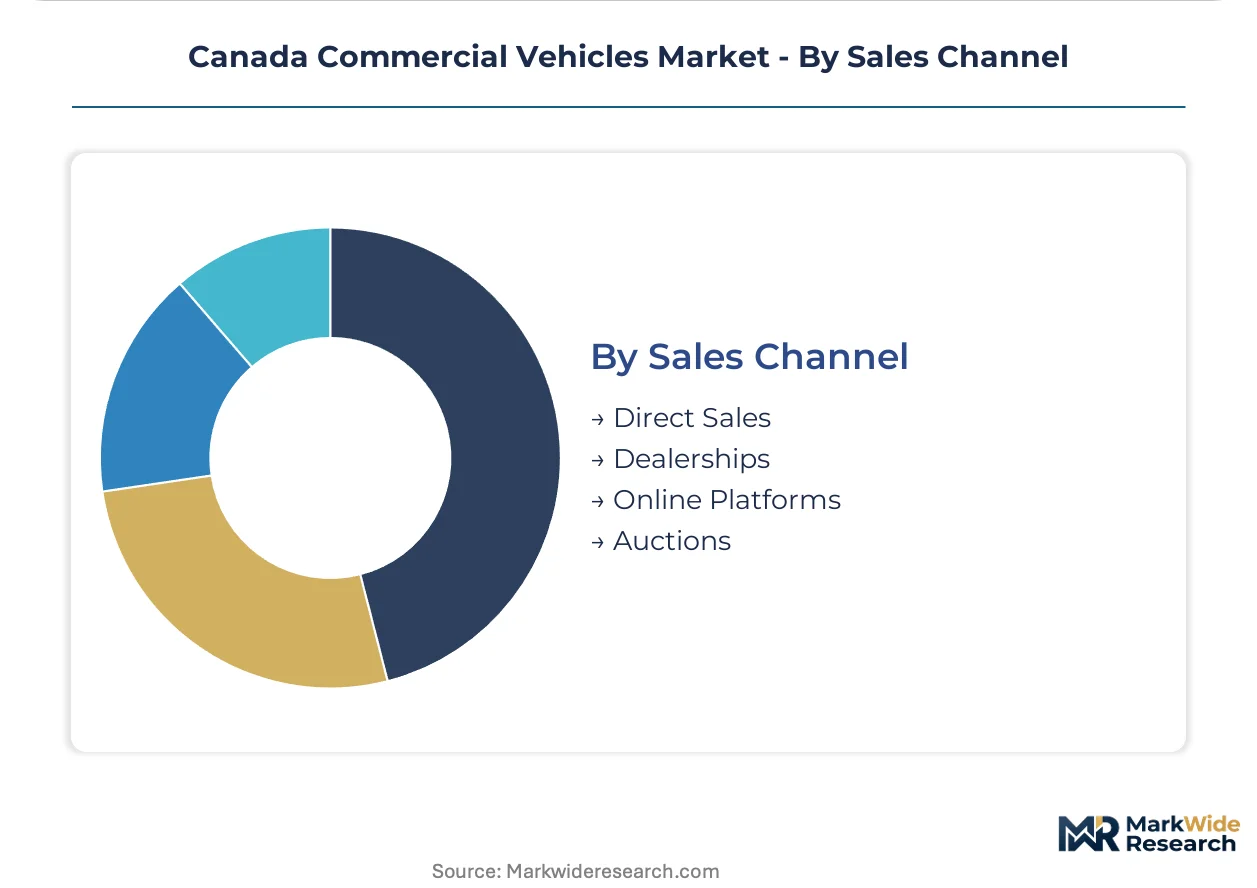
Sales Channel:
Customer type differentiation separates national fleet operators seeking direct manufacturer relationships from small contractors dependent on localized service networks.
- Dealerships:Franchise networks sustain dominant positioning in light-duty fleet sales through commercial financing structures and geographic density across Ontario and Quebec. Service bay capacity and parts availability anchor contractor loyalty in secondary markets.
- Direct Sales:Manufacturer-direct procurement concentrates among national logistics companies operating across provincial boundaries, enabling customized chassis specifications and volume pricing structures.
- Online Platforms:Digital configuration tools and virtual fleet management interfaces are emerging for standardized light-duty orders with predictable delivery timelines.
- Auctions:Secondary market disposition channels serve price-sensitive operators and regional fleets seeking depreciated assets for seasonal or backup deployment.
Dealerships maintain channel dominance; direct sales are climbing the fastest as national fleets consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway corridor underwrites national freight connectivity, linking Atlantic ports through Ontario's manufacturing belt to Pacific container terminals and prairie energy logistics hubs.
Ontario
The Golden Horseshoe warehousing density drives light-duty fleet renewal cycles for e-commerce fulfillment operators. Transport Canada's Motor Vehicle Safety Act compliance requirements shape manufacturer product planning for vehicles serving cross-border freight routes. Toronto's logistics clusters concentrate procurement authority for national fleet operators consolidating vendor relationships.
Quebec
Montreal's port-linked distribution networks generate demand for medium-duty urban delivery configurations. The provincial low-carbon fuel standard creates procurement advantages for fleet operators deploying electric platforms on cross-provincial routes. Manufacturing corridors around Quebec City anchor vocational chassis production for construction and municipal applications.
Alberta
Oil sands logistics operators expand heavy-duty unit procurement to serve extraction operations and pipeline construction schedules. Environment and Climate Change Canada's greenhouse gas regulations for heavy-duty vehicles intensify compliance cost structures for high-mileage fleets. Calgary's energy sector headquarters concentrate fleet management decisions for prairie resource logistics.
British Columbia
Vancouver's port infrastructure drives container drayage and intermodal freight demand for medium and heavy-duty configurations. Municipal zero-emission procurement mandates reshape competitive bidding requirements for transit and urban delivery operators. The Lower Mainland's distribution networks link Pacific trade flows to interior Canadian markets.
Prairie Provinces
Agricultural logistics in Saskatchewan and Manitoba favor durable configurations with extended service intervals for seasonal utilization patterns. Sparse high-power charging networks along Trans-Canada Highway corridors limit long-haul electrification feasibility for regional freight operators. Winnipeg's transportation hub position anchors cross-country distribution consolidation points.
Canada Commercial Vehicles Market Competitive Environment
Concentration sits with integrated North American manufacturers possessing established dealership networks and commercial financing structures. The competitive terrain divides between legacy automakers with light-duty fleet dominance and specialized truck manufacturers serving vocational heavy-duty segments. Strategic archetypes include full-line manufacturers spanning passenger and commercial portfolios, dedicated commercial vehicle specialists, and emerging electric platform developers. Dominant competitive moves encompass powertrain portfolio diversification toward electrified platforms and consolidation of direct sales relationships with national logistics operators.
Among North American-based manufacturers, Ford Motor Company, General Motors Company, and Stellantis occupy positions reflecting full-line commercial portfolio strategies. Volvo Trucks North America and Kenworth Truck Company exemplify dedicated heavy-duty specialists serving energy and long-haul logistics segments. Toyota Motor Corporation and Honda Motor Co. Ltd. represent diversified automotive groups with selective commercial vehicle presence. Peterbilt Motors Company and Ram Trucking, Inc. anchor vocational and light-duty specializations respectively.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volvo Trucks North America |
| Ford Motor Company |
| Peterbilt Motors Company |
| Ram Trucking, Inc. |
| General Motors Company |
| Honda Motor Co. Ltd. |
| Kenworth Truck Company |
| Stellantis |
| Others |
Value Chain & Pricing Dynamics
Inventory cycles spanning 45-60 days for chassis components concentrate pricing power with integrated North American manufacturers possessing captive stamping capacity and long-term steel supply agreements. This lead-time band tightens during peak fleet renewal seasons in Ontario and Alberta, amplifying cost pass-through capability for OEMs with backward-integrated powertrain production.
Pricing Analysis
Volume-discount tiering structures separate national logistics operators securing fleet-average pricing from small contractors absorbing list-plus-financing premiums. Three-tier pricing stratifies across premium specifications with extended powertrain warranties, standard configurations with baseline service intervals, and economy tiers for price-sensitive regional operators in Prairie provinces. Cost compression in electric powertrain tiers is intensifying because lithium-ion cell supply contracts reprice quarterly. Small contractor fleets exhibit highest price sensitivity due to thin working capital reserves, while integrated national operators leverage scale for lowest total-cost-of-ownership positioning.
Supply Chain Analysis
Inbound logistics costs from Port of Vancouver container congestion and Trans-Pacific trade lane volatility inflate landed costs for battery cells and electric motor assemblies sourced from South Korea and China. Canadian commercial vehicle production draws from steel coil supply anchored in Ontario and U.S. Great Lakes corridors, with axle and transmission components sourced from Mexico and Germany. Single-source vulnerability concentrates in semiconductor content for advanced driver-assistance systems. Distribution runs through manufacturer-direct channels for national fleet accounts and franchised dealership networks serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's commercial vehicle market functions as a service-attach opportunity where integrated maintenance contracts and charging infrastructure-as-a-service layers expand faster than underlying hardware shipments. Fleet operators increasingly procure full-lifecycle packages bundling vehicles, energy management, and predictive maintenance.
For Market Incumbents: Shield core dealership relationships in Ontario and Quebec by embedding proprietary telematics platforms that raise switching costs for contractor fleets. Expand captive financing arms to match emerging electric-platform entrants offering battery-leasing structures. Consolidate service bay capacity in secondary Prairie markets before regional specialists capture maintenance revenue from electrified municipal fleets.
For New Entrants and Emerging Players: Transport Canada Motor Vehicle Safety Act certification fast-tracks for low-speed urban delivery configurations present the most penetrable regulatory pathway. Target last-mile logistics operators in Toronto and Vancouver metropolitan areas with sub-200km route profiles where battery economics align without requiring Trans-Canada Highway range capability. Pursue direct procurement relationships with national grocery and parcel carriers consolidating vendor rosters.
For Investors and Strategic Acquirers: Long-term, this sits as a utility-linked infrastructure play because vehicle-to-grid integration capabilities transform fleet assets into grid-stabilization revenue streams. Acquisition candidates center on charging network operators with established real estate positions along Ontario-Quebec freight corridors. Monitor Environment and Climate Change Canada zero-emission mandate acceleration announcements as the primary inflection signal for powertrain portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Electrification Roadmap | Aligns powertrain portfolios with Transport Canada emissions compliance timelines and Quebec low-carbon fuel incentives. |
| Charging Infrastructure Partnership | Secures depot and highway corridor access for fleet operators navigating sparse high-power network coverage. |
| Vehicle-to-Grid Integration Development | Opens bidirectional charging revenue streams with provincial utility demand-response programs. |
| Aftermarket Service Network Expansion | Addresses technician certification bottlenecks constraining electric powertrain repair capacity. |
| Direct Fleet Procurement Consolidation | Captures national logistics operator volume migrating from fragmented dealership relationships. |
Study Parameters
Cross-validation between fleet operator procurement directors and OEM platform engineering managers anchors the qualitative findings on powertrain transition timelines. Primary interviews with dealership network principals, aftermarket service heads, and Transport Canada regulatory affairs specialists combined with secondary validation from vehicle production databases, provincial greenhouse gas reporting disclosures, and cross-border trade flow records. Bottom-up unit shipment modeling and top-down value aggregation triangulate market size estimates.
Sensitivity analysis on battery cost trajectories and charging infrastructure deployment schedules tests forecast robustness across the projection horizon. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, fleet operator size tier, and provincial regulatory cluster. CAGRs derive from logistic adoption curves fitted to fleet replacement cycle data and compliance deadline proximity. Forecast inputs incorporate Alberta oil sands capital expenditure patterns and Ontario warehousing construction permits.
Decision-makers should treat outputs as directional under sustained cross-border EPA alignment and stable lithium carbonate pricing assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Semi-Tractor Trailer Market