
 India Commercial Vehicle (CV) Market | 2026-2036
India Commercial Vehicle (CV) Market Size, Share, and Industry Trends Forecast 2026-2036
India Commercial Vehicle (CV) Market Insights
BS-VI emission compliance is collapsing the cost gap between basic and premium powertrain configurations. Tata Motors Limited leverages its in-house engine development to sustain margin control across the heavy-duty range. Ashok Leyland Limited anchors its position in the bus segment through dedicated plant capacity in Tamil Nadu. Eicher Motors Limited differentiates via its joint venture with Volvo, competing on technology transfer in medium-duty platforms.
Commercial vehicles encompass motorized transport equipment designed for goods carriage and passenger movement, with gross vehicle weight ratings spanning from 3.5 tonnes in light formats to over 16 tonnes in heavy configurations, engineered for payload efficiency and operating cycle durability. Light Commercial Vehicles occupy the volume tier due to e-commerce proliferation and urban freight restrictions, while Electric Commercial Vehicles represent the emerging margin pool as battery costs decline and charging infrastructure expands. Heavy Commercial Vehicles dominate the value tier through long-haul freight and mining applications, with diesel retention strongest where electrification remains technically constrained.
BIS certification mandates govern vehicle safety and component standards, while the CEA regulates charging infrastructure standards for electric variants, and the PLI scheme administered by the Ministry of Heavy Industries shapes capital allocation toward cleaner technology platforms. These frameworks collectively determine product homologation timelines and factory certification requirements for new entrants. Stakeholders must monitor the interplay between subsidy phase-out schedules and total cost of ownership parity for electric alternatives against diesel baselines.
Market Dynamics
BS-VI emission mandates are compressing product lifecycles across the India Commercial Vehicle market, forcing simultaneous powertrain upgrades and electrification roadmaps while tier-2 logistics networks expand procurement.
Growth Catalysts
- PLI Scheme for Automotive Manufacturing:Ministry of Heavy Industries incentives are redirecting factory investment toward cleaner technology platforms, accelerating domestic battery and fuel-cell component capacity.
- E-commerce Logistics Density:Last-mile delivery networks penetrating tier-2 and tier-3 cities are sustaining replacement demand for light commercial vehicle fleets.
- Industrial Corridor Freight:Dedicated freight corridors linking Maharashtra, Gujarat, and Tamil Nadu are generating heavy-duty vehicle pull from mining and containerized cargo operators.
Market Restraints
- Lithium Supply Concentration:Electric commercial vehicle production remains exposed to raw material import dependencies, constraining domestic battery pack cost competitiveness.
- BS-VI Compliance Capital Burden:Smaller fleet operators face compressed returns as after-treatment systems and engine management upgrades raise vehicle acquisition costs.
- Charging Infrastructure Gaps:CEA standards for grid integration are advancing faster than distribution utility readiness, creating deployment friction for electric bus and truck operators.
Strategic Opportunities
- State-Level Electric Bus Mandates:Tamil Nadu and Maharashtra urban transit corporations are tendering large-scale battery-electric deployments, opening fleet-as-a-service contracting models.
- Ethanol-Blended Diesel Compatibility:Engine platforms engineered for E20 compliance are capturing early-mover positioning as petroleum marketing companies expand biofuel retail infrastructure.
- Telematics-Enabled Asset Utilization:Connected fleet management systems are penetrating owner-operator segments previously inaccessible to technology vendors.
Industry Challenges
- Homologation Timeline Compression:BIS certification cycles for new powertrain variants are extending as safety and emission testing protocols layer complexity.
- Skilled Technician Scarcity:High-voltage systems diagnostics and battery pack servicing require training pipelines that technical institutes have not yet scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Commercial Vehicle (CV) Market |
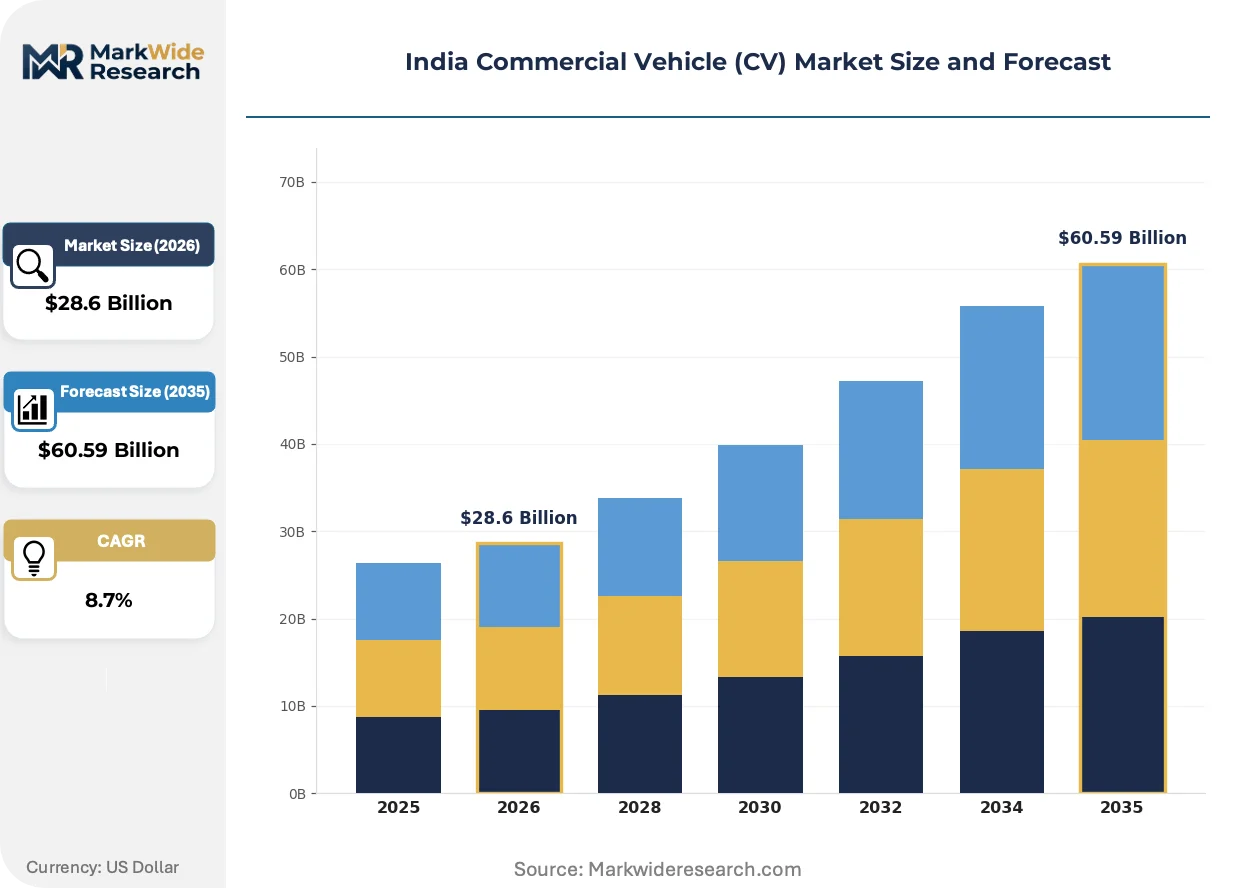
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Commercial Vehicles, Medium Commercial Vehicles, Heavy Commercial Vehicles, Electric Commercial Vehicles Fuel Type: Diesel, CNG, Petrol, Electric Application: Logistics, Construction, Public Transport, Freight End User: Fleet Operators, Government Agencies, Construction Firms, Delivery Services |
| Companies Covered | Tata Motors Limited, Mahindra & Mahindra Limited, Ashok Leyland Limited, VE Commercial Vehicles Limited, SML Isuzu Limited, Daimler India Commercial Vehicles Pvt. Ltd, Eicher Motors Limited, Hino Motors Sales India Private Limited, Scania Commercial Vehicles India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Commercial Vehicle (CV) Market Trends and Innovations
Powertrain electrification is intersecting with digital fleet management across Indian commercial vehicle operations, creating new competitive dimensions around total cost of ownership and asset productivity.
Integrated electric axle platforms combining motor, inverter, and transmission in single housings are displacing conventional driveline architectures in medium-duty delivery applications. E-commerce logistics operators in Bengaluru and Hyderabad are piloting these configurations for 12-hour duty cycles. The technology is displacing multi-component assembly supply chains while reducing vehicle weight and maintenance intervals.
The Ministry of Heavy Industries has tightened PLI scheme disbursement criteria to require minimum domestic value addition in battery pack assembly. This industrial policy shift is redirecting component sourcing from fully-built imports toward local cell-to-pack operations. Heavy commercial vehicle manufacturers are responding by renegotiating joint venture terms to capture subsidy eligibility.
Fleet operators are consolidating vehicle procurement through centralized tendering platforms rather than decentralized dealer negotiations. Large cement and steel transporters in Gujarat are aggregating demand to extract volume-based service commitments. This procurement concentration is most visible in the western industrial corridor where organized fleet penetration exceeds other regions.
India Commercial Vehicle (CV) Market Segmentation
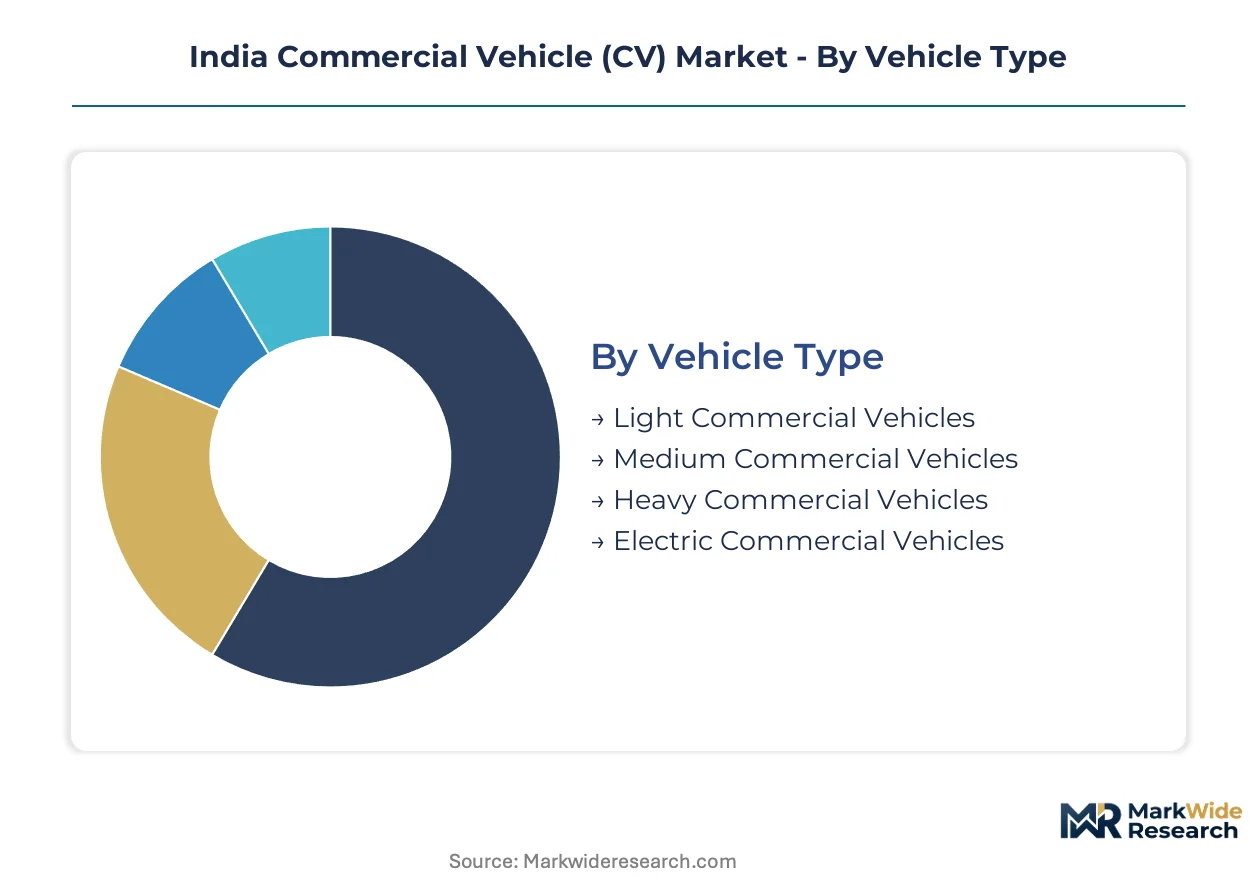
Segmentation in India's commercial vehicle market reveals divergent margin structures across duty cycles and fuel platforms. Powertrain electrification and logistics automation are fragmenting traditional volume hierarchies, forcing manufacturers to rebalance capacity allocation across emerging and legacy segments.
Vehicle Type:
Margin concentration in heavy configurations contrasts with volume dominance in lighter platforms, creating distinct competitive terrains for manufacturers.
- Light Commercial Vehicles:Gross vehicle weight ratings between 3.5 and 7.5 tonnes serve urban freight restrictions and last-mile distribution networks. E-commerce logistics operators in Maharashtra and Gujarat are expanding procurement as tier-2 city penetration deepens, though payload limitations constrain per-unit revenue.
- Heavy Commercial Vehicles:Configurations exceeding 16 tonnes gross vehicle weight dominate long-haul freight corridors and mining applications. Industrial clusters linking ports in Tamil Nadu sustain diesel retention where electrification remains technically constrained by battery energy density.
- Medium Commercial Vehicles:Intermediate duty platforms balance maneuverability with payload capacity for regional distribution.
- Electric Commercial Vehicles:Battery-electric and fuel-cell platforms are capturing early-mover positioning in urban bus mandates and depot-based logistics.
Heavy Commercial Vehicles hold installed capacity. Electric Commercial Vehicles is rotating up the share rankings.
Fuel Type:
Cost tier differentiation separates legacy internal combustion from emerging clean technology platforms, with capital requirements determining manufacturer participation.
- Diesel:Compression-ignition engines with BS-VI after-treatment systems retain dominance in heavy freight and mining applications where energy density requirements exceed current battery capabilities. Fleet operators in Gujarat's cement transport corridor continue diesel procurement despite compliance cost inflation.
- Electric:Battery-electric powertrains with lithium-ion cell chemistry are penetrating urban bus and light delivery segments. CEA grid integration standards and PLI scheme disbursement criteria are redirecting investment toward domestic cell-to-pack assembly operations.
- CNG:Compressed natural gas configurations serve municipal bus fleets and urban freight with established refueling infrastructure.
- Petrol:Spark-ignition platforms occupy niche applications in light commercial segments with lower utilization intensity.
Diesel retains revenue concentration. Electric is climbing the fastest.
Application:
Customer workflow requirements dictate vehicle specification, with duty cycle intensity determining technology adoption timelines.
- Logistics:Containerized freight and parcel distribution networks require optimized payload-to-tare ratios and telematics integration. E-commerce fulfillment centers in Bengaluru and Hyderabad are piloting integrated electric axle platforms for 12-hour duty cycles.
- Public Transport:Scheduled bus operations with depot-based charging enable predictable electrification roadmaps. State urban transit corporations in Tamil Nadu and Maharashtra are tendering large-scale battery-electric deployments under fleet-as-a-service models.
- Construction:Off-highway durability requirements and site access constraints favor conventional powertrains in current procurement cycles.
- Freight:Long-haul container movement along dedicated industrial corridors sustains heavy diesel platform demand.
Logistics commands technology investment. Public Transport is expanding most quickly.
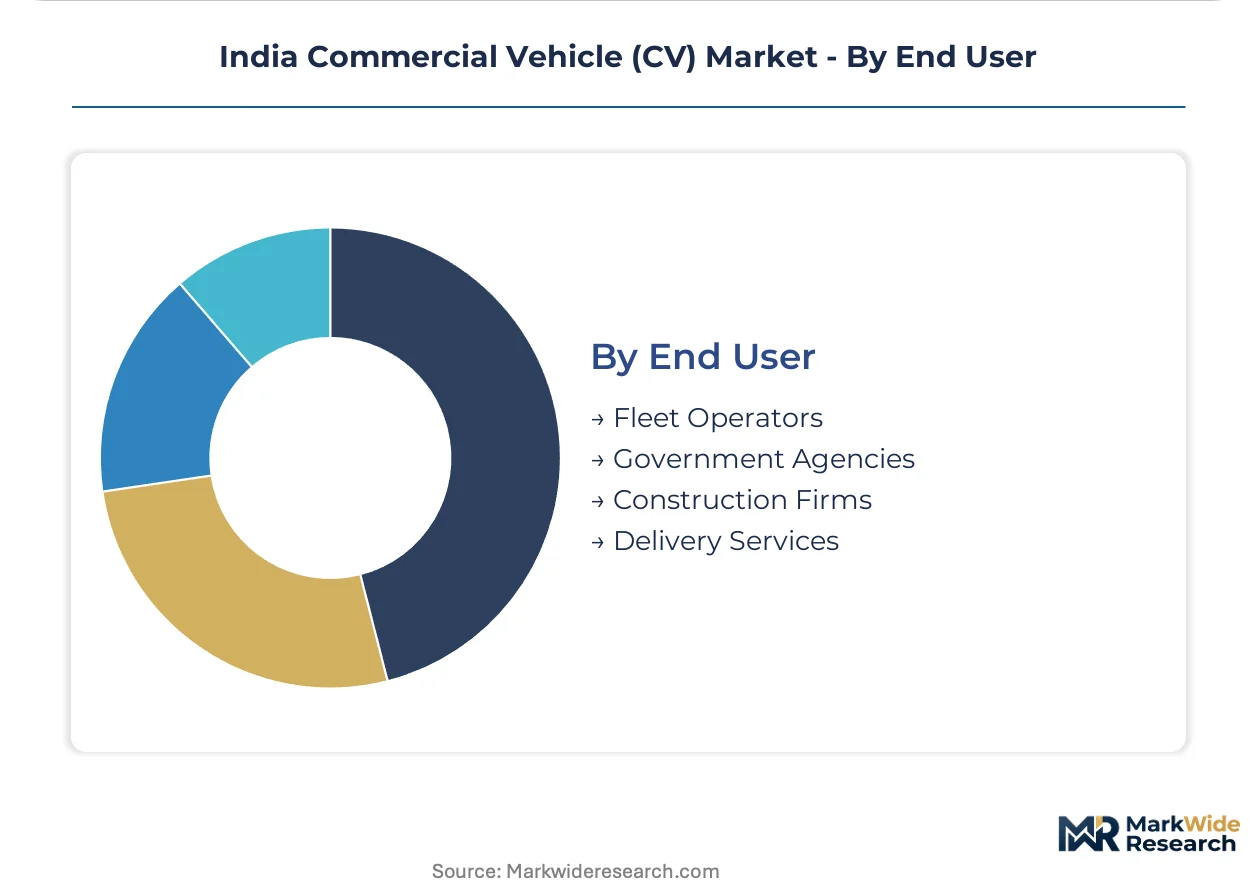
End User:
Procurement scale and financing sophistication separate organized fleet consolidation from fragmented owner-operator purchasing patterns.
- Fleet Operators:Large-scale logistics and cement transporters are consolidating procurement through centralized tendering platforms rather than decentralized dealer negotiations. Aggregated demand in Gujarat's western industrial corridor is extracting volume-based service commitments previously unavailable to fragmented buyers.
- Government Agencies:State transport undertakings and urban development authorities drive standardization through emission mandates and electric vehicle adoption targets. BIS certification requirements and PLI scheme administration by the Ministry of Heavy Industries shape product homologation timelines for public tenders.
- Construction Firms:Project-based equipment procurement with seasonal utilization patterns constrains technology upgrade cycles.
- Delivery Services:Rapid-turnover last-mile operators prioritize acquisition cost over total cost of ownership in current fleet decisions.
Fleet Operators anchor procurement volume. Government Agencies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along western and southern industrial corridors where port connectivity and freight density sustain heavy vehicle demand. State-level electric bus mandates and PLI scheme disbursement criteria are redirecting investment toward Tamil Nadu and Maharashtra. Sub-regional differentiation reflects varying infrastructure maturity and logistics network penetration.
Maharashtra
Mumbai-Pune industrial belt generates sustained heavy commercial vehicle procurement from cement and steel transporters. The state urban transit corporation tenders large-scale battery-electric bus deployments under fleet-as-a-service contracting models. JNPT port connectivity sustains containerized freight movement through dedicated logistics parks in Navi Mumbai.
Gujarat
Dedicated freight corridors linking Mundra and Hazira ports generate diesel retention in long-haul mining applications. The western industrial corridor exceeds other regions in organized fleet penetration, with cement transporters consolidating procurement through centralized tendering platforms. Ahmedabad-Surat manufacturing belt hosts component suppliers aligned with BS-VI compliance requirements.
Tamil Nadu
Chennai metropolitan transit operations enable predictable electrification roadmaps with depot-based charging infrastructure. Ashok Leyland anchors dedicated plant capacity in this state, serving both domestic bus demand and export markets. Sriperumbudur automotive cluster concentrates powertrain component suppliers benefiting from PLI scheme value-addition mandates.
Karnataka
Bengaluru e-commerce fulfillment centers pilot integrated electric axle platforms for 12-hour urban delivery cycles. The state technical institutes face scaling challenges for high-voltage systems diagnostics training pipelines. Hoskote industrial area hosts last-mile logistics operators expanding light commercial vehicle fleets into tier-2 city networks.
Telangana
Hyderabad logistics parks sustain medium-duty platform demand for regional distribution networks. The state urban development authority drives standardization through emission mandates affecting public transport procurement timelines. Shamshabad cargo hub generates freight vehicle pull from pharmaceutical and electronics exporters.
India Commercial Vehicle (CV) Market Competitive Landscape
Concentration sits with diversified automotive conglomerates and dedicated commercial vehicle specialists. The market structure reflects tiered participation where integrated engine developers control margin positions in heavy-duty segments while joint venture platforms compete on technology transfer. Three archetypes dominate: domestic engine developers with in-house powertrain capabilities, foreign-owned subsidiaries leveraging global platform architectures, and specialist bus manufacturers with dedicated plant capacity. Competitive moves center on renegotiating joint venture terms for PLI eligibility and consolidating procurement through fleet-as-a-service contracting models.
Within the domestic conglomerate tier, Tata Motors Limited and Mahindra & Mahindra Limited occupy positions reflecting integrated manufacturing footprints across light and heavy configurations. Ashok Leyland Limited exemplifies the specialist archetype with concentrated bus segment exposure. Among joint venture platforms, Eicher Motors Limited and VE Commercial Vehicles Limited represent technology-transfer-dependent positioning. SML Isuzu Limited anchors the Japanese-affiliated specialist segment.
| Leading Market Players |
|---|
| Tata Motors Limited |
| Mahindra & Mahindra Limited |
| Ashok Leyland Limited |
| VE Commercial Vehicles Limited |
| SML Isuzu Limited |
| Daimler India Commercial Vehicles Pvt. Ltd |
| Eicher Motors Limited |
| Hino Motors Sales India Private Limited |
| Scania Commercial Vehicles India Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day engine component lead times concentrate pricing power with integrated manufacturers holding captive forging and casting capacity, while tier-2 fleet operators absorb BS-VI compliance cost inflation through extended financing tenures. The supply chain's geographic clustering around Tamil Nadu and Maharashtra industrial corridors reinforces margin asymmetry between in-house powertrain developers and assembly-dependent competitors.
Pricing Analysis
BS-VI emission mandates dictate the pricing tier structure across heavy and light commercial configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated engine manufacturers from joint-venture platforms and import-dependent assemblers. Price differentiation rests on after-treatment system sophistication and telematics bundling intensity. Cost compression in economy-tier light commercial vehicles is intensifying because smaller fleet operators face compressed returns on after-treatment investments. Cement transporters in Gujarat's western corridor exhibit lowest price sensitivity due to consolidated procurement scale, while owner-operator segments in tier-3 cities demonstrate acute acquisition cost responsiveness.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and rare-earth magnets characterizes inventory strategy as domestic battery pack assembly scales under PLI scheme mandates. Component sourcing draws from China, South Korea, and Japan for cell chemistry and power electronics, while domestic forging capacity concentrates in Tamil Nadu and Maharashtra for driveline hardware. Raw material dependencies span lithium carbonate, neodymium-dysprosium rare earths, and high-grade electrical steel. Single-source vulnerability in semiconductor gate drivers for inverter modules threatens production continuity. Distribution runs through OEM-owned dealership networks for heavy configurations and aggregator platforms for light commercial fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as e-commerce logistics density creates tier-2 and tier-3 service gaps that national OEMs under-serve with standardized product portfolios. Last-mile delivery operators demand flexible financing and rapid service turnaround that centralized manufacturing footprints struggle to match.
For Market Incumbents: Compound margin defensibility through captive battery pack assembly investments qualifying for PLI scheme disbursement, while extending service network density into Karnataka and Telangana logistics corridors. Threat from integrated electric axle platform specialists demands pre-emptive joint venture restructuring to capture cell-to-pack value addition. Capacity addition in Sriperumbudur and Hoskote industrial clusters anchors regional service responsiveness against emerging electric-first competitors. For New Entrants and Emerging Players: Fleet-as-a-service contracting gaps in state urban transit corporation tendering create white-space entry points where incumbent OEMs resist long-term asset ownership models. Most penetrable segment sits in depot-based electric bus operations across Tamil Nadu and Maharashtra where tendering volume aggregates but service innovation lags. Target telematics-enabled utilization optimization as go-to-market angle, bundling predictive maintenance with per-kilometer pricing structures that transfer battery degradation risk from operators to technology vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates seeking to monetize non-core commercial vehicle divisions as electrification capital requirements intensify. Long-term viability frames around platform standardization capability and charging infrastructure partnership depth rather than unit volume scale. Acquisition target archetype: mid-cap electric axle specialists with CEA certification progress and state-level bus tendering relationships. Signal to watch is PLI scheme disbursement acceleration triggering consolidation among subsidy-dependent assemblers unable to meet domestic value-addition thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell offtake from Korean suppliers for Tamil Nadu pack assembly qualifying under PLI. |
| Platform Standardization | Reduces variant complexity across Maharashtra-Gujarat heavy-duty range while preserving BS-VI compliance. |
| Charging Infrastructure Partnership | Links depot-based bus operators with CEA-certified grid integration vendors in Karnataka urban corridors. |
| Software-Defined Vehicle Investment | Enables telematics-enabled asset utilization models penetrating owner-operator segments in tier-2 cities. |
| Geographic Manufacturing Footprint | Extends Hoskote assembly capacity to capture Telangana pharmaceutical logistics demand growth. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement managers, OEM platform engineers, Tier 1 supplier commercial leads, and state transport undertaking tendering officers; and secondary validation through vehicle production databases, IHS Markit registration data, Ministry of Heavy Industries PLI disbursement records, and BIS certification filings. Bottom-up modeling of segment-level demand triangulated against top-down macroeconomic drivers including industrial corridor freight intensity and e-commerce logistics penetration metrics.
Across the projection horizon, the analytical framework modeled vehicle class, propulsion architecture, gross vehicle weight rating, and regional production cluster dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating fuel price sensitivity and total cost of ownership parity assumptions for electric alternatives. Industry-specific forecast inputs encompassed PLI scheme phase-out schedules and CEA grid integration standard adoption timelines affecting electric bus deployment velocity.
Forecasts assume regulatory continuity in BS-VI emission enforcement and PLI scheme administration; material policy shifts including subsidy acceleration or biofuel mandate expansion would require re-modeling. Revision becomes warranted when lithium supply concentration or charging infrastructure deployment gaps cross thresholds that alter electric vehicle adoption trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Electric LCV Market