
 Industrial Vehicles Market | 2026-2036
Industrial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Vehicles Market Intelligence
Multi-source component procurement is realigning supply chain risk profiles across the industrial vehicles sector. Daimler Truck leverages captive powertrain manufacturing to secure margin control across heavy-duty segments. Volvo Group anchors its position through integrated safety systems and autonomous vehicle R&D pipelines. KION Group AG specializes in electric forklift architectures and warehouse automation interfaces.
Industrial vehicles encompass self-propelled machines engineered for material handling, earthmoving, and cargo transport, typically operating at load capacities from one ton to over one hundred tons across construction and logistics environments. These machines employ hydraulic actuation, diesel-electric hybrid powertrains, or fully electric battery systems to execute lifting, hauling, and grading functions in continuous-duty industrial cycles. Forklifts and excavators command the largest installed bases, though electric-hybrid technology is capturing the fastest expansion as fleet operators confront total-cost-of-ownership pressures. Warehouse operations and mining applications generate divergent margin pools, with logistics providers prioritizing energy efficiency and mining corporations demanding extreme-duty structural specifications.
EPA tailpipe standards for off-road diesel engines, EU Green Deal carbon-border adjustments, and China's MIIT new-energy vehicle mandates are forcing parallel powertrain transitions across North American, European, and Chinese markets. OSHA workplace safety protocols and ISO 3691 industrial truck standards further constrain product design and market access for non-compliant manufacturers. Fleet operators and OEM boards must resolve capital allocation between electrification R&D and aftermarket service infrastructure before regulatory phase-outs tighten.
Market Dynamics
The shift from diesel to electric powertrains is compressing product development cycles and forcing parallel investments in battery supply chains and charging infrastructure across manufacturing footprints.
Growth Catalysts
- EU Green Deal decarbonization mandates:Fleet operators in Germany and the Netherlands are accelerating forklift electrification to avoid carbon-border adjustment penalties on logistics operations.
- Shanghai-Pearl River Delta manufacturing corridor:Dense clustering of automotive and electronics production is generating concentrated demand for automated guided vehicles and electric counterbalance forklifts.
- Lithium iron phosphate battery chemistry:Improved thermal stability and cycle life are enabling multi-shift warehouse operations without battery swap infrastructure.
Market Restraints
- Cathode active material supply concentration:Processing capacity for battery-grade lithium and nickel concentrates in Indonesia and the Democratic Republic of Congo creates input cost volatility for electric powertrain OEMs.
- OSHA workplace safety protocol compliance:Retrofitting existing facilities with pedestrian detection systems and automatic speed limiting adds capital intensity to fleet upgrades.
- Technical limitation in fast-charging infrastructure:Grid connection capacity constraints at older industrial parks limit deployment of high-power charging for heavy-duty electric forklifts.
Strategic Opportunities
- India's Production-Linked Incentive scheme for automotive:Greenfield manufacturing investments in Tamil Nadu and Gujarat offer tariff advantages for electric forklift assembly serving South Asian logistics networks.
- Autonomous vehicle R&D convergence:Integration of LiDAR-based navigation with warehouse management systems is opening retrofit markets for existing forklift fleets.
- EPA emissions standards phase-out timeline:Tier 4 Final compliance deadlines for diesel engines are creating captive replacement demand for electric alternatives in California and Texas distribution centers.
Industry Challenges
- Electrification skill gap:Maintenance technicians trained on internal combustion powertrains require re-certification in high-voltage battery systems and thermal management diagnostics.
- ISO 3691 industrial truck standard certification timelines:Multi-country type approval processes delay product launches by eight to fourteen months for modular platform designs.
- Legacy warehouse management system integration:Proprietary communication protocols from incumbent automation vendors obstruct seamless data exchange with new electric forklift telematics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Vehicles Market |
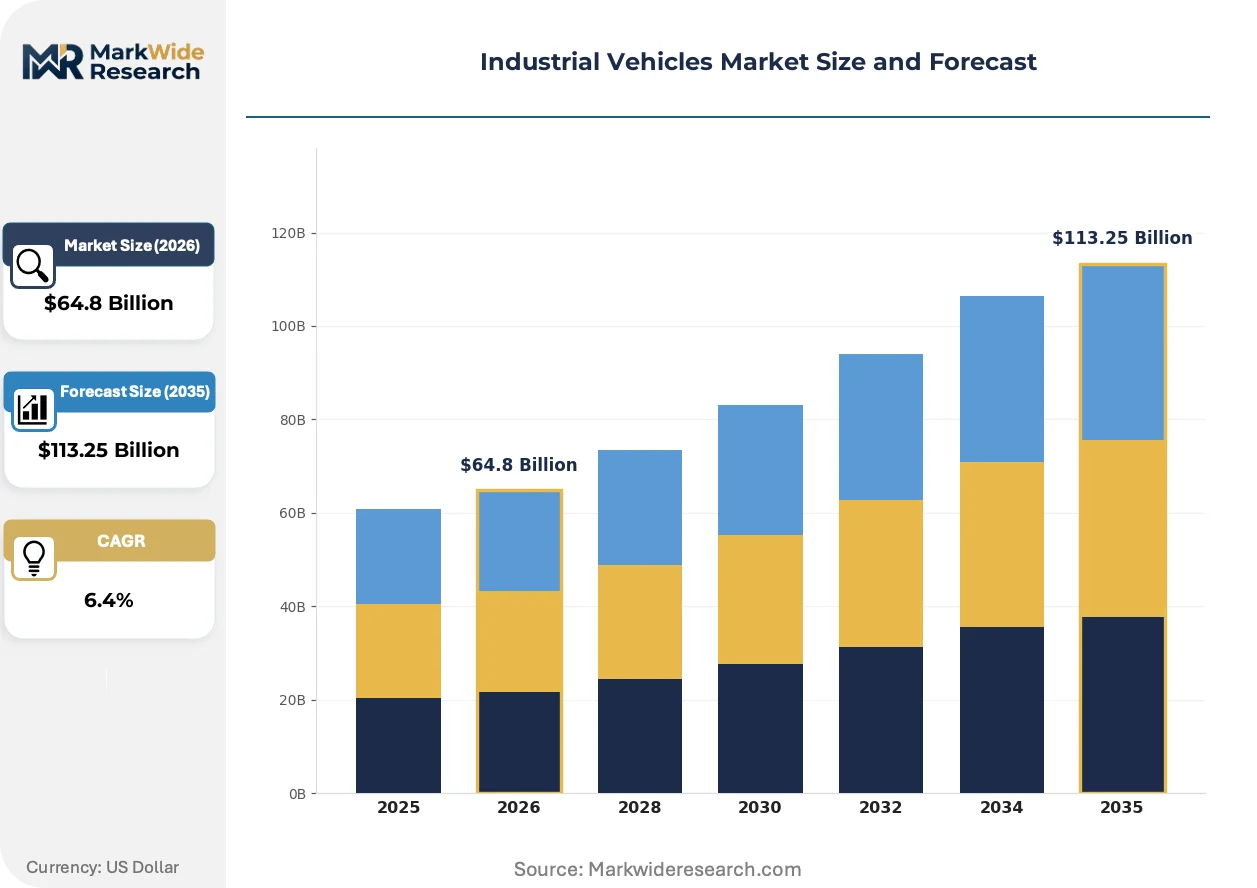
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $113.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Loaders, Cranes, Conveyors, Bulldozers, Excavators Technology: Hydraulic, Electric, Pneumatic, Diesel, Gasoline, Hybrid Application: Warehouse Operations, Construction Sites, Mining, Ports, Agriculture, Shipyards End User Industry: Manufacturing Plants, Logistics Providers, Mining Corporations, Agriculture Firms, Construction Contractors, Shipping Companies |
| Companies Covered | Traton Group, Tata Motors, Daimler Truck, Hino Motors, Isuzu Motors, Volvo Group, Iveco Group, KION Group AG, PACCAR Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Vehicles Market Strategic Shifts & Innovations
Powertrain electrification is converging with automation software and predictive maintenance analytics, collapsing the traditional separation between vehicle hardware and fleet optimization platforms.
Battery-swapping infrastructure is unifying charging logistics across multi-shift warehouse operations. Third-party logistics providers in China's Yangtze River Delta are deploying automated swap stations to eliminate dwell time. This architecture is unifying fleet utilization rates with energy cost management, compressing total-cost-of-ownership calculations for electric forklift procurement.
EPA tailpipe standards for off-road diesel engines are forcing premature retirement of existing forklift fleets. The regulatory consequence is a demand spike for electric alternatives that outpaces current manufacturing capacity. California's Air Resources Board enforcement timeline is most affected, with warehouse operators in the Inland Empire accelerating procurement to avoid operational penalties.
Fleet operators are consolidating vendor relationships around integrated service contracts. Single-source agreements covering vehicles, batteries, and maintenance are displacing transactional procurement of discrete components. This concentration is most visible among US-based e-commerce fulfillment networks, where uptime guarantees now determine contract awards more than unit pricing.
Industrial Vehicles Market Segmentation
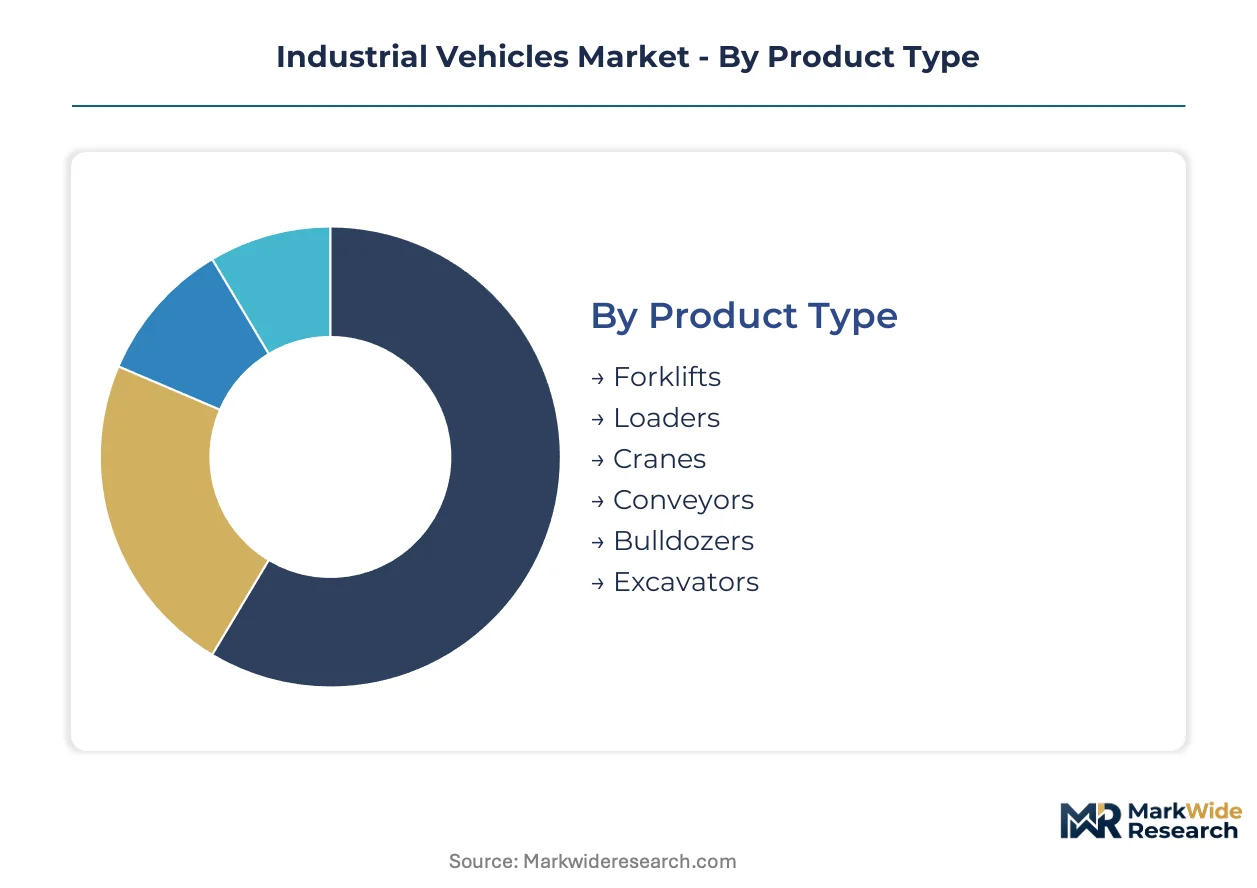
Industrial vehicles serve divergent duty cycles across material handling, earthmoving, and bulk transport functions. Segmentation by product type, technology, application, and end user reveals how electrification pressures and automation requirements reshape procurement patterns across fleet operators.
Product Type:
Replacement cycles for aging diesel fleets are compressing as EPA Tier 4 Final deadlines and EU Green Deal phase-outs force premature retirements.
- Forklifts:Electric counterbalance and reach truck configurations dominate warehouse material handling, with lithium iron phosphate battery systems enabling multi-shift operations without swap infrastructure. Logistics providers in Germany and the United States are expanding fleet procurement to avoid carbon-border adjustment exposure.
- Excavators:Hydraulic actuation systems at load capacities exceeding twenty tons serve mining and heavy construction applications, though diesel-electric hybrid powertrains are penetrating where total-cost-of-ownership pressures mount. Demand concentrates in East Asian manufacturing clusters around Shanghai.
- Loaders:Wheel and track configurations handle bulk material aggregation across quarry and port operations.
- Cranes:Mobile and tower variants execute vertical lifting in construction and shipyard environments.
- Conveyors:Continuous belt and roller systems automate intra-facility material flow.
- Bulldozers:Tracked earthmovers with blade attachments grade and clear terrain in mining and infrastructure projects.
Volume placements concentrate in forklifts; the faster expansion belongs to excavators as hybrid powertrains penetrate heavy-duty segments.
Technology:
Cost tier differentiation separates premium electric architectures from legacy combustion systems as battery supply chains mature.
- Electric:Battery-powered drivetrains with permanent magnet motors and regenerative braking capture warehouse automation demand. China's MIIT new-energy vehicle mandates and California Air Resources Board enforcement timelines are accelerating procurement by logistics providers seeking operational compliance.
- Hybrid:Diesel-electric configurations combine internal combustion prime movers with electric auxiliary systems to reduce fuel consumption in intermittent-duty cycles. Mining corporations in Australia and Canada are piloting these systems where grid connectivity is absent.
- Hydraulic:Fluid power transmission remains standard for high-force earthmoving applications.
- Diesel:Compression-ignition engines face regulatory phase-outs across US and European markets.
- Gasoline:Spark-ignition powertrains persist in light-duty material handling.
- Pneumatic:Compressed air systems serve specialized explosive-environment operations.
Procurement volume clusters around electric systems; hybrid architectures are climbing the fastest as transitional solutions for off-grid heavy-duty applications.
Application:
Margin structure varies sharply between indoor warehouse automation and extreme-duty outdoor environments.
- Warehouse Operations:Automated guided vehicles and electric counterbalance forklifts execute pallet movement and rack storage in climate-controlled facilities. Third-party logistics providers in China's Yangtze River Delta are deploying battery-swap stations to eliminate charging dwell time.
- Mining:Ultra-class haul trucks and hydraulic excavators operate in continuous-duty cycles exceeding twenty hours daily. Mining corporations demand extreme-duty structural specifications and on-site service infrastructure that OEMs must provision through captive dealer networks.
- Construction Sites:Mobile cranes and earthmovers serve project-based deployment patterns.
- Ports:Container handlers and straddle carriers manage intermodal cargo transfer.
- Agriculture:Tractor-mounted loaders and conveyors support seasonal harvest logistics.
- Shipyards:Heavy-lift gantry cranes and transport platforms execute vessel assembly.
Revenue concentration sits with warehouse operations; mining applications generate the steepest expansion trajectory as autonomous haulage systems mature.
End User Industry:
Customer type determines service contract structure and fleet financing arrangements.
- Logistics Providers:E-commerce fulfillment networks and third-party warehouse operators prioritize uptime guarantees and integrated service contracts covering vehicles, batteries, and predictive maintenance analytics. Single-source vendor consolidation is displacing transactional component procurement.
- Manufacturing Plants:Automotive and electronics production facilities in the Pearl River Delta industrial corridor generate concentrated demand for automated guided vehicles synchronized with just-in-time assembly lines.
- Mining Corporations:Integrated resource extraction companies specify extreme-duty equipment with lifecycle cost guarantees.
- Construction Contractors:Project-based rental and lease arrangements dominate equipment access.
- Agriculture Firms:Seasonal utilization patterns favor short-term rental over ownership.
- Shipping Companies:Container terminal operators invest in electrified yard equipment.
Procurement volume aggregates with logistics providers; manufacturing plants are gaining share fastest as production automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric forklifts concentrates in three manufacturing corridors: Germany's logistics networks, the United States distribution centers, and China's Yangtze and Pearl River Delta industrial zones. Fleet procurement decisions in these markets now hinge on regulatory compliance timelines rather than capital cost alone.
United States
Third-party logistics providers in California's Inland Empire and Texas distribution corridors are accelerating electric forklift procurement ahead of EPA Tier 4 Final deadlines. OSHA workplace safety protocols mandate pedestrian detection retrofits that add capital intensity to fleet upgrades. Chicago and Detroit automotive manufacturing clusters generate concentrated demand for automated guided vehicles synchronized with just-in-time assembly lines.
Germany
Logistics operators in the Ruhr industrial belt and Bavarian manufacturing zones are expanding electric counterbalance forklift fleets to avoid EU Green Deal carbon-border adjustment penalties. The country's national emissions regulator enforces stringent off-road diesel standards that compress replacement cycles for aging internal combustion fleets. Stuttgart and Munich automotive production facilities anchor demand for warehouse automation interfaces.
China
MIIT new-energy vehicle mandates are forcing parallel powertrain transitions across Shanghai and Pearl River Delta manufacturing clusters. The Yangtze River Delta logistics corridor deploys automated battery-swap stations to eliminate charging dwell time for multi-shift warehouse operations. Shenzhen and Guangzhou electronics production facilities generate concentrated procurement of electric forklifts with lithium iron phosphate battery systems.
Japan
Automotive and electronics manufacturers in the Kanto and Kansai industrial belts prioritize integrated service contracts covering vehicles, batteries, and predictive maintenance analytics. METI industrial standards constrain product design for non-compliant powertrain imports. Nagoya and Osaka port operations invest in electrified yard equipment for container handling.
India
The Production-Linked Incentive scheme for automotive manufacturing is attracting greenfield electric forklift assembly investments in Tamil Nadu and Gujarat. The country's national automotive regulator enforces localization requirements that favor domestic battery supply chain development. Mumbai-Pune logistics corridors and Delhi-NCR distribution networks generate emerging demand for warehouse automation.
Industrial Vehicles Market Key Industry Players
Capacity expansion dominates the current landscape as OEMs resolve capital allocation between electrification R&D and aftermarket service infrastructure. The vendor base stratifies across three tiers: integrated automotive conglomerates with captive powertrain manufacturing, specialized material handling equipment manufacturers, and regional fabricators serving price-sensitive procurement. Strategic archetypes include full-stack integrators controlling battery supply chains, automation-focused specialists converging hardware with fleet optimization software, and scale-driven assemblers leveraging India's PLI tariff advantages. Parallel competitive moves center on geographic expansion into South Asian logistics networks and technology licensing for autonomous navigation systems.
Among German-based industrial conglomerates, KION Group AG occupies a position exemplifying the automation-specialist archetype through its electric forklift architectures and warehouse automation interfaces. Daimler Truck and Volvo Group represent the full-stack integrator tier, with the former leveraging captive powertrain manufacturing and the latter anchoring integrated safety systems development. These three entities sit within distinct strategic vectors—material handling specialization, heavy-duty powertrain control, and autonomous vehicle R&D convergence—rather than competing directly across identical customer segments.
| Leading Market Players |
|---|
| Traton Group |
| Tata Motors |
| Daimler Truck |
| Hino Motors |
| Isuzu Motors |
| Volvo Group |
| Iveco Group |
| KION Group AG |
| PACCAR Inc |
| Others |
Cost & Logistics Intelligence
EU Green Deal decarbonization mandates gate qualified supply access and premium-tier pricing power for electric forklift OEMs serving German and Dutch logistics networks. Fleet operators seeking carbon-border adjustment compliance face tiered procurement costs that separate certified electric architectures from transitional hybrid systems and legacy diesel units facing regulatory phase-out.
Pricing Analysis
Volume placements cluster in standard-tier electric forklifts with lithium iron phosphate battery systems, while margins concentrate in premium automated guided vehicles with integrated warehouse management interfaces. Price differentiation hinges on ISO 3691 certification tier and after-sales service bundling, with California Air Resources Board compliance deadlines intensifying cost compression in diesel-equivalent segments. Third-party logistics providers in the Inland Empire exhibit acute price sensitivity, whereas mining corporations in Australia prioritize lifecycle cost guarantees over unit economics.
Supply Chain Analysis
ISO 3691 certification and EPA Tier 4 Final qualification requirements filter component suppliers and assembly partners across the industrial vehicles sector. Battery-grade lithium processing concentrates in Indonesia and the Democratic Republic of Congo, with cathode active material supply drawing from Chinese and South Korean chemical processors. Single-source vulnerability in nickel concentrate supply creates input cost volatility for electric powertrain OEMs. Distribution runs through captive dealer networks for mining applications and direct fleet contracts for warehouse automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial vehicles sector is consolidating around vertical-integration races for battery supply chain control and aftermarket service infrastructure. Players are pursuing backward integration into lithium processing and forward integration into predictive maintenance platforms as decisive competitive levers.
For Market Incumbents: Anticipate margin compression from Chinese electric forklift manufacturers leveraging MIIT new-energy vehicle mandates and domestic battery cost advantages. Secure captive lithium supply agreements with Indonesian and DRC processors to stabilize input costs. Accelerate ISO 3691 certification pipelines to compress multi-country type approval timelines that currently delay product launches. For New Entrants and Emerging Players: Autonomous navigation software for retrofit forklift fleets offers a technology-first wedge into established warehouse automation markets. Target India's Tamil Nadu and Gujarat manufacturing corridors where Production-Linked Incentive schemes reduce tariff exposure for greenfield assembly investments. Pursue battery-swap infrastructure partnerships with Yangtze River Delta logistics providers as the primary go-to-market angle. For Investors and Strategic Acquirers: KION Group AG's warehouse automation interface acquisitions are the leading indicator that material handling software capabilities are consolidating faster than hardware manufacturing scale. Frame long-term viability around captive battery supply and integrated service contract penetration rather than unit shipment growth. Monitor EPA Tier 4 Final enforcement timelines in California and Texas as the critical inflection signal for electric forklift demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Materials | Captive lithium and nickel supply from Indonesian processors insulates OEMs from cathode active material price volatility. |
| Warehouse Management System Integration | LiDAR-based navigation convergence with proprietary automation protocols opens retrofit markets for existing forklift fleets. |
| Multi-Shift Battery Swap Infrastructure | Automated swap stations in China's Yangtze River Delta eliminate charging dwell time and compress total-cost-of-ownership calculations. |
| ISO 3691 Certification Acceleration | Compressed type approval timelines enable faster product launches across modular electric platform designs. |
| India PLI Manufacturing Footprint | Greenfield assembly investments in Tamil Nadu and Gujarat capture tariff advantages for South Asian logistics network expansion. |
Research Approach
Independent corroboration across OEM procurement executives, fleet maintenance directors, battery supply chain specialists, and warehouse automation engineers underwrites the qualitative findings. Primary fieldwork with logistics providers in Germany, the United States, and China combined with secondary validation from EPA regulatory filings, EU Green Deal implementation documents, MIIT new-energy vehicle mandate disclosures, and SEC 10-K equipment manufacturer disclosures. Bottom-up demand modeling from individual fleet procurement decisions triangulates against top-down market sizing from production database aggregation.
Comparable-period anchoring to historical electric forklift penetration rates and diesel fleet replacement cycles established the forecast window baseline. The analytical framework segments by propulsion architecture, application duty cycle, and end-user industry vertical throughout the projection horizon. CAGRs derive from regression analysis against regulatory compliance deadlines and battery cost decline curves. Forecast inputs incorporate lithium iron phosphate battery chemistry adoption trajectories and autonomous vehicle R&D pipeline maturation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA enforcement acceleration or Indonesia nickel export restriction scenarios. A model refresh is warranted upon material change in EU carbon-border adjustment implementation timelines or Chinese MIIT mandate expansion to heavy-duty excavator segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Van Market