
 Trailers and Semi-Trailers Market | 2026-2036
Trailers and Semi-Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Trailers and Semi-Trailers Market Insights
The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is expanding the addressable market for lightweight trailer architectures across North American freight corridors. Wabash National Corporation leverages its DuraPlate composite panel technology to sustain margin premiums in dry van segments. Schmitz Cargobull anchors European refrigerated trailer demand through its S.KO COOL product line and dense service network across Germany and Poland.
Trailers and semi-trailers are unpowered freight vehicles designed for coupling to tractor units, typically constructed from high-strength steel, aluminum alloys, or composite sandwich panels with gross vehicle weight ratings spanning 10,000 to 80,000 pounds, serving the primary purpose of goods transportation across road networks. Flatbed configurations dominate North American construction and steel hauling due to loading flexibility, while refrigerated trailers command the highest per-unit margins driven by pharmaceutical cold-chain compliance and fresh food distribution requirements. Electric trailer technology, including axle-mounted regenerative systems, is gaining traction in European logistics fleets where emission-free zones in cities like Rotterdam and Hamburg restrict diesel tractor access.
The Federal Motor Carrier Safety Administration enforces structural integrity and brake performance standards that dictate trailer design minimums across interstate commerce. The European Union's F-Gas Regulation restricts refrigerant types in transport refrigeration units, compelling reefer manufacturers to adopt CO2 or propane-based cooling systems. Stakeholders must monitor how axle-load harmonization talks between the US DOT and Transport Canada reshape cross-border fleet specifications.
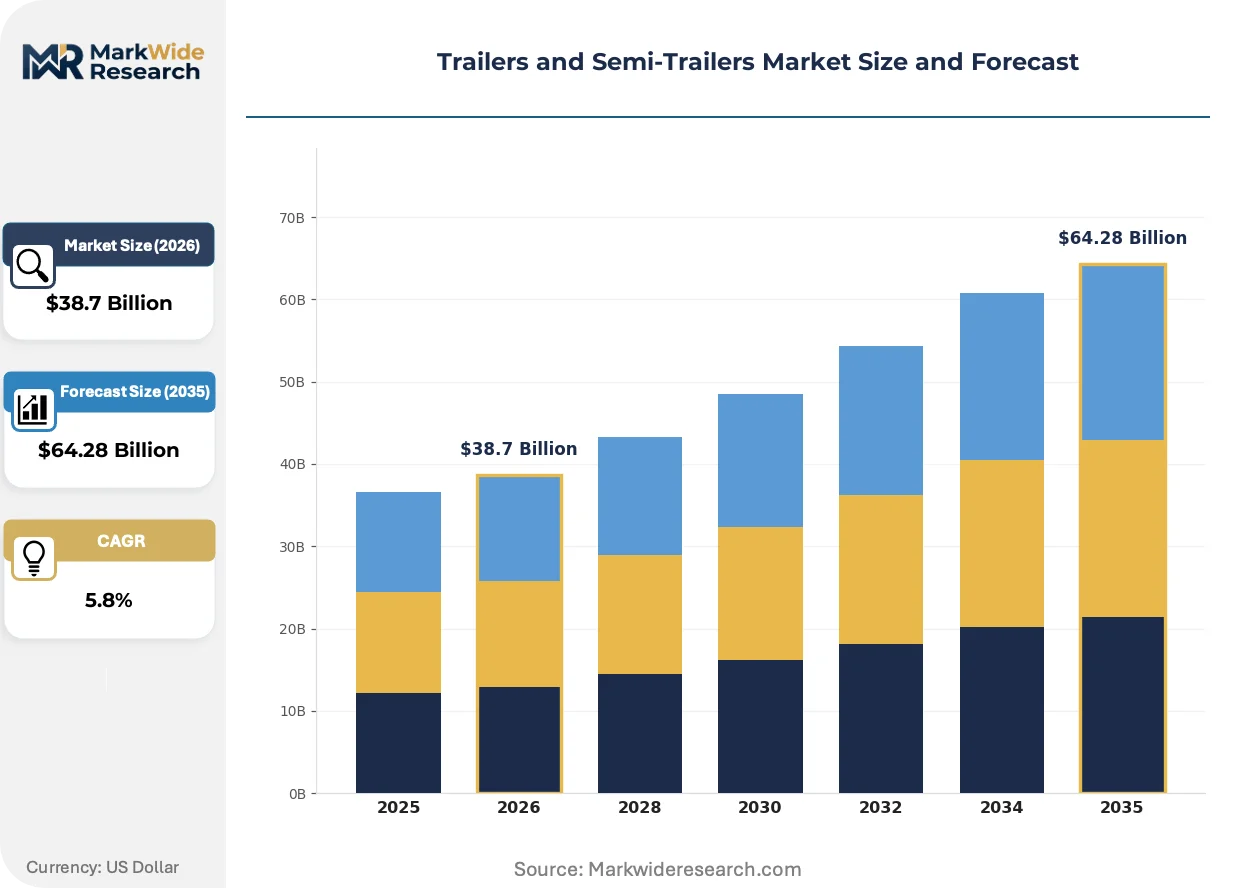
Market Dynamics
Lightweight material substitution is compressing trailer tare weights across long-haul fleets, driven by EPA Phase 3 compliance deadlines and fuel-economy imperatives from logistics operators running thin margins on diesel indexation.
Growth Catalysts
- Refrigerated trailer demand from pharmaceutical cold-chain:Temperature-sensitive biologics distribution is expanding reefer fleet orders, with fleet operators prioritizing units capable of maintaining 2-8°C across multi-day transits.
- EPA Phase 3 greenhouse gas standards:The regulation mandates progressive CO2 reductions for heavy-duty tractors, indirectly pressuring trailer weight reduction to preserve payload capacity under gross combination weight limits.
- E-commerce fulfillment center expansion:Parcel carriers are adding drop-frame dry vans and liftgate-equipped trailers to serve last-mile sortation facilities with dock-height mismatches.
Market Restraints
- Aluminum sheet and extrusion price volatility:Lightweight trailer architectures depend on primary aluminum inputs subject to LME price swings and Section 232 tariff uncertainty, compressing manufacturer margins on fixed-price fleet contracts.
- High-strength steel supply concentration:Domestic production of advanced high-strength steel grades for trailer chassis components concentrates among a limited set of integrated mills, creating vulnerability to mill outage or allocation decisions.
- Transport refrigeration unit refrigerant transition costs:The EU F-Gas Regulation and parallel US SNAP rules are phasing down hydrofluorocarbon refrigerants, forcing reefer manufacturers to retool for CO2 or propane systems with unproven service network coverage.
Strategic Opportunities
- Axle-mounted regenerative braking systems:Electric trailer technology capturing kinetic energy during deceleration offers independent propulsion assistance in urban emission-free zones, particularly relevant to Rotterdam and Hamburg access restrictions.
- Composite sandwich panel adoption in dry van sidewalls:DuraPlate-style composite construction delivers weight savings and damage resistance, creating upgrade cycles among fleets seeking total cost of ownership reductions.
- Cross-border fleet standardization between US DOT and Transport Canada:Harmonization talks on axle-load configurations and brake performance standards could simplify trailer specifications for North American operators running transcontinental routes.
Industry Challenges
- Welding technician scarcity for aluminum fabrication:Trailer manufacturers transitioning from steel to aluminum construction face competition for certified welders capable of gas metal arc welding on thin-gauge extrusions.
- Telematics integration with legacy fleet management platforms:Smart trailer deployments carrying sensor payloads for cargo monitoring, brake performance, and tire pressure require API compatibility with disparate carrier dispatch systems.
- Extended certification timelines for novel refrigerant systems:Transport refrigeration units using CO2 or propane require separate EPA and CARB approvals, delaying product launches against compressed fleet replacement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailers and Semi-Trailers Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Refrigerated, Lowboy, Dump End Use: Construction, Logistics, Agriculture, Manufacturing Technology: Hydraulic, Pneumatic, Electric, Mechanical Capacity: Lightweight, Medium Duty, Heavy Duty, Ultra Heavy |
| Companies Covered | Hyundai Translead, Wabash National Corporation, Utility Trailer Manufacturing Company, Great Dane, Schmitz Cargobull, Fontaine Trailer Company, Stoughton Trailers, Vanguard National Trailer, Krone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailers and Semi-Trailers Market Trends and Innovations
Digital freight matching platforms and sensor-enabled trailer telematics are compressing asset utilization cycles, while regulatory pressure on tractor emissions indirectly accelerates trailer lightweighting investments.
Axle-mounted regenerative systems are electrifying trailer propulsion architectures. European logistics operators in Rotterdam and Hamburg emission-free zones are piloting units that capture braking energy and redeploy it for low-speed maneuvering. This technology is electrifying the traditional unpowered trailer category, enabling diesel tractor access restrictions without requiring full battery-electric tractor replacement.
The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in transport refrigeration units. Reefer manufacturers are redesigning cooling circuits around CO2 transcritical or propane-based systems with lower global warming potential. Pharmaceutical and fresh food distribution fleets face the steepest compliance timelines, accelerating pre-buy activity ahead of phase-down deadlines.
Asset-light procurement models are displacing traditional trailer ownership among mid-sized carriers. Third-party trailer pooling services offering per-mile or per-day pricing are capturing share from capital-intensive fleet purchases. This shift concentrates most visibly among US regional LTL operators seeking flexibility against freight volume volatility.
Trailers and Semi-Trailers Market Segmentation
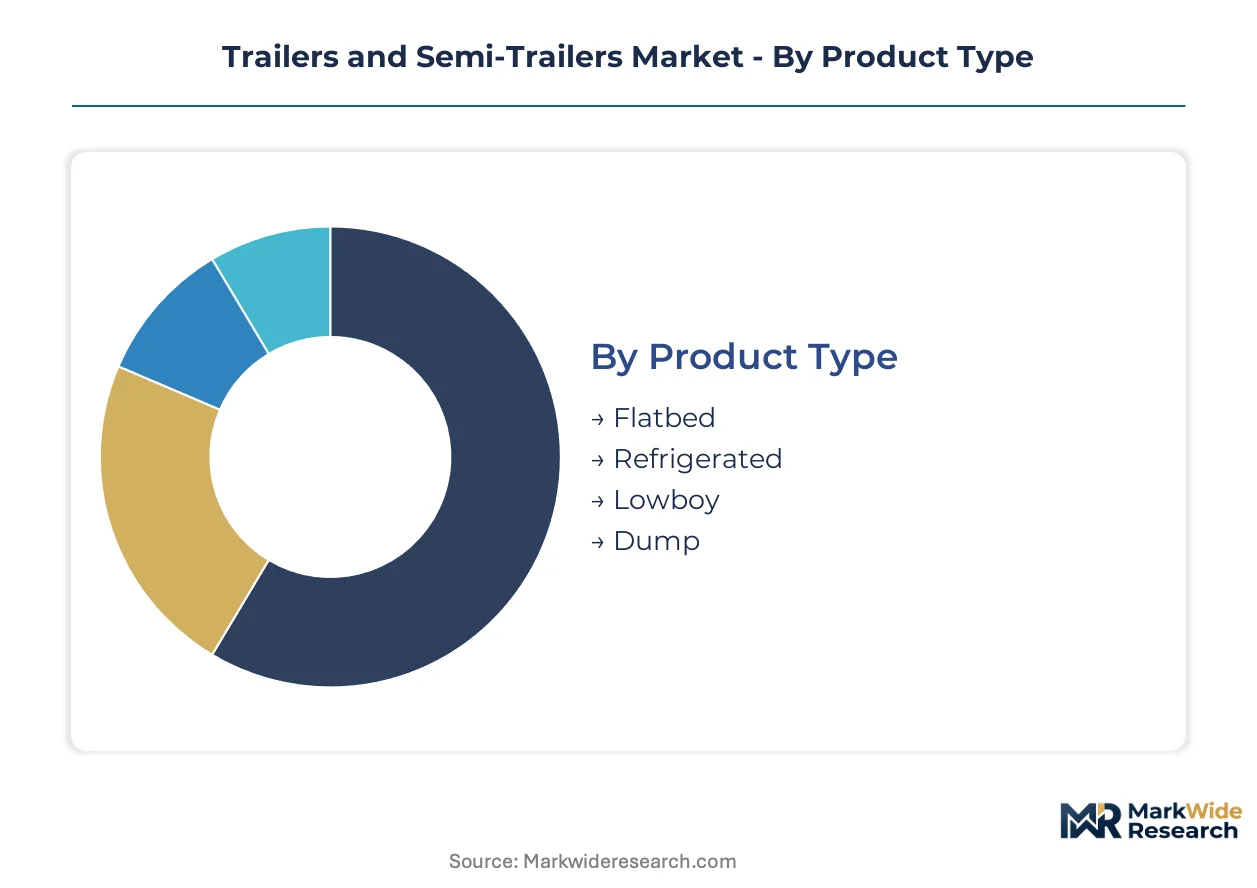
Segmentation reveals where capital deployment concentrates and which trailer configurations command pricing power. Fleet operators and manufacturers allocate resources differently across product architectures, end-use applications, and technology tiers.
Product Type:
Capital intensity varies sharply across trailer architectures, with refrigerated units requiring the steepest upfront investment due to integrated cooling systems and pharmaceutical-grade insulation.
- Flatbed:Open-deck steel or aluminum platforms enable side-loading flexibility for construction materials and industrial equipment. Demand clusters in Texas and Alberta oilfield corridors where pipe and machinery hauling dominates fleet utilization, though steel price volatility compresses margins on fixed-rate contracts.
- Refrigerated:Insulated composite sandwich panels surround transport refrigeration units maintaining temperature bands from frozen to controlled ambient. Pharmaceutical distributors in Germany and fresh food chains in California drive specification upgrades toward CO2-based cooling systems ahead of F-Gas Regulation deadlines.
- Lowboy:Drop-deck configurations accommodate oversized loads with deck heights below 24 inches.
- Dump:Hydraulic-lift beds serve aggregate and construction waste hauling with reinforced steel bodies.
Flatbed absorbs the bulk of installed capacity; refrigerated is expanding most quickly.
End Use:
Application context determines duty cycles, corrosion exposure, and telematics requirements across trailer deployments.
- Construction:Harsh-duty flatbeds and dumps face abrasion from aggregate loading and de-icing salt exposure. Fleet operators in Florida and Arizona prioritize aluminum configurations for corrosion resistance against coastal and desert operating conditions.
- Logistics:Dry vans and reefers serve parcel sortation and cold-chain distribution with dock-height compatibility and liftgate integration. E-commerce fulfillment networks in Pennsylvania and Ohio drive demand for drop-frame configurations addressing facility grade mismatches.
- Agriculture:Grain hoppers and livestock trailers require washdown-compatible interiors and ventilation systems.
- Manufacturing:Just-in-time parts delivery favors curtain-sided trailers with rapid access for assembly line sequencing.
Logistics commands the largest share of new orders; construction shows the steepest replacement cycle volatility.
Technology:
Lifting and suspension architectures separate premium specifications from commodity offerings in fleet procurement decisions.
- Hydraulic:High-pressure fluid systems enable precise load positioning in dump and lowboy applications. Mining operators in Western Australia specify hydraulic suspensions for terrain adaptability on unimproved haul roads, though seal maintenance drives lifecycle cost premiums.
- Electric:Axle-mounted regenerative systems capture braking energy for auxiliary propulsion in urban emission-free zones. Rotterdam and Hamburg logistics pilots demonstrate diesel tractor compatibility with zero-emission zone access, creating retrofit demand among European refrigerated fleets.
- Pneumatic:Air-ride suspensions protect fragile cargo and enable chassis height adjustment for dock alignment.
- Mechanical:Leaf-spring suspensions dominate price-sensitive agricultural and construction segments.
Hydraulic retains the largest installed base; electric is climbing the fastest on regulatory tailwinds.
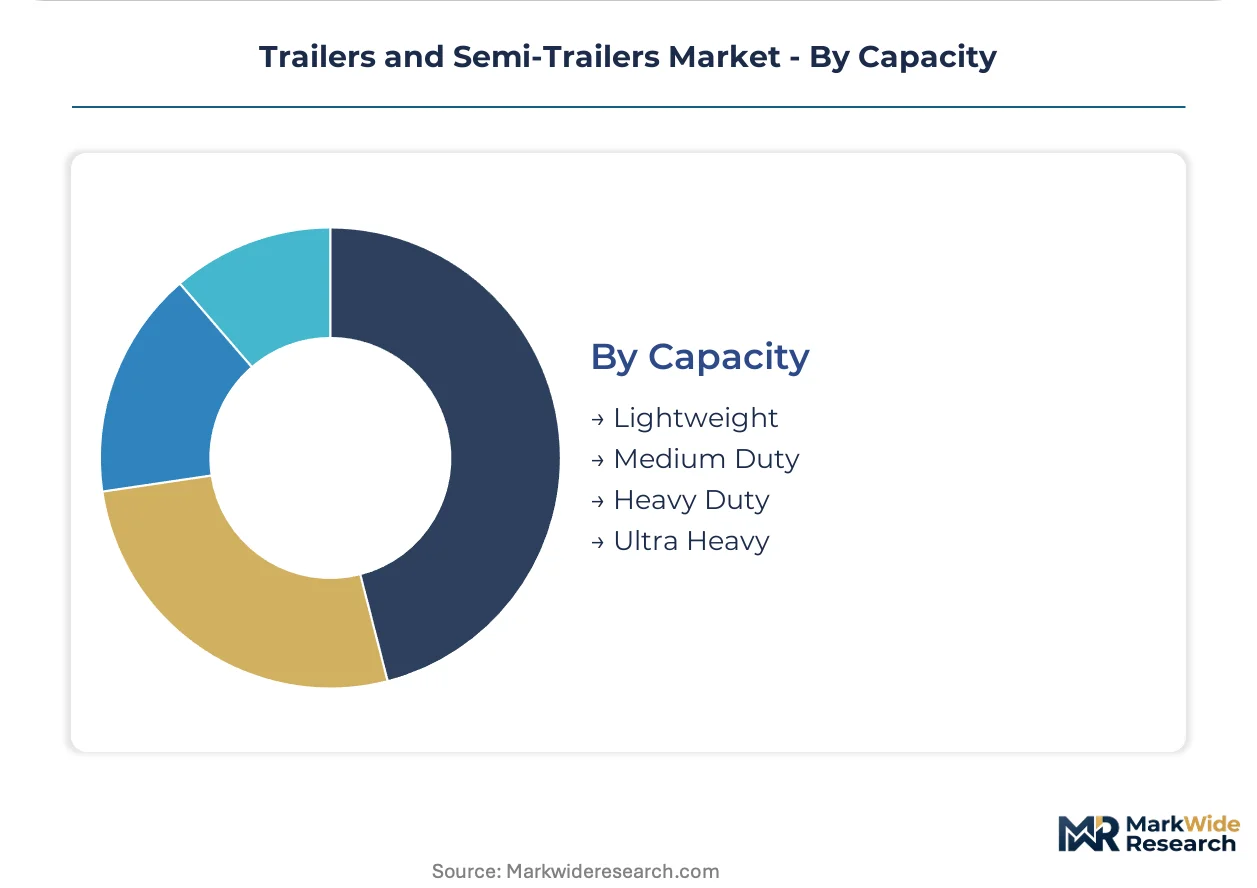
Capacity:
Gross vehicle weight ratings dictate chassis engineering, brake specifications, and regulatory compliance burdens across fleet categories.
- Heavy Duty:Steel or hybrid chassis configurations rated 33,000 to 80,000 pounds gross vehicle weight serve interstate bulk commodity and refrigerated freight. Long-haul operators running I-80 and I-10 corridors prioritize aluminum substitution to preserve payload under EPA Phase 3 combination weight constraints.
- Lightweight:Composite-intensive designs below 10,000 pounds gross vehicle weight enable passenger vehicle towing for last-mile delivery and recreational applications. Last-mile parcel carriers in suburban California and Texas deploy lightweight dry vans behind medium-duty trucks for residential drop density.
- Medium Duty:Regional distribution and urban delivery configurations balance maneuverability with cubic capacity.
- Ultra Heavy:Specialized permits allow overweight configurations for mining and wind energy component transport.
Heavy Duty carries the majority of freight ton-miles; lightweight is gaining share fastest on e-commerce last-mile expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American trailer demand through its dense concentration of automotive parts logistics and cross-border freight corridors serving Ontario assembly plants.
United States
Long-haul freight volumes along I-80 and I-10 corridors drive heavy-duty dry van replacement cycles. The EPA Phase 3 greenhouse gas standards pressure fleet operators toward aluminum-intensive designs to preserve payload capacity. Dallas-Fort Worth concentrates refrigerated trailer distribution for pharmaceutical cold-chain networks serving Southwestern population centers.
Germany
Schmitz Cargobull's S.KO COOL product line dominates refrigerated trailer specifications for pharmaceutical distributors. The EU F-Gas Regulation compels reefer manufacturers to retool for CO2 transcritical cooling systems ahead of hydrofluorocarbon phase-down deadlines. The Ruhr industrial corridor hosts dense service networks supporting cross-border fleets operating into Poland and the Netherlands.
China
E-commerce logistics expansion in the Yangtze River Delta generates demand for lightweight dry vans behind medium-duty trucks. The MIIT enforces fuel consumption standards for commercial vehicles that indirectly favor trailer weight reduction. Shanghai's port logistics cluster pilots electric trailer technology with axle-mounted regenerative systems for urban emission-free zones.
Mexico
Nearshoring manufacturing growth in Nuevo León and the Bajío Region accelerates cross-border flatbed demand for machinery and automotive components transport. The Secretariat of Economy coordinates with US DOT on axle-load harmonization talks affecting transcontinental fleet specifications. Monterrey serves as the primary distribution hub for US-bound refrigerated produce from Sinaloa and Jalisco growing regions.
Netherlands
Rotterdam's emission-free zone restrictions drive pilot deployments of electric trailer technology with independent low-speed propulsion. The EU Green Deal freight transport decarbonization targets align with Dutch national policies favoring zero-emission logistics corridors. The Randstad logistics cluster integrates smart trailer telematics with port automation systems for North Sea shipping connections.
Trailers and Semi-Trailers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and cold-chain specialization tiers. The vendor base stratifies between integrated manufacturers with captive composite panel production and regional fabricators purchasing standardized subassemblies. Three archetypes dominate: lightweight technology specialists, refrigerated system integrators, and scale-driven dry van producers. Consolidation pressures concentrate among mid-tier regional players lacking proprietary material technologies, while technology licensing agreements proliferate between European cooling system specialists and North American chassis manufacturers.
Among North American fabricators, Wabash National Corporation and Utility Trailer Manufacturing Company occupy positions within the premium-tier composite technology segment. Schmitz Cargobull anchors European refrigerated trailer specifications through its dense service infrastructure. Hyundai Translead represents the scale-driven archetype serving high-volume fleet operators with standardized dry van configurations.
| Leading Market Players |
|---|
| Hyundai Translead |
| Wabash National Corporation |
| Utility Trailer Manufacturing Company |
| Great Dane |
| Schmitz Cargobull |
| Fontaine Trailer Company |
| Stoughton Trailers |
| Vanguard National Trailer |
| Krone |
| Others |
Pricing and Supply Chain Analysis
Certified aluminum welders in the Upper Midwest command wage premiums that compress margin spreads between premium composite trailers and commodity steel units. Labor-cost differentials across fabrication regions widen pricing-tier spreads as manufacturers compete for gas metal arc welding specialists capable of thin-gauge extrusion work.
Pricing Analysis
Total-cost-of-ownership guarantees anchor value-based pricing for refrigerated trailers serving pharmaceutical cold-chain operators. Three-tier pricing structure across premium, standard, and economy levels separates CO2-based reefer systems from hydrofluorocarbon legacy units from basic dry van configurations. Price differentiation hinges on insulation R-value certification and telematics integration depth. Cost compression in economy-tier steel flatbeds is intensifying because of high-strength steel allocation constraints at domestic integrated mills. Fleet operators running thin diesel margins exhibit highest price sensitivity; pharmaceutical distributors with compliance-driven procurement show lowest.
Supply Chain Analysis
Dual-sourcing requirements from major fleet operators mandate multi-supplier qualification for aluminum sheet and extrusion inputs across the United States, Germany, and China. Raw material dependencies center on primary aluminum, advanced high-strength steel grades, and composite sandwich panel substrates. Supply chain risk concentrates in Section 232 tariff exposure affecting aluminum price volatility. Distribution runs through direct OEM-fleet contracts and third-party trailer pooling services capturing share from capital-intensive ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trailers and semi-trailers market sits in a technology-transition phase as axle-mounted regenerative braking systems displace conventional unpowered architectures in European emission-free zones.
For Market Incumbents: Deepen captive composite panel production to defend margin premiums against regional fabricators purchasing standardized subassemblies. Expand service network density in Germany and Poland to anchor refrigerated trailer specifications ahead of F-Gas Regulation compliance deadlines. Prioritize welding technician apprenticeship pipelines to secure aluminum fabrication capacity against workforce scarcity. For New Entrants and Emerging Players: Direct-to-fleet telematics platforms offer a digital-channel route to bypass incumbent distributor relationships. Target lightweight dry van segments serving e-commerce fulfillment networks in Pennsylvania and Ohio with dock-height mismatch solutions. Pursue asset-light procurement partnerships with regional LTL operators seeking per-mile pricing flexibility. For Investors and Strategic Acquirers: The window for entry favors mid-tier regional fabricators lacking proprietary material technologies but holding dense service infrastructure. Long-term viability rests on consolidation plays that integrate composite technology licensing with established fleet relationships. Watch EPA Phase 3 compliance timeline acceleration as inflection indicator for aluminum-intensive trailer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Panel Technology Licensing | Enables margin premiums in dry van segments through DuraPlate-style weight reduction. |
| CO2 Transcritical Cooling System Retooling | Positions reefer manufacturers ahead of EU F-Gas Regulation phase-down deadlines. |
| Axle-Mounted Regenerative System Deployment | Captures Rotterdam and Hamburg emission-free zone access without full tractor electrification. |
| Third-Party Trailer Pooling Service Expansion | Addresses freight volume volatility for mid-sized carriers seeking capital flexibility. |
| Cross-Border Axle-Load Harmonization Alignment | Simplifies fleet specifications for US-Canada transcontinental operators under DOT-Transport Canada talks. |
Research Methodology
Multi-period observation of fleet replacement cycles, refrigerated trailer order backlogs, and aluminum price volatility anchored the trend analysis, supplemented by interviews with fleet procurement directors, trailer manufacturing plant managers, welding technician training program administrators, and transport refrigeration unit service heads. Secondary validation drew from FMCSA brake performance filings, EPA Phase 3 regulatory dockets, EU F-Gas Regulation implementation reports, and customs trade data on aluminum extrusion imports. Bottom-up unit economics triangulated against top-down freight volume projections.
Input-output matrices mapped trailer production capacity, material input costs, and fleet utilization rates across product type, end-use application, technology tier, and gross vehicle weight rating segments. CAGRs were derived from regression analysis against freight ton-mile growth and regulatory compliance timeline assumptions. Industry-specific forecast inputs included diesel price indexation sensitivity and pharmaceutical cold-chain expansion rates.
The model holds under stable aluminum tariff regimes and phased regulatory implementation; deviation in Section 232 trade policy or accelerated EPA enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Europe Automotive Lightweight Car Market