
 Trailer Telematics Market | 2026-2036
Trailer Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Telematics Market Outlook
The trailer telematics market is repositioning around a stark split between premium sensor-integrated platforms and basic GPS-only commodity hardware. Fleet operators now face diverging procurement paths as advanced units bundle tire pressure monitoring, cargo sensing, and predictive maintenance algorithms while entry-level devices remain confined to location tracking. Trimble leverages its agricultural and construction telemetry heritage to anchor high-value trailer solutions with cross-vertical data interoperability. Samsara competes through cloud-native architecture that unifies tractor and trailer visibility on a single software layer. Geotab sustains channel dominance via its open-platform ecosystem, allowing third-party sensor integration without proprietary lock-in.
Trailer telematics encompasses hardware and software systems that capture, transmit, and analyze operational data from semi-trailers and commercial freight containers, typically integrating GPS receivers, cellular modems, and CAN-bus interfaces to report location, status, and environmental conditions at refresh intervals ranging from one minute to real-time streaming. These systems serve primary industrial purposes of asset utilization optimization, regulatory compliance automation, and cargo integrity assurance across distributed supply chains. Fleet management solutions now capture the deepest margin pools as recurring software subscriptions outpace hardware margins, while sensors represent the fastest-expanding hardware category as temperature, door, and tire pressure monitoring become standard in pharmaceutical and food logistics. Communication modules remain the most mature segment, dominated by commoditized cellular chipsets where differentiation has collapsed to firmware customization and carrier negotiation.
The Federal Motor Carrier Safety Administration's ELD mandate and the EPA's Phase 2 greenhouse gas standards collectively shape product roadmaps by mandating electronic logging and incentivizing fuel-efficiency telemetry. The FCC governs spectrum allocation for cellular and satellite communication modules that underpin data transmission from remote highway corridors. The NHTSA's emerging connected-vehicle standards will likely extend to trailer-to-tractor and trailer-to-infrastructure communication protocols. Stakeholders must now decide whether to build in-house telematics stacks or surrender data sovereignty to platform aggregators as fleet data becomes the decisive input for insurance underwriting and shipper procurement algorithms.
Market Dynamics
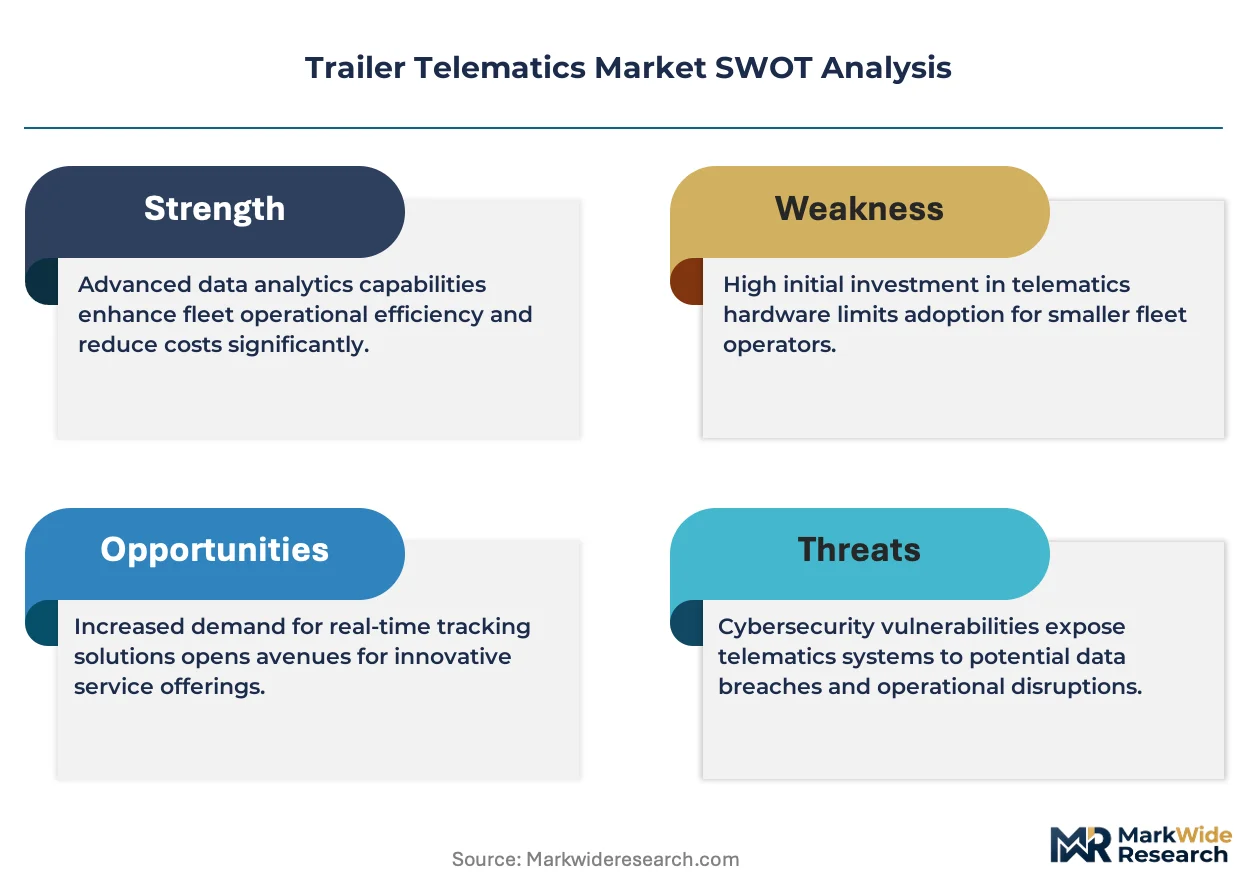
Trailer telematics hardware suppliers face margin compression as cellular modems commoditize and fleet operators demand unified tractor-trailer software stacks rather than siloed point solutions.
Growth Catalysts
- ELD Mandate Enforcement:The Federal Motor Carrier Safety Administration's electronic logging device requirement forces fleet-wide connectivity upgrades across long-haul operations, embedding telematics as a compliance infrastructure layer.
- Cold-Chain Integrity Demands:Pharmaceutical and food logistics operators deploy temperature-monitoring sensors to reduce spoilage liability and satisfy shipper audit requirements.
- Insurance Underwriting Algorithms:Fleet data feeds directly into risk-scoring models, creating procurement pressure for granular trailer visibility beyond basic location pings.
Market Restraints
- Cellular Module Commoditization:Qualcomm and MediaTek chipset dominance collapses hardware differentiation to firmware layers, eroding OEM margins.
- Fleet Operator Data Sovereignty Concerns:Large carriers resist surrendering operational data to third-party platform aggregators, slowing cloud-native adoption.
- Legacy Trailer Retrofit Costs:Older dry van and refrigerated fleets require expensive installation labor and power routing, extending replacement cycles.
Strategic Opportunities
- Underpenetrated Flatbed and Tanker Segments:Specialized freight categories lag dry van in sensor penetration, creating whitespace for cargo-secure monitoring and hazardous materials compliance tools.
- Trailer-to-Tractor Autonomous Handshaking:V2V communication protocols enable automated pairing and diagnostics, reducing yard management labor.
- Predictive Maintenance Algorithms:Tire pressure and brake wear data streams unlock subscription revenue from component suppliers seeking fleet-wide failure forecasting.
Industry Challenges
- Cross-Platform Data Interoperability:Fleet management systems from disparate vendors resist seamless integration, forcing operators into expensive middleware or single-source lock-in.
- Certification Lag for Satellite Backup Modules:Dual-mode cellular-satellite hardware faces extended FCC and carrier approval timelines, delaying coverage for remote corridor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Telematics Market |
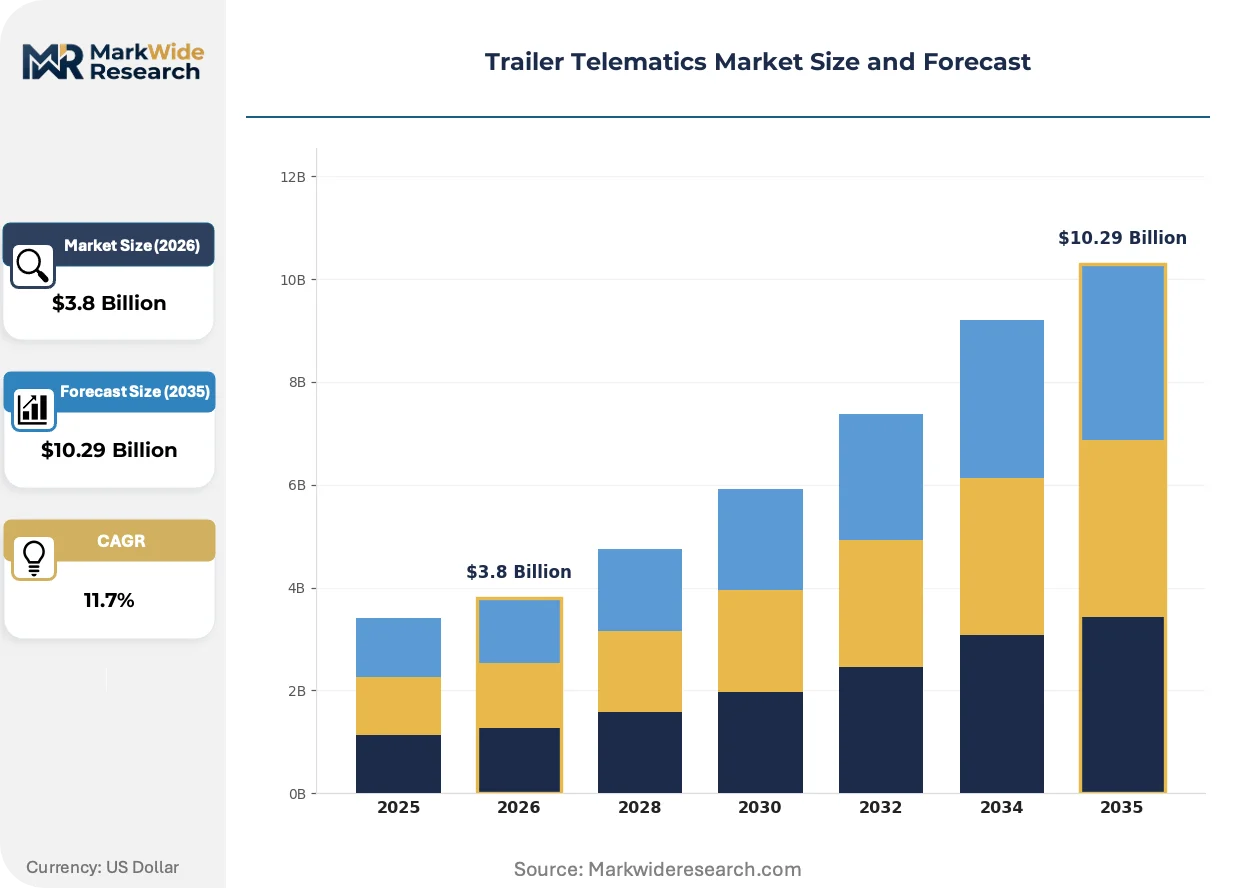
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracking Systems, Fleet Management Solutions, Sensors, Communication Modules Application: Vehicle Tracking, Asset Management, Performance Monitoring, Safety Compliance End User: Logistics Companies, Fleet Operators, Shipping Enterprises, Third-Party Logistics Technology: GPS, IoT, Telematics Software, Cloud Computing |
| Companies Covered | Trimble, Omnitracs, Geotab, Teletrac Navman, Platform Science, Samsara, Powerfleet, Zonar, Verizon Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Telematics Market Strategic Shifts
Sensor fusion architectures and edge computing capabilities are compressing refresh intervals from minutes to seconds, enabling real-time cargo anomaly detection that shifts liability frameworks between carriers and shippers.
Multi-sensor trailer gateways are consolidating tire pressure, door status, temperature, and cargo imaging into single hardware units. Refrigerated fleet operators in pharmaceutical logistics adopt these integrated platforms fastest, collapsing procurement from four vendor relationships to one. The structural result is margin pressure on standalone sensor suppliers and accelerated platform consolidation among surviving hardware vendors.
The EPA's Phase 2 greenhouse gas standards incentivize aerodynamic and tire rolling-resistance telemetry that feeds fuel-efficiency scoring. Trailer-mounted sensors now capture real-world performance data that manufacturers use for regulatory credit documentation. Dry van fleets in California face the steepest compliance burdens, driving early adoption of integrated aerodynamic monitoring packages.
Shippers now specify telematics certification tiers in procurement contracts, unbundling hardware compliance from rate negotiations. Large retail and grocery chains audit trailer sensor coverage before awarding dedicated fleet contracts. This behavioral shift concentrates most intensely in United States food and pharmaceutical corridors where cargo integrity liability carries the highest financial penalties.
Trailer Telematics Market Segmentation
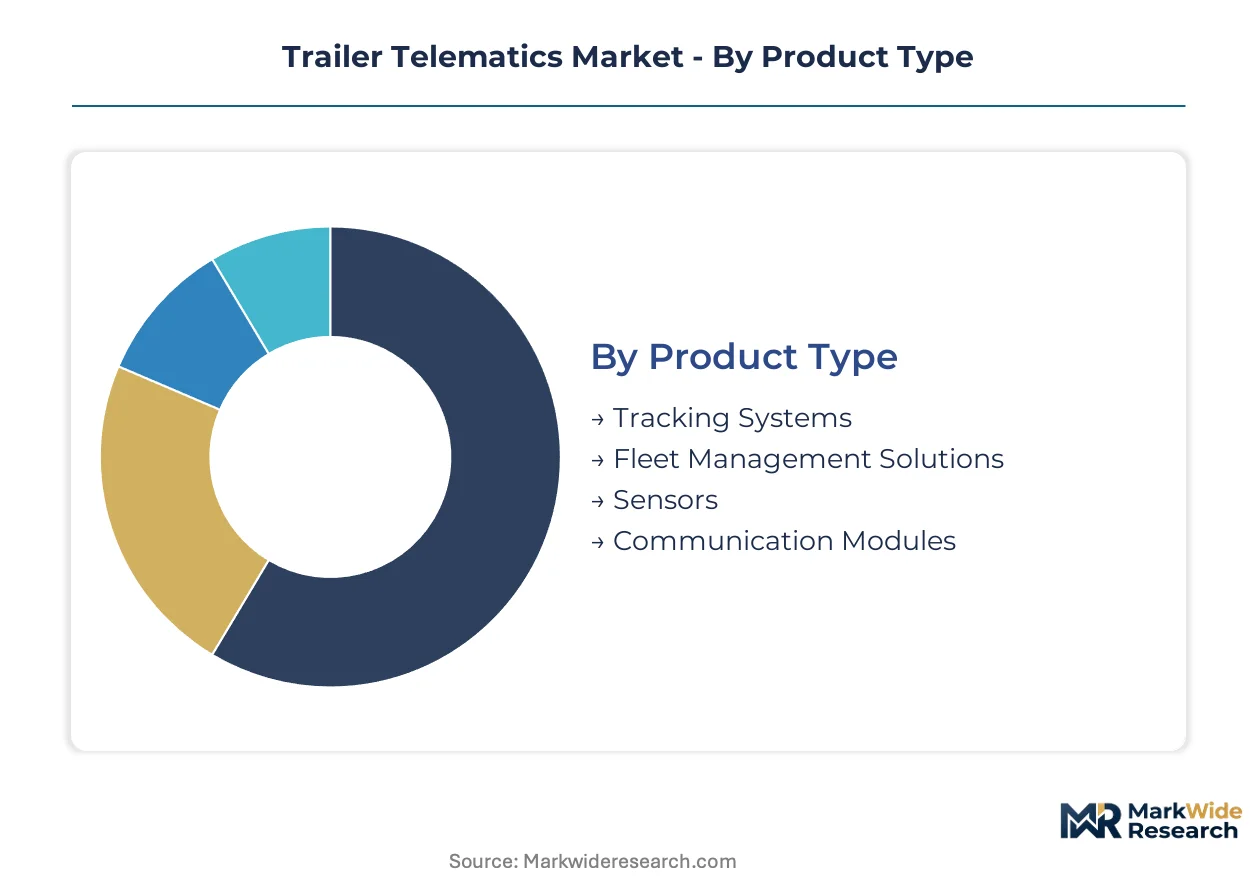
Trailer telematics procurement splits sharply between hardware-centric buyers seeking component modularity and software-first operators demanding unified data layers. Fleet managers now evaluate segments through total cost of ownership lenses rather than upfront equipment pricing.
Product Type:
Supply concentration tilts toward integrated platform vendors as standalone hardware margins compress and fleet operators consolidate vendor relationships.
- Fleet Management Solutions:Cloud-native software stacks unify tractor and trailer visibility through subscription billing models. Demand concentrates among large US-based carriers seeking to reduce middleware costs and eliminate data silos between dispatch and maintenance systems.
- Sensors:Multi-sensor gateways consolidate tire pressure, door status, temperature, and cargo imaging into single hardware units. Cold-chain operators in pharmaceutical corridors deploy these fastest to satisfy shipper audit requirements and reduce spoilage liability.
- Tracking Systems:GPS-dominant hardware with refresh intervals from one minute to real-time streaming serves asset-heavy fleets with basic visibility needs.
- Communication Modules:Cellular and satellite modems face commoditization pressure from Qualcomm and MediaTek chipset dominance, collapsing differentiation to firmware customization.
Today's leader: Fleet Management Solutions. Tomorrow's challenger: Sensors.
Application:
Cost tier stratification separates premium predictive platforms from compliance-minimum installations as insurance underwriting algorithms raise the data granularity threshold.
- Asset Management:Utilization optimization tools track dwell time, detention billing, and pool fleet rotation. Large retail and grocery chains in US food corridors now specify telematics certification tiers before awarding dedicated fleet contracts.
- Safety Compliance:ELD mandate enforcement and hours-of-service automation embed telematics as regulatory infrastructure. The FMCSA's electronic logging requirements force fleet-wide connectivity upgrades across long-haul operations.
- Vehicle Tracking:Location-centric applications serve smaller operators with basic GPS pings and geofencing alerts.
- Performance Monitoring:Fuel-efficiency and aerodynamic telemetry feed EPA Phase 2 greenhouse gas compliance documentation for dry van manufacturers.
Asset Management commands premium pricing. Safety Compliance drives volume penetration.
End User:
Customer type fragmentation produces divergent procurement patterns as asset owners, contracted carriers, and brokered networks prioritize different data sovereignty models.
- Logistics Companies:Integrated supply chain operators demand end-to-end visibility across shipper, carrier, and receiver touchpoints. Third-party platform aggregators capture this segment fastest through API-first architectures.
- Fleet Operators:Asset-owning carriers resist surrendering operational data to external platforms, favoring open-ecosystem vendors allowing in-house data lake retention.
- Third-Party Logistics:Brokerage-heavy networks prioritize rapid deployment and minimal installation labor across heterogeneous trailer pools.
- Shipping Enterprises:Container lines and maritime intermodal operators seek cross-modal visibility spanning port, rail, and drayage segments.
Logistics Companies set integration standards. Fleet Operators resist data centralization.
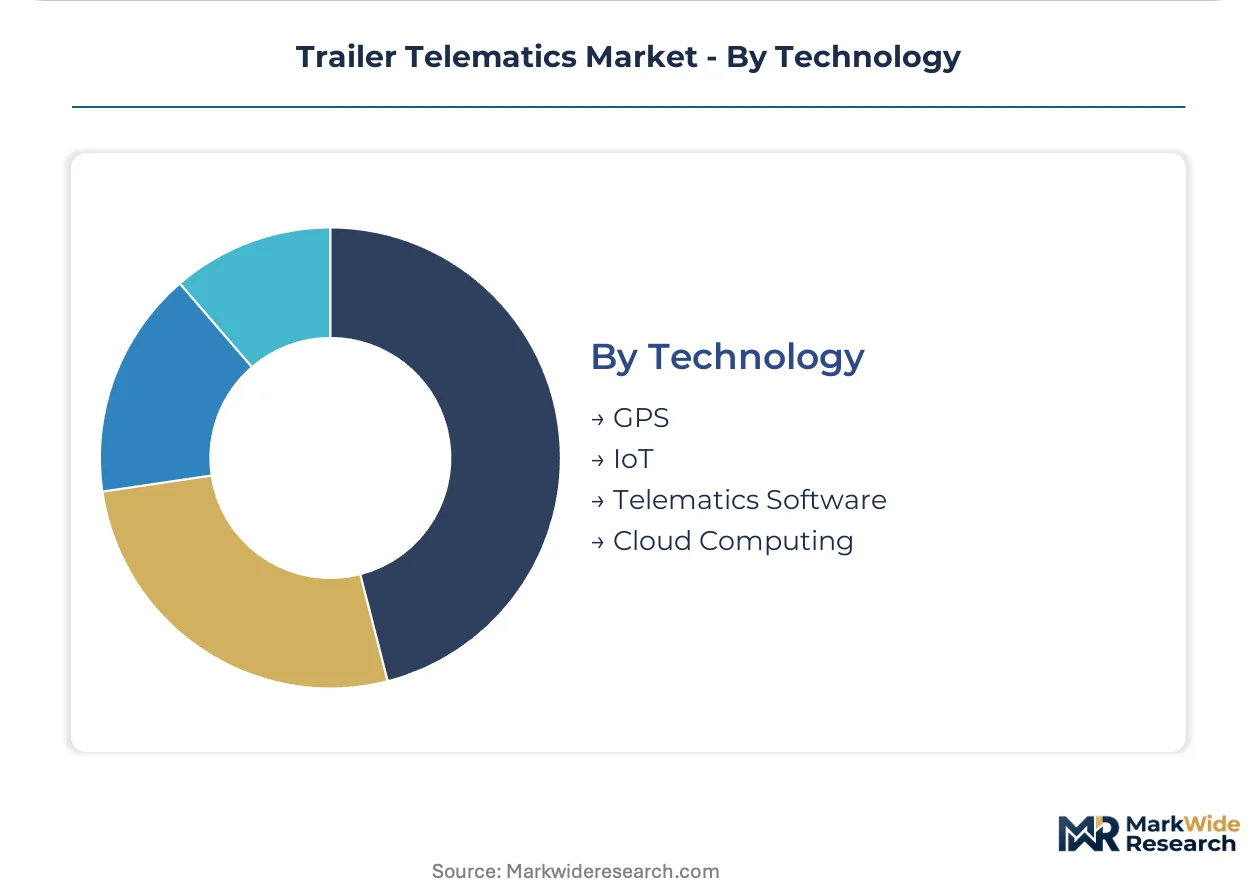
Technology:
Maturity curves diverge sharply as GPS and cellular hardware commoditize while edge computing and AI-driven analytics command expanding margin pools.
- Cloud Computing:Centralized data architectures enable predictive maintenance algorithms and subscription revenue models. Component suppliers seeking fleet-wide failure forecasting partner with cloud-native platform vendors for tire pressure and brake wear analytics.
- IoT:Sensor fusion architectures compress refresh intervals from minutes to seconds, enabling real-time cargo anomaly detection that shifts liability frameworks between carriers and shippers.
- GPS:Satellite positioning remains foundational but undifferentiated, with accuracy improvements driven by multi-constellation receiver integration.
- Telematics Software:Middleware layers face consolidation pressure as fleet management platforms absorb functionality previously delivered by standalone vendors.
Cloud Computing anchors recurring revenue. IoT enables the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet telematics engineers and logistics software developers concentrate in North American freight corridors, German automotive clusters, and Chinese manufacturing hubs where cold-chain compliance and ELD enforcement drive hardware deployment.
United States
Long-haul freight density and the FMCSA's ELD mandate force fleet-wide connectivity upgrades across interstate corridors. The EPA's Phase 2 greenhouse gas standards incentivize aerodynamic telemetry documentation. California's Central Valley and Texas's Dallas-Fort Worth metro anchor pharmaceutical and food logistics operations where temperature-monitoring sensors reduce spoilage liability.
Germany
Precision manufacturing heritage and dense autobahn freight networks sustain demand for integrated tractor-trailer visibility platforms. The EU's CSRD reporting requirements and Germany's national emissions trading scheme pressure fleet operators toward granular fuel-efficiency telemetry. Baden-Württemberg's Stuttgart region hosts automotive logistics clusters where predictive maintenance algorithms command premium subscription pricing.
China
Domestic e-commerce logistics expansion and MIIT-connected vehicle mandates accelerate telematics penetration across refrigerated freight fleets. The country's dual carbon goals incentivize real-world fuel consumption monitoring for regulatory credit documentation. Yangtze River Delta manufacturing corridors around Shanghai deploy multi-sensor gateways fastest to satisfy export cold-chain audit requirements.
United Kingdom
Post-Brexit customs complexity and port congestion drive demand for cross-modal visibility spanning maritime, rail, and road segments. The UK's adoption of EU-derived vehicle emissions standards maintains pressure on aerodynamic performance monitoring. Midlands logistics hubs around Birmingham concentrate third-party fleet operators resisting data sovereignty surrender to external platform aggregators.
India
Pharmaceutical export growth and FSSAI cold-chain regulations expand temperature-monitoring sensor deployment across refrigerated fleets. The government's PLI scheme for automotive components indirectly supports telematics hardware manufacturing scale. Maharashtra's Mumbai-Pune industrial corridor anchors logistics technology adoption where brokered networks prioritize rapid deployment across heterogeneous trailer pools.
Trailer Telematics Market Competitive Environment
Capital-heavy hardware producers compete with asset-light software platform designers across the trailer telematics value chain. Cellular modem manufacturers face margin compression from chipset commoditization while cloud-native platform vendors capture recurring subscription revenue. Three strategic archetypes dominate: integrated fleet management platforms bundling tractor-trailer visibility, standalone sensor specialists consolidating multi-function gateways, and telecommunication carriers leveraging network infrastructure for vertical service expansion. Competitive intensity centers on M&A activity absorbing point-solution vendors into unified stacks and strategic partnerships between component suppliers seeking failure-forecasting data access.
Among North American platform vendors, Trimble, Samsara, and Geotab exemplify divergent architectural approaches to fleet data unification. Trimble represents cross-vertical telemetry heritage extending into agricultural and construction equipment interoperability. Samsara occupies a position within cloud-native architecture emphasizing unified software layers across distributed assets. Geotab anchors open-platform ecosystem strategies enabling third-party sensor integration without proprietary data lock-in. These three vendors collectively illustrate the strategic tension between integrated vertical stacks and modular interoperability that shapes procurement decisions among large fleet operators.
| Leading Market Players |
|---|
| Trimble |
| Omnitracs |
| Geotab |
| Teletrac Navman |
| Platform Science |
| Samsara |
| Powerfleet |
| Zonar |
| Verizon Connect |
| Others |
Value Chain & Pricing Dynamics
Backward integration into cellular modem firmware anchors pricing power for integrated platform vendors while eroding margins for standalone hardware suppliers. Fleet operators now consolidate vendor relationships around bundled tractor-trailer software stacks, compressing procurement leverage for point-solution vendors.
Pricing Analysis
Bundled subscription services separate integrated fleet management platforms from unbundled hardware-only transactions. Three-tier pricing structure across premium sensor-integrated, standard compliance-grade, and economy GPS-only levels reflects certification intensity and data granularity. Pricing pressure stems from Qualcomm and MediaTek chipset commoditization collapsing hardware differentiation. Small brokered fleets exhibit highest price sensitivity; pharmaceutical cold-chain operators show lowest sensitivity due to spoilage liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced cellular baseband chipsets and GPS receiver modules. Component sourcing draws from China for plastic enclosures and battery cells, Mexico for cable assemblies, and Germany for precision sensors. Tariff exposure on Chinese electronics intensifies supply chain risk for cost-optimized hardware tiers. Distribution runs through direct enterprise sales for large fleets and telecommunications carrier channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trailer telematics market reads as a late-cycle quality story where shipper procurement algorithms now specify telematics certification tiers before awarding dedicated fleet contracts. Premium sensor-integrated platforms capture expanding margin pools as basic GPS hardware commoditizes.
For Market Incumbents: Cement platform stickiness through predictive maintenance algorithm partnerships with tire and brake component suppliers seeking fleet-wide failure forecasting data. Deepen API-first architectures to capture third-party logistics integration standards before cloud-native competitors consolidate shipper-facing visibility layers. Threat substitution from open-ecosystem vendors like Geotab demands proprietary data lake retention capabilities for fleet operator data sovereignty concerns. For New Entrants and Emerging Players: Telecommunications carriers offer the most penetrable channel partnership for vertical service expansion into trailer telematics without captive hardware manufacturing. Target flatbed and tanker segments where cargo-secure monitoring and hazardous materials compliance tools remain underpenetrated relative to dry van saturation. White-space exists in satellite backup modules for remote corridor coverage where FCC certification lag delays incumbent deployment timelines. For Investors and Strategic Acquirers: Roll-up economics work for standalone sensor specialists because multi-sensor gateway consolidation collapses procurement from four vendor relationships to one, creating platform-scale exit multiples. Long-term viability centers on recurring software subscription revenue outrunning hardware margin compression. Watch shipper audit requirement intensity in US food and pharmaceutical corridors as the inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies tractor and trailer visibility through cloud-native software layers, reducing middleware costs for large US-based carriers. |
| Sensor Gateway Consolidation | Collapses tire pressure, door status, temperature, and cargo imaging into single hardware units for pharmaceutical cold-chain operators. |
| Strategic Partnership | Enables component suppliers to access fleet-wide tire pressure and brake wear data for predictive maintenance subscription revenue. |
| Acquisition of Specialist Firm | Absorbs point-solution vendors into unified stacks, accelerating platform consolidation among surviving hardware vendors. |
| Geographic Expansion | Targets underpenetrated flatbed and tanker segments where cargo-secure monitoring lags dry van sensor penetration. |
Study Parameters
Multiple input streams — fleet management executives, telematics hardware procurement leads, cold-chain logistics operators, and insurance underwriting specialists — were reconciled against regulatory filings and trade data. Secondary validation drew from FMCSA enforcement databases, EPA Phase 2 compliance documentation, FCC equipment authorization records, and customs import manifests for cellular modem shipments. Bottom-up triangulation across hardware unit economics and top-down reconciliation against fleet operator IT spending patterns anchored market sizing.
Historical adoption curves were cross-referenced against panel input from platform vendors and sensor manufacturers to project penetration rates across the analysis window. Segmentation dimensions modeled include product type, application intensity, end-user data sovereignty preferences, and technology maturity tier. CAGRs were derived from slope consistency checks against ELD mandate enforcement timelines and cold-chain regulatory expansion patterns. Forecast inputs incorporated shipper audit requirement diffusion rates and insurance risk-scoring algorithm granularity thresholds.
Revisions become necessary when satellite backup module certification timelines accelerate, when fleet operator data sharing preferences shift toward platform aggregation, or when pharmaceutical cold-chain regulations expand beyond current corridor concentrations. Forecasts reflect documented assumptions about regulatory enforcement intensity and hardware cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market