
 United States Commercial Vehicles Market | 2026-2036
United States Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Vehicles Market Analytics
Modular chassis-and-cab configurations is broadening buyer choice across fleet procurement cycles. PACCAR Inc. sustains manufacturing scale advantages through its integrated powertrain and axle operations in the Pacific Northwest. Ford Motor Company leverages its F-Series platform architecture to dominate light-duty commercial segments with extensive dealer network coverage. Daimler Trucks North America anchors premium heavy-duty positioning through its Detroit powertrain vertical integration strategy.
United States commercial vehicles encompass motorized transport equipment engineered for goods movement, passenger carriage, and vocational services, typically featuring gross vehicle weight ratings exceeding 8,500 pounds with ladder-frame construction, diesel or alternative-fuel powertrains, and duty cycles measured in hundreds of thousands of miles. Heavy duty trucks command substantial margin pools due to powertrain complexity and aftermarket parts dependency, while electric fuel type variants represent the fastest-expanding segment as battery energy density improvements and charging infrastructure deployment reduce total cost of ownership barriers. Light duty trucks maintain volume leadership across logistics and delivery services applications where route predictability supports electrification trials.
NHTSA Federal Motor Vehicle Safety Standards govern crashworthiness and braking performance thresholds, while EPA emissions regulations mandate progressive nitrogen oxide and particulate matter reductions that reshape engine architecture investments. The Department of Transportation hours-of-service rules directly influence fleet size requirements and vehicle utilization rates across freight transportation operators. Stakeholders must weigh powertrain transition capital commitments against residual value uncertainty in diesel-dominated secondary markets.
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing diesel powertrain development timelines while battery-electric platforms capture incremental fleet procurement share across last-mile and regional-haul duty cycles.
Growth Catalysts
- E-commerce fulfillment density:Parcel volume concentration in Texas and California metropolitan corridors is expanding Class 3-6 truck replacement cycles for dedicated delivery contractors.
- Charging infrastructure deployment:NEVI program corridor buildouts along Interstate highway systems are reducing range anxiety barriers for electric medium-duty route operations.
- Detroit powertrain integration:In-house engine-transmission-axle manufacturing is shortening lead times for heavy-duty fleet spec configurations.
Market Restraints
- Lithium carbonate price volatility:Battery pack cost uncertainty is compressing electric truck margin projections for vocational body upfitters.
- Great Lakes supplier concentration:Axle and transmission component sourcing clusters in Michigan and Ohio create weather-related production disruption exposure.
- Secondary market diesel dependency:Residual value collapse risk for internal combustion assets is extending fleet depreciation schedules.
Strategic Opportunities
- Appalachian manufacturing corridor:Greenfield battery cell and pack assembly investments in Kentucky and Tennessee are localizing electric powertrain supply chains.
- Vocational upfit digitization:Telematics-integrated chassis-cab configurations are enabling usage-based insurance and predictive maintenance revenue streams.
- IRA commercial clean vehicle credits:Federal tax incentives up to forty thousand dollars per qualified electric truck are accelerating municipal and utility fleet conversions.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain diagnostic and repair certification programs are lagging fleet electrification deployment timelines across dealer networks.
- Multi-platform software integration:Telematics, battery management, and autonomous safety system interoperability is extending vehicle development validation cycles.
- NHTSA FMVSS compliance sequencing:Crashworthiness testing bottlenecks for alternative-fuel configurations are delaying new model year introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Vehicles Market |
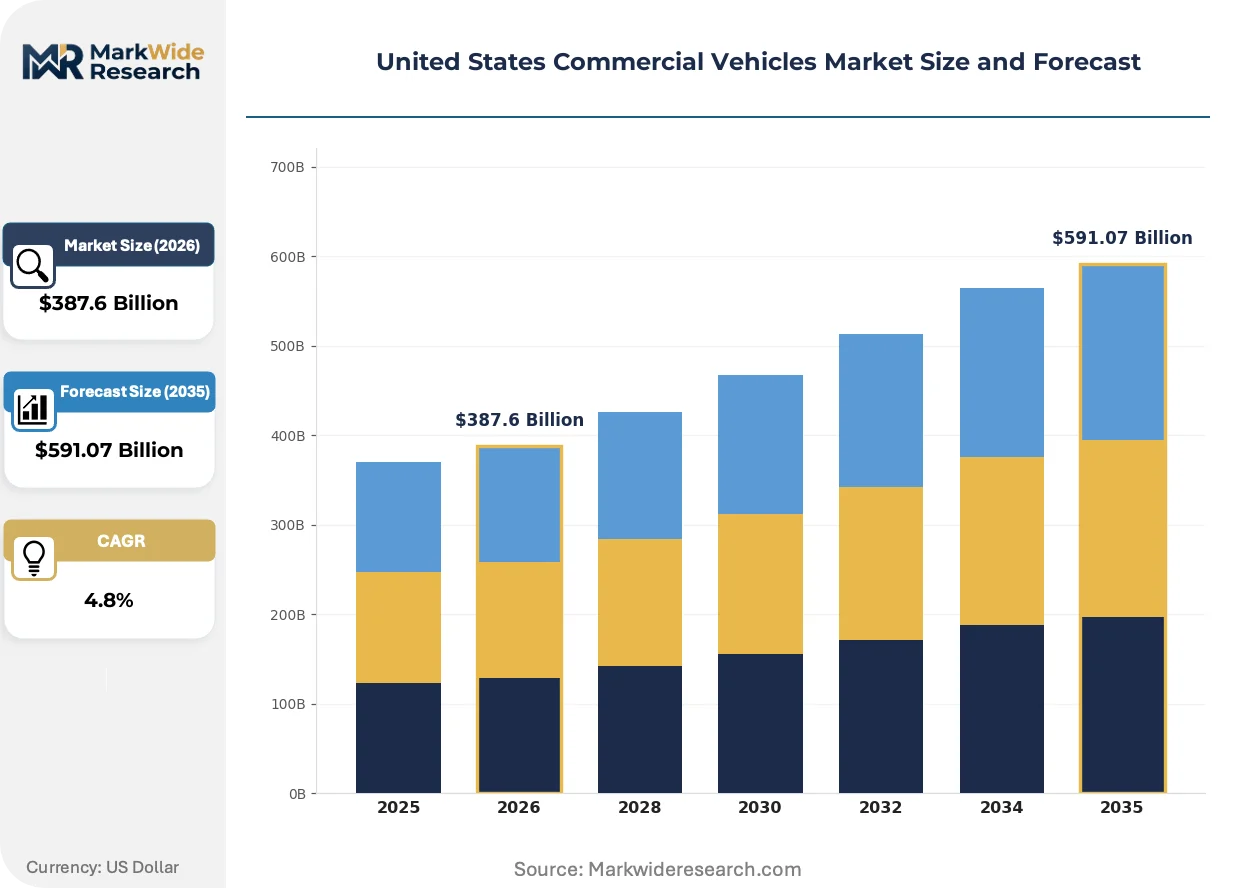
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Buses, Vans Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Logistics, Public Transport, Construction, Delivery Services Application: Freight Transportation, Passenger Transport, Construction Services, Waste Management |
| Companies Covered | Ford Motor Company, General Motors Company, PACCAR Inc., Daimler Trucks North America, Volvo Group, Navistar International Corporation, Toyota Motor Corporation, Hino Motors Ltd., Isuzu Motors Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Vehicles Market Evolving Landscape
Powertrain electrification is restructuring competitive advantage around battery supply security and charging ecosystem control rather than engine displacement hierarchies.
Battery-electric medium-duty platforms is overtaking diesel equivalents in urban delivery applications where route predictability and depot charging infrastructure align. Regional parcel carriers and beverage distributors are standardizing electric chassis specifications for stop-and-go duty cycles. This shift is compressing traditional powertrain supplier relationships and elevating cell chemistry partnerships as core strategic assets.
NHTSA Federal Motor Vehicle Safety Standards updates for automatic emergency braking mandates are forcing sensor fusion architecture investments across all GVWR classes. Heavy-duty truck manufacturers must integrate radar and camera systems previously optional in vocational segments. The Great Lakes manufacturing corridor is absorbing compliance engineering talent to meet phased implementation deadlines.
Fleet procurement centralization through national leasing and mobility service providers is displacing decentralized dealer network purchasing for Class 1-5 vehicles. Large logistics operators are negotiating direct manufacturer agreements with standardized telematics and maintenance bundles. This concentration is most visible in California and Texas where multi-thousand unit fleet operators command volume pricing leverage.
United States Commercial Vehicles Market Segmentation
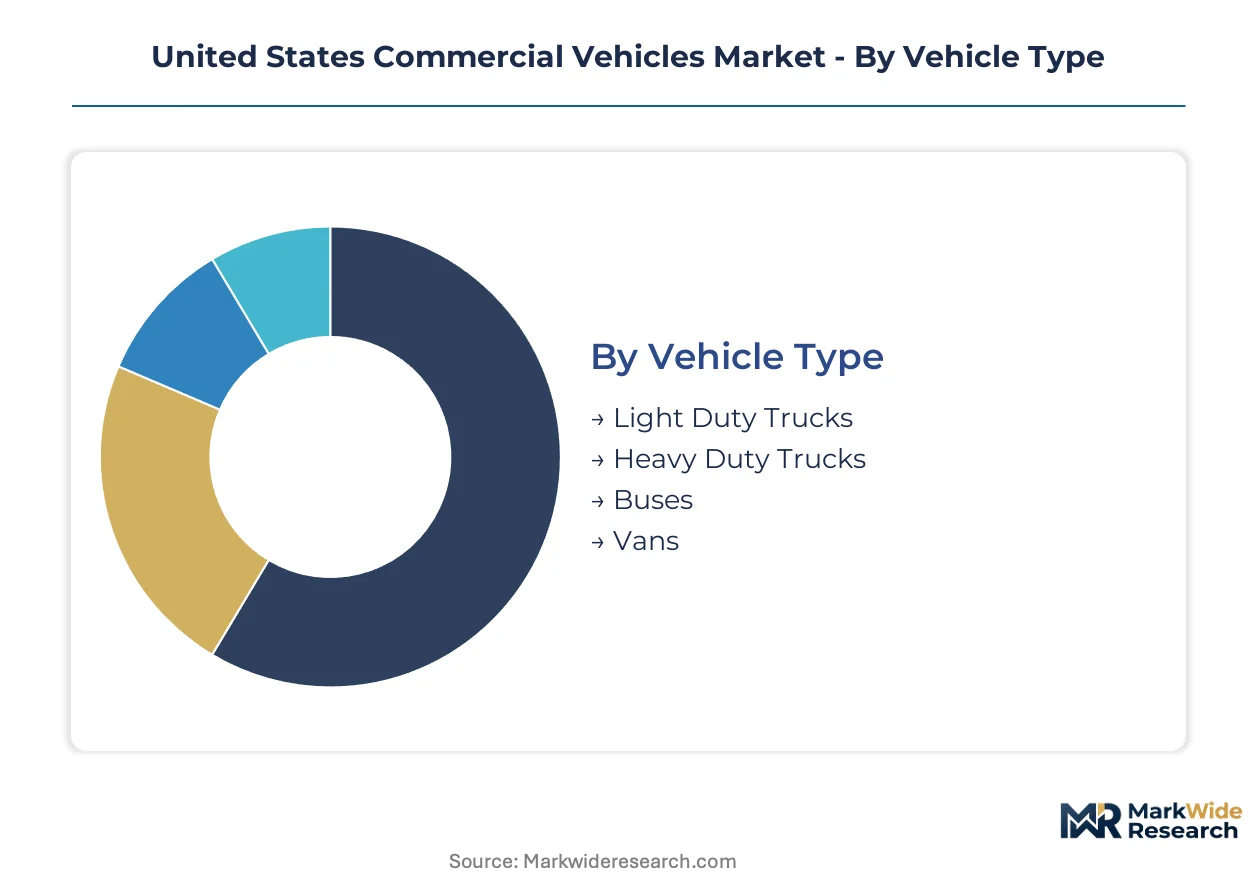
Segmentation reveals how procurement patterns diverge across duty cycles and regulatory exposure. Fleet operators calibrate specifications differently for urban delivery density versus interstate freight corridors. Understanding these splits clarifies where electrification investments concentrate and where diesel assets retain residual value protection.
Vehicle Type:
Replacement cycles vary sharply by GVWR classification, with lighter platforms turning faster and heavy-duty assets depreciating over decade-long horizons.
- Light Duty Trucks:GVWR ratings from 8,500 to 14,000 pounds dominate last-mile logistics and contractor fleets. California and Texas metropolitan corridors are absorbing the highest unit volumes as e-commerce fulfillment networks expand hub-and-spoke distribution.
- Heavy Duty Trucks:Class 7-8 tractors and straight trucks feature ladder-frame construction and integrated powertrain architectures optimized for 500,000-plus mile duty cycles. The Great Lakes manufacturing corridor anchors production, though fleet procurement is compressing lead times through Detroit powertrain vertical integration.
- Buses:Transit and coach configurations serve municipal and intercity passenger carriage with specialized chassis requirements and ADA compliance mandates.
- Vans:Compact and full-size cargo variants fill urban delivery and service technician applications where maneuverability constraints dominate payload optimization.
Light Duty Trucks sits at the top of the volume ranking, with Electric fuel variants climbing the fastest across urban route applications.
Fuel Type:
Cost tier stratification separates established diesel infrastructure from emerging electric platforms requiring capital-intensive charging ecosystem investments.
- Diesel:Compression-ignition powertrains retain dominance in heavy-duty long-haul applications where energy density and refueling speed remain critical. Secondary market liquidity and technician training depth reinforce fleet confidence in residual value stability.
- Electric:Battery-electric platforms are capturing procurement share fastest in Class 3-6 medium-duty segments where depot charging aligns with predictable route structures. NEVI corridor buildouts along Interstate highways are reducing range anxiety barriers for regional operators.
- Gasoline:Spark-ignition engines persist in light-duty vocational applications where acquisition cost sensitivity outweighs fuel economy optimization.
- Hybrid:Dual-powertrain configurations offer transitional positioning for stop-and-go duty cycles where full electrification infrastructure remains incomplete.
Diesel retains the largest installed base, though Electric platforms are expanding most quickly across municipal and utility fleet conversions.
End User:
Customer type concentration shapes specification standardization, with national fleet operators commanding direct manufacturer negotiations that bypass traditional dealer networks.
- Logistics:National parcel carriers and third-party freight operators drive high-volume procurement with standardized telematics and maintenance bundle requirements.
- Delivery Services:Regional contractors and dedicated last-mile operators prioritize Class 3-5 chassis with upfit flexibility for parcel, beverage, and food service body configurations.
- Construction:Vocational buyers demand specialized axle ratings, PTO provisions, and severe-duty suspension packages for equipment transport and material hauling.
- Public Transport:Municipal transit authorities and school districts operate under distinct federal funding cycles and Buy America domestic content requirements.
Logistics commands the highest procurement volumes, with Delivery Services gaining share fastest as e-commerce fulfillment density intensifies.
Application:
Geographic deployment patterns align application demand with infrastructure availability and regulatory stringency across state boundaries.
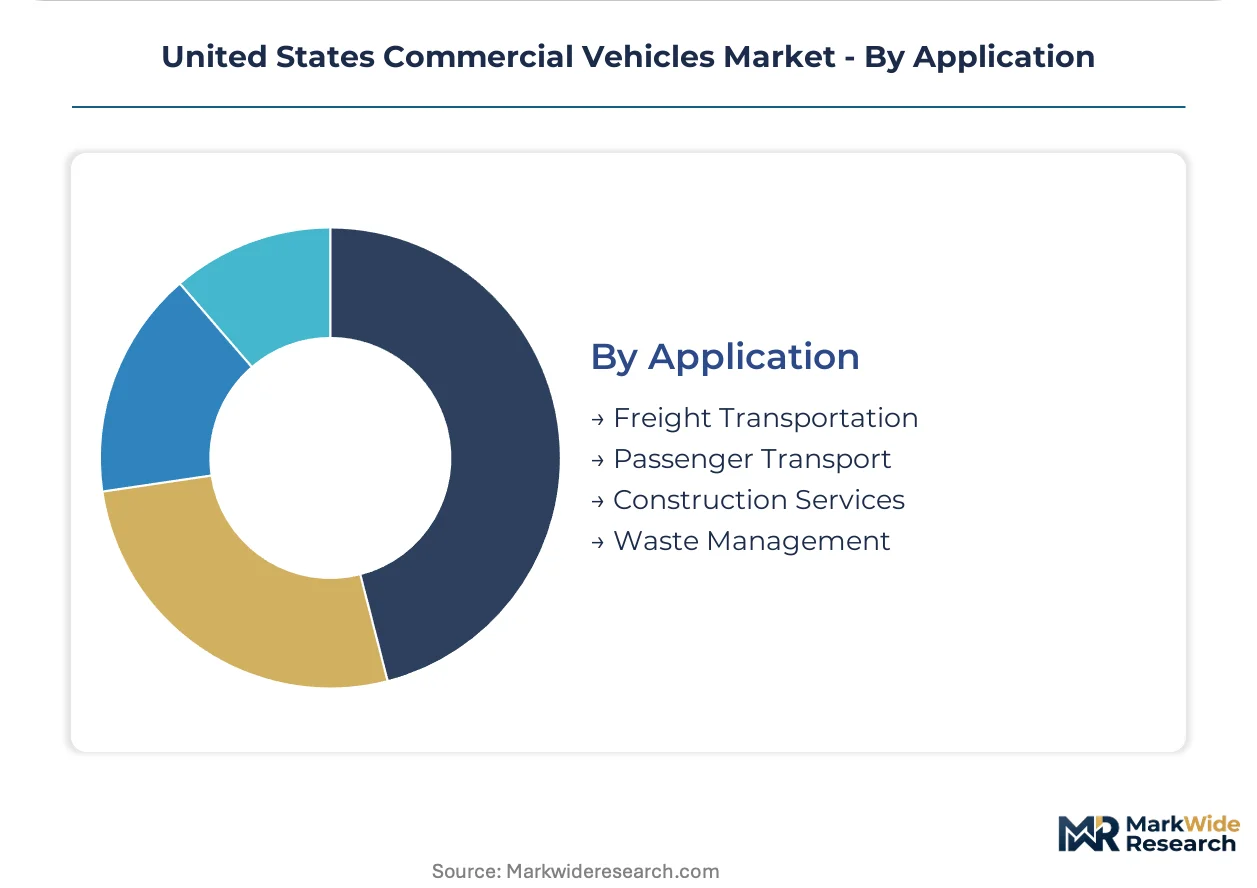
- Freight Transportation:Interstate and regional trucking operations concentrate in the Texas-California corridor where logistics density supports dedicated fleet facilities and maintenance networks.
- Passenger Transport:Transit, shuttle, and intercity coach services cluster in metropolitan areas with EPA non-attainment designations that accelerate zero-emission procurement mandates.
- Construction Services:Equipment hauling and material delivery applications favor vocational chassis with high-torque powertrains and reinforced frame rails for off-road durability.
- Waste Management:Refuse collection and recycling operations require specialized cab-over-engine configurations with automated side-loader body integration and frequent stop-start duty cycles.
Freight Transportation leads application-level procurement, with Passenger Transport expanding most quickly under municipal fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commercial vehicle industry traces its mass-production origins to Detroit's early twentieth-century assembly innovations, with subsequent geographic expansion following interstate highway construction and logistics corridor development across the continental states.
Texas
Energy sector equipment hauling and cross-border freight to Mexico drive heavy-duty chassis demand across the Permian Basin and Rio Grande Valley. NHTSA Federal Motor Vehicle Safety Standards enforcement maintains rigorous braking and crashworthiness thresholds for vehicles operating along Interstate 35. Dallas-Fort Worth anchors fleet maintenance networks serving national logistics operators with concentrated dealer and service infrastructure.
California
EPA non-attainment designations and state-level Advanced Clean Trucks regulations are accelerating municipal and delivery fleet electrification mandates in Los Angeles and San Francisco metropolitan areas. CARB zero-emission vehicle requirements phase in through 2036 with escalating sales quotas for manufacturers. The Central Valley agricultural corridor sustains demand for medium-duty vocational chassis with specialized upfit configurations for produce distribution.
Great Lakes Manufacturing Corridor
Heavy-duty powertrain and axle component sourcing clusters in Michigan and Ohio supply Detroit-based final assembly operations with integrated engine-transmission-axle configurations. EPA Phase 3 greenhouse gas standards are compressing diesel development timelines while battery-electric platform engineering talent concentrates in Ann Arbor and Detroit tech corridors. Winter weather exposure creates seasonal production disruption risks for just-in-time supplier networks.
Southeast
Appalachian manufacturing investments in Kentucky and Tennessee are localizing battery cell and pack assembly for electric medium-duty platforms serving regional distribution networks. IRA commercial clean vehicle credits up to forty thousand dollars per qualified electric truck are accelerating municipal fleet conversions in Atlanta and Charlotte metropolitan areas. Greenville-Spartanburg anchors vocational body upfitter operations for construction and utility service applications.
Pacific Northwest
Integrated powertrain and axle manufacturing operations in Washington and Oregon sustain premium heavy-duty positioning through captive supply chain control. Port of Seattle and Port of Tacoma logistics density supports dedicated fleet facilities serving Asia-Pacific import-export corridors. NEVI program corridor buildouts along Interstate 5 are reducing range anxiety barriers for electric regional-haul operations connecting California distribution hubs.
United States Commercial Vehicles Market Competitive Landscape
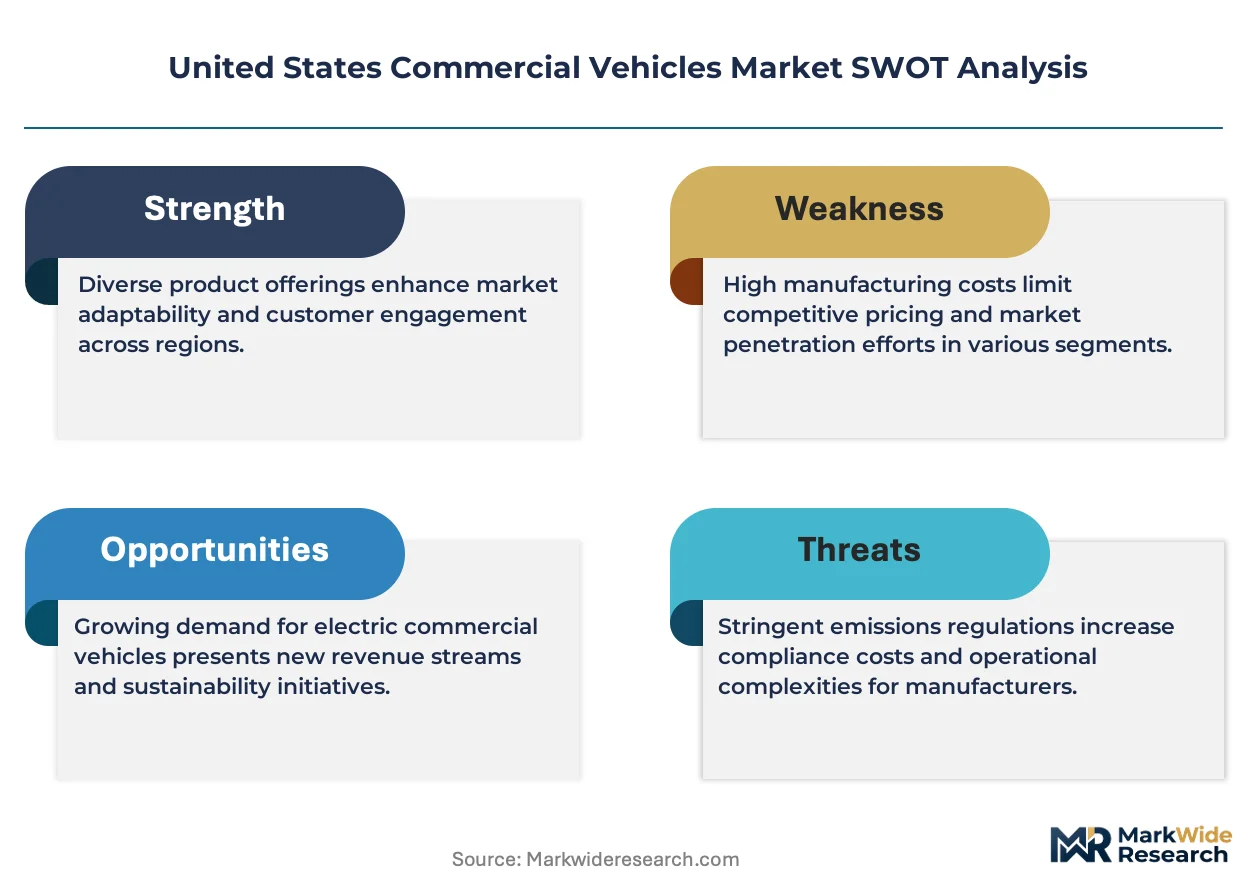
Premium-margin players sit above commodity-margin players across powertrain integration depth and aftermarket parts dependency. The market structure consolidates around manufacturers with captive engine-transmission-axle production versus assemblers relying on external component sourcing. Three archetypes dominate: vertically integrated heavy-duty specialists, platform-leveraging light-duty volume producers, and vocational upfitter partners. Competitive moves concentrate on charging ecosystem partnerships and telematics-integrated service bundling.
Within the integrated powertrain tier, PACCAR Inc. and Daimler Trucks North America exemplify manufacturers with in-house production of critical drivetrain components. Ford Motor Company occupies a distinct position leveraging light-duty platform architecture across extensive dealer network coverage. These three entities anchor the competitive structure through differentiated approaches to electrification investment and fleet customer relationship depth.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| PACCAR Inc. |
| Daimler Trucks North America |
| Volvo Group |
| Navistar International Corporation |
| Toyota Motor Corporation |
| Hino Motors Ltd. |
| Isuzu Motors Limited |
| Others |
Value Network & Pricing Analysis
Battery-electric platform engineering simultaneously compresses powertrain cost curves and concentrates supply chain control around cell chemistry partnerships and charging ecosystem investments. EPA Phase 3 greenhouse gas standards accelerate this dual restructuring by collapsing diesel development timelines while elevating captive battery supply as a pricing determinant.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Detroit powertrain-integrated heavy-duty configurations from modular light-duty platforms and basic vocational chassis. Price differentiation hinges on powertrain integration depth and telematics bundling sophistication. Cost compression in electric medium-duty segments is intensifying because lithium carbonate volatility compresses margin projections. Municipal fleet operators exhibit highest price sensitivity due to budget cycle constraints, while national logistics operators prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Buy America domestic content requirements under IRA commercial clean vehicle provisions are reshaping sourcing patterns toward Appalachian battery cell assembly and Great Lakes axle component clusters. Heavy-duty powertrain production draws from Michigan, Ohio, and Indiana supplier networks. Raw material dependencies span lithium carbonate, rare earth magnet feedstocks, and high-strength steel alloys. Single-source vulnerability concentrates in semiconductor power modules for electric drivetrains. Distribution runs through captive dealer networks for heavy-duty segments and direct manufacturer agreements for centralized fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States commercial vehicles market functions as a regulatory compounder where EPA Phase 3 standards and IRA clean vehicle credits create synchronized demand acceleration for electric platforms.
For Market Incumbents: Lock in battery supply security through long-term cell chemistry partnerships before Appalachian manufacturing capacity saturates. Prioritize telematics-integrated service bundling to defend against fleet procurement centralization threatening traditional dealer network economics. Vertical integration into charging infrastructure control offers defensive positioning against ecosystem competitors. For New Entrants and Emerging Players: Regional beverage distributors and specialized construction contractors represent underserved buyer archetypes bypassed by national fleet direct agreements. Target vocational upfit digitization gaps where predictive maintenance software lacks chassis-agnostic integration. Pursue white-label electric chassis partnerships with established body builders as the primary go-to-market pathway. For Investors and Strategic Acquirers: Roll-up economics work for vocational telematics specialists because fleet procurement centralization demands standardized data platforms across fragmented body-upfitter networks. Five-to-ten year viability centers on software-defined vehicle capability depth rather than manufacturing scale. Acquisition targets should demonstrate EPA certification pipeline readiness and NEVI corridor charging partnerships. Monitor NHTSA automatic emergency braking mandate compliance sequencing as the critical inflection signal for platform technology maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell chemistry partnerships with Appalachian manufacturers secure IRA credit eligibility and cost stability. |
| Charging Infrastructure Partnership | NEVI corridor buildout participation reduces range anxiety barriers for regional-haul electric fleet operators. |
| Telematics Platform Integration | Usage-based insurance and predictive maintenance bundling captures recurring revenue from centralized fleet procurement. |
| Powertrain Platform Standardization | Modular chassis-cab configurations accelerate fleet replacement cycles across Class 3-6 delivery applications. |
| Vocational Body Upfit Digitization | Software-agnostic telematics integration addresses unmet demand from specialized construction and utility service fleets. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and NEVI program administrators grounded qualitative findings in operational reality. Secondary validation incorporated EPA regulatory filings, NHTSA safety standard updates, DOE charging infrastructure deployment data, and state-level CARB implementation schedules. Bottom-up vehicle production estimates and top-down freight demand modeling enabled cross-verification across the analysis window.
Segment-level projections across vehicle class, propulsion architecture, GVWR tier, and regional regulatory cluster fed into compound annual growth derivation through logistic diffusion curves for electric platform adoption. CAGRs reflect powertrain transition capital commitment timelines and residual value uncertainty in diesel-dominated secondary markets. Forecast inputs incorporated lithium carbonate price trajectory assumptions and NEVI corridor completion schedules.
Underlying measurement precision varies by segment; electric platform forecasts carry tighter precision than diesel residual value projections given policy visibility. Forecasts reflect documented assumptions regarding EPA enforcement continuity and IRA credit extension. Supply disruption scenarios and battery chemistry substitution risks could materially revise trajectory conclusions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Philippines Commercial Vehicles Market