
 US Paper Cups and Paper Plates Market | 2026-2036
US Paper Cups and Paper Plates Market Size, Share, and Industry Trends Forecast 2026-2036
US Paper Cups and Paper Plates Market Intelligence
Quick-service restaurants and institutional catering operators are redrawing procurement patterns across disposable foodservice packaging. Solo Cup Company leverages its broad retail distribution network to sustain shelf presence in club and grocery channels. Graphic Packaging International anchors large-format foodservice accounts with integrated paperboard converting capacity. Dart Container Corporation dominates cold-cup manufacturing through extensive thermoforming and printing operations.
US paper cups and paper plates comprise formed fiber structures engineered from bleached or unbleached kraft pulp, often laminated with polyethylene or bio-based coatings to resist liquid penetration and grease migration, serving primarily as single-use vessels for prepared food and beverage service. Hot cups lead product-type value pools due to specialty barrier requirements and premium pricing, while biodegradable paper materials are expanding fastest as foodservice chains execute zero-waste commitments. The medium size bracket occupies the highest volume position across both cups and plates, reflecting standard portion norms in fast-casual dining.
The FDA governs food contact notifications for coatings and additives, while the EPA oversees pulp mill effluent standards and landfill methane regulations affecting end-of-life pathways; state-level extended producer responsibility frameworks in California, Oregon, and Washington are reshaping design-for-recyclability mandates. The USDA BioPreferred program and ASTM D6400 certification requirements influence material selection and supplier qualification protocols. Stakeholders must monitor how municipal composting infrastructure buildout and fiber sourcing traceability standards will determine which material platforms achieve scalable circularity.
Market Dynamics
State-level plastic bans and municipal composting mandates are compressing demand for conventional polyethylene-lined serveware while redirecting procurement toward fiber-based alternatives across quick-service and institutional channels.
Growth Catalysts
- Extended Producer Responsibility frameworks:California, Oregon, and Washington EPR laws mandate design-for-recyclability standards that favor molded fiber and bio-based coatings over conventional plastics in foodservice packaging procurement.
- Quick-service chain zero-waste commitments:Major fast-casual operators are specifying ASTM D6400-certified compostable serveware in system-wide supply agreements, creating pull-through demand for barrier-coated paper cups and molded fiber plates.
- Southeast manufacturing corridor concentration:Integrated pulp-to-converting facilities clustered near Georgia, Alabama, and Tennessee paper mills shorten logistics loops and reduce working capital requirements for regional foodservice distributors.
Market Restraints
- Bleached kraft pulp price volatility:Input cost swings for northern softwood pulp constrain margin stability for converters lacking long-term fiber supply agreements or captive pulp sourcing.
- Polyethylene coating regulatory friction:FDA food contact notification requirements for alternative barrier chemistries extend qualification timelines and raise R&D overhead for coating innovators.
- Municipal composting infrastructure gaps:Limited industrial composting facility availability in the Midwest and Mountain West regions undermines end-of-life value propositions for certified compostable serveware.
Strategic Opportunities
- USDA BioPreferred program leverage:Federal procurement preference for biobased products opens institutional catering and government foodservice contracts to certified fiber-based alternatives.
- Direct-to-chain e-commerce platforms:Digital procurement portals are compressing distributor layers and enabling smaller converters to access quick-service account procurement teams.
- Hot-cup barrier technology convergence:Integration of bio-based polymers with fiber forming is creating premium-positioned serveware for specialty coffee chains seeking differentiated sustainability credentials.
Industry Challenges
- Composting certification timeline compression:ASTM D6400 and BPI certification cycles create inventory risk for converters launching new coating formulations ahead of validated facility acceptance.
- Thermoforming-to-fiber process retooling:Legacy polystyrene and PET equipment conversion requires capital deployment for heated platen presses and fiber slurry handling systems.
- Barrier performance standardization delays:Absence of unified hot-fill and grease-resistance test protocols complicates buyer specification and supplier qualification across multi-chain operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Paper Cups and Paper Plates Market |
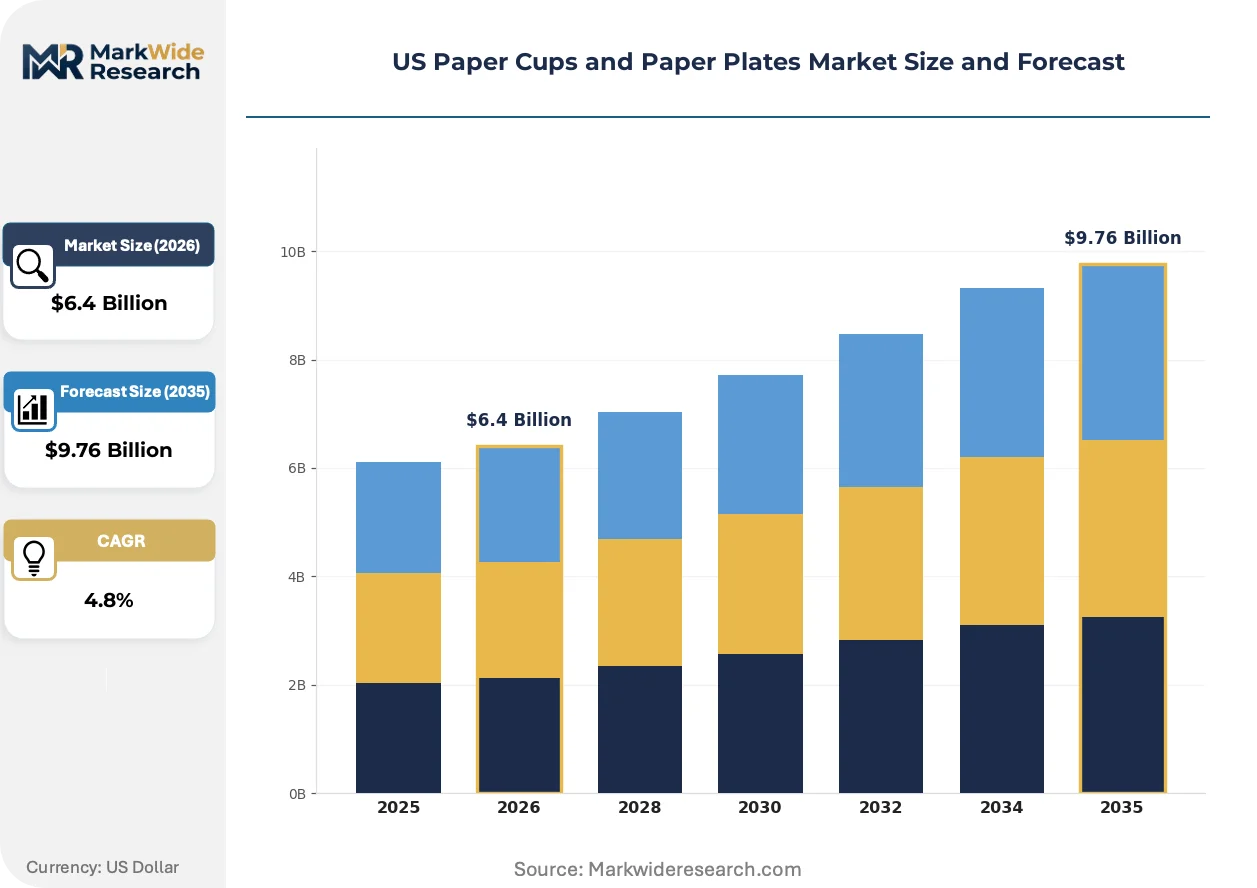
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Composite Plates, Plain Plates Material: Recycled Paper, Virgin Paper, Coated Paper, Biodegradable Paper End User: Foodservice, Retail, Events, Household Size: Small, Medium, Large, Extra Large |
| Companies Covered | Solo Cup Company, Graphic Packaging International, Dart Container Corporation, Novolex, Genpak, International Paper, Huhtamaki North America, WinCup, Georgia-Pacific (Dixie), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Paper Cups and Paper Plates Market Strategic Shifts & Innovations
Barrier coating chemistry and forming process control are the primary vectors of product differentiation, with sustainability-linked procurement specifications now filtering material selection before cost considerations in chain-account negotiations.
Polylactic acid and polyhydroxyalkanoate bio-based coatings are displacing conventional polyethylene linings in hot-cup applications. Specialty coffee chains and fast-casual soup operators are specifying these chemistries in multi-year supply agreements. The shift is compressing demand for legacy extrusion-coated cupstock while rewarding converters with in-house bio-polymer lamination capability.
California's SB 54 and Oregon's Plastic Pollution and Recycling Modernization Act mandate recycled content minimums and extended producer responsibility fees that scale with non-recyclable packaging volumes. These frameworks are accelerating converter investment in repulpable barrier structures. Foodservice packaging procurement teams in the Pacific Northwest and California are now requiring third-party recyclability certifications before contract award.
Chain-level consolidated procurement is consolidating supplier relationships around fewer, larger converting partners capable of national distribution and inventory management. Regional distributors are losing share to direct manufacturer-to-chain arrangements supported by vendor-managed inventory systems. This pattern is most pronounced in the quick-service burger and coffee segments, where procurement centralization has compressed the approved supplier base by half over the past three contract cycles.
US Paper Cups and Paper Plates Market Segmentation
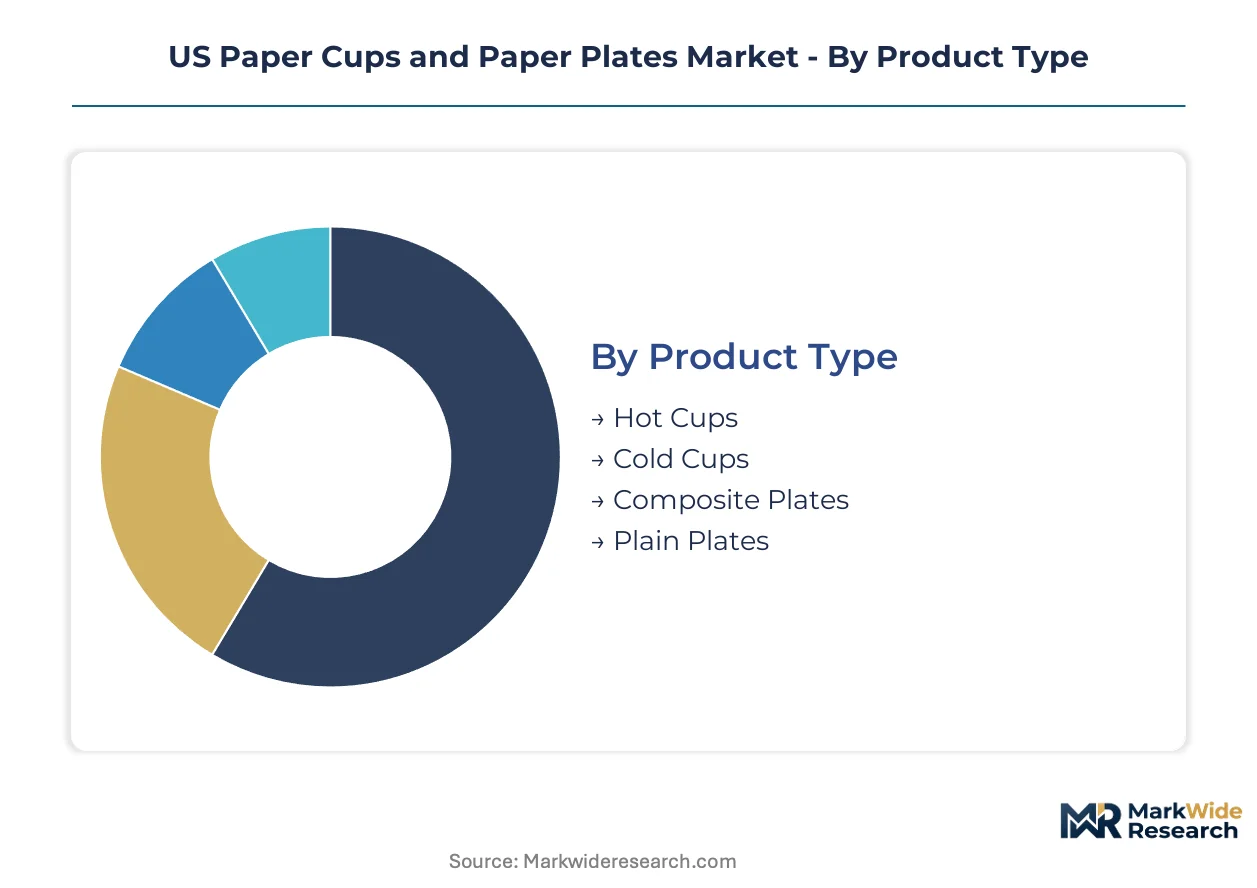
Segmentation in the US paper cups and paper plates market reveals how procurement specifications, barrier technology requirements, and end-use consumption patterns create distinct margin pools. Understanding these divides helps converters align capacity investments with the highest-value demand channels.
Product Type:
Margin concentration skews heavily toward hot-fill applications where barrier complexity and specialty coatings command premium pricing over commodity cold-serve formats.
- Hot Cups:Double-walled or single-wall structures with polyethylene or bio-based barrier coatings engineered for 180-200°F liquid contact. Quick-service coffee chains and specialty café operators in the Pacific Northwest and California drive specification intensity through zero-waste procurement mandates.
- Cold Cups:Single-wall formed fiber with thinner barrier requirements for ambient or refrigerated beverages. High-volume fast-food fountain drink programs in the Southeast manufacturing corridor absorb capacity from integrated converting facilities near Atlanta and Birmingham.
- Composite Plates:Multi-layer structures combining molded fiber bases with laminated barriers for cut resistance and grease containment.
- Plain Plates:Unbleached or bleached kraft fiber formed into single-use dinnerware without supplemental coatings.
Hot Cups holds installed capacity. Cold Cups is rotating up the share rankings.
Material:
Cost tier stratification separates virgin fiber stability from recycled and bio-based alternatives facing supply intermittency and certification overhead.
- Recycled Paper:Post-consumer fiber content meeting EPA procurement guidelines and state-level recycled-content mandates. California SB 54 compliance requirements are pulling institutional foodservice contracts toward minimum 50% post-consumer fiber specifications.
- Virgin Paper:Northern softwood kraft pulp delivering consistent fiber length and formation quality for high-speed converting lines. Integrated mills in Georgia and Tennessee maintain captive supply agreements with regional converters serving quick-service national accounts.
- Coated Paper:Polyethylene or bio-polymer laminated substrates providing liquid resistance.
- Biodegradable Paper:ASTM D6400-certified substrates with PLA or PHA barrier layers qualifying for industrial composting streams.
Virgin Paper holds installed capacity. Biodegradable Paper is rotating up the share rankings.
End User:
Volume concentration clusters in foodservice channels where centralized procurement and multi-year supply agreements create contract manufacturing stability.
- Foodservice:Quick-service restaurants, fast-casual chains, and institutional catering operations specifying barrier performance and sustainability certification in RFP criteria. USDA BioPreferred program eligibility opens federal cafeteria and military foodservice contracts to qualified fiber-based suppliers.
- Retail:Club stores, grocery chains, and mass merchandisers stocking private-label and branded disposable dinnerware. Southeast distribution hubs serving Walmart, Target, and Costco regional DCs prioritize suppliers with vendor-managed inventory capability.
- Events:Temporary catering and stadium concessions requiring single-use serveware.
- Household:Consumer pantry stocking of disposable plates and cups for informal entertaining.
Foodservice holds installed capacity. Retail is rotating up the share rankings.
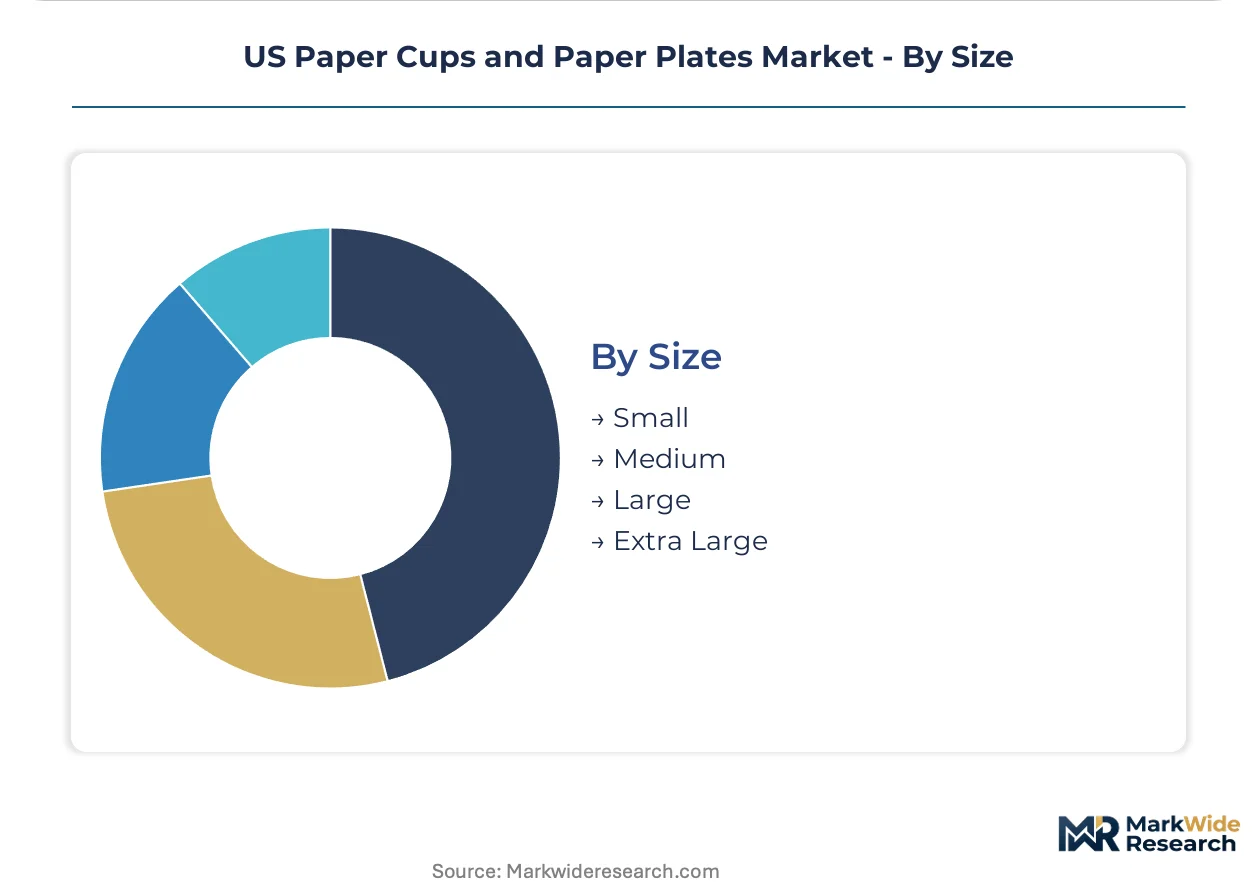
Size:
Application norms and portion standardization in fast-casual dining concentrate procurement around mid-range formats.
- Small:Espresso cups, condiment vessels, and children's portion containers. Specialty coffee chains in Portland and Seattle specify 4-8 oz formats with compostable certification for single-origin espresso service.
- Medium:12-16 oz cups and 9-inch plates matching standard quick-service portion profiles. National burger and sandwich chains specify this bracket in system-wide supply agreements, creating the highest volume demand pool across both cups and plates.
- Large:20-24 oz cups and 10-inch plates for combo meals and family portions.
- Extra Large:32 oz cups and compartmentalized platters for catering and group service.
Medium holds installed capacity. Large is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Georgia and Tennessee anchor North American export flows of formed fiber serveware to Canadian quick-service chains and Mexican foodservice distributors. The Southeast manufacturing corridor shortens transit times to Atlantic and Gulf ports. Regional demand patterns track state-level plastic ban implementation timelines.
Southeast Manufacturing Corridor
Integrated pulp-to-converting facilities cluster near Atlanta and Birmingham to serve quick-service national accounts. Alabama and Georgia state tax incentives for capital equipment deployment support thermoforming-to-fiber retooling investments. Savannah and Charleston ports handle containerized exports to Caribbean and Latin American foodservice markets.
Pacific Northwest
Seattle and Portland specialty coffee chains drive ASTM D6400-certified compostable cup procurement at premium price points. Oregon's Plastic Pollution and Recycling Modernization Act mandates extended producer responsibility fees scaling with non-recyclable packaging volumes. Tacoma and Vancouver BC municipal composting facilities accept industrial-certified fiber serveware, validating end-of-life value propositions.
California
SB 54 recycled-content minimums pull institutional foodservice contracts toward 50% post-consumer fiber specifications. Los Angeles and San Francisco quick-service procurement teams require third-party recyclability certifications before contract award. Central Valley distribution hubs prioritize suppliers with vendor-managed inventory capability for club store replenishment.
Midwest
Chicago and Detroit institutional catering operators absorb high-volume cold-cup capacity from regional converters. Limited industrial composting facility availability in Illinois and Ohio undermines certified compostable serveware adoption. Minneapolis-St. Paul distributors maintain safety stock positions to buffer against northern softwood pulp price volatility.
Northeast Corridor
New York Metro and Boston fast-casual chains specify double-walled hot cups for specialty coffee and soup service. Connecticut and New Jersey extended producer responsibility frameworks accelerate design-for-recyclability mandates. Philadelphia and Baltimore ports receive European bio-polymer imports for barrier coating lamination lines.
US Paper Cups and Paper Plates Market Key Industry Players
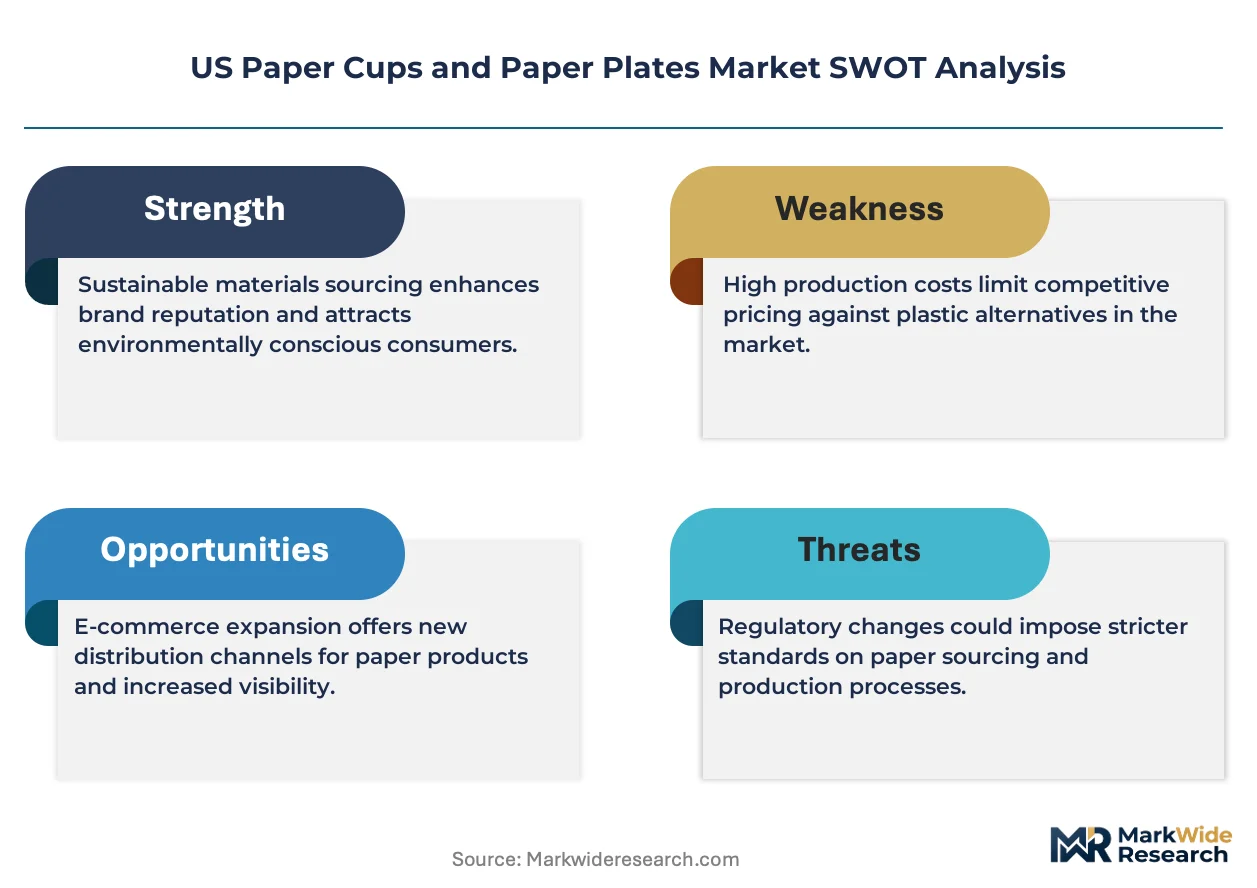
Player mix skews toward integrated paperboard converters with captive pulp supply agreements and national distribution networks. Market structure concentrates around three to four large-scale operators capable of vendor-managed inventory systems for quick-service chain accounts. Strategic archetypes include integrated mill-to-converting conglomerates, specialty barrier technology developers, and regional distributors pivoting toward direct-to-chain digital platforms. Dominant competitive moves encompass backward integration into northern softwood pulp sourcing and strategic partnerships with bio-polymer coating innovators.
Among integrated packaging conglomerates, International Paper and Georgia-Pacific anchor the scale-driven tier with mill assets in the Southeast manufacturing corridor. Solo Cup Company and Dart Container Corporation occupy positions within the foodservice-specialist archetype, with Dart Container representing thermoformed cold-cup manufacturing expertise. Graphic Packaging International and Huhtamaki North America exemplify the barrier-technology-forward segment, with Huhtamaki North America reflecting Finnish parent-company bio-coating capabilities. Novolex, Genpak, and WinCup sit within the mid-tier converter category serving regional distributor channels.
| Leading Market Players |
|---|
| Solo Cup Company |
| Graphic Packaging International |
| Dart Container Corporation |
| Novolex |
| Genpak |
| International Paper |
| Huhtamaki North America |
| WinCup |
| Georgia-Pacific (Dixie) |
| Others |
Cost & Logistics Intelligence
ASTM D6400 certification gates both supplier qualification and price tiering simultaneously, separating compostable-certified serveware from conventional polyethylene-lined alternatives while California SB 54 and Oregon EPR frameworks impose cost premiums on non-recyclable formats. Buyers face dual qualification hurdles—barrier performance validation plus end-of-life certification—that compress margin pools for uncertified converters.
Pricing Analysis
Barrier-technology pricing gaps separate bio-polymer coated next-generation cups from legacy polyethylene-lined formats and uncoated fiber prior-generation plates. Three-tier pricing structure across premium compostable-certified, standard recyclable, and economy virgin-fiber levels tracks certification grade and volume scale. Cost compression in the standard tier intensifies because integrated Southeast mills leverage captive pulp sourcing. Quick-service national accounts exhibit lowest price sensitivity due to procurement centralization, while regional distributors face acute margin pressure.
Supply Chain Analysis
Georgia, Alabama, and Tennessee anchor formed fiber converting capacity through integrated pulp-to-converting facilities clustered near Atlanta and Birmingham. Raw material dependencies draw from northern softwood kraft pulp, bio-polymer barrier coatings, and post-consumer recycled fiber feedstocks. Supply chain risk centers on single-source vulnerability for PLA and PHA coating chemistries imported through Charleston and Savannah ports. Distribution runs through vendor-managed inventory systems serving quick-service chain DCs directly, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where FDA food contact notification requirements and state-level EPR frameworks create multi-year qualification barriers that protect incumbent positions.
For Market Incumbents: Fortify barrier technology leadership through in-house bio-polymer lamination capability and captive pulp supply agreements with Georgia and Tennessee integrated mills. Emerging specialty coating developers threaten premium positioning; defend through accelerated ASTM D6400 certification pipelines and exclusive quick-service chain supply agreements. For New Entrants and Emerging Players: Differentiate on compostable certification speed-to-market targeting Pacific Northwest specialty coffee chains where Oregon EPR fees and Seattle municipal composting infrastructure validate premium pricing. The most penetrable white space sits in direct-to-chain digital procurement platforms compressing distributor margins. Pursue USDA BioPreferred qualification to access federal institutional catering contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based coating lamination lines and thermoforming-to-fiber retooling investments. Long-term viability over the next decade favors integrated converters with backward fiber control and national distribution networks. Acquisition target archetype: mid-tier regional converters with established quick-service relationships but lacking certification capabilities. Watch composting infrastructure buildout in Midwest and Mountain West regions as inflection indicator for certified compostable serveware scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Northern Softwood Pulp | Captive fiber supply from Georgia and Tennessee mills insulates margin stability against price volatility. |
| Bio-Polymer Coating Technology Partnership | PLA and PHA lamination capability unlocks premium positioning with Pacific Northwest coffee chains. |
| ASTM D6400 Certification Acceleration | Third-party compostable validation enables contract access under California SB 54 and Oregon EPR mandates. |
| Direct-to-Chain Digital Platform Launch | Vendor-managed inventory systems bypass distributor layers and capture quick-service procurement centralization. |
| Southeast Manufacturing Corridor Expansion | Atlanta and Birmingham proximity shortens logistics loops for regional foodservice distribution. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews encompassed quick-service procurement directors, foodservice packaging converters, pulp mill operations managers, and municipal composting facility operators. Secondary sources integrated FDA food contact substance notifications, EPA pulp mill effluent records, state-level EPR framework texts, and USDA BioPreferred program databases. Bottom-up capacity and demand modeling triangulated against top-down market sizing.
Across the projection horizon, the analytical framework modeled segmentation across product type, material platform, end-user channel, and geographic demand cluster. CAGRs derived from historical shipment data, capacity expansion announcements, and procurement contract renewal patterns. Forecast inputs incorporated barrier technology substitution curves and municipal composting infrastructure development timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EPR framework implementation and bio-polymer coating cost curves; material deviation in regulatory enforcement or feedstock pricing would warrant model refresh. Recalibration cycles align with material shifts in state-level plastic ban adoption and industrial composting facility commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
China Paper Packaging Market