
 Fluting Paper Market | 2026-2036
Fluting Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Fluting Paper Market Foresight
Indonesia is rewriting regional supply dynamics through major mill expansions targeting containerboard integration. Smurfit Kappa leverages its European recycling network to secure fiber access across multiple jurisdictions. Mondi Group anchors its competitive position through kraftliner-fluting co-production at integrated Central European sites. DS Smith specializes in lightweight fluting formulations that reduce logistics costs for e-commerce clients.
Fluting paper constitutes the corrugated inner layer between linerboards, typically manufactured from recycled or virgin Kraft pulp at basis weights ranging from 80 to 200 grams per square meter to achieve defined crush resistance and cushioning performance. Recycled Kraft commands volume leadership across European and North American markets where post-consumer collection infrastructure matures, while Virgin Kraft retains premium positioning in moisture-resistant and food-contact applications requiring higher plybond strength. Semi-chemical fluting occupies a narrowing but defended niche in heavy-duty industrial packaging where ring crush values must exceed standard recycled grades.
EPA emissions guidelines and FSC chain-of-custody certification shape North American mill investment cycles, while REACH chemical compliance and EU Packaging Waste Directive recycling targets govern European product specifications. China's GB standards on imported recovered paper purity and Indonesia's Ministry of Environment forestry audits are tightening feedstock access across Asia-Pacific production bases. Stakeholders must track evolving extended producer responsibility schemes and fiber certification thresholds as these frameworks increasingly determine market access rather than mere product differentiation.
Market Dynamics
China's GB standards on imported recovered paper purity are forcing regional mills to rebuild fiber sourcing networks around domestic collection systems and alternative pulp grades.
Growth Catalysts
- E-commerce fulfillment density:Asia-Pacific logistics hubs are consuming corrugated packaging at accelerating rates as last-mile delivery networks expand warehouse footprints and box turnover velocity.
- REACH chemical compliance:European circular packaging mandates are redirecting brand procurement toward FSC-certified recycled Kraft grades with verified chain-of-custody documentation.
- Lightweighting formulations:Advanced fluting chemistries are reducing basis weights while maintaining ring crush performance, cutting per-unit fiber consumption and shipping cube.
Market Restraints
- Old corrugated container price volatility:OCC spot markets swing 30-40% annually, compressing mill margins and destabilizing long-term supply contracts with packaging converters.
- Indonesian fiber concentration:APP and APRIL control 60% of regional hardwood pulp supply, creating bottleneck risk for containerboard producers dependent on mixed furnish strategies.
- Semi-chemical fluting obsolescence:High-energy NSSC pulping cannot match recycled Kraft cost structures, relegating the grade to shrinking heavy-duty industrial niches.
Strategic Opportunities
- India's organized retail expansion:Modern trade and quick-commerce platforms are adopting corrugated standards that favor consistent fluting specifications over traditional jute alternatives.
- EU Packaging Waste Directive recycling targets:Mandatory 70% paper recovery rates by 2030 are incentivizing closed-loop collection partnerships between mills and supermarket chains.
- Digital print compatibility:High-performance fluting grades that withstand direct-to-corrugate inkjet printing are capturing premium positioning in customized unboxing experiences.
Industry Challenges
- Paper machine conversion timelines:Shifting from newsprint or coated grades to containerboard requires 18-24 month rebuilds with uncertain fiber blend optimization.
- Extended producer responsibility registration:Multi-jurisdiction compliance schemes demand dedicated regulatory staff and traceability software investments that burden mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluting Paper Market |
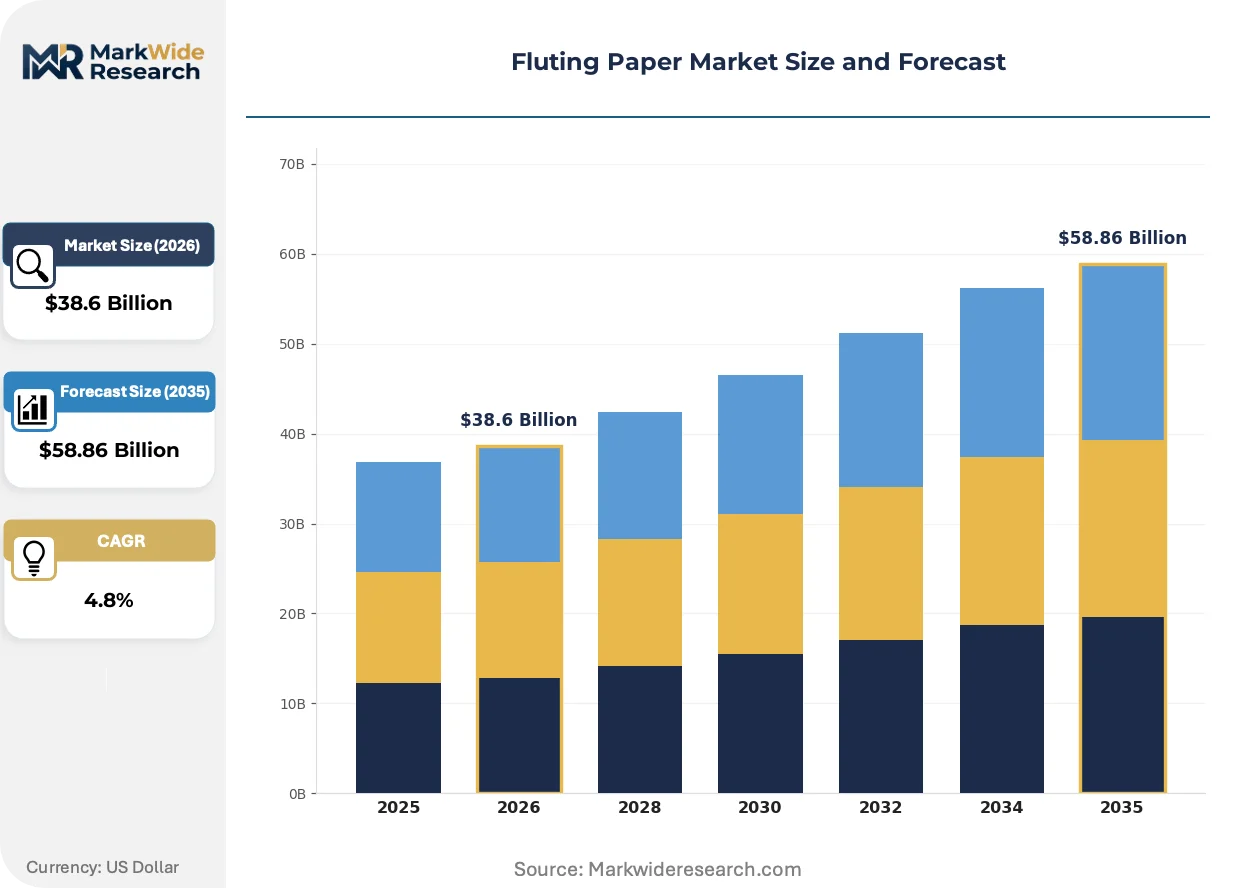
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin Kraft, Recycled Kraft, Semi-Chemical, Testliner, Coated Paper Application: Corrugated Packaging, Folding Cartons, Cushioning Material, Protective Wraps, Industrial Packaging End User Industry: Consumer Goods, Electronics Manufacturing, Food & Beverage, Pharmaceutical Logistics, E-commerce Fulfillment Distribution Channel: Direct Sales, Wholesalers, Distributors, Online Marketplaces, Retail Suppliers |
| Companies Covered | Smurfit Kappa, Mondi Group, DS Smith, International Paper, Stora Enso, WestRock, Nine Dragons Paper, Sappi, Rengo Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluting Paper Market Shifts & Advancements
Sensor-enabled process control and fiber characterization tools are compressing quality variation in recycled furnish streams. These advances are reshaping how mills balance cost, performance, and compliance across divergent regional standards.
Near-infrared spectroscopy paired with automated contaminant removal is digitizing raw material sorting decisions at integrated containerboard mills. European producers deploying these systems report 15% yield improvements in mixed waste streams. The technology is compressing the cost gap between virgin and recycled Kraft furnish.
EPA emissions guidelines under the Clean Air Act are tightening particulate and sulfur dioxide limits for US pulp and paper facilities. Mills in the Southeast are investing in biomass boiler retrofits to maintain operating permits. The regulatory pressure is accelerating consolidation toward larger, more capitalized producers with compliance scale.
Brand procurement teams are consolidating corrugated suppliers to capture volume-based sustainability reporting. Major food and beverage packagers now require detailed carbon footprint disclosures per SKU. This concentration is visible most acutely in German and French markets where CSRD disclosure mandates begin with 2025 reporting cycles.
Fluting Paper Market Segmentation
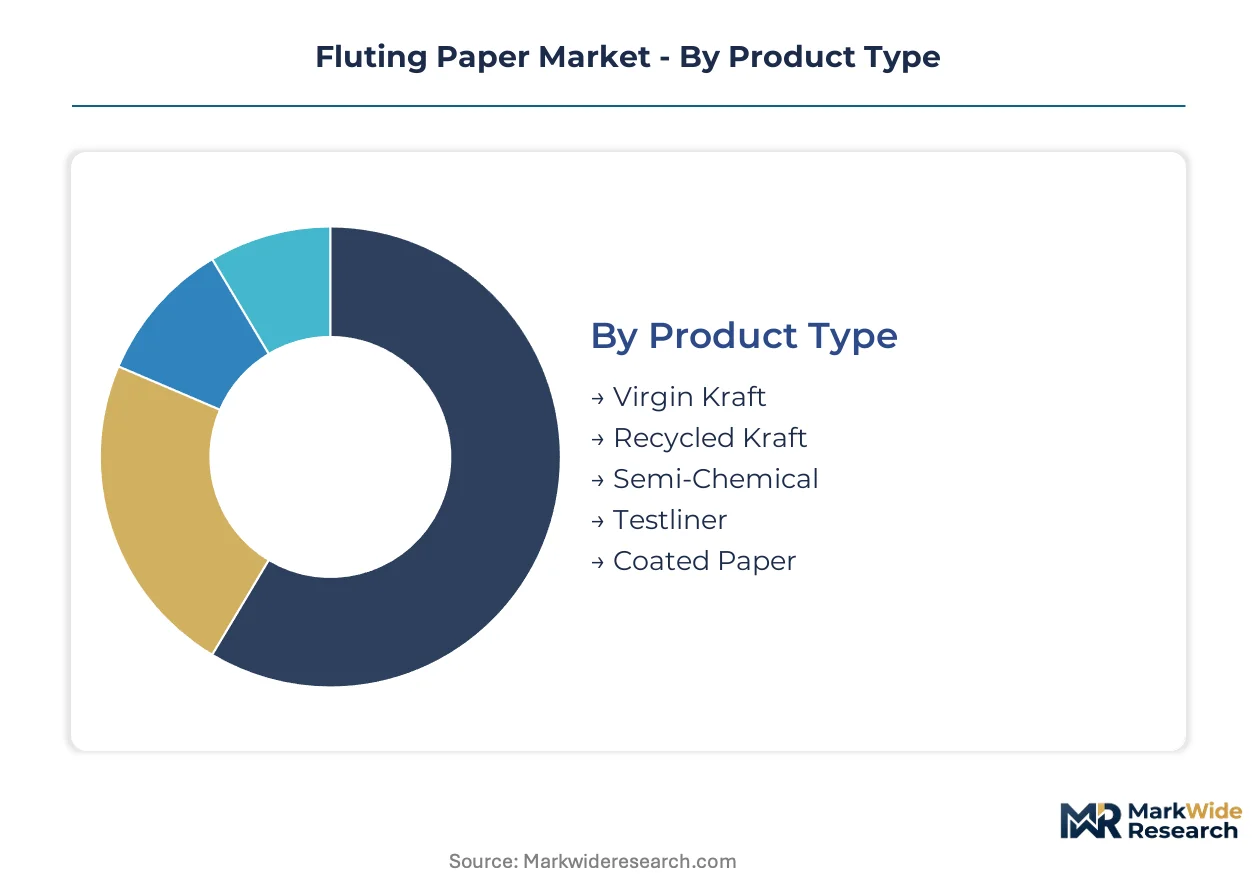
Fluting paper specifications diverge sharply across end-use requirements, with fiber composition and crush resistance parameters determining suitability for e-commerce shipping versus heavy industrial loads. Understanding these segment boundaries enables mills to optimize furnish blends and machine configurations for margin capture.
Product Type:
After-sales service intensity varies dramatically across product grades, with virgin Kraft requiring technical support for moisture-resistant formulations while recycled grades demand supply continuity guarantees.
- Virgin Kraft:Manufactured from unbleached softwood pulp with superior plybond strength and moisture resistance. Food-contact applications in Germany and France specify this grade for frozen seafood and chilled produce packaging where fiber purity standards under EU Packaging Waste Directive recycling targets still permit virgin content.
- Recycled Kraft:Processed from post-consumer corrugated containers with controlled short-fiber content for defined ring crush values. E-commerce fulfillment centers in the Netherlands and Belgium prioritize this grade for CSRD-aligned carbon reporting, though OCC price volatility forces mills to maintain 90-day inventory buffers.
- Semi-Chemical:Neutral sulfite semi-chemical pulping yields high-stiffness board for heavy machinery crating. Retains niche defense in German automotive parts logistics.
- Testliner:Hybrid furnish combining recycled fibers with virgin reinforcement for cost-optimized linerboard substitution. Polish and Czech converters favor this grade for secondary packaging.
- Coated Paper:Surface-treated fluting for direct-print branding applications. Premium chocolate and cosmetics unboxing experiences in Italy and Spain drive specification.
Recycled Kraft holds the largest share; momentum sits with Virgin Kraft as food-contact compliance tightens.
Application:
Volume concentration follows corrugated packaging infrastructure, with folding cartons representing a higher-margin adjacent category requiring distinct caliper control.
- Corrugated Packaging:Inner fluting layer between linerboards in RSC and die-cut boxes. Asia-Pacific logistics hubs in Indonesia and Vietnam consume this application at accelerating rates as warehouse automation raises box turnover velocity.
- Folding Cartons:Micro-flute grades for retail-ready shelf packaging. Pharmaceutical blister packs in Switzerland and Austria specify E-flute constructions with printable white top liners.
- Cushioning Material:Convoluted or die-cut inserts for electronics protection. Semiconductor equipment shipments from South Korea and Taiwan demand anti-static formulations.
- Protective Wraps:Interleaving sheets for glass and polished metals. Italian ceramic tile exporters specify moisture-buffered grades for containerized ocean freight.
- Industrial Packaging:Heavy-duty triple-wall constructions for capital equipment. German machine tool manufacturers retain semi-chemical specifications despite cost premiums.
Corrugated Packaging dominates volume; Folding Cartons is climbing the fastest as retail-ready formats displace secondary packaging.
End User Industry:
Customer procurement maturity separates commodity buyers from sustainability-mandated purchasers with embedded carbon accounting requirements.
- Consumer Goods:Personal care and household products requiring consistent printability. Unilever and Henkel procurement teams in the Netherlands enforce FSC chain-of-custody documentation across tier-2 suppliers.
- Electronics Manufacturing:Anti-static and moisture-vapor transmission specifications for semiconductor and display shipments. Foxconn and Pegatron facilities in China demand lot-traceable fiber sourcing.
- Food & Beverage:The most stringent regulatory exposure with direct food contact approvals. Nestlé and Danone sustainability teams in Switzerland and France now require per-SKU carbon disclosures.
- Pharmaceutical Logistics:Temperature-validated cold chain packaging with tamper-evidence integration. Temperature excursion liability drives specification conservatism.
- E-commerce Fulfillment:Highest volume velocity with lowest per-unit margin tolerance. Amazon and Zalando distribution networks in Germany prioritize lightweighting formulations to reduce dimensional weight charges.
Food & Beverage holds the largest share; E-commerce Fulfillment is gaining share fastest as last-mile density intensifies.
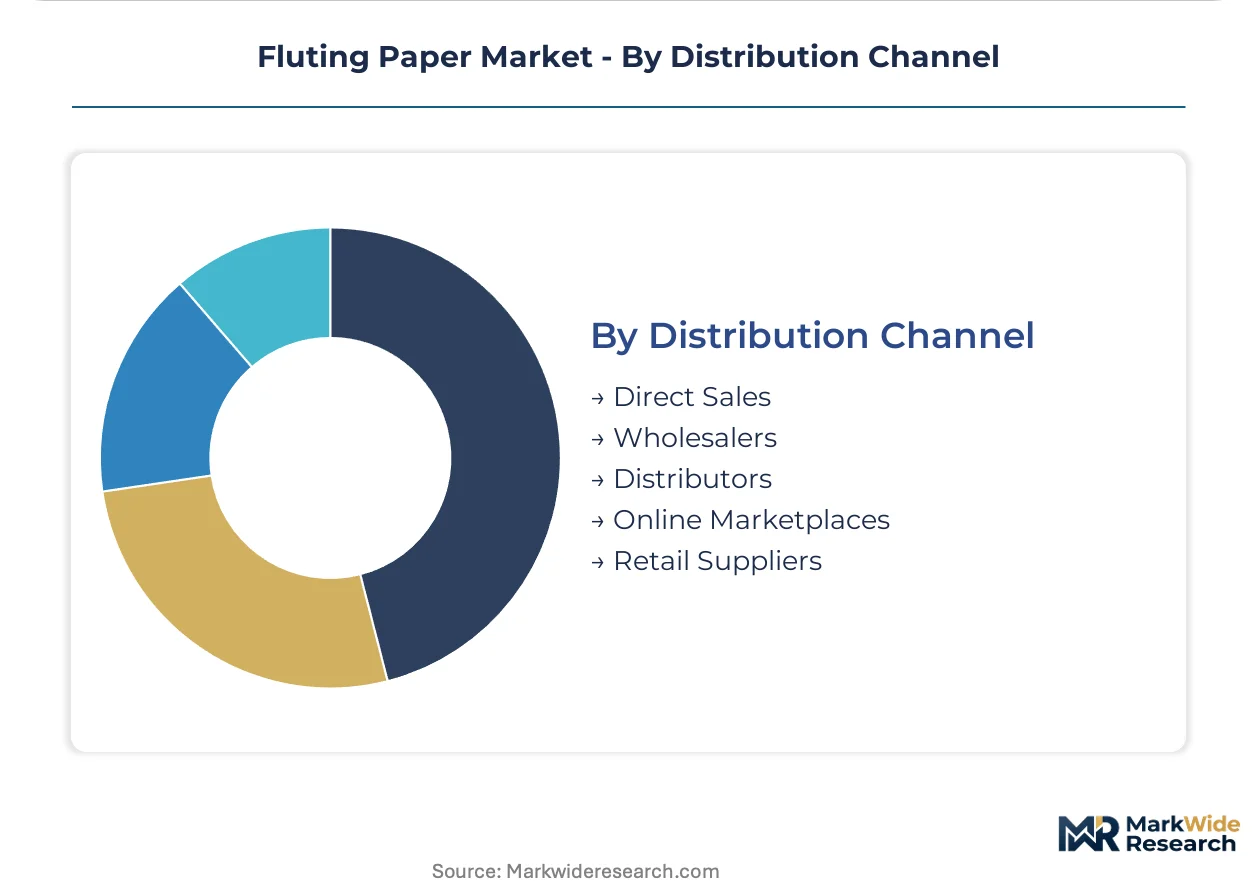
Distribution Channel:
Channel selection reflects order fragmentation, with direct sales capturing program accounts while distributors serve spot-market converters.
- Direct Sales:Mill-to-converter relationships for volume-program accounts. Smurfit Kappa and Mondi Group deploy dedicated key account managers for European retail chains.
- Wholesalers:Regional inventory pooling for mid-scale box plants. French and Italian wholesalers maintain 30-day stock positions near Lyon and Milan.
- Distributors:Technical specification support for specialty grades. Benelux distributors carry coated and food-contact certified inventories.
- Online Marketplaces:Spot purchasing for small converters and print shops. Alibaba and domestic platforms serve China's fragmented packaging base.
- Retail Suppliers:Consumer-facing sheet sales for craft and small business use. Stationery channels in Germany and Austria stock limited fluting assortments.
Direct Sales holds the largest share; Online Marketplaces is expanding most quickly as digital procurement penetrates mid-market converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardwood pulp concentration in Southeast Asia and integrated containerboard capacity in Central Europe are redirecting trade flows for fluting paper feedstock. China's waste import restrictions have fragmented regional sourcing networks. Regulatory divergence across EPA, REACH, and GB standards is forcing mills to maintain parallel compliance systems.
China
E-commerce fulfillment centers in Yangtze River Delta cities consume corrugated packaging at accelerating rates as warehouse automation raises box turnover velocity. GB standards on imported recovered paper purity have forced mills to rebuild fiber sourcing around domestic collection systems. Nine Dragons Paper operates integrated mills in Guangdong and Jiangsu provinces that process mixed furnish for regional containerboard supply.
Germany
Automotive parts logistics and food-contact packaging specifications sustain demand for moisture-resistant fluting grades. REACH chemical compliance and CSRD disclosure mandates beginning with 2025 reporting cycles enforce FSC chain-of-custody documentation. DS Smith and Smurfit Kappa maintain integrated production sites in Rhineland-Palatinate and North Rhine-Westphalia serving Benelux distribution networks.
United States
EPA emissions guidelines under the Clean Air Act tighten particulate limits for Southeast pulp and paper facilities. Biomass boiler retrofits in Georgia and Alabama accelerate consolidation toward capitalized producers with compliance scale. WestRock and International Paper operate containerboard mills across the Southeast and Pacific Northwest with captive recycling networks.
Indonesia
APP and APRIL control approximately 60% of regional hardwood pulp supply, creating bottleneck risk for containerboard producers. Ministry of Environment forestry audits tighten feedstock access for mills dependent on mixed furnish strategies. New mill capacity in Riau Province targets vertical integration into containerboard to capture Asia-Pacific logistics demand.
India
Organized retail expansion and quick-commerce platforms are adopting corrugated standards that displace traditional jute alternatives. Modern trade procurement teams in Mumbai and Delhi enforce consistent fluting specifications for automated packaging lines. Domestic mills in Gujarat and Maharashtra are expanding recycled fiber processing capacity to serve e-commerce fulfillment networks.
Fluting Paper Market Competitive Landscape
Integrated multinational groups and regional specialists split the market between scale-driven cost positions and flexible service models. Consolidation favors capitalized producers with captive fiber supply and multi-jurisdiction compliance infrastructure. Three archetypes dominate: integrated containerboard giants with recycling networks, virgin pulp-based premium specialists, and emerging Asian producers with hardwood pulp integration. Capacity expansion and strategic partnerships represent the dominant competitive moves as mills secure feedstock access.
Within the integrated multinational tier, Smurfit Kappa and Mondi Group exemplify archetypes built on European recycling networks and Central European co-production sites. DS Smith occupies a position emphasizing lightweight formulation specialization for e-commerce logistics cost reduction. Among Asia-Pacific producers, Nine Dragons Paper represents the scale-driven model with captive pulp integration and domestic market concentration. These anchors illustrate how fiber access and regulatory compliance scale separate competitive tiers.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Mondi Group |
| DS Smith |
| International Paper |
| Stora Enso |
| WestRock |
| Nine Dragons Paper |
| Sappi |
| Rengo Co. |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit cost volatility from Indonesian hardwood pulp concentration into European fluting paper price differentiation, compressing margins for converters dependent on mixed furnish strategies while rewarding integrated producers with captive fiber access.
Pricing Analysis
EU Packaging Waste Directive recycling targets dictate the pricing tier structure across virgin Kraft, recycled Kraft, and semi-chemical grades. Pricing stratifies across FSC-certified premium, standard recycled, and economy testliner tiers based on chain-of-custody documentation and moisture-resistance specifications. Cost compression in recycled Kraft is intensifying because OCC spot market swings force mills to absorb fiber input volatility. E-commerce fulfillment centers exhibit highest price sensitivity due to dimensional weight shipping economics, while pharmaceutical cold chain logistics tolerate premium pricing for lot-traceable fiber sourcing.
Supply Chain Analysis
Extended payment terms from Indonesian hardwood pulp suppliers to regional containerboard mills compress working capital cycles and favor capitalized producers with supply-chain finance facilities. Fiber sourcing concentrates in Indonesia, China, and Germany, with mixed furnish strategies drawing from domestic OCC collection systems and imported pulp blends. Production rests on old corrugated containers, unbleached softwood pulp, and neutral sulfite semi-chemical inputs. Single-source vulnerability from APP and APRIL controlling regional hardwood supply creates bottleneck exposure. Distribution runs through direct mill-to-converter relationships for volume accounts and regional wholesalers for fragmented box plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluting paper demand sits in early-cycle expansion as Asia-Pacific e-commerce fulfillment density accelerates corrugated packaging consumption beyond traditional industrial applications.
For Market Incumbents: Entrench competitive position through backward integration into captive pulp supply and certification investment for EU Packaging Waste Directive compliance. Smurfit Kappa and Mondi Group demonstrate how multi-jurisdiction recycling networks defend against Indonesian fiber concentration. Prioritize lightweighting R&D to capture Amazon and Zalando procurement specifications for dimensional weight reduction. For New Entrants and Emerging Players: India's organized retail corridors offer white-space penetration as quick-commerce platforms displace jute alternatives with standardized corrugated specifications. Target Gujarat and Maharashtra mill expansions serving domestic e-commerce fulfillment networks. Pursue FSC chain-of-custody certification as mandatory entry credential for European brand procurement teams. For Investors and Strategic Acquirers: Regional specialists with integrated containerboard capacity and hardwood pulp backward integration represent acquisition targets with defensible feedstock positioning. Long-term viability hinges on compliance scale across EPA, REACH, and GB standards. Monitor OCC spot market volatility as early signal for margin compression cycles and consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Pulp | Captive fiber supply from Indonesian plantations insulates against APP and APRIL bottleneck risk. |
| FSC Chain-of-Custody Certification | Mandatory documentation for Unilever and Henkel procurement compliance under EU circular mandates. |
| Lightweighting Formulation Development | DS Smith specialization reduces dimensional weight charges for Amazon fulfillment network specifications. |
| Domestic OCC Collection Network Expansion | China's GB standards on imported recovered paper purity force mills toward domestic sourcing rebuilds. |
| Digital Print Compatibility Investment | High-performance fluting grades capture premium positioning in Italian cosmetics unboxing experiences. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, mill capacity disclosures, and regulatory filings across EPA, ECHA, and Chinese Ministry of Ecology and Environment documentation. Primary interviews engaged containerboard plant managers, corrugated converter procurement leads, brand sustainability directors, and logistics packaging engineers. Secondary validation drew from FSC chain-of-custody databases, OCC price indices, and SEC 10-K filings from listed paper and packaging groups. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Forecast inputs span product type segmentation across virgin Kraft, recycled Kraft, semi-chemical, and testliner grades; application segmentation across corrugated packaging, folding cartons, and cushioning material; and end-use industry segmentation across food and beverage, e-commerce fulfillment, and electronics manufacturing. CAGRs derive from elasticity-adjusted demand modeling across the projection horizon. Industry-specific inputs incorporate e-commerce fulfillment center expansion pipelines and EU Packaging Waste Directive recycling target compliance trajectories.
Practitioners should monitor OCC spot market volatility, Indonesian forestry audit outcomes, and REACH chemical compliance amendments for early signals of forecast deviation. Macroeconomic contraction in Asia-Pacific logistics, regulatory relaxation of extended producer responsibility schemes, or breakthrough substitution from molded fiber alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Medical Packaging Paper Market