
 Coffee Filter Paper Market | 2026-2036
Coffee Filter Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Filter Paper Market Analysis
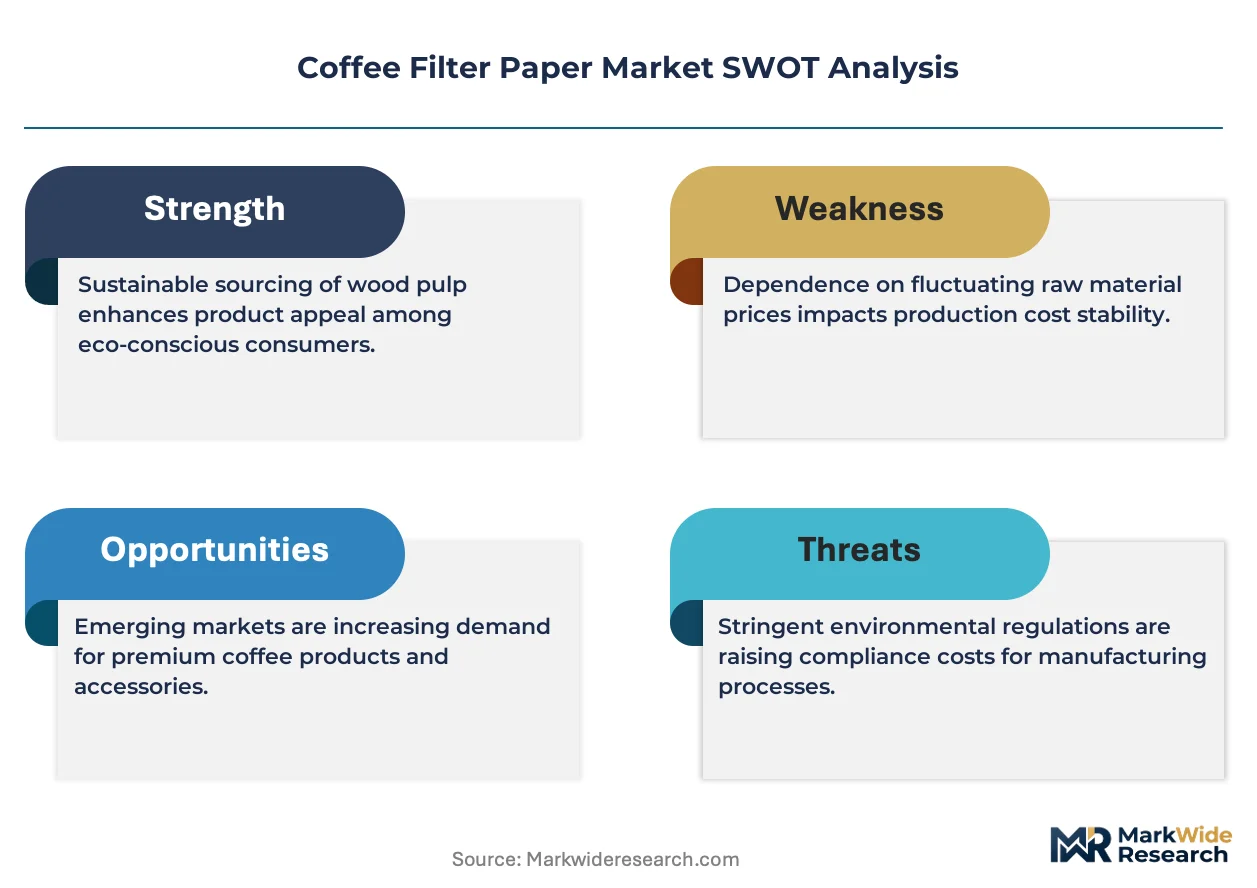
EU REACH chemical compliance is shifting the cost-of-entry calculus for pulp sourcing and bleaching chemistry across the Coffee Filter Paper Market. Ahlstrom-Munksjö leverages its Nordic pulp integration to sustain cost-competitive supply of unbleached grades for European roasters. Melitta Group anchors premium cone filter manufacturing through direct retail and foodservice channel control in Germany and adjacent markets.
Coffee filter paper is a porous cellulose sheet engineered to 15–30 micron pore sizes, typically composed of abaca pulp blends or wood fibers, designed to separate coffee grounds from brewed liquid while controlling extraction time and oil passage. Cone filters lead in specialty and pour-over segments where barista-grade precision commands margin premiums, while basket filters dominate household volume through compatibility with automatic drip machines. Biodegradable material grades are gaining fastest traction as roasters and retailers respond to packaging waste scrutiny across the EU and select US municipalities.
FDA food-contact substance regulations govern bleaching agent residues and pulp purity for US-bound products, while EU REACH and the F-Gas Regulation indirectly pressure energy-intensive drying processes in filter paper mills. BIS certification requirements affect export access for pulp suppliers serving Indian commercial brewing equipment markets. Stakeholders must monitor evolving compostability certification standards and pulp fiber provenance rules that will determine which material grades retain market access in major consuming regions.
Market Dynamics
The EU Single-Use Plastics Directive is forcing pulp suppliers to abandon plastic-reinforced filter grades and accelerate biodegradable fiber development, while specialty coffee chains in Western Europe and North America consolidate procurement around unbleached basket formats.
Growth Catalysts
- REACH chemical compliance:ECHA enforcement on bleaching agent residues is pushing roasters toward certified unbleached pulp suppliers with verified fiber provenance.
- Specialty coffee channel expansion:Pour-over and third-wave café formats in Germany, the Netherlands, and the United States are standardizing cone filter specifications that command margin premiums.
- Compostability certification:TÜV OK Compost and BPI standards are becoming de facto procurement gates for foodservice distributors serving municipal zero-waste mandates.
Market Restraints
- Abaca pulp supply concentration:Philippine and Ecuadorian fiber harvests dominate high-performance filter pulp, exposing mills to weather-driven input volatility and shipping cost spikes.
- F-Gas Regulation energy costs:EU restrictions on industrial refrigerants are raising drying process expenses for Nordic and Central European paper mills.
- Reusable metal filter substitution:Stainless steel mesh alternatives are capturing household segments in Germany and Scandinavia where durability preferences override disposable convenience.
Strategic Opportunities
- India commercial brewing equipment:BIS certification requirements for imported filters create captive supply opportunities for domestic pulp converters serving café chains in Mumbai and Bangalore.
- EU Green Deal carbon accounting:Scope 3 emissions disclosure mandates are rewarding filter paper suppliers with certified sustainable forestry chain-of-custody documentation.
- Direct-to-roaster digital platforms:E-procurement portals are disintermediating traditional foodservice distributors for mid-size specialty roasters in Italy and Spain.
Industry Challenges
- Compostability testing timelines:TÜV and BPI certification cycles for novel fiber blends extend 18-24 months, delaying product launches ahead of seasonal roasting contracts.
- Legacy equipment retrofit costs:Automatic drip machine installed bases in North American households constrain basket filter format innovation despite cone filter performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Filter Paper Market |
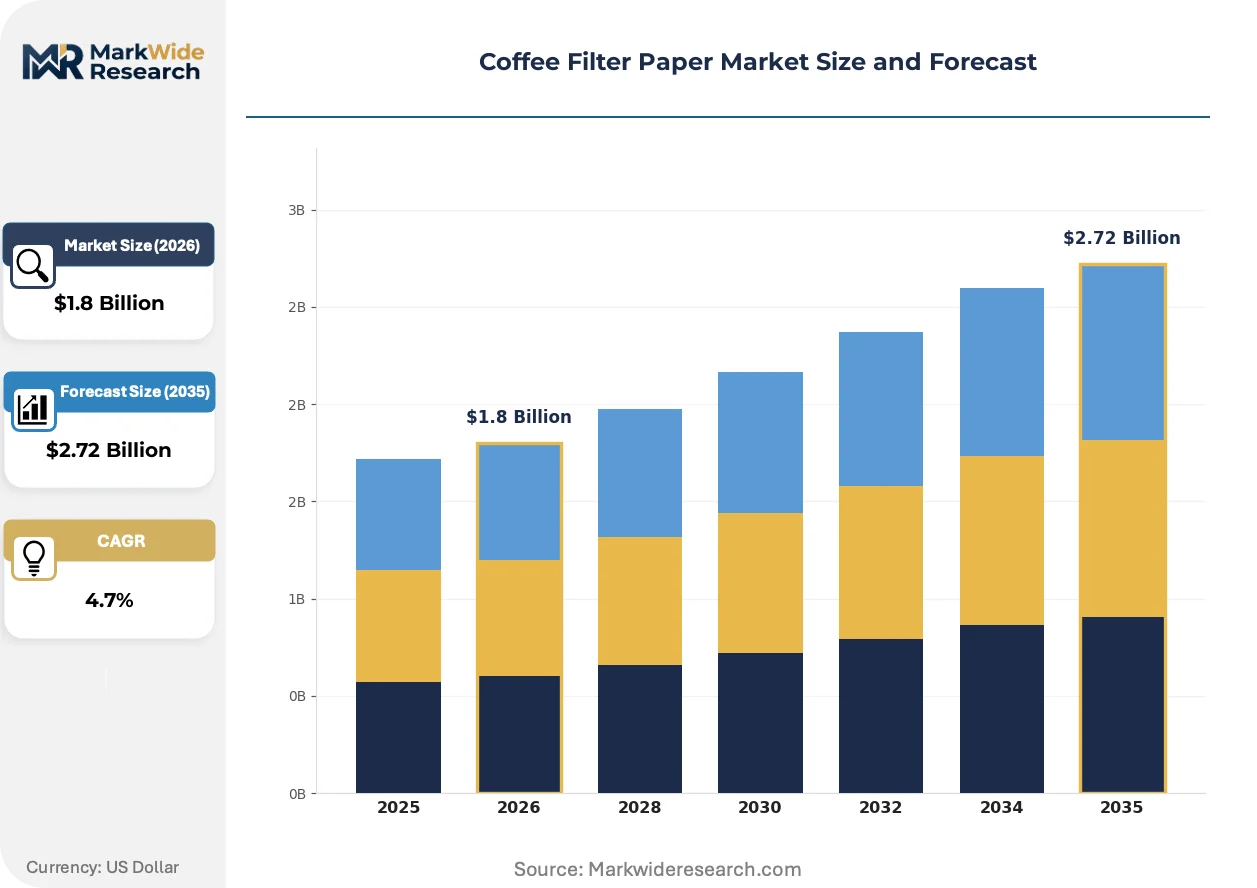
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cone Filter, Basket Filter, Disk Filter, Reusable Filter Material: Pulp, Synthetic Fiber, Natural Fiber, Biodegradable Material Application: Household, Commercial, Specialty, Instant Coffee Packaging Type: Packaged, Bulk, Individual Wrap, Retail-Friendly |
| Companies Covered | Filtropa, Ahlstrom-Munksjö, Melitta Group, Shawano Specialty Papers, Purico Group, Hario Co. Ltd., Rockline Industries, Little Rapids Corporation, Chemex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Filter Paper Market Emerging Trajectories
Bleached-free pulp grades and precision pore engineering are displacing conventional filter specifications as regulatory scrutiny and extraction science reshape buyer specifications across foodservice and household channels.
Bamboo-hemp fiber blends are expanding into specialty cone filter production as roasters seek alternatives to abaca-dependent supply chains. Third-wave cafés in Portland, Melbourne, and Copenhagen are piloting these grades for pour-over applications. The technology is expanding into premium private-label contracts previously held by Nordic pulp suppliers.
EU F-Gas Regulation enforcement is compressing energy-intensive drying capacity at Central European mills. Manufacturers are relocating finishing operations to Nordic sites with biomass energy integration. Cone filter production for German retail chains is most affected, with suppliers accelerating heat-recovery equipment upgrades.
Certification-driven procurement is consolidating supplier rosters as foodservice buyers mandate OK Compost HOME or BPI verification. Distributors in France and California are delisting uncertified grades. Roasters with direct retail footprints are absorbing compliance costs to secure shelf placement in municipal zero-waste zones.
Coffee Filter Paper Market Segmentation
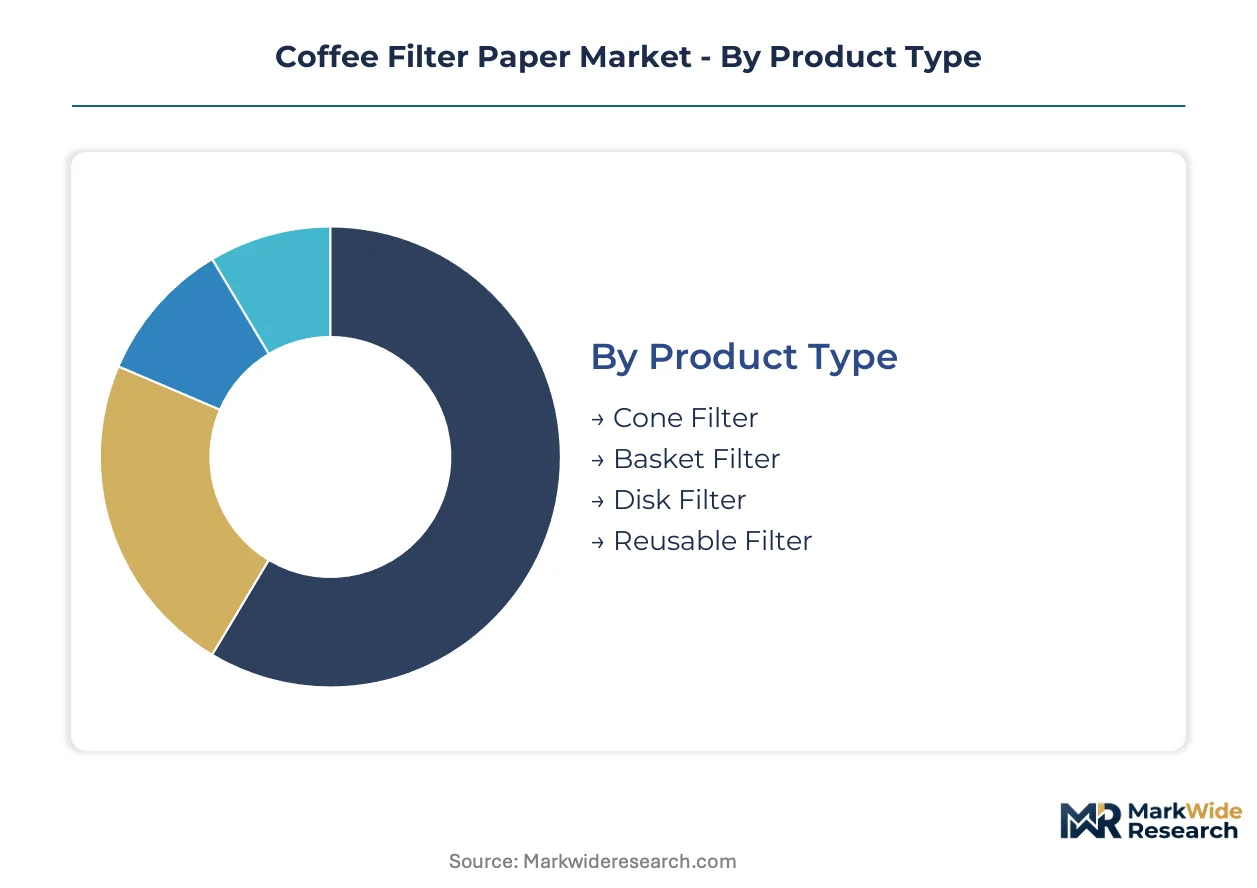
Coffee filter paper segmentation tracks the tension between household volume scale and specialty margin capture. Material certification tiers and format compatibility with brewing equipment determine supplier access to distinct procurement channels.
Product Type:
Cone filters command extraction precision premiums while basket formats dominate automatic drip machine compatibility and household volume.
- Cone Filter:Tapered cellulose construction with 18–25 micron pore calibration enables controlled flow rates for pour-over brewing. Third-wave cafés in Portland and Copenhagen standardize V60 and Chemex-compatible specifications, with procurement consolidating around bleached-free Nordic pulp grades. ECHA REACH compliance on bleaching residues is accelerating verified fiber provenance requirements for roaster direct contracts.
- Basket Filter:Flat-bottomed format engineered for automatic drip machines with wider pore distribution to accommodate faster extraction cycles. North American household volume concentrates here, though EU Single-Use Plastics Directive pressure is shifting foodservice procurement toward biodegradable pulp alternatives. Compatibility with legacy equipment installed bases constrains format migration despite cone filter performance advantages.
- Disk Filter:Circular format designed for AeroPress and similar immersion-pressure hybrid devices, typically denser caliper to withstand manual compression.
- Reusable Filter:Stainless steel mesh or cloth construction capturing durability-focused segments in Germany and Scandinavia where municipal waste mandates and consumer preference intersect.
Today's leader: Basket Filter. Tomorrow's challenger: Cone Filter.
Material:
Certification tiers separate foodservice-accessible grades from commodity pulp exposed to regulatory delisting.
- Pulp:Abaca-blend and wood fiber grades remain the performance baseline, with 15–30 micron pore engineering dependent on Philippine and Ecuadorian fiber harvests. TÜV OK Compost and BPI verification is becoming a procurement gate for distributors serving French and California municipal zero-waste mandates.
- Biodegradable Material:Bamboo-hemp fiber blends are gaining fastest traction as roasters seek alternatives to abaca supply concentration. Portland and Melbourne cafés are piloting these grades for pour-over applications, with private-label contracts expanding beyond traditional Nordic pulp supplier relationships.
- Natural Fiber:Unprocessed cellulose grades including cotton and sisal, positioned between certified biodegradable and conventional pulp on sustainability credentials.
- Synthetic Fiber:Plastic-reinforced grades facing phase-out under EU Single-Use Plastics Directive, with remaining demand concentrated in price-sensitive instant coffee processing.
Certification-compliant pulp holds current share. Biodegradable material grades are climbing the fastest as regulatory deadlines approach.
Application:
Channel differentiation tracks brewing equipment investment levels and consumer extraction knowledge.
- Specialty:Pour-over and third-wave café formats in Germany, the Netherlands, and the United States standardizing cone filter specifications with margin premiums attached to barista-grade precision. Direct-to-roaster digital procurement platforms are disintermediating traditional foodservice distributors for mid-size operators in Italy and Spain.
- Household:Automatic drip machine compatibility drives basket filter dominance, with purchasing concentrated through retail and e-commerce channels. Reusable metal filter substitution is capturing segments in Germany and Scandinavia where durability preferences override disposable convenience.
- Commercial:Office and institutional brewing equipment requiring high-volume, consistent extraction performance with cost minimization priorities.
- Instant Coffee:Industrial-scale filtration for soluble coffee production, typically synthetic fiber or lower-grade pulp due to minimal consumer-facing brand exposure.
Household volume anchors current supply. Specialty application represents the steepest expansion trajectory as café channel density increases.
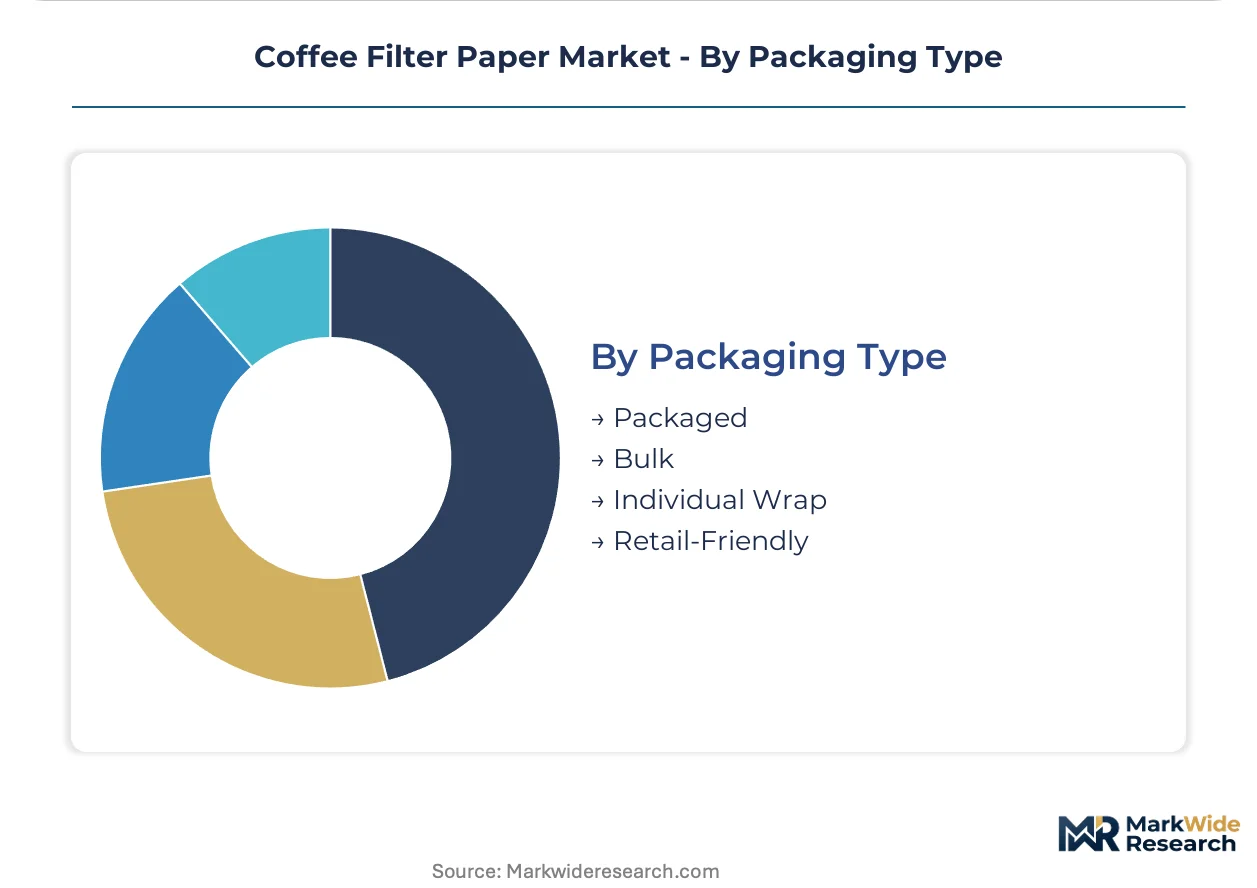
Packaging Type:
Packaging configuration reflects channel margin structure and shelf-life requirements.
- Retail-Friendly:Consumer-optimized formats with branding surface and reseal features, dominant in supermarket and specialty retail channels across Germany and North America.
- Bulk:Unwrapped carton formats for high-volume commercial accounts and roaster direct procurement, minimizing unit cost and packaging waste.
- Individual Wrap:Single-unit sealed packaging for hospitality amenity programs and foodservice portion control.
- Packaged:Standard multi-unit bags and boxes serving mainstream retail distribution.
Retail-friendly formats defend current margin. Bulk packaging is gaining share fastest as B2B e-procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coffee roasting expertise clusters in Germany, the United States, and Japan, anchoring premium filter paper demand through direct procurement relationships with Nordic and Southeast Asian pulp suppliers.
Germany
Third-wave café density in Berlin and Hamburg drives cone filter standardization for pour-over protocols. ECHA REACH enforcement on bleaching agent residues pushes roasters toward verified unbleached pulp suppliers. The Melitta Group anchors production in Minden, supplying both retail chains and foodservice distributors across Central Europe.
United States
Specialty roasting clusters in Portland and Los Angeles consolidate procurement around bleached-free basket formats for automatic drip compatibility. FDA food-contact substance regulations govern pulp purity for domestic-bound products. Shawano Specialty Papers maintains finishing capacity in Wisconsin serving Midwestern commercial brewing equipment markets.
Japan
Pour-over culture in Tokyo and Osaka sustains demand for precision-calibrated cone filters with 18–22 micron pore specifications. METI guidelines on sustainable procurement reward suppliers with certified chain-of-custody documentation. Hario Co. Ltd. anchors domestic production in Nihonbashi, supplying both household retail and café channels.
Netherlands
Amsterdam and Rotterdam roasting hubs source compostable grades for municipal zero-waste compliance. EU Single-Use Plastics Directive deadlines accelerate biodegradable fiber adoption across foodservice distribution. Filtropa serves Benelux café chains through direct-to-roaster digital procurement platforms.
India
Café chain expansion in Mumbai and Bangalore creates captive demand for BIS-certified filters compatible with imported commercial brewing equipment. Central Pollution Control Board waste management rules pressure foodservice operators toward biodegradable alternatives. Domestic pulp converters in Maharashtra and Karnataka scale capacity to replace imported basket filter supply.
Coffee Filter Paper Market Vendor Landscape
The competitive structure tilts toward integrated pulp-to-filter manufacturers with Nordic fiber sourcing advantages. Tier-one positions concentrate around European and North American firms controlling bleached-free grade certification. Three archetypes dominate: Nordic pulp-integrated specialists, Japanese precision-equipment hybrids, and North American volume-scale converters. Capacity expansion in biodegradable fiber processing and strategic partnerships with third-wave café chains represent the dominant competitive moves.
Among Nordic pulp-integrated specialists, Ahlstrom-Munksjö and Filtropa exemplify the certification-heavy tier serving EU foodservice distributors with verified fiber provenance. Melitta Group occupies a position bridging premium cone filter manufacturing with direct retail channel control. At the precision-equipment end, Hario Co. Ltd. and Chemex Corporation sit within the Japanese-origin archetype where brewing device and filter specification integration commands margin premiums.
| Leading Market Players |
|---|
| Filtropa |
| Ahlstrom-Munksjö |
| Melitta Group |
| Shawano Specialty Papers |
| Purico Group |
| Hario Co. Ltd. |
| Rockline Industries |
| Little Rapids Corporation |
| Chemex Corporation |
| Others |
Supply Flow & Price Mechanics
Abaca pulp fiber costs originating in Philippine and Ecuadorian harvests cascade through three pricing tiers before reaching end-buyers, with ECHA REACH compliance certification adding a discrete premium layer that separates foodservice distributors from household retail channels. Nordic mills with integrated biomass energy operations capture margin advantages over Central European competitors facing F-Gas Regulation-driven drying cost inflation.
Pricing Analysis
Bundled certification-and-product offerings command premiums over unbundled commodity grades, with TÜV OK Compost verification adding a compliance tier that foodservice distributors absorb to secure municipal zero-waste zone shelf placement. Three-tier pricing structure across premium cone, standard basket, and economy instant-coffee grades reflects extraction precision and fiber provenance differentiation. Pricing pressure stems from reusable metal filter substitution in German and Scandinavian household segments. Specialty roasters show lowest price sensitivity, while instant coffee processors resist any certification-driven cost pass-through.
Supply Chain Analysis
Workforce availability constraints in Finnish and Swedish pulp mill regions are tightening operational flexibility for Nordic integrated producers serving EU foodservice distributors. Philippine abaca fiber harvests, Ecuadorian wood pulp supply, and German cone filter finishing capacity anchor upstream concentration. Single-source vulnerability runs through Philippine fiber exposure to typhoon disruption. Distribution runs through roaster-direct digital platforms disintermediating traditional foodservice distributors for mid-size specialty operators in Italy and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Coffee Filter Paper Market represents a late-cycle quality story as third-wave café density in Berlin, Portland, and Tokyo consolidates procurement around bleached-free cone specifications with attached margin premiums.
For Market Incumbents: Extend certification coverage into bamboo-hemp fiber blends ahead of abaca supply concentration risks, and deepen backward integration into Nordic pulp sourcing to defend against F-Gas Regulation energy cost compression at Central European finishing sites. Channel control through direct-to-roaster digital platforms protects against distributor disintermediation. For New Entrants and Emerging Players: Capture BIS-certified filter supply gaps in Mumbai and Bangalore café chain expansion, and exploit compostability certification backlogs delaying incumbent product launches. White-space concentration sits in biodegradable basket filters for Indian commercial brewing equipment imports. Go-to-market leverage runs through domestic pulp converter partnerships bypassing import certification timelines. For Investors and Strategic Acquirers: Roll-up economics work for Nordic pulp-integrated specialists because EU Green Deal Scope 3 disclosure mandates are consolidating buyer procurement around verified chain-of-custody suppliers with captive fiber sourcing. Long-term viability favors platforms with biomass energy integration and certification infrastructure. Signal to monitor: TÜV OK Compost certification cycle compression indicating regulatory barrier reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Fiber Capacity Expansion | Bamboo-hemp blend investments reduce abaca supply concentration exposure for roaster direct contracts. |
| Certification Infrastructure Buildout | TÜV OK Compost and BPI verification capabilities unlock foodservice distributor access in California and France. |
| Backward Integration into Nordic Pulp | Finnish and Swedish fiber sourcing insulates margin from F-Gas Regulation energy cost pressure. |
| Direct-to-Roaster Digital Platform Launch | E-procurement portals disintermediate traditional distributors for mid-size Italian and Spanish specialty operators. |
| Heat-Recovery Equipment Upgrade | Biomass energy integration at Nordic finishing sites captures cone filter production relocating from Central Europe. |
Methodological Framework
Multiple input streams — structured interviews with specialty roaster procurement heads, pulp mill operations directors, and foodservice distribution category managers; trade data from EU customs filings and ECHA REACH registration databases; and SEC 10-K disclosures from paper industry participants — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation across product type, material certification tier, application channel, and regional regulatory cluster dimensions generated segment-level projections over the analysis window. CAGRs were derived from elasticity-adjusted volume trajectories and price-premium capture rates for certified grades. Forecast inputs incorporated ECHA enforcement intensity indices and café channel density metrics for third-wave markets.
Abaca harvest volatility, REACH compliance timeline acceleration, and reusable filter substitution velocity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification adoption curves and pulp fiber substitution elasticities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
GCC Paper Packaging Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Testliner Market