
 Paper Edge Protectors Market | 2026-2036
Paper Edge Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Edge Protectors Market Outlook
Buyer concentration in the logistics sector is decoupling from traditional manufacturing procurement patterns as e-commerce fulfillment operators fragment demand across smaller, more frequent orders. Smurfit Kappa leverages its European mill network to anchor regional supply security for corrugated paper edge formats. Sonoco Products Company specializes in custom edge engineering for automotive component shipping, while WestRock Company competes through integrated containerboard-to-protector production lines.
Paper edge protectors are structural packaging components manufactured from laminated kraft paperboard layers, typically formed into L-shaped, U-shaped, or flat profiles with calipers ranging from 2mm to 8mm, designed to shield palletized goods from strapping damage and corner impact during transit. Corner edge configurations dominate volume demand from appliance and furniture manufacturers, while recycled paper material grades capture expanding share as sustainability specifications harden in retail and e-commerce channels. Coated paper variants occupy premium positioning for moisture-sensitive pharmaceutical and electronics shipments where surface integrity commands price premiums.
The EPA's recyclable packaging guidelines and the EU Green Deal's packaging waste reduction targets are reshaping material specifications across North American and European supply chains. China's GB standards for transport packaging and India's BIS certification requirements for corrugated materials are elevating product testing protocols in Asian sourcing corridors. Stakeholders must monitor regulatory divergence between recycled content mandates and performance standards to calibrate regional product portfolios without fragmenting manufacturing scale.
Market Dynamics
E-commerce fulfillment networks are fragmenting procurement volumes into smaller, more frequent orders, decoupling logistics-sector demand from traditional manufacturing bulk purchasing patterns and forcing producers to reconfigure production scheduling and inventory management systems.
Growth Catalysts
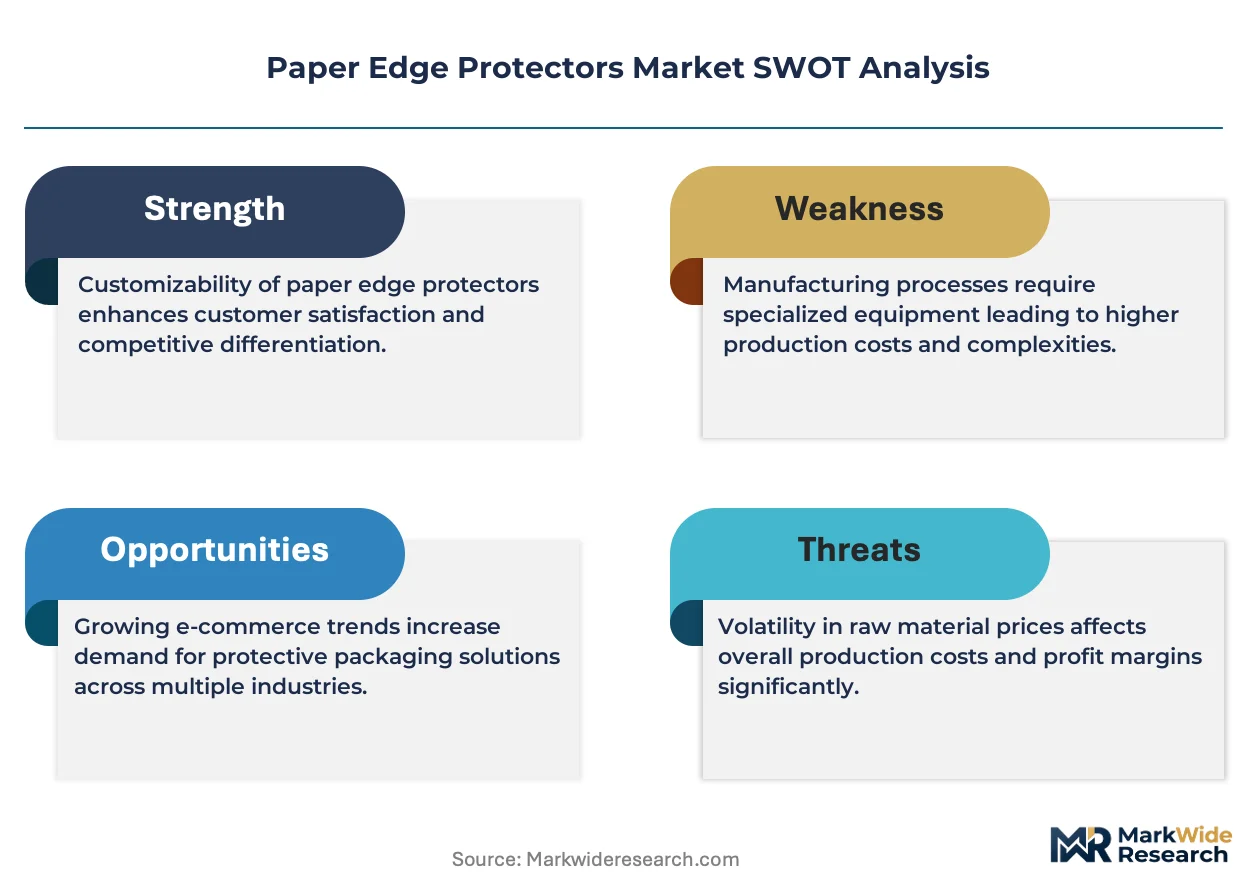
- EU Green Deal packaging waste targets:Mandates for recyclable transport packaging are accelerating specifications for recycled-content edge protectors across German and French retail supply chains.
- Automated distribution facility expansion:Dense networks of robotic fulfillment centers in China, Germany, and the United States are standardizing corner-edge formats to protect palletized goods in high-velocity sortation environments.
- Coated paperboard technology:Moisture-resistant surface treatments are capturing premium positioning for pharmaceutical and electronics shipments where humidity control commands specification priority.
Market Restraints
- Kraft pulp price volatility:Fluctuations in recycled paper feedstock costs compress margin predictability for producers dependent on post-consumer waste streams.
- Supply concentration in containerboard mills:Regional dependence on a limited number of integrated paperboard producers creates vulnerability to capacity allocation decisions in Germany and the United States.
- Performance limitations of recycled grades:Lower structural integrity in high-humidity environments restricts adoption for heavy-machinery and agricultural equipment exports.
Strategic Opportunities
- Indian BIS certification corridors:Emerging compliance requirements for corrugated transport materials are opening specification windows for producers establishing local testing partnerships.
- Pharmaceutical cold-chain expansion:Insulated edge protector configurations with thermal barrier properties address temperature-sensitive biologics distribution in North American and European markets.
- Digital print integration:Inline branding and tracking code application during protector manufacturing enables traceability-as-a-service offerings for high-value electronics and automotive components.
Industry Challenges
- GB standards compliance timelines:China's evolving transport packaging testing protocols require extended product validation cycles that delay market entry for new format introductions.
- Labor availability for precision forming:Skilled machine operators capable of calibrating multi-layer lamination equipment remain scarce in regions with declining paper industry employment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Edge Protectors Market |
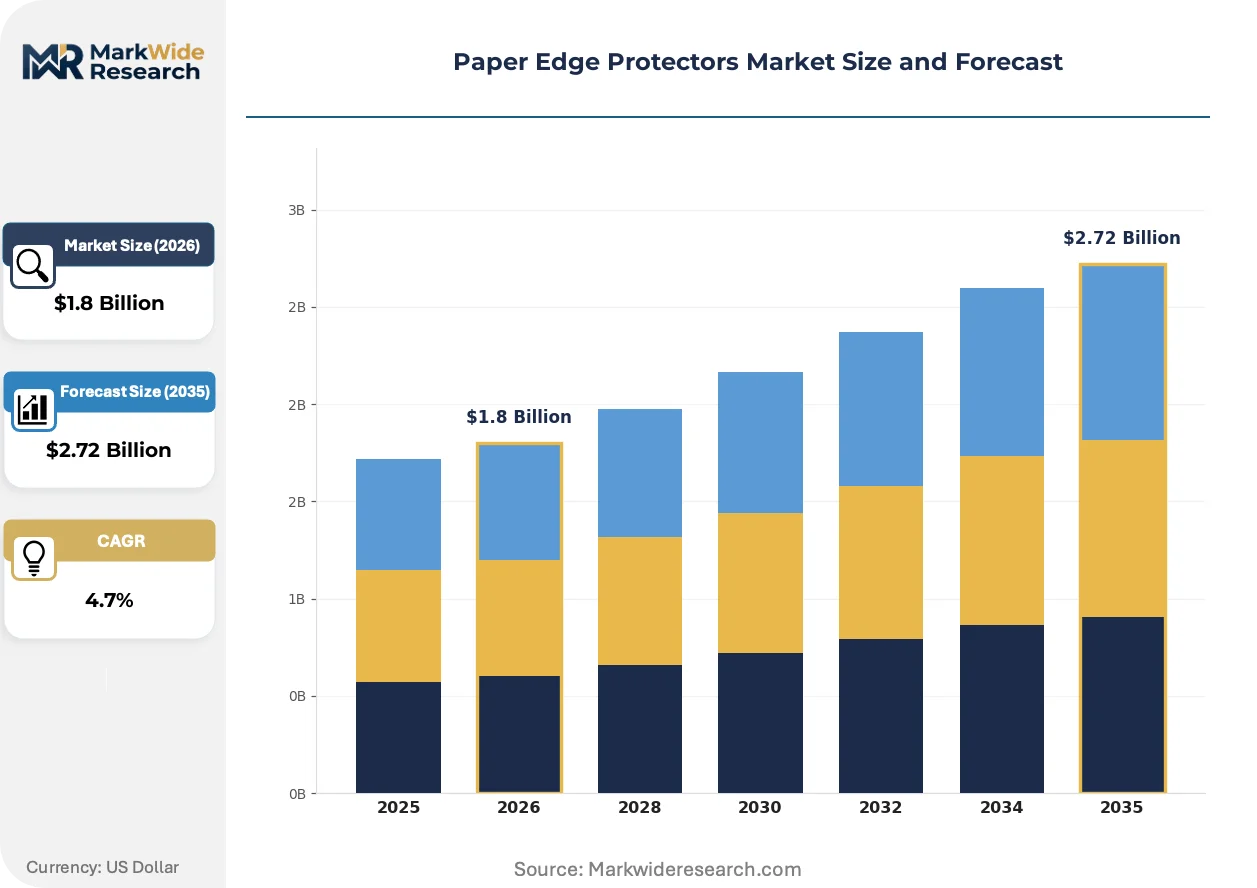
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Edge, Corner Edge, Multi-Use Edge, Custom Edge Material: Kraft Paper, Recycled Paper, Coated Paper, Corrugated Paper End User: Manufacturing, Logistics, Retail, E-commerce Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Smurfit Kappa, Sonoco Products Company, Packaging Corporation of America, Cascades Inc., WestRock Company, Mondi Group, VPK Group, Kunert Group, Napco National, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Edge Protectors Market Strategic Shifts
Active investment in material science and regulatory alignment is compressing product development cycles while expanding the functional boundaries of what edge protection systems can deliver beyond physical impact absorption.
Water-based barrier coatings derived from bio-wax formulations are electrifying moisture-resistance performance without compromising recyclability streams. Pharmaceutical distributors and fresh-produce exporters are specifying these treatments for ocean-container shipments where condensation exposure previously mandated plastic alternatives. This technology is electrifying competitive positioning by collapsing the performance gap between fiber-based and synthetic protective systems.
EPA recyclable packaging guidelines are mandating disclosure of post-consumer content percentages across federal procurement channels. Suppliers to United States government logistics contracts must now certify minimum recycled fiber thresholds, pushing integrated producers to reconfigure pulping lines toward higher waste-paper integration rates. Military and aerospace component shippers face the steepest compliance ramps given their legacy reliance on virgin kraft specifications.
Consolidated buying desks at major e-commerce operators are unbundling protective packaging from freight contracts and awarding separate multi-year agreements to specialized edge protector manufacturers. Third-party logistics providers in the United States and Germany are ceding specification control to platform operators who demand format standardization across their fulfillment networks. Appliance and furniture verticals exhibit the most pronounced concentration of procurement authority into centralized sustainability and packaging engineering teams.
Paper Edge Protectors Market Segmentation
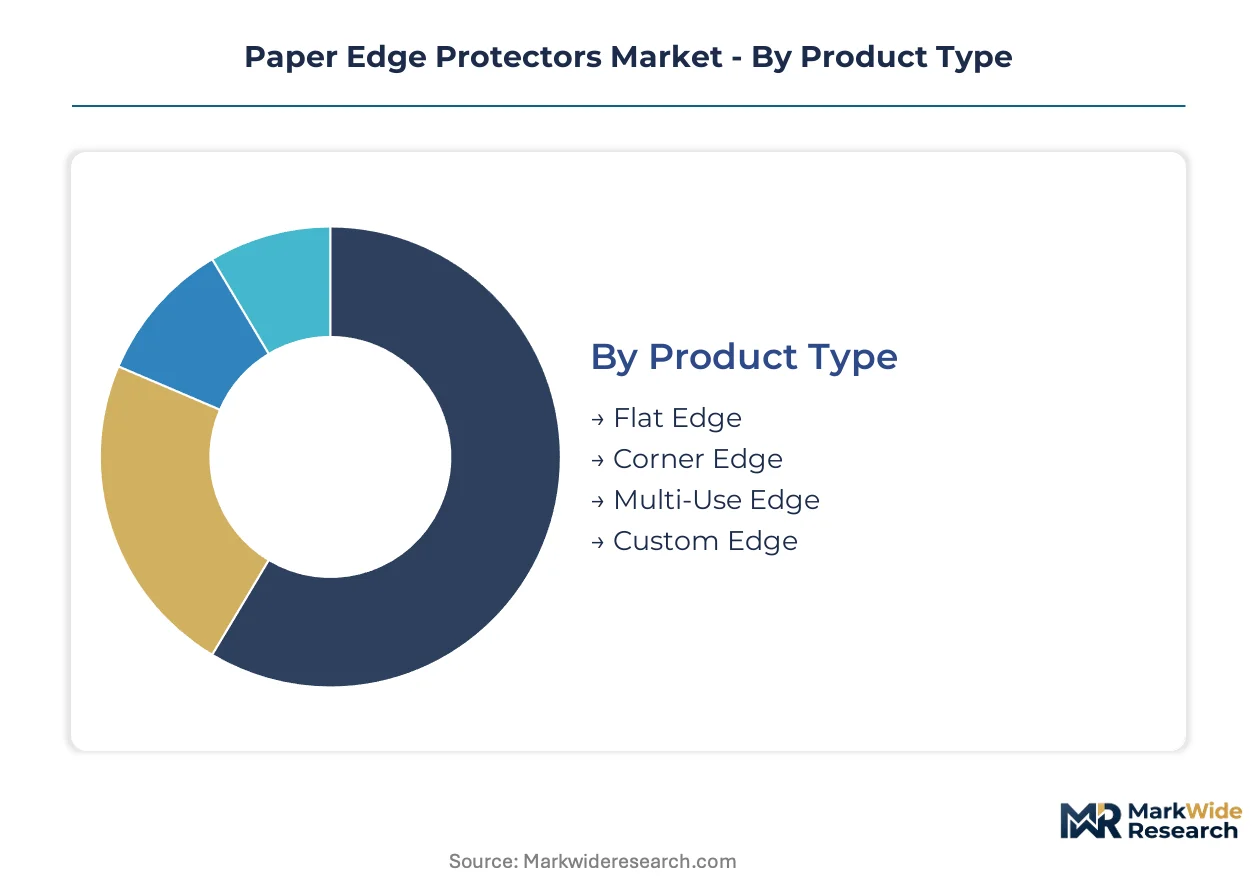
Paper edge protector procurement fragments across technical specifications, material grades, and channel structures that reflect divergent buyer priorities. Understanding these fault lines clarifies where producers must calibrate customization depth against manufacturing scale.
Product Type:
Customization intensity varies sharply across this category, from commodity flat formats to engineered multi-layer configurations requiring precision lamination.
- Corner Edge:L-shaped profiles formed from multi-layer kraft paperboard laminations with calipers between 3mm and 6mm. Appliance manufacturers in Germany and furniture exporters in China concentrate procurement here, driven by automated palletization systems that standardize corner protection protocols.
- Custom Edge:Application-specific geometries including U-channels, circular profiles, and compound angles requiring CNC forming equipment. Automotive component shippers specify these for irregular part geometries, though order fragmentation strains production scheduling.
- Flat Edge:Single-plane protectors deployed primarily for edge stacking reinforcement in bulk commodity shipments.
- Multi-Use Edge:Convertible profiles adaptable between corner and flat applications through score-line configurations.
Most installed capacity flows through Corner Edge formats. Expansion is steepest in Custom Edge as e-commerce fulfillment networks fragment specification requirements.
Material:
Cost tier stratification aligns with performance requirements and regulatory pressure across sourcing corridors.
- Recycled Paper:Post-consumer fiber content ranging from 80% to 100%, processed through repulping and reconstitution into laminated boardstock. EU Green Deal compliance deadlines in Germany and France are accelerating specifications here, though humidity performance lags virgin grades.
- Coated Paper:Surface-treated kraft substrates with bio-wax or polymer barriers enabling moisture resistance without compromising recyclability streams. Pharmaceutical distributors in the United States specify these for ocean-container biologics shipments.
- Kraft Paper:Virgin fiber laminations retaining maximum structural integrity for heavy machinery exports.
- Corrugated Paper:Fluted medium constructions offering crush cushioning at reduced material weights.
Volume leadership sits with Recycled Paper as retail procurement mandates harden. Coated Paper is climbing the fastest as cold-chain pharmaceutical distribution expands.
End User:
Customer type determines order frequency, specification control locus, and sustainability compliance stringency.
- E-commerce:Fulfillment operators including Amazon, Alibaba, and regional platform logistics arms. Centralized packaging engineering teams unbundle protective specifications from freight contracts, demanding format standardization across multi-node distribution networks.
- Logistics:Third-party providers and dedicated contract carriers. Procurement authority is fragmenting as platform operators assume specification control.
- Manufacturing:Appliance, furniture, and automotive OEMs with legacy bulk purchasing patterns.
- Retail:Big-box and specialty chains consolidating sustainability compliance across private-label supply chains.
Procurement volume concentrates in E-commerce. Manufacturing retains the steepest expansion trajectory as reshoring initiatives rebuild domestic production footprints.
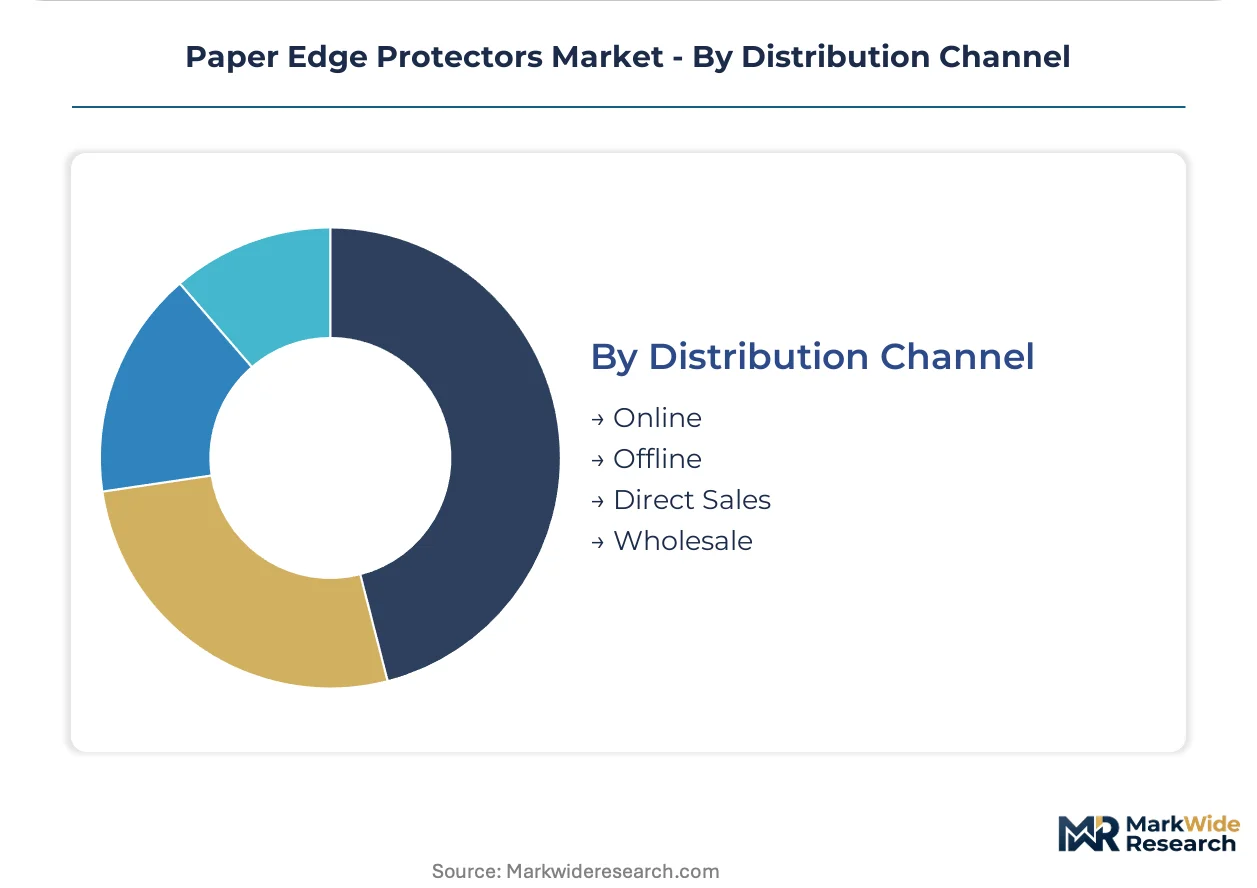
Distribution Channel:
Channel selection reflects buyer scale, technical consultation requirements, and inventory velocity constraints.
- Direct Sales:Producer-to-end-user relationships for high-volume accounts requiring format engineering collaboration. Major e-commerce operators in the United States and Germany negotiate multi-year agreements directly with specialized manufacturers.
- Wholesale:Distributor intermediaries serving mid-tier manufacturers and regional logistics providers with standardized catalog formats.
- Online:Digital procurement platforms enabling spot purchasing for smaller fulfillment operators.
- Offline:Traditional trade relationships through paper industry brokers and packaging distributors.
Revenue concentration flows through Direct Sales. Wholesale channels are expanding most quickly as mid-market e-commerce entrants seek supply security without engineering investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled machine operators for multi-layer lamination equipment concentrate in Germany's Ruhr industrial corridor, China's Yangtze River Delta, and the American Midwest, anchoring production capacity in these three manufacturing heartlands.
United States
Amazon and Walmart fulfillment networks drive specification standardization for corner-edge formats across multi-node distribution centers. EPA recyclable packaging guidelines mandate minimum post-consumer fiber thresholds for federal logistics contracts. Chicago and Dallas automated sortation hubs concentrate procurement authority into centralized packaging engineering teams.
Germany
Dense robotic fulfillment infrastructure in Bavaria and North Rhine-Westphalia standardizes pallet protection protocols for appliance manufacturers. EU Green Deal packaging waste targets accelerate recycled-content specifications through 2030. The Düsseldorf-Cologne corridor hosts Europe's tightest network of integrated containerboard-to-protector production lines.
China
Alibaba and JD.com logistics arms fragment demand into smaller, more frequent orders across Pearl River Delta fulfillment nodes. GB standards for transport packaging elevate product testing protocols with extended validation cycles. Shanghai and Shenzhen automated distribution facilities anchor regional demand for moisture-resistant coated variants.
India
Flipkart and Reliance Retail logistics expansion concentrates procurement in Maharashtra and Karnataka fulfillment corridors. BIS certification requirements for corrugated transport materials open specification windows for producers establishing local testing partnerships. Mumbai-Pune industrial belt hosts emerging conversion capacity for export-grade edge protection systems.
France
Pharmaceutical cold-chain distributors in Île-de-France specify insulated edge configurations for temperature-sensitive biologics shipments. EU Green Deal compliance deadlines harden sustainability specifications across retail supply chains. Lyon and Paris logistics clusters drive adoption of bio-wax barrier coatings for ocean-container pharmaceutical exports.
Paper Edge Protectors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Containerboard-integrated multinationals leverage captive pulp supply and mill network density to anchor regional cost positions. Specialized converters occupy premium niches through custom engineering capabilities and format flexibility. Consolidated buying desks at major e-commerce operators concentrate procurement authority, forcing producers to defend margin position through multi-year contract structures and logistics integration partnerships.
Within the integrated paperboard tier, Smurfit Kappa and WestRock Company exemplify scale-driven positioning through mill network control and containerboard-to-protector production integration. Sonoco Products Company occupies a specialist position in custom edge engineering for automotive and industrial component shipping. These three anchors represent divergent competitive vectors: European mill density, North American vertical integration, and application-specific engineering depth.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Sonoco Products Company |
| Packaging Corporation of America |
| Cascades Inc. |
| WestRock Company |
| Mondi Group |
| VPK Group |
| Kunert Group |
| Napco National |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste reduction targets gate qualified supply access and premium-tier pricing power by mandating certified recycled-content thresholds that only integrated mill networks can reliably deliver. Buyers seeking federal logistics contracts in the United States face parallel EPA disclosure requirements that compress procurement options toward certified suppliers capable of documenting post-consumer fiber percentages.
Pricing Analysis
Bundled freight-and-packaging contracts are unbundling into separate multi-year agreements for edge protector specifications, with e-commerce operators now controlling format standardization across fulfillment networks. Pricing stratifies across moisture-resistant coated variants for pharmaceutical cold-chain, certified recycled grades for EU retail compliance, and commodity kraft formats for heavy machinery exports. Cost compression in standard recycled grades is intensifying because kraft pulp feedstock volatility erodes margin predictability. Mid-tier logistics providers exhibit the steepest price sensitivity, while pharmaceutical distributors accept substantial premiums for bio-wax barrier coatings.
Supply Chain Analysis
Certification requirements from BIS in India and evolving GB standards in China are gating market entry and fragmenting qualified supplier pools across Asian sourcing corridors. Production gravity centers on Germany, the United States, and China, where skilled lamination equipment operators concentrate in the Ruhr corridor, American Midwest, and Yangtze River Delta. Feedstock supply draws from post-consumer waste streams, virgin kraft pulp, and bio-wax coating inputs. Single-source vulnerability runs through integrated containerboard mills in Germany and the United States. Distribution runs through direct sales relationships with major e-commerce operators and wholesale intermediaries serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification control is migrating toward e-commerce fulfillment operators demanding premium-performance formats with certified sustainability credentials. The shift toward moisture-resistant coated variants for pharmaceutical and electronics shipments rewards producers with material science capabilities over commodity converters.
For Market Incumbents: Anchor regional supply security by locking multi-year fiber supply agreements with integrated containerboard mills in Germany and the American Midwest before capacity allocation decisions favor alternative product lines. Invest in water-based barrier coating R&D to defend premium positioning against synthetic substitute technologies. Certification depth for EU Green Deal and EPA compliance serves as the primary defensible moat.
For New Entrants and Emerging Players: Capture specification windows in Indian BIS certification corridors and pharmaceutical cold-chain segments where incumbent coverage remains thin. Maharashtra and Karnataka fulfillment clusters offer the most penetrable geography for establishing local testing partnerships. Lead with digital print integration for traceability-as-a-service offerings to differentiate from commodity producers.
For Investors and Strategic Acquirers: Roll-up economics work for regional custom-edge specialists because e-commerce procurement fragmentation is concentrating demand into format-flexible converters with engineering depth. The five-to-ten year viability window favors producers with captive coating technology and multi-region certification coverage. Monitor Alibaba and JD.com logistics procurement centralization as the inflection signal for pricing power consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Supply | Captive pulp access insulates margin from kraft price volatility in German and US corridors. |
| Bio-Wax Barrier Coating Scale-Up | Moisture-resistant fiber formats displace plastic alternatives in pharmaceutical ocean-container shipments. |
| BIS Certification Partnership in India | Local testing capability unlocks specification windows in Maharashtra and Karnataka fulfillment clusters. |
| Digital Print Integration for Traceability | Inline branding and tracking codes enable premium positioning for automotive and electronics components. |
| Multi-Year Contract Structuring with E-commerce Operators | Amazon and Alibaba logistics arms are unbundling packaging from freight contracts and consolidating procurement authority. |
Study Parameters
Direct dialogue with packaging engineering directors at e-commerce fulfillment operators, procurement leads at third-party logistics providers, plant managers at integrated containerboard mills, and sustainability compliance officers at retail chains grounded qualitative findings. Secondary validation drew from EPA recyclable packaging guidelines, EU Green Deal regulatory filings, Chinese GB standards documentation, Indian BIS certification protocols, and customs trade data for laminated paperboard categories. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators.
Segment-level projections for corner edge, custom edge, flat edge, and multi-use formats were generated across the analysis window by calibrating adoption curves to automated distribution facility buildout timelines in named countries. Material-grade splits between recycled paper, coated paper, kraft paper, and corrugated paper were modeled against regulatory compliance deadlines. CAGRs were derived from logistic curve fitting to historical capacity expansion patterns and forward-looking procurement contract disclosures.
Kraft pulp price volatility, regulatory divergence between recycled content mandates and performance standards, and labor scarcity for precision lamination equipment are the dominant revision risks that could compress or extend projected growth trajectories. A model refresh is warranted upon material change in e-commerce operator procurement centralization patterns or EU Green Deal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market