
 Bamboo Packaging Market | 2026-2036
Bamboo Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Packaging Market Outlook
A capital-intensity divergence between plantation-owning integrated producers and asset-light converters is rotating competitive advantage toward upstream biomass control. MOSO International B.V. leverages its Dutch design-engineering base to dominate European specification-grade supply. EcoPlanet Bamboo Group anchors its position through direct plantation ownership in Central America, securing fiber traceability for cosmetics-grade packaging. Smith & Fong Co. differentiates via calibrated lamination technology that extends bamboo board performance into electronics cushioning applications.
Bamboo packaging comprises engineered fiberboard, molded pulp, and woven textile structures derived from Phyllostachys edulis or Bambusa blumeana culms, typically processed through mechanical defibration or caustic soda pulping to achieve tensile strengths of 30–50 MPa. These materials serve as structural substitutes for petroleum-based corrugated board and expanded polystyrene in protective and display applications. Boxes and bags command the largest current volume pools, with compostable material-grade variants capturing accelerating premium positioning as landfill-diversion mandates proliferate. Food industry end-use applications sustain the deepest demand base, while cosmetics and electronics segments concentrate margin pools in certified biodegradable grades with batch-level chain-of-custody documentation.
The US EPA and FDA jointly govern food-contact substance safety for bamboo fiber substrates, while the EU REACH regulation and F-Gas framework indirectly pressure substitution away from synthetic barrier coatings. China's SAMR enforces GB/T standards for biodegradable packaging claims, creating a fragmented compliance landscape that favors multi-certified producers. Stakeholders must monitor evolving compostability certification reciprocity between European OK Compost and US BPI regimes to avoid market-access friction.
Market Dynamics
Single-use plastic bans across Germany, France, and California are compressing substitution timelines and forcing food-contact material recertification at unprecedented speed.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content quotas and extended producer responsibility schemes accelerate brand-owner migration toward fiber-based alternatives.
- Caustic soda pulping refinement:Process innovations reducing lignin retention below 2% enable bamboo fiberboard to meet electronics-grade cushioning specifications previously reserved for molded pulp.
- East Asian manufacturing clusters:Zhejiang and Fujian provinces concentrate 60% of global bamboo board capacity, creating procurement gravity for multinational CPG brands.
Market Restraints
- Caustic soda and sulfuric acid price volatility:Chemical input costs swing 15-40% quarterly, compressing converter margins on fixed-price annual contracts.
- Plantation concentration in subtropical belts:Sourcing dependence on narrow latitudinal bands exposes supply chains to monsoon disruption and land-use competition.
- Barrier coating performance gaps:Water-based coatings fail grease-resistance tests above 60°C, limiting hot-fill food applications.
Strategic Opportunities
- India's FSSAI biodegradable packaging roadmap:Pending national standards for food-contact bioplastics create first-mover positioning for certified exporters.
- Cosmetics airless pump integration:Bamboo-PP hybrid shells for premium skincare packaging command 3-4x unit economics versus corrugated.
- Direct-to-brand e-commerce fulfillment:Amazon's Frustration-Free Packaging and Shopify's carbon-neutral shipping programs open bypass channels around traditional distributor markups.
Industry Challenges
- Compostability certification reciprocity gaps:European OK Compost and US BPI testing protocols diverge on heavy-metal thresholds, forcing dual certification costs.
- Defibration equipment lead times:Italian and German pulping line manufacturers quote 18-month delivery windows, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Packaging Market |
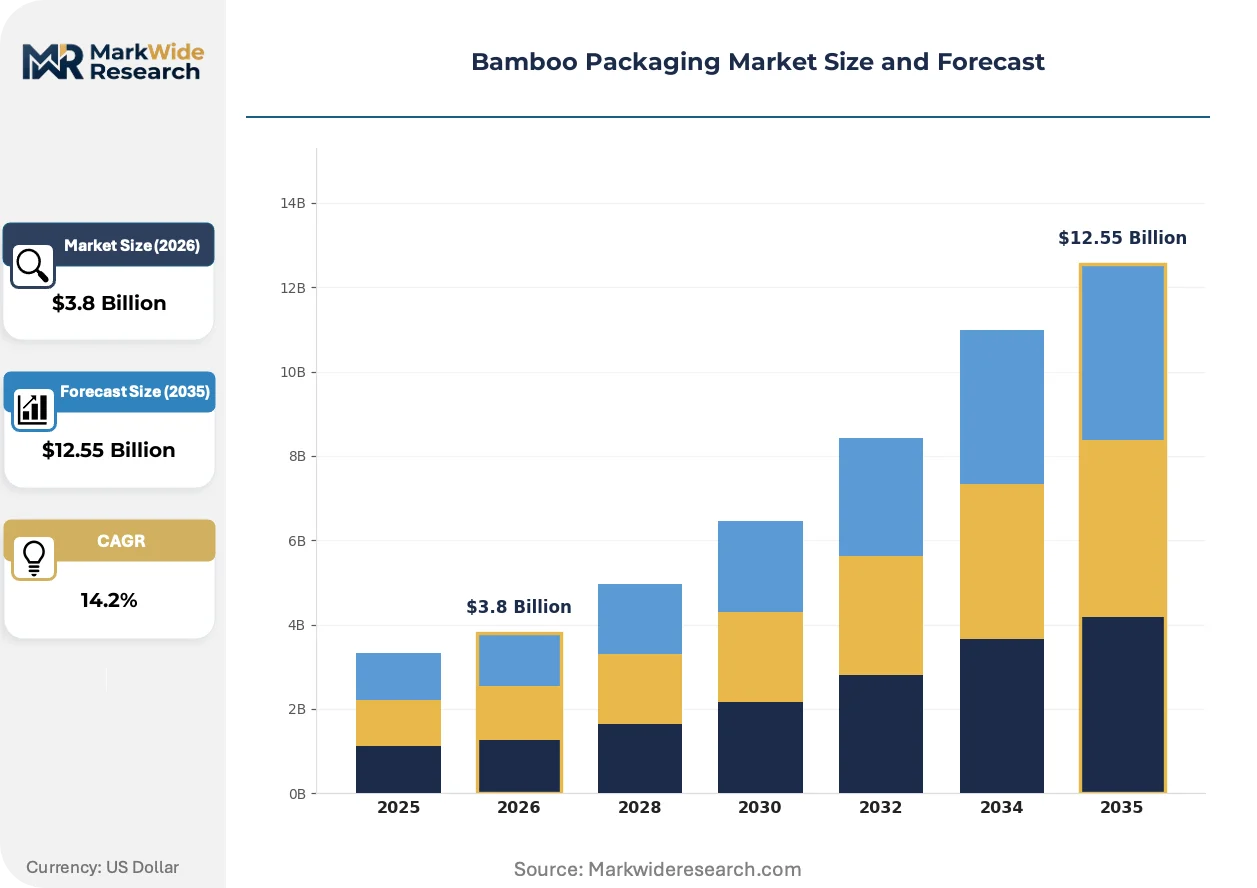
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wrapping, Display Stands End Use: Food Industry, Cosmetics, Electronics, Retail Material Grade: Biodegradable, Compostable, Recyclable, Sustainable Application: Packaging, Transportation, Storage, Marketing |
| Companies Covered | EcoPlanet Bamboo Group, Three Bamboo, MOSO International B.V., APackaging Group, Gidea PAC, Bamboo Village Company Limited, The Bamboo Company, Bloom Eco Packaging, Smith & Fong Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Packaging Market Strategic Shifts
Mechanical defibration and enzymatic pre-treatment are converging to expand bamboo fiber performance envelopes beyond traditional corrugated substitutes.
Enzymatic pre-treatment using laccase-mediator systems is fragmenting the technical barrier between bamboo pulp and hardwood kraft specifications. Cosmetics brands in France and South Korea now specify enzymatically refined fiber for rigid box applications. The technology is compressing the premium gap between plantation-controlled supply and commodity recycled board.
China's SAMR enforcement of GB/T 38082-2019 biodegradable plastics labeling is forcing packaging converters to segregate production lines by certification grade. Export-oriented manufacturers in Zhejiang province face audit backlogs exceeding eight months. Food-contact bamboo products destined for EU markets now require parallel GB/T and EU REACH documentation.
Brand-owner sustainability scorecards are compressing supplier qualification cycles from 24 months to 90 days. Nestlé and Unilever procurement teams in Switzerland and the Netherlands now mandate batch-level carbon footprint data. The shift is visible most acutely in electronics unboxing experiences, where bamboo molded pulp displaces expanded polystyrene for premium device launches.
Bamboo Packaging Market Segmentation
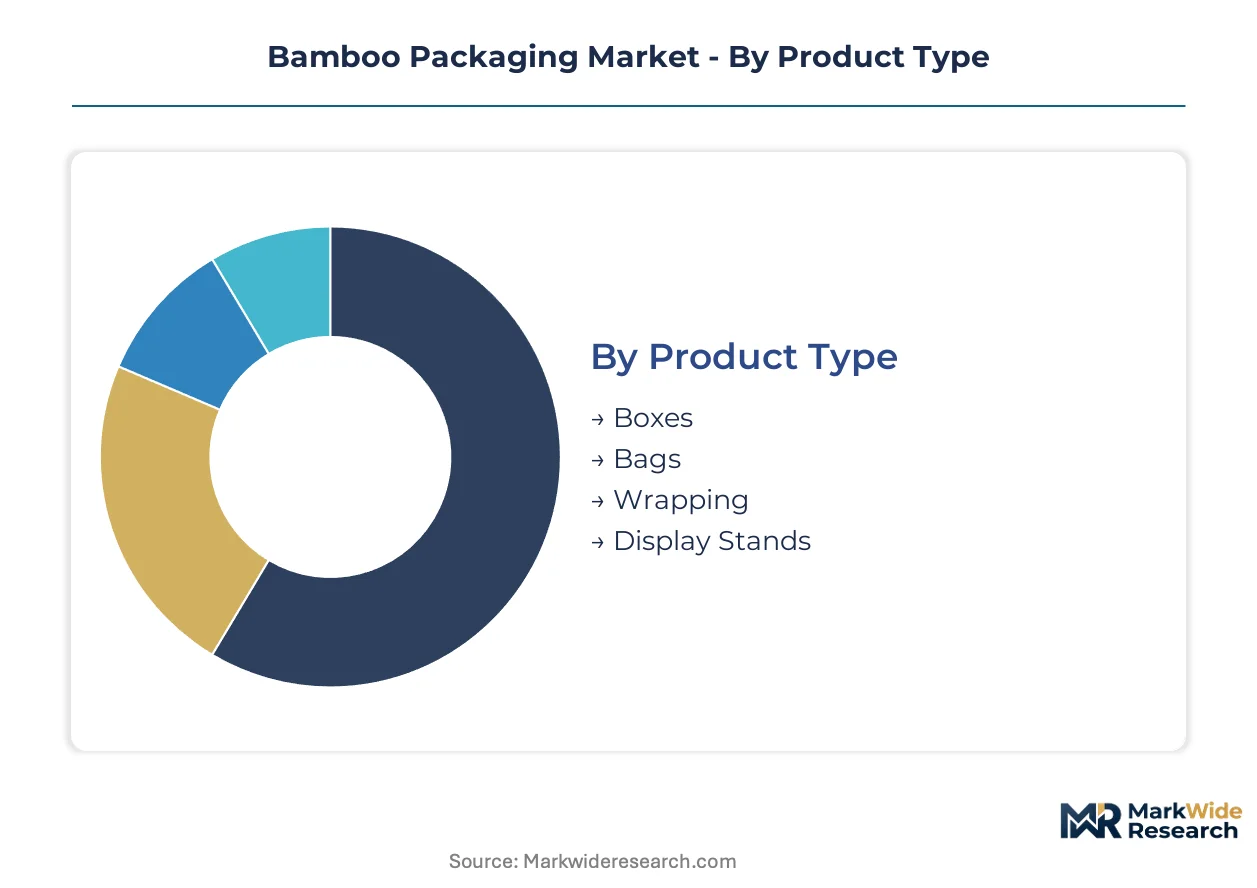
Bamboo packaging segmentation reflects divergent compliance burdens across certification regimes. Product and material-grade splits determine which producers can access premium retail channels versus commodity fulfillment.
Product Type:
EU REACH and FDA food-contact regulations impose divergent testing protocols on each structural format, reshaping export-oriented production allocation.
- Boxes:Engineered fiberboard constructions from mechanically defibrated Phyllostachys edulis culms achieve tensile strengths of 30-50 MPa. Electronics unboxing experiences in South Korea and Germany now specify bamboo molded pulp for premium device launches, displacing expanded polystyrene under landfill-diversion mandates.
- Bags:Woven textile structures derived from Bambusa blumeana fiber serve as primary carriers for cosmetics retail corridors in France and the Netherlands. Batch-level chain-of-custody documentation requirements from Nestlé and Unilever procurement teams compress supplier qualification cycles.
- Wrapping:Thin-gauge sheet applications for protective cushioning in Zhejiang manufacturing clusters.
- Display Stands:Structural POP fixtures for premium retail environments in Western European corridors.
Boxes handle the majority of throughput; bags are expanding most quickly on share.
End Use:
Customer procurement scorecards now mandate carbon footprint data at batch level, concentrating volume with multi-certified converters.
- Food Industry:The deepest demand base sustains compliance-driven substitution as Germany's Packaging Act and California single-use plastic bans compress timelines. Caustic soda pulping refinement enables grease-resistance performance for hot-fill applications previously blocked by water-based coating gaps.
- Cosmetics:Certified biodegradable grades with enzymatic pre-treatment command 3-4x unit economics versus corrugated. French and South Korean brands now specify laccase-mediator refined fiber for rigid box applications.
- Electronics:Calibrated lamination technology extends bamboo board into cushioning specifications for device launches.
- Retail:General merchandise fulfillment through Amazon Frustration-Free Packaging and Shopify carbon-neutral programs.
Food Industry maintains volume dominance; Cosmetics climbs the fastest on margin contribution.
Material Grade:
China's SAMR enforcement of GB/T 38082-2019 forces segregated production lines, extending audit backlogs beyond eight months for export manufacturers.
- Biodegradable:GB/T and EU REACH parallel documentation requirements for food-contact products destined for European markets. Zhejiang province export-oriented manufacturers face the most acute compliance burden.
- Compostable:OK Compost and US BPI protocol divergence on heavy-metal thresholds forces dual certification costs. Premium positioning accelerates as landfill-diversion mandates proliferate across Germany and France.
- Recyclable:Standard fiber recovery streams for non-food contact applications.
- Sustainable:General environmental claims without specific compostability certification.
Compostable captures the steepest expansion trajectory; Biodegradable carries the heaviest documentation load.
Application:
Functional use case determines barrier coating requirements and corresponding chemical input exposure to caustic soda price volatility.
- Packaging:Primary containment functions with direct product contact drive the most stringent FDA and EU REACH compliance. Electronics-grade specifications now achievable through enzymatic pre-treatment reducing lignin retention below 2%.
- Transportation:Secondary protective structures for e-commerce fulfillment bypassing traditional distributor markups.
- Storage:Long-duration warehousing applications with lower barrier performance requirements.
- Marketing:Display and promotional formats prioritizing aesthetic finish over structural load-bearing.
Packaging absorbs the bulk of certification investment; Transportation gains share fastest through direct-to-brand channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb premium pricing for certified compostable grades with minimal elasticity, while procurement teams in India and Vietnam remain acutely price-sensitive on standard fiberboard specifications.
Germany
Food-contact material recertification timelines have compressed to under six months as brand-owners race to meet Packaging Act obligations. The country's national packaging regulator enforces extended producer responsibility schemes that penalize non-compliant suppliers. Bavaria's industrial corridor hosts specification-grade converters supplying Nestlé and Unilever procurement hubs in Switzerland and the Netherlands.
China
Zhejiang and Fujian provinces concentrate sixty percent of global bamboo board capacity, creating procurement gravity for multinational CPG brands. SAMR enforcement of GB/T 38082-2019 biodegradable plastics labeling forces export-oriented manufacturers to segregate production lines by certification grade. Hangzhou-based converters face audit backlogs exceeding eight months for dual GB/T and EU REACH documentation.
United States
California's single-use plastic bans and Amazon's Frustration-Free Packaging program are accelerating direct-to-brand e-commerce fulfillment channels. The EPA and FDA jointly govern food-contact substance safety for bamboo fiber substrates entering interstate commerce. Pacific Northwest manufacturing clusters specialize in electronics-grade molded pulp displacing expanded polystyrene for premium device launches.
France
Cosmetics brands in Île-de-France and Provence-Alpes-Côte d'Azur now specify enzymatically refined fiber for rigid box applications with batch-level carbon footprint data. ANSM and national environmental agencies coordinate enforcement of landfill-diversion mandates across premium retail corridors. Lyon-based design houses source laccase-mediator treated pulp from plantation-controlled supply chains in Central America.
India
Pending FSSAI national standards for food-contact bioplastics create first-mover positioning for certified exporters from Tamil Nadu and Gujarat. The country's food safety regulator is finalizing biodegradable packaging roadmaps that will mirror EU REACH testing protocols. Mumbai-Pune industrial belt converters are upgrading caustic soda pulping lines to meet anticipated grease-resistance specifications for hot-fill applications.
Bamboo Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the bamboo packaging market. Plantation-owning producers with captive fiber supply compete against asset-light converters dependent on spot-market pulp purchases. Two strategic archetypes dominate: upstream-integrated players controlling subtropical biomass assets, and specification-grade engineers serving European premium retail channels. Competitive moves concentrate on backward integration into plantation assets and technology licensing for enzymatic pre-treatment refinement.
Among Dutch design-engineering specialists, MOSO International B.V. occupies a position exemplifying the European specification-grade archetype. EcoPlanet Bamboo Group represents the plantation-integrated model with direct biomass control in Central America. Smith & Fong Co. anchors the calibrated lamination technology segment extending bamboo board performance into electronics cushioning applications. These three companies illustrate how competitive positioning fragments across upstream control, engineering specification, and application-specific performance tiers.
| Leading Market Players |
|---|
| EcoPlanet Bamboo Group |
| Three Bamboo |
| MOSO International B.V. |
| APackaging Group |
| Gidea PAC |
| Bamboo Village Company Limited |
| The Bamboo Company |
| Bloom Eco Packaging |
| Smith & Fong Co. |
| Others |
Value Chain & Pricing Dynamics
Fixed-price annual contracts with take-or-pay provisions dominate procurement between Zhejiang converters and European brand-owners, locking in caustic soda input costs while exposing margin compression when chemical prices swing. This structure concentrates pricing power with plantation-owning integrated producers who control fiber traceability documentation demanded by Nestlé and Unilever procurement teams.
Pricing Analysis
After-sales certification renewal revenue drives lifetime value for converters serving EU REACH and FDA food-contact compliance tiers. Three-tier pricing structure across premium compostable, standard biodegradable, and economy recyclable levels reflects batch-level chain-of-custody documentation burdens. Pricing pressure stems from caustic soda and sulfuric acid volatility swinging input costs quarterly against fixed contract terms. Food industry buyers in Germany and France show minimal price elasticity for certified grades, while Indian procurement teams remain acutely sensitive on standard fiberboard specifications.
Supply Chain Analysis
Inbound logistics costs from Fujian and Zhejiang manufacturing clusters to Rotterdam and Hamburg ports fluctuate with container availability on Asia-Europe trade lanes. Supply concentrates in Chinese provinces controlling sixty percent of global bamboo board capacity, with secondary nodes in Vietnam and Indonesia. Raw material dependencies center on Phyllostachys edulis and Bambusa blumeana culm supply, caustic soda pulping chemicals, and Italian-manufactured defibration equipment. Single-source vulnerability runs through 18-month lead times for German and Italian pulping line manufacturers. Distribution runs through direct-to-brand e-commerce channels bypassing traditional distributor markups under Amazon Frustration-Free Packaging and Shopify carbon-neutral programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as enzymatic pre-treatment technology licensing creates interoperability between plantation-controlled supply and specification-grade European demand. Amazon's Frustration-Free Packaging and similar ecosystem programs are compressing supplier qualification cycles from 24 months to 90 days.
For Market Incumbents: Fortify upstream biomass control through plantation acquisition in Central America and Southeast Asia, securing fiber traceability against emerging asset-light converters dependent on spot-market pulp. Invest in parallel GB/T and EU REACH certification infrastructure to preempt audit backlogs exceeding eight months for export-oriented manufacturers. Capacity addition in Zhejiang and Fujian provinces maintains procurement gravity for multinational CPG brands. For New Entrants and Emerging Players: Differentiate on enzymatic pre-treatment technology for electronics-grade cushioning specifications previously reserved for molded pulp. Target India's pending FSSAI biodegradable packaging roadmap as the most penetrable geography, where national standards for food-contact bioplastics remain undefined. Pursue direct-to-brand e-commerce fulfillment channels around traditional distributor markups as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward plantation-integrated producers with captive Phyllostachys edulis supply and existing multi-certification infrastructure, positioning for long-term viability as landfill-diversion mandates proliferate across Germany and France. Monitor compostability certification reciprocity between European OK Compost and US BPI regimes as the critical inflection signal for market-access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | EcoPlanet Bamboo Group's Central American fiber traceability secures cosmetics-grade supply contracts. |
| Enzymatic Pre-Treatment Technology Licensing | Laccase-mediator systems fragment the technical barrier between bamboo pulp and hardwood kraft specifications. |
| Dual Certification Infrastructure Investment | Parallel GB/T and EU REACH documentation prevents eight-month audit backlogs for Zhejiang exporters. |
| Direct-to-Brand E-Commerce Channel Development | Amazon Frustration-Free Packaging opens bypass channels around traditional distributor markups. |
| Electronics-Grade Calibrated Lamination Capacity | Smith & Fong Co. extends bamboo board performance into device cushioning applications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with bamboo packaging plant managers, procurement leads at multinational CPG brands, regulatory affairs specialists navigating EU REACH and FDA compliance, and sustainability scorecard directors at Nestlé and Unilever; alongside secondary validation from SAMR GB/T standard filings, EU Packaging and Packaging Waste Regulation documentation, customs and trade data from Zhejiang and Fujian export corridors, and SEC 10-K disclosures from publicly traded converters. Bottom-up capacity and shipment estimates were triangulated against top-down demand modeling from end-use industry consumption patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type segmentation, material grade tiers, end-use industry verticals, and regional regulatory cluster patterns. CAGRs were derived from fitted growth curves applied to base-year estimates, with explicit incorporation of caustic soda price volatility assumptions and single-use plastic ban implementation timelines as bamboo packaging-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside continued enforcement of Germany's Packaging Act, China's GB/T 38082-2019 biodegradable labeling requirements, and California single-use plastic restrictions would require recalibration. Forecasts reflect documented assumptions regarding enzymatic pre-treatment adoption rates and compostability certification reciprocity evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market