
 Global Fanfold Corrugated Market | 2026-2036
Global Fanfold Corrugated Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fanfold Corrugated Market Analysis
Southeast Asia is rewriting capacity dynamics in fanfold corrugated supply as Nine Dragons Paper extends its integrated pulp-to-box model across Vietnam and Indonesia. Smurfit Kappa leverages its European recycled fiber network to dominate specialty fanfold grades for automated fulfillment. Pratt Industries anchors North American supply through its 100% recycled containerboard mills, while Mondi Group competes on kraftliner-based fanfold solutions for heavy-duty industrial applications.
Fanfold corrugated consists of continuous accordion-folded sheets of fluted medium sandwiched between linerboards, typically manufactured with flute profiles ranging from A-flute to E-flute and fed in lengths of 50–250 meters for on-demand box making. The format eliminates die-cutting waste and enables just-in-time packaging customization across warehousing and distribution operations. Single wall configurations occupy the highest volume tier for lightweight e-commerce parcels, while double wall grades capture margin pools in electronics and automotive parts protection where stacking strength requirements exceed 32 ECT. Specialty fanfold variants incorporating moisture-resistant or anti-static treatments represent the fastest-expanding segment as pharmaceutical and cleanroom electronics end users tighten material specifications.
The EPA's recycled content standards under the Comprehensive Procurement Guideline shape fiber sourcing compliance for US-based producers, while REACH and the EU Packaging and Packaging Waste Regulation mandate recyclability thresholds and restricted substance limits across European supply chains. China's GB standards for packaging materials, enforced by SAMR, impose heavy metal limits and labeling requirements on export-bound fanfold products. Stakeholders must monitor divergence between regional extended producer responsibility frameworks and fiber certification schemes to avoid compliance fragmentation that could restrict market access or trigger reformulation costs.
Market Dynamics
Automated packaging lines in e-commerce fulfillment centers are compressing box-making cycles and forcing converters toward continuous-feed fanfold formats that eliminate die-cutting waste and enable real-time dimensional customization.
Growth Catalysts
- E-commerce fulfillment automation:Warehouse robotics and auto-boxing machinery require continuous fanfold feed systems that synchronize with pick-and-pack velocities. Fulfillment operators in Germany and the Netherlands are retrofitting lines for on-demand corrugated production.
- REACH and EU Packaging Waste Regulation:Recyclability mandates across EU member states are disqualifying multi-material alternatives and steering shippers toward single-fiber fanfold solutions that qualify for extended producer responsibility credits.
- Flute miniaturization:E-flute and F-flute profiles are penetrating pharmaceutical and electronics packaging where dimensional precision and print quality requirements exceed what traditional RSC boxes deliver.
Market Restraints
- Old corrugated container price volatility:OCC bale costs swing with Chinese import policies and domestic collection rates, compressing converter margins when fiber spikes coincide with fixed-price contract periods.
- Containerboard mill concentration:North American linerboard supply concentrates among a handful of integrated producers, exposing independent fanfold converters to allocation risk during capacity outages or export surges.
- Corrugated plastic substitution:Reusable polypropylene totes and pallets are capturing closed-loop logistics circuits in automotive and beverage distribution, displacing single-trip fanfold applications.
Strategic Opportunities
- Vietnam and Indonesia manufacturing expansion:Southeast Asian electronics assembly and apparel export growth is outpacing domestic box capacity, creating import substitution openings for regional fanfold producers.
- Anti-static and moisture-resistant treatments:Cleanroom electronics and cold-chain pharmaceutical distributors are specifying functionalized fanfold grades that command premium positioning over commodity brown boxes.
- Digital print convergence:Single-pass inkjet systems are hybridizing with fanfold converting lines to enable lot-size-one customization with variable graphics, collapsing minimum order quantities for brand-owner packaging.
Industry Challenges
- Controls engineering talent scarcity:Automated fanfold lines require technicians fluent in servo-driven web handling and HMI programming, skills concentrated among legacy folding carton and flexible packaging specialists.
- Legacy ERP integration friction:Real-time dimensional software must interface with warehouse management systems and carrier rate-shopping APIs, stretching IT resources at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fanfold Corrugated Market |
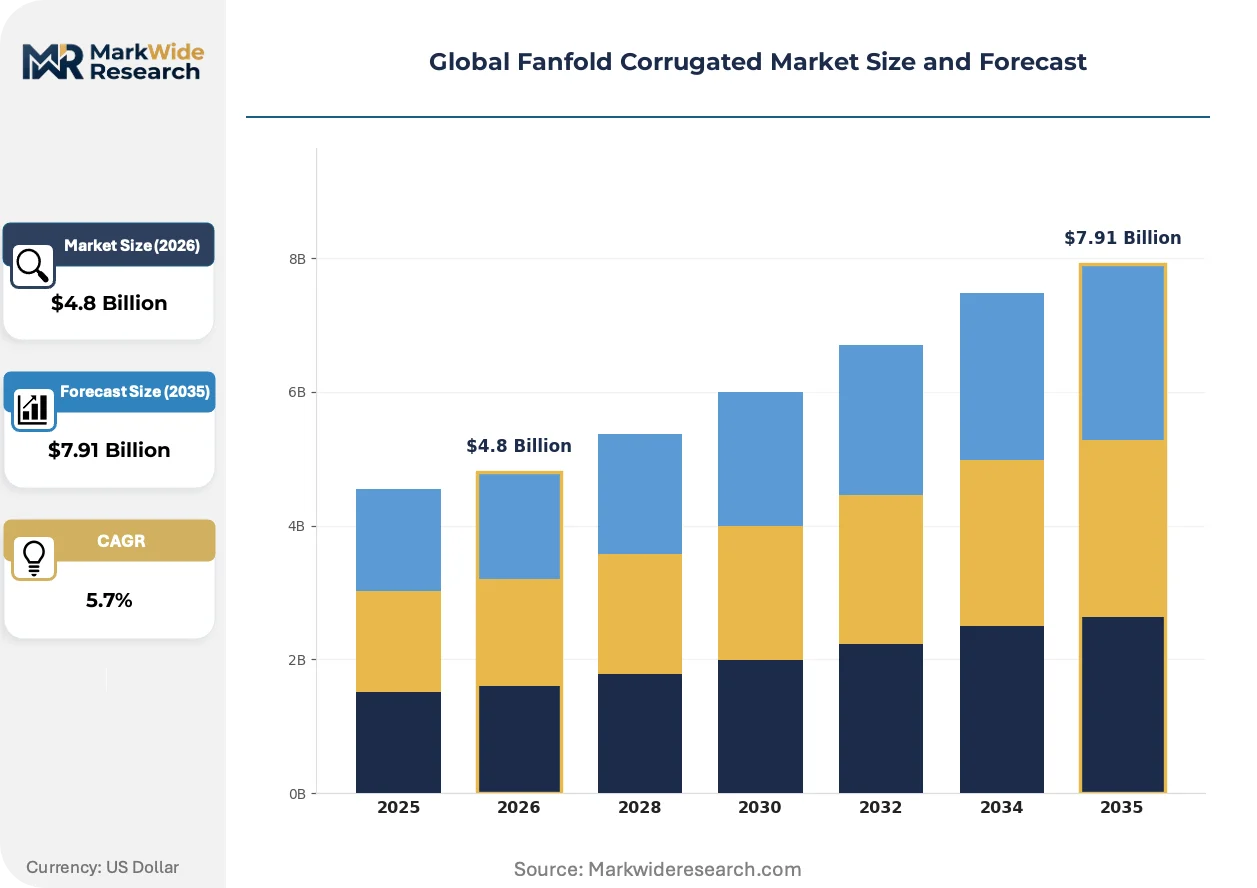
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Specialty Fanfold End User: Retail, Electronics, Food & Beverage, Textile Application: Packaging, Shipping, Display, Protection Size: Standard, Custom, Large Format, Mini |
| Companies Covered | Smurfit Kappa, Nine Dragons Paper, International Paper, Pratt Industries, Packaging Corporation of America, WestRock, Mondi Group, Rondo Ganahl, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fanfold Corrugated Market Emerging Trajectories
Convergence between digital printing, functional coatings, and servo-controlled converting is collapsing production batch sizes while expanding the addressable market for fanfold formats beyond traditional high-volume industrial shipping.
Barrier-coated kraftliner is hybridizing with nanocellulose and bio-wax treatments to deliver grease and moisture resistance without compromising repulpability. Food service and agricultural exporters in California and Florida are adopting these grades for produce and prepared meal applications. The technology is compressing the performance gap between corrugated and plastic alternatives while preserving fiber recovery economics.
The EU Packaging and Packaging Waste Regulation is mandating design-for-recycling criteria and minimum recycled content thresholds that phase in through 2030. Packaging producers serving French and German retail channels are reformulating adhesives and eliminating fluorescent whitening agents to maintain market access. Specialty fanfold grades with certified fiber provenance are capturing shelf-space compliance contracts from multinational brand owners.
Shippers are unbundling box procurement from freight contracts and bringing dimensional optimization in-house. Third-party logistics providers in the US Midwest are installing fanfold converting equipment at sortation hubs to right-size packaging at the point of shipment. This behavior is most visible in parcel networks serving omnichannel retailers, where dimensional weight pricing and sustainability scorecards drive packaging decisions upstream from traditional converter relationships.
Global Fanfold Corrugated Market Segmentation
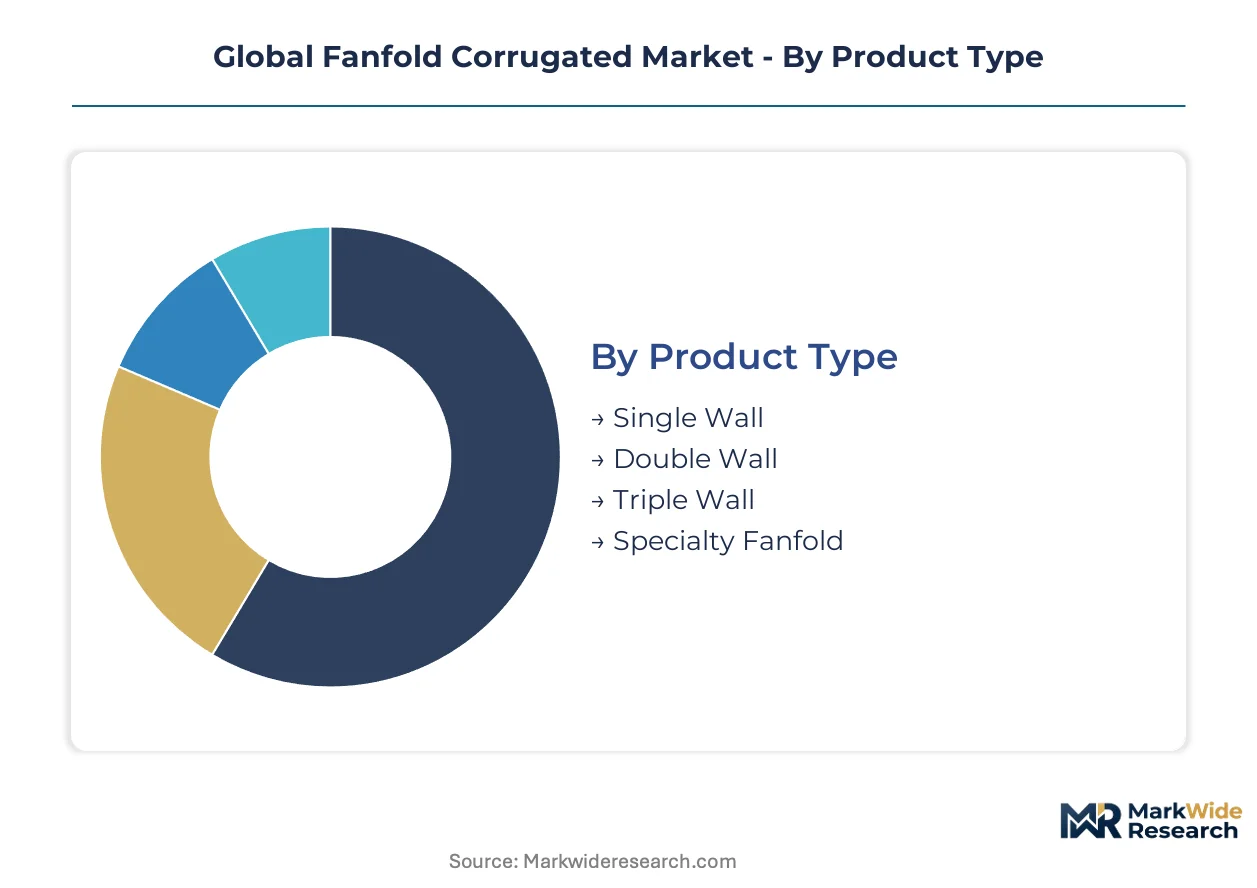
Fanfold corrugated markets fragment across structural configurations, end-use specifications, and dimensional formats. Each segmentation axis carries distinct margin profiles and automation compatibility requirements that shape converter investment priorities.
Product Type:
After-sales service intensity escalates with structural complexity—triple wall installations demand field calibration and web-tension optimization that single wall systems rarely require.
- Single Wall:One fluted medium layer between two linerboards, typically A-flute through C-flute profiles. E-commerce fulfillment centers in Germany and the Netherlands deploy this grade for lightweight parcel automation where dimensional weight pricing drives material minimization.
- Double Wall:Two fluted layers separated by an intermediate liner, combining B-flute and C-flute for stacking strength above 32 ECT. Automotive parts distributors specify this grade for engine component shipments requiring palletized load stability.
- Triple Wall:Heavy-duty configurations with three fluted layers for export machinery and metal fabrication. Field service contracts accompany installations due to precision feed alignment requirements.
- Specialty Fanfold:Functionalized grades incorporating moisture barriers, anti-static treatments, or grease resistance. Cold-chain pharmaceutical distributors and cleanroom electronics manufacturers drive specification tightening.
By volume, single wall leads. By growth pace, specialty fanfold is ahead.
End User:
Cost tier stratification separates commodity brown-box buyers from premium functionalized grade purchasers.
- Retail:Omnichannel operators balance SKU proliferation against packaging standardization. Third-party logistics hubs in the US Midwest install on-demand converting equipment to collapse box-making cycles.
- Electronics:Cleanroom and semiconductor manufacturers specify anti-static fanfold with surface resistivity controls. REACH substance restrictions and ECHA compliance documentation accompany every shipment.
- Food & Beverage:Agricultural exporters in California and Florida adopt barrier-coated kraftliner for produce and prepared meal applications where moisture resistance must not compromise repulpability.
- Textile:Apparel fulfillment networks prioritize lightweight single wall for dimensional weight optimization. Southeast Asian export growth outpaces domestic box capacity in Vietnam and Indonesia.
Electronics commands premium pricing per square meter. Retail moves the highest absolute tonnage.
Application:
Application maturity curves diverge—shipping remains volume-dominant while display applications accelerate with digital print convergence.
- Packaging:On-demand box making at warehouse scale eliminates die-cutting waste. Automated lines synchronize with pick-and-pack velocities in automated fulfillment centers.
- Shipping:Continuous fanfold feed systems dominate high-volume industrial logistics. Automotive and machinery exporters favor this format for palletized freight efficiency.
- Display:Single-pass inkjet hybridization enables lot-size-one customization with variable graphics. Brand owners collapse minimum order quantities for retail-ready presentation.
- Protection:Double and triple wall configurations capture electronics and automotive parts protection where stacking strength requirements exceed standard thresholds.
Shipping generates baseline volume. Display applications are climbing the fastest as digital print hybridization spreads.
Size:
Customer type segmentation separates enterprise fulfillment operators with automated converting capability from mid-tier buyers relying on converter-supplied cut blanks.
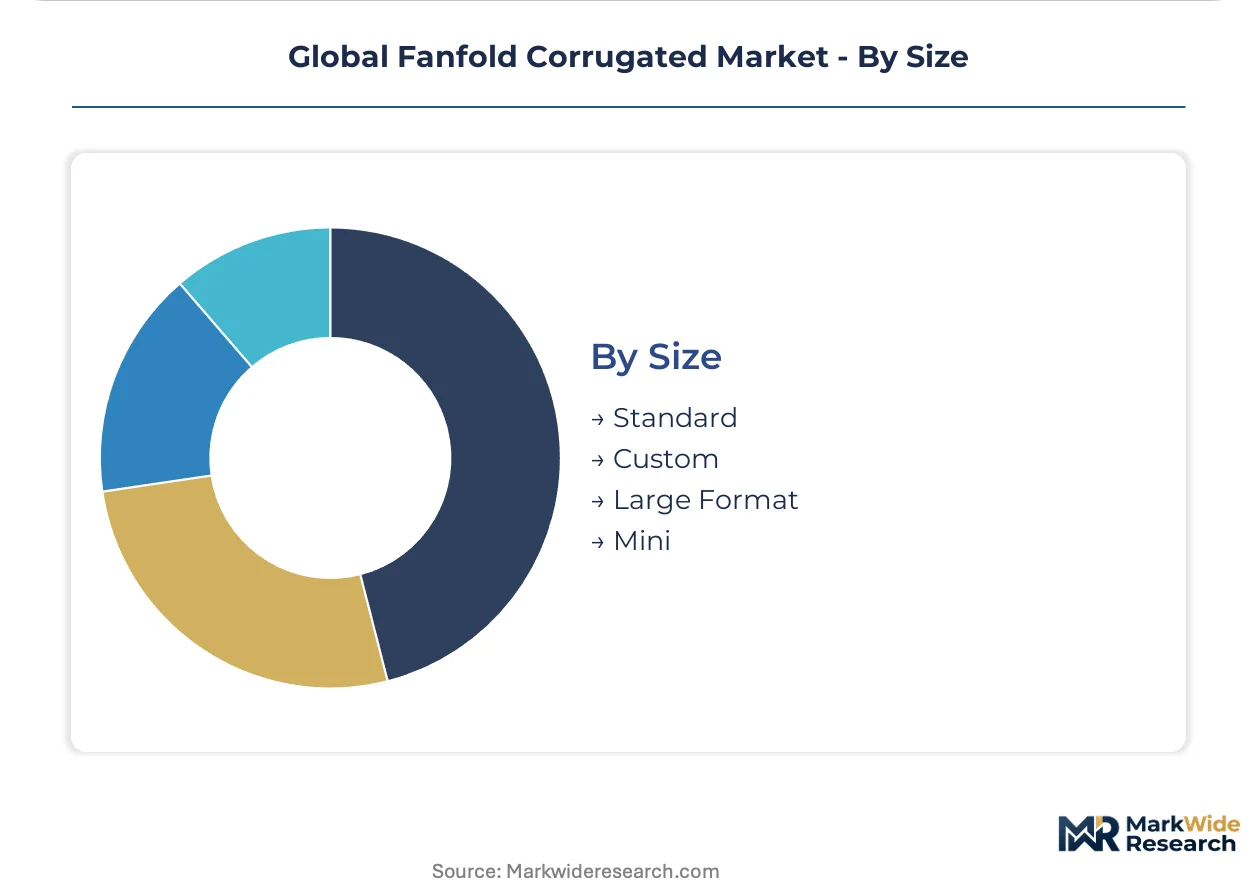
- Standard:Pre-engineered widths and flute profiles for high-velocity automated lines. Major e-commerce operators standardize across distribution networks to minimize SKU complexity.
- Custom:Width and flute combinations engineered to specific product dimensions. Dimensional optimization software interfaces with warehouse management systems at point of shipment.
- Large Format:Extended widths for furniture, appliance, and industrial equipment shipping. Feed system modifications accommodate web handling at scale.
- Mini:Narrow widths for pharmaceutical blister packs and small electronics accessories. E-flute and F-flute profiles penetrate where dimensional precision exceeds traditional RSC capabilities.
Standard sizes dominate procurement volume. Custom formats are gaining share fastest as shippers unbundle box procurement from freight contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Packaging and Packaging Waste Regulation anchor European compliance frameworks, while EPA recycled content standards and China's GB standards shape fiber sourcing requirements across other major production zones.
Germany
Automotive and machinery exporters in Baden-Württemberg and Bavaria drive continuous fanfold feed system installations for high-volume palletized shipping. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that disqualify multi-material alternatives. Stuttgart's industrial corridor concentrates automated packaging line retrofits serving outbound freight to EU and Asian markets.
United States
Third-party logistics hubs across the Midwest install on-demand fanfold converting equipment to right-size packaging at sortation centers. EPA Comprehensive Procurement Guideline standards enforce recycled fiber compliance for federal procurement. Chicago and Detroit distribution clusters lead dimensional optimization adoption among parcel networks serving omnichannel retailers.
China
Export-bound manufacturing in the Yangtze River Delta and Pearl River Delta sustains demand for GB standards-compliant fanfold grades. SAMR enforces heavy metal limits and labeling requirements on packaging materials. Shenzhen and Suzhou electronics assembly corridors specify moisture-resistant and anti-static treatments for semiconductor shipments.
Vietnam
Apparel and electronics export growth outpaces domestic box capacity, creating import substitution openings for regional producers. National technical regulations on packaging materials align with export destination requirements. Ho Chi Minh City and Binh Duong manufacturing zones attract integrated pulp-to-box investments from regional paper groups.
Netherlands
E-commerce fulfillment operators retrofit automated lines for real-time dimensional customization synchronized with pick-and-pack velocities. REACH substance restrictions govern adhesive and coating formulations. Rotterdam's port logistics cluster and Eindhoven's distribution corridor concentrate fanfold deployment for cross-border EU fulfillment.
Global Fanfold Corrugated Market Vendor Landscape
Capability concentration sits with specialty grade developers; scale advantage sits with integrated containerboard producers. The market structures around a consolidated upstream supplying a fragmented downstream converter base. Three archetypes dominate: European recycled fiber specialists, North American integrated producers with captive OCC supply, and Asian integrated pulp-to-box operators expanding across Southeast Asia. Competitive moves center on backward integration into containerboard production and geographic expansion into under-boxed manufacturing zones.
Among European-based operators, Smurfit Kappa and Mondi Group occupy positions within the specialty and kraftliner-grade tiers respectively. Nine Dragons Paper represents the Asian integrated expansion archetype with Vietnam and Indonesia manufacturing footprints. These three entities exemplify the strategic divergence between regional fiber network dominance and cross-border capacity migration.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Nine Dragons Paper |
| International Paper |
| Pratt Industries |
| Packaging Corporation of America |
| WestRock |
| Mondi Group |
| Rondo Ganahl |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Southeast Asian containerboard mills is compressing export pricing while tightening supply discipline among European and North American integrated producers, forcing independent fanfold converters toward longer-term offtake contracts to lock in fiber access.
Pricing Analysis
North American linerboard trades at a premium to European recycled grades due to Pratt Industries' captive OCC supply and EPA Comprehensive Procurement Guideline compliance requirements. Pricing stratifies across premium, standard, and economy tiers based on flute profile complexity and anti-static certification. Cost compression in commodity single-wall grades is intensifying because Chinese import policy swings disrupt OCC bale arbitrage. Mid-tier e-commerce fulfillment operators exhibit highest price sensitivity, while pharmaceutical distributors accept premium positioning for REACH-compliant specialty grades.
Supply Chain Analysis
Integrated containerboard producers including Smurfit Kappa, Mondi Group, and Nine Dragons Paper hold the majority of fanfold-grade capacity across Germany, Vietnam, and the United States. Raw material sourcing draws from recovered paper collection networks, kraftliner pulp supply, and barrier-coating chemical inputs. Single-source vulnerability concentrates in linerboard mill concentration, where allocation risk spikes during export surges or maintenance outages. Distribution runs through converter networks supplying automated fulfillment centers and third-party logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field service contracts for triple-wall fanfold installations and digital print line integration services are expanding faster than base material sales, creating recurring revenue pools that outpace hardware margins.
For Market Incumbents: Harden backward integration into containerboard production to secure fiber supply against OCC price volatility and Chinese import policy shifts. Anchor capacity additions in Vietnam and Indonesia where electronics and apparel export growth outpaces domestic box supply. Certify specialty grades under REACH and EU Packaging and Packaging Waste Regulation thresholds to maintain shelf-space compliance contracts from multinational brand owners. For New Entrants and Emerging Players: Pursue specialty fanfold white space in cold-chain pharmaceutical and cleanroom electronics segments where anti-static and moisture-resistant treatments command premium positioning. Vietnam and Indonesia present the most penetrable geographies given import substitution gaps and national technical regulation alignment with export destinations. Lead with digital print hybridization capabilities to capture lot-size-one customization demand from omnichannel retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated fanfold converting lines as servo-driven web handling and HMI programming requirements escalate. Long-term viability favors targets with established field service organizations and certified specialty grade portfolios. Monitor containerboard mill utilization rates and OCC bale price spreads as inflection indicators for converter margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Production | Captive fiber supply insulates margins from OCC volatility and Chinese import policy swings. |
| Specialty Grade Certification Investment | REACH and EU Packaging Waste Regulation compliance secures shelf-space contracts from German automotive exporters. |
| Southeast Asian Capacity Expansion | Vietnam and Indonesia electronics assembly growth outpaces domestic box capacity, creating import substitution openings. |
| Digital Print Line Hybridization | Single-pass inkjet integration collapses minimum order quantities for omnichannel retail packaging. |
| Field Service Organization Buildout | Triple-wall installations demand precision feed calibration that locks in recurring maintenance revenue. |
Methodological Framework
Initial hypotheses were tested against primary input from containerboard mill operations directors, fanfold converter plant managers, third-party logistics procurement leads, and e-commerce fulfillment automation engineers, and refined through secondary validation against customs trade data, EPA Comprehensive Procurement Guideline filings, SEC 10-K disclosures from integrated producers, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up volume estimates triangulated with top-down market sizing across the analysis window.
Demand-supply balance modeling anchored forecasts, with segmentation dimensions spanning structural configuration, end-use specification, flute profile, and geographic production cluster. CAGRs derived from historical volume trajectories and capacity utilization projections. Key inputs included OCC bale price indices, linerboard mill operating rates, and automated packaging line installation data from fulfillment center operators.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, ocean freight rates, and recovered paper collection economics would shift the trajectory. Forecasts reflect assumptions around regulatory phase-in schedules and fiber certification scheme harmonization. Quarterly review of containerboard mill utilization, OCC price spreads, and automated line retrofit announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market