
 Envelope Market | 2026-2036
Envelope Market Size, Share, and Industry Trends Forecast 2026-2036
Envelope Market Analysis
North American linerboard supply is hardening after years of mill consolidation, tightening substrate availability for envelope converters. Cenveo Corporation leverages its integrated paper procurement network to sustain cost-advantaged production across multiple facilities. Tension Corporation specializes in security and tamper-evident formats, dominating niche government and financial channels. National Envelope Corporation anchors high-volume commercial printing relationships through direct mill partnerships and national distribution infrastructure.
An envelope is a flat, foldable containment vessel manufactured from paper, plastic, kraft, or bubble laminates, typically sealed via gummed adhesive, self-seal latex, peel-and-strip, or metal clasp mechanisms, with standardized dimensions such as DL (110 × 220 mm) and C5 (162 × 229 mm) ensuring compatibility with postal automation systems. Its primary purpose is to protect, conceal, and transport documents, cards, or lightweight goods through postal, courier, or interoffice channels. Paper-based formats retain the largest volume share but face margin compression from fiber cost volatility, while bubble and plastic variants command premium positioning in e-commerce protective mail applications. Closure type differentiation increasingly shapes procurement decisions, with peel-and-seal formats gaining traction in high-speed fulfillment environments where labor minimization drives operational economics.
EPA guidelines on recycled content in federal procurement, FDA indirect food contact standards for kraft mailers, and USPS automation compatibility requirements collectively dictate material selection, dimensional tolerance, and barrier performance specifications across the supply base. The EU Packaging and Packaging Waste Regulation extends extended producer responsibility obligations to cross-border mailers, compelling converters to certify recyclability pathways or face market access restrictions. Stakeholders must monitor evolving postal operator automation specifications and regional extended producer responsibility frameworks to align capital allocation with compliance-locked demand segments.
Market Dynamics
E-commerce fulfillment automation is compressing envelope procurement cycles while the EU Packaging and Packaging Waste Regulation forces material redesign across European converting operations. These dual pressures reward converters with integrated paper sourcing and certified recyclable product lines.
Growth Catalysts
- E-commerce protective mailers:Bubble and kraft-laminated formats capture expanding parcel volume from fulfillment centers requiring damage-resistant lightweight containment. Amazon, Zalando, and regional logistics platforms specify these formats for automated sortation compatibility.
- REACH chemical compliance:EU adhesive and coating formulations meeting ECHA substance restrictions gain preferential access to cross-border mailer contracts. Converters certifying SVHC-free supply chains secure long-term retail and postal procurement agreements.
- Peel-and-seal automation:Self-adhesive closure systems eliminate moisture-activation stations in high-speed inserting equipment. Fulfillment operators in Germany and the Netherlands retrofit lines to accommodate latex-free sealing for allergen-sensitive distribution environments.
Market Restraints
- Linerboard cost volatility:North American mill consolidation has reduced spot market liquidity for kraft and white-top linerboard grades. Envelope converters without captive pulp supply face margin compression during fiber price spikes.
- Plastic film substitution limits:Polyethylene bubble mailers face recyclability certification gaps in EU extended producer responsibility schemes. Postal operators in France and Italy restrict non-certified plastic formats from bulk mail contracts.
- Automation capex concentration:Precision converting equipment for windowed security envelopes requires specialized die-cutting and vision systems. This concentrates production capability among German and Austrian equipment clusters.
Strategic Opportunities
- India e-commerce penetration:Flipkart, Meesho, and Reliance JioMart fulfillment networks lack standardized protective mailer supply. Domestic converters with BIS-certified kraft grades can displace imported bubble formats.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates scope 3 emissions tracking for packaging procurement. Envelope suppliers with verified lifecycle data capture premium positioning in enterprise mailroom contracts.
- Pharma cold-chain expansion:Insulated envelope formats with phase-change liners address temperature-sensitive biologic shipments. Specialty converters integrating thermal barriers meet FDA and EMA distribution requirements for last-mile delivery.
Industry Challenges
- Recyclability certification timelines:EU harmonized assessment protocols for fiber-plastic laminate separation remain under development. Converters await finalized testing standards before committing capital to multi-material production lines.
- Postal automation tolerance drift:USPS and Deutsche Post periodically tighten dimensional and stiffness specifications. Envelope manufacturers must maintain statistical process control across multiple national postal authority requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Envelope Market |
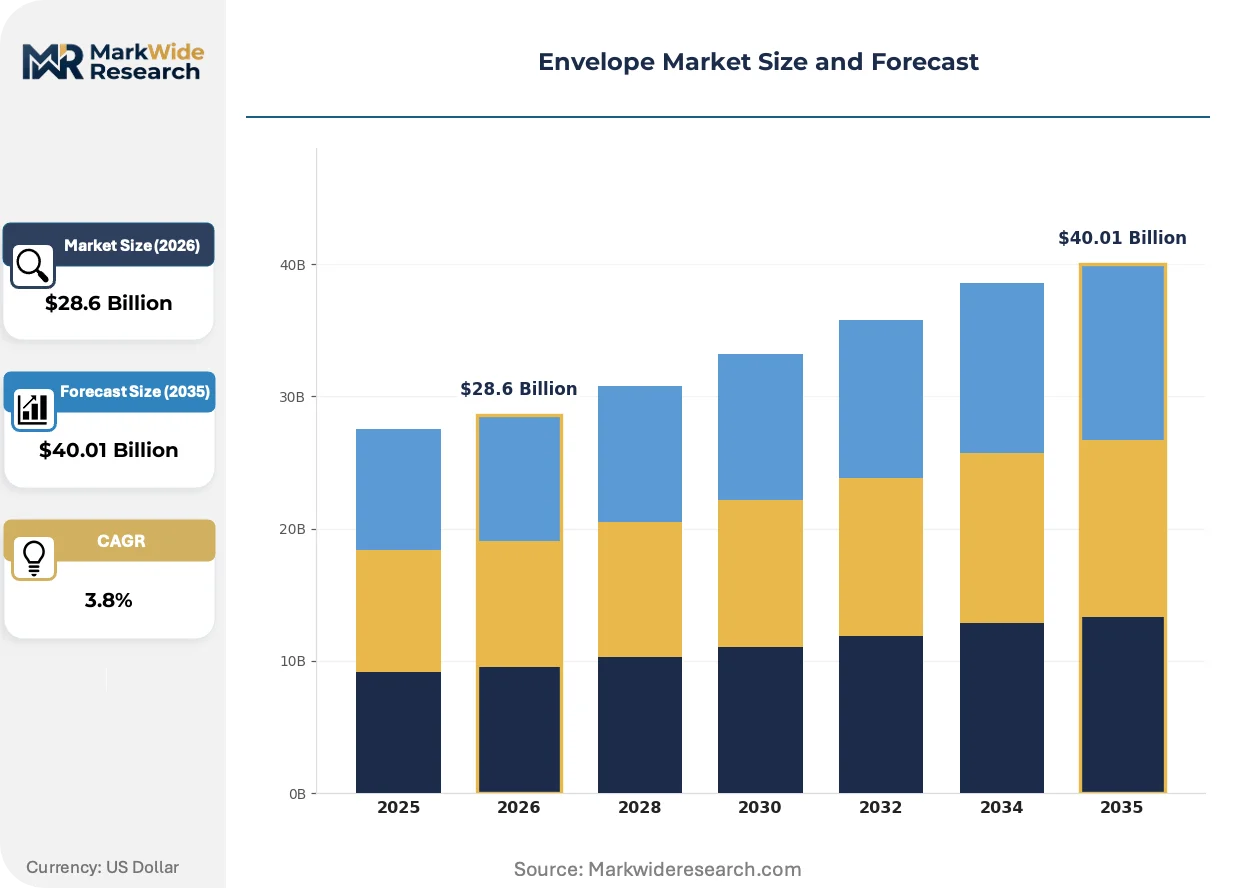
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Kraft, Bubble Closure Type: Self-Seal, Gummed, Peel & Seal, Clasp Size: A1, A2, DL, C5 Application: Business Correspondence, Direct Mail, Packaging, Greeting Cards |
| Companies Covered | National Envelope Corporation, Continental Envelope, Cenveo Corporation, Sheppard Envelope, Victor Envelope Company, Tension Corporation, Mac Papers Envelope Converters, Diamond Envelope Corporation, Double Envelope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Envelope Market Emerging Trajectories
Digital printing integration and material science advances are collapsing minimum order quantities while expanding graphic customization capabilities. These developments reshape converter-customer relationships and equipment investment priorities.
Water-based barrier coatings are unifying grease resistance and moisture protection within single-layer kraft constructions. Quick-service restaurant chains and meal-kit operators specify these formats for food-contact mailers. The technology is unifying previously separate waxed paper and plastic film applications into unified fiber-based solutions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel reformulation of oil-resistant envelope treatments. Converters in Belgium and Sweden pilot silicone and bio-wax alternatives for document protection. Financial and legal mail segments most affected are accelerating supplier qualification for fluorine-free certified supply chains.
Direct-to-brand procurement platforms disintermediate traditional paper merchant distribution for standardized envelope formats. Mid-sized e-commerce merchants in the United Kingdom and Germany now specify custom-printed mailers through digital storefronts rather than regional distributors. This channel compression concentrates volume with converters maintaining web-to-print infrastructure and 48-hour turnaround capability.
Envelope Market Segmentation
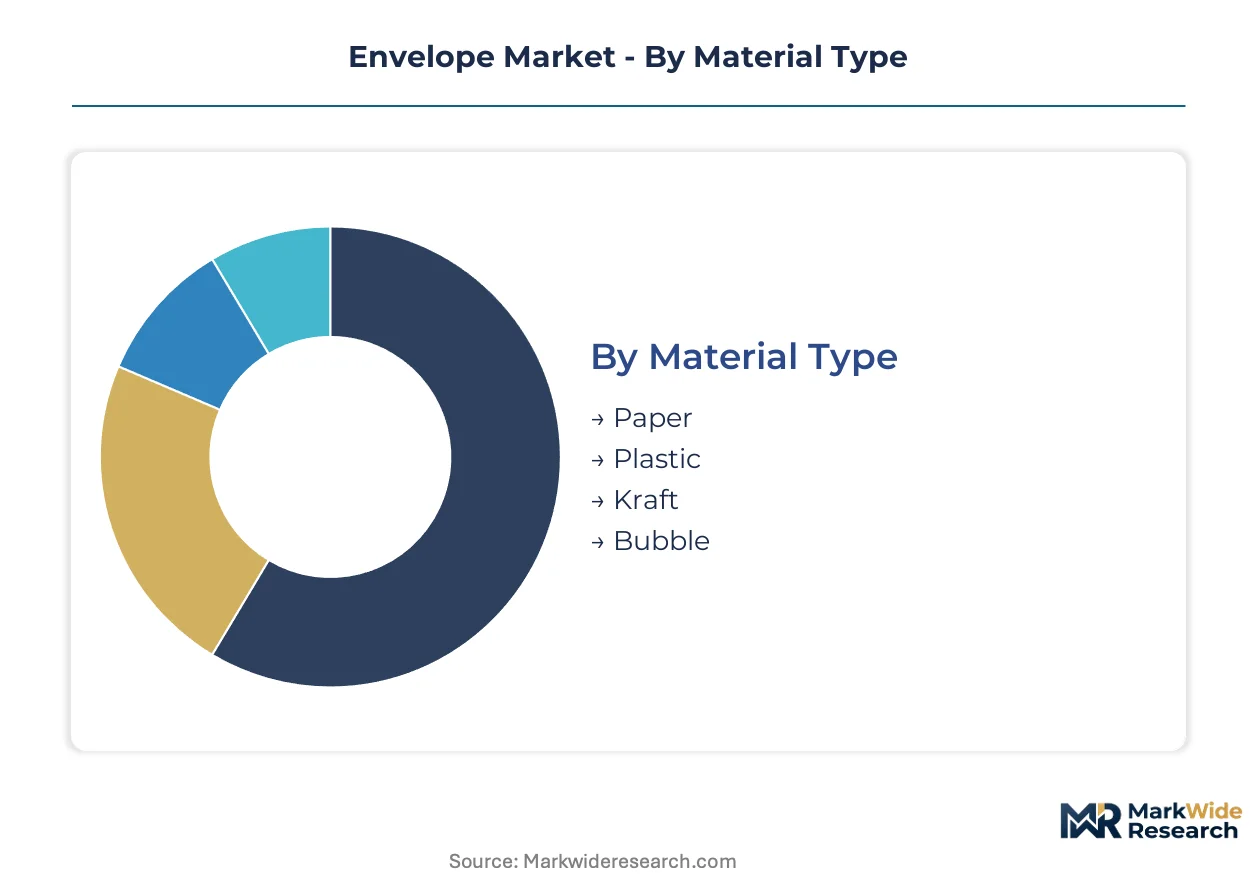
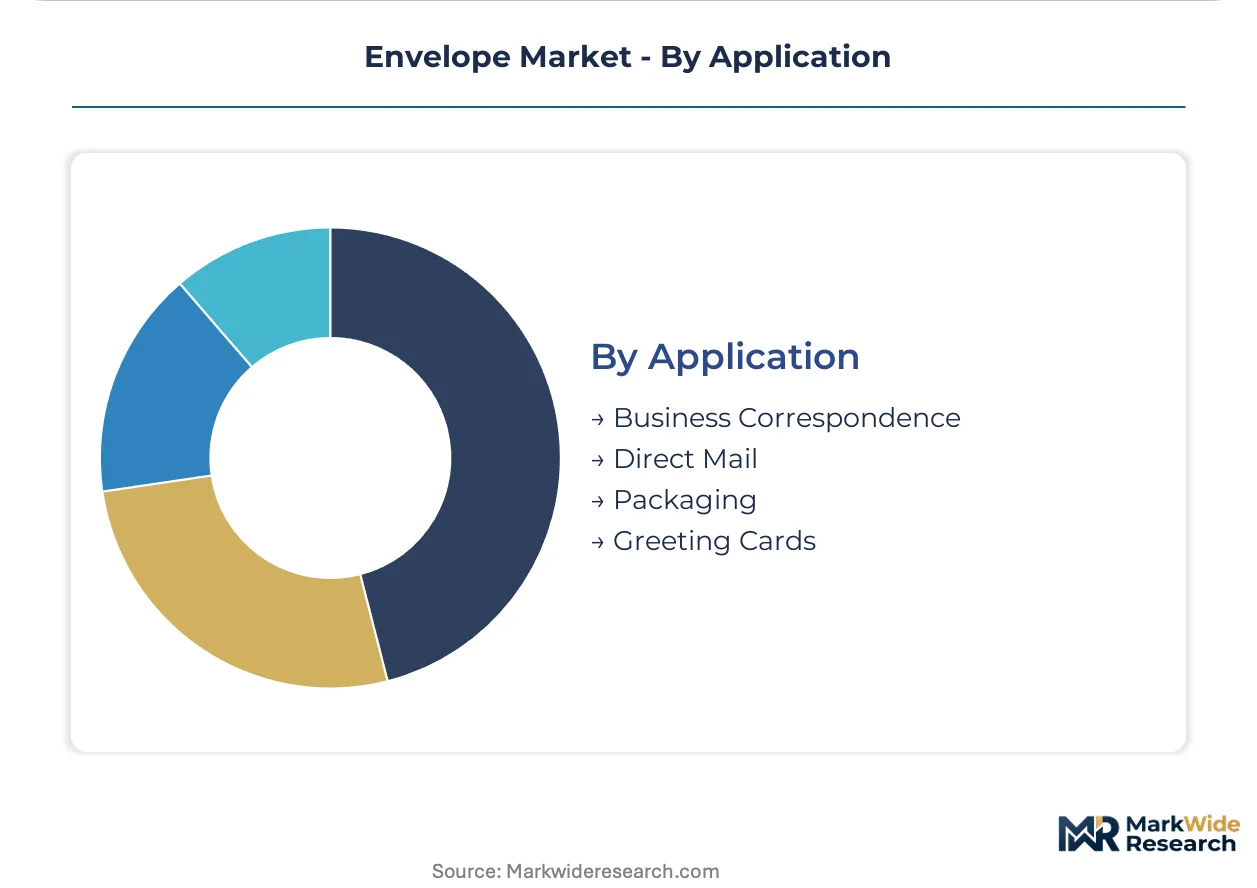
Envelope procurement patterns diverge sharply across material grades and closure systems, with automation compatibility and regulatory compliance driving specification lock-in. Converters must align capacity investments with the segments where postal certification and sustainability mandates concentrate purchasing power.
Material Type:
Capital intensity escalates from commodity paper lines through multi-layer barrier laminates requiring co-extrusion and adhesive bonding stations.
- Paper:Virgin and recycled fiber grades processed on rotary or platen presses dominate high-volume transactional mail. Deutsche Post and USPS automation specifications favor specific basis weights and stiffness calipers that constrain supplier qualification lists.
- Bubble:Polyethylene film laminated to air-cell cushioning demands blown film extrusion and rotary sealing equipment with precision temperature control. E-commerce fulfillment centers in Germany and the Netherlands specify these formats for damage-prone electronics and cosmetics shipments, though EU extended producer responsibility schemes restrict non-certified variants.
- Plastic:Monolayer and co-extruded polyolefin formats serve moisture-critical document protection in humid climates.
- Kraft:Unbleached sulfate pulp constructions with high tear resistance anchor industrial shipping and food-contact applications.
Most installed capacity flows through Paper. Expansion is steepest in Bubble.
Closure Type:
Automation retrofit requirements and labor cost differentials across fulfillment networks determine which sealing technologies capture incremental volume.
- Peel & Seal:Pressure-sensitive adhesive strips protected by silicone-coated release liners eliminate moisture activation and drying stations. High-speed inserting lines at insurance and financial services mailrooms in the United Kingdom and Germany have standardized on this format to achieve throughput targets above 20,000 pieces per hour.
- Self-Seal:Latex-based cohesive coatings on opposing flaps bond under pressure without separate adhesive application. Government procurement channels in France and Belgium mandate latex-free formulations for allergen-sensitive distribution environments, splitting demand between synthetic rubber and hot-melt alternatives.
- Gummed:Dextrin or synthetic resin adhesives requiring moisture activation persist in philatelic and certificate-of-mailing applications.
- Clasp:Metal wire and fiber-reinforced closure systems serve reusable interoffice routing and legal document chains-of-custody.
Procurement volume concentrates in Peel & Seal. Gaining share fastest is Self-Seal.
Size:
Postal authority dimensional tolerances and inserting equipment throat specifications constrain format proliferation despite customization demand.
- DL:The 110 × 220 mm format matches trifold A4 correspondence and dominates European business correspondence. German envelope converting clusters maintain dedicated DL production lines with statistical process control for Deutsche Post's 0.5 mm tolerance requirements.
- C5:The 162 × 229 mm half-A4 format captures folded document mailings and direct marketing campaigns. Austrian and Swiss postal operators specify C5 stiffness thresholds that favor specific fiber blends and corrugation patterns.
- A2:Larger portrait formats serve certificates and photographic prints.
- A1:Maximum dimension envelopes accommodate unfolded legal documents and architectural drawings.
Production runs heaviest on DL. Climbing the fastest is C5.
Application:
End-use concentration in regulated channels versus fragmented merchant demand shapes converter margin structures and certification investments.
- Packaging:Protective mailers for e-commerce parcel substitution require burst strength and puncture resistance certification. Amazon, Zalando, and Otto Group specifications in Germany and the United Kingdom mandate drop-testing and automated sortation compatibility that filter supplier bases.
- Direct Mail:Variable-data printed envelopes for customer acquisition and retention programs demand inkjet-compatible coatings and window positioning precision. Financial services and retail marketers in France and Spain prioritize formats that maximize postal workshare discounts.
- Business Correspondence:Transactional statements and regulatory notices require archival-quality adhesives and opacity standards.
- Greeting Cards:Seasonal demand spikes and premium finishing requirements favor flexible converting arrangements.
Volume concentrates in Packaging. Steepest expansion trajectory sits with Direct Mail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping envelope manufacturing geography as converters migrate toward jurisdictions with lower compliance friction. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility costs that North American facilities currently avoid. This cost-of-compliance gap concentrates investment decisions on certification timelines and material recovery infrastructure.
United States
USPS automation compatibility specifications drive dimensional precision requirements for domestic converters. EPA recycled content guidelines for federal procurement favor suppliers with verified post-consumer fiber sourcing. Midwestern converting clusters around Chicago and Milwaukee maintain legacy capacity for high-volume transactional mail.
Germany
Deutsche Post tolerance standards of 0.5 millimeter deviation filter supplier qualification lists to precision-engineered operations. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel adhesive reformulation across converting lines. The Rhine-Main corridor hosts specialized equipment clusters serving central European distribution networks.
India
Flipkart and Reliance JioMart fulfillment networks generate protective mailer demand lacking standardized domestic supply. BIS certification requirements for kraft grades create entry barriers that favor established paper mills. Gujarat and Maharashtra converting operations expand capacity to displace imported bubble formats.
United Kingdom
Direct-to-brand procurement platforms compress distribution channels for mid-sized e-commerce merchants. CSRD supply chain disclosure mandates scope 3 emissions tracking for enterprise mailroom contracts. Midlands converting facilities retrofit for 48-hour turnaround capability to capture web-to-print volume.
France
ANSM allergen-sensitive distribution requirements split government procurement between latex-free synthetic rubber and hot-melt adhesive alternatives. Postal operators restrict non-certified plastic bubble formats from bulk mail contracts. Lyon and Paris basin converters pilot silicone barrier coatings for fluorine-free document protection.
Envelope Market Vendor Landscape
German and Austrian producers anchor the precision-engineered tier; North American integrated paper networks hold cost-advantaged scale positions. The vendor base splits between mill-linked converters with captive fiber supply and independent specialists serving niche security formats. Three archetypes dominate: integrated paper-procurement operations, security-format specialists, and regional fulfillment-focused converters. Competitive moves concentrate on automated inserting line retrofit partnerships and recyclable material certification pre-positioning.
Within the integrated procurement tier, Cenveo Corporation and National Envelope Corporation exemplify mill-linked scale operations. Tension Corporation occupies the security-format specialist position. These three anchors represent divergent strategic postures: backward integration into paper sourcing, direct postal authority specification compliance, and tamper-evident technology concentration respectively.
| Leading Market Players |
|---|
| National Envelope Corporation |
| Continental Envelope |
| Cenveo Corporation |
| Sheppard Envelope |
| Victor Envelope Company |
| Tension Corporation |
| Mac Papers Envelope Converters |
| Diamond Envelope Corporation |
| Double Envelope |
| Others |
Supply Flow & Price Mechanics
Peel-and-seal automation retrofits across German and Dutch fulfillment centers simultaneously compress converter margins and concentrate volume with equipment-integrated suppliers. This production-method transition rewards capital-heavy operators while squeezing independent converters lacking high-speed inserting line partnerships.
Pricing Analysis
Distributor markups on standardized paper formats run 15-25 points above direct mill partnerships, though e-commerce merchants increasingly bypass both through web-to-print procurement platforms. Three-tier pricing structure across certified recyclable, standard kraft, and commodity paper grades reflects EU extended producer responsibility compliance costs. Pricing pressure stems from linerboard fiber volatility, with spot market spikes compressing margins for non-integrated converters. Small-format transactional mailers exhibit highest price sensitivity, while pharma cold-chain insulated formats command premium positioning with limited buyer elasticity.
Supply Chain Analysis
Direct-to-brand digital storefronts now handle mid-sized e-commerce merchant demand, disintermediating traditional paper merchant networks. Raw material supply concentrates in Germany, Austria, and the United States, with precision-engineered converting clusters anchored in the Rhine-Main corridor. Kraft pulp, polyethylene film, and pressure-sensitive adhesives constitute critical input dependencies. Single-source vulnerability runs through North American linerboard mill consolidation, where reduced spot liquidity amplifies cost volatility. Distribution runs through postal-certified converter networks with Deutsche Post and USPS automation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The envelope market functions as a stable compounder anchored by e-commerce fulfillment automation, with protective mailer demand compounding steadily regardless of macro cycles.
For Market Incumbents: Deploy certification pre-positioning as the primary defensive lever. Secure EU harmonized recyclability protocols ahead of finalized testing standards to lock in retail procurement contracts. Deepen captive paper sourcing through direct mill partnerships in Germany and the Midwestern United States to insulate against linerboard spot volatility. Counter emerging web-to-print disintermediation by acquiring 48-hour turnaround capability.
For New Entrants and Emerging Players: Begin with BIS-certified kraft production for India's Flipkart and Reliance JioMart fulfillment networks, where standardized domestic supply remains underdeveloped. Target pharma cold-chain insulated formats as the most penetrable premium segment, given FDA and EMA distribution requirements that filter incumbent qualification lists. Pursue direct-to-brand digital storefront relationships rather than traditional merchant distribution.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent regional converters lacking postal automation certification or captive fiber supply. Long-term viability favors integrated operations with verified lifecycle data for CSRD scope 3 disclosure compliance. Monitor EU harmonized recyclability protocol finalization as the critical inflection signal for multi-material production line capital commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Recyclability Certification Pre-Positioning | Secures preferential access to EU extended producer responsibility-locked retail contracts. |
| Backward Integration into Paper Sourcing | Insulates margin structures from North American linerboard spot market volatility. |
| Peel-and-Seal Automation Retrofit Partnerships | Captures high-volume insurance and financial services mailroom procurement in Germany. |
| Direct-to-Brand Digital Storefront Launch | Disintermediates traditional merchant distribution for mid-sized UK and German e-commerce volume. |
| Pharma Cold-Chain Thermal Barrier Integration | Addresses FDA and EMA requirements for temperature-sensitive biologic last-mile delivery. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Primary interviews incorporated envelope converting plant managers, procurement leads at Amazon and Zalando fulfillment networks, postal authority specification engineers, and paper mill sales directors. Secondary sources included Deutsche Post automation tolerance documentation, EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation drafts, customs trade data for kraft linerboard grades, and SEC filings from publicly traded paper companies. Bottom-up volume modeling across material grades and closure types was cross-checked against top-down macro envelope consumption estimates.
Granularity-level modeling captured material type, closure system, size format, and end-use application dimensions at the country level. CAGRs were derived from segment-level volume trajectories weighted by postal automation retrofit timelines and e-commerce penetration curves. Industry-specific forecast inputs included fulfillment center expansion pipelines from major logistics platforms and evolving national postal authority dimensional tolerance specifications.
Several conditions sit outside the modeled scope, including sudden shifts in pulp fiber commodity markets, unilateral postal rate restructuring, and acceleration of paperless document substitution beyond historical trend rates. Forecasts reflect documented assumptions regarding EU regulatory timeline adherence and e-commerce fulfillment automation adoption curves. Periodic stress-testing of base assumptions is recommended against linerboard spot price volatility and postal operator specification drift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
GCC Paper Packaging Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market