
 Disposable Icepacks Market | 2026-2036
Disposable Icepacks Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Icepacks Market Insights
Polymer chemistry expertise is bifurcating the competitive landscape as formulators with in-house gel engineering capabilities pull ahead of commodity assemblers. Cardinal Health leverages its healthcare distribution network to sustain institutional contract density across hospital systems. Cryopak specializes in temperature-assurance design for biopharmaceutical cold chain, occupying a defensible niche in validated shipping systems. Cold Chain Technologies anchors North American production capacity for phase-change materials, competing on lot-size flexibility and regulatory documentation support.
Disposable icepacks are single-use temperature-control devices comprising sealed polymer bladders filled with phase-change gels, dry ice sublimation cells, or endothermic reaction chemicals; polyethylene and PVC films typically form the outer barrier, with gel-based formulations employing superabsorbent polymers or saline solutions engineered to maintain target temperatures for defined durations. These devices serve commercial applications spanning injury treatment, perishable food preservation, and pharmaceutical cold chain logistics where precise thermal management prevents product degradation. Instant cold packs lead volume in sports and emergency care channels due to convenience and no preconditioning requirements, while gel packs command margin pools in healthcare and biopharma logistics where temperature validation documentation carries compliance value. Dry ice packs represent the fastest-growing format for frozen vaccine and cell therapy distribution, though handling complexity limits adoption beyond specialist logistics providers.
FDA 21 CFR Part 211 guidelines govern pharmaceutical cold chain packaging validation, while EPA Resource Conservation and Recovery Act provisions shape end-of-life disposal pathways for gel and chemical contents; OSHA hazard communication standards additionally influence workplace handling protocols for dry ice variants. The EU MDR and REACH frameworks apply to polyethylene and PVC material sourcing for devices entering European healthcare channels, creating dual compliance burdens for multinational suppliers. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States, as California and New York advance packaging waste rules that could mandate recyclable or biodegradable film substitutions ahead of federal action.
Market Dynamics
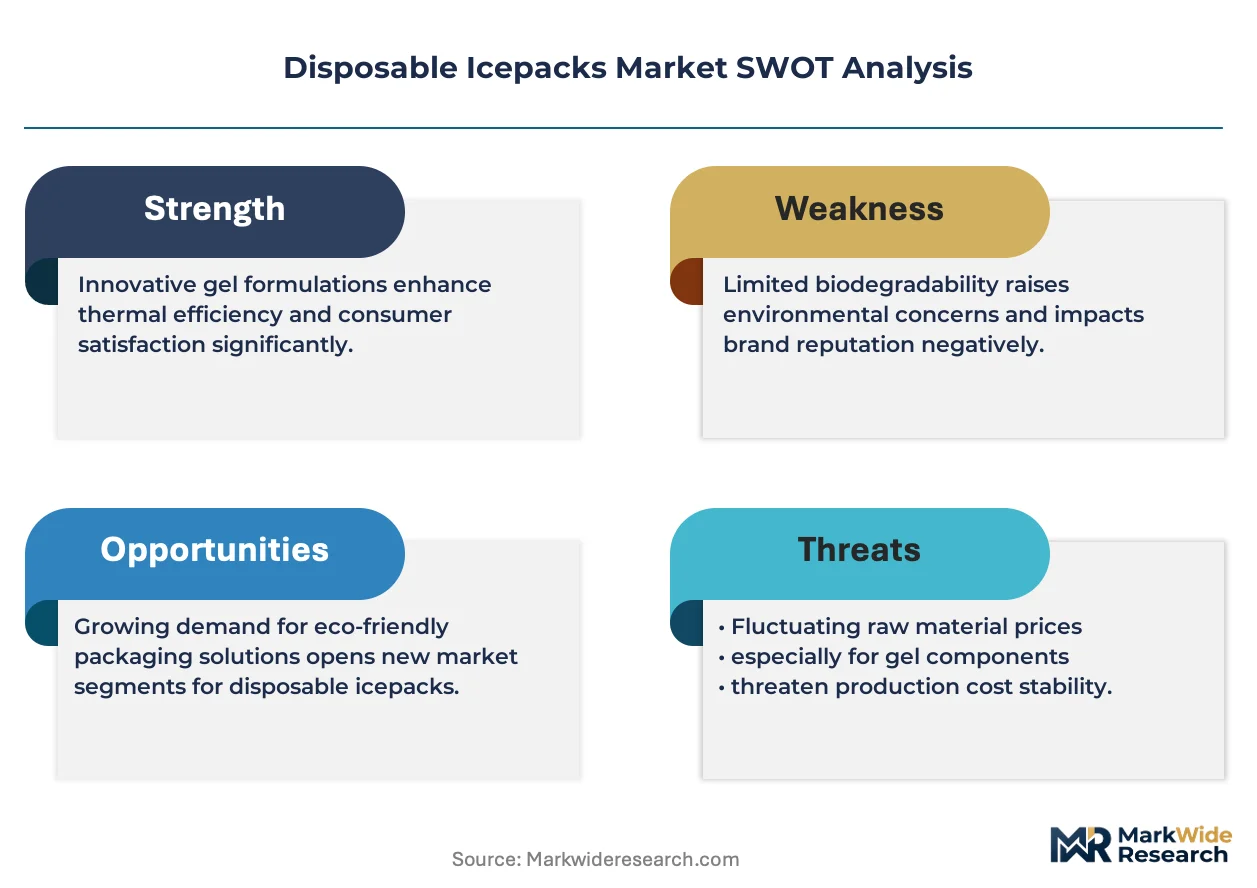
Polymer chemistry capabilities are concentrating competitive advantage among formulators with in-house gel engineering, while cold chain logistics providers demand validated temperature-assurance documentation that commodity assemblers cannot supply.
Growth Catalysts
- Biopharmaceutical cold chain expansion:Cell therapy and mRNA vaccine distribution networks require precise thermal management for last-mile delivery, pulling demand for phase-change gel formats with validated performance documentation.
- EPA material safety tightening:Non-toxic gel formulation standards under Resource Conservation and Recovery Act provisions are accelerating substitution of legacy chemical packs in United States healthcare procurement.
- Food delivery platform consolidation:Meal-kit and perishable grocery channels are standardizing instant cold pack specifications for subscriber retention and spoilage reduction.
Market Restraints
- Polyethylene film cost volatility:Resin price fluctuations and supply tightness from petrochemical feedstock disruptions compress margin pools for high-volume pack assemblers.
- Dry ice handling complexity:OSHA hazard communication requirements and sublimation management limitations restrict adoption beyond specialist pharmaceutical logistics providers with trained personnel.
- PVC regulatory pressure:REACH restrictions on plasticizer content in European healthcare channels create dual formulation burdens for multinational suppliers serving multiple jurisdictions.
Strategic Opportunities
- Biodegradable film substitution:California and New York extended producer responsibility legislation is creating first-mover advantage for suppliers with compostable barrier materials ahead of federal packaging waste rules.
- Cell therapy logistics specialization:Cryogenic and ultra-low temperature formats for CAR-T and gene therapy distribution represent underpenetrated white space beyond standard gel pack performance envelopes.
- Retail pharmacy channel expansion:Vaccine administration at drugstore chains and urgent care clinics is opening direct procurement relationships bypassing traditional hospital supply aggregators.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation scientists with phase-change material expertise command premium compensation, constraining R&D velocity for mid-cap competitors.
- Validation documentation intensity:FDA 21 CFR Part 211 compliance for pharmaceutical cold chain packaging requires extensive stability testing that extends product development timelines.
- Legacy equipment integration:Automated filling and sealing systems for novel biodegradable films demand capital reconfiguration incompatible with existing polyethylene production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Icepacks Market |
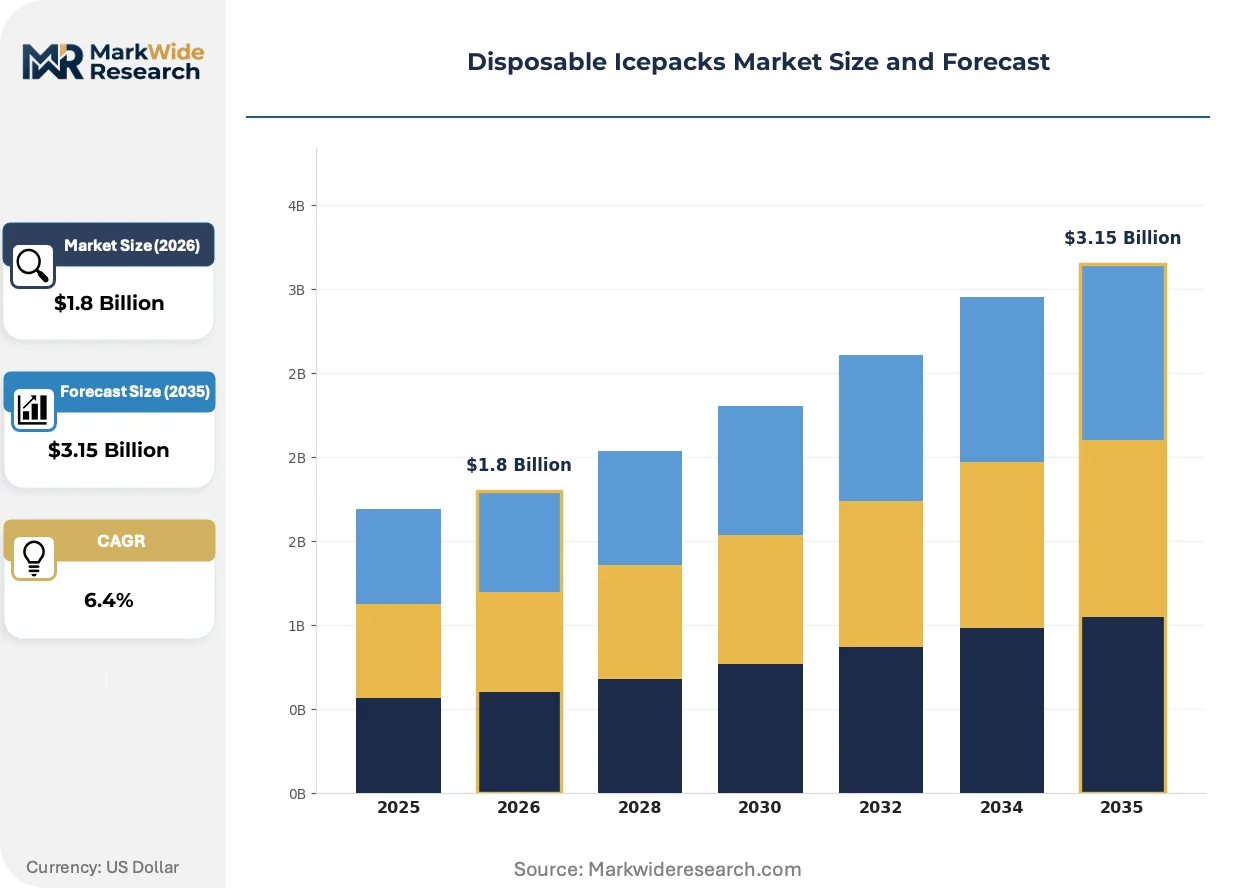
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Packs, Dry Ice Packs, Instant Cold Packs, Reusable Ice Packs End User: Healthcare Facilities, Sports Teams, Food Delivery Services, Retail Providers Material: Polyethylene, PVC, Gel-Based, Non-Toxic Components Application: Injury Treatment, Food Preservation, Cold Chain Logistics, Emergency Care |
| Companies Covered | Cardinal Health, TECHNI ICE, Arctic Ice LLC, 3M Co., Cryopak, Cold Chain Technologies, Dynarex, INTCO Medical, ThermoSafe Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Icepacks Market Trends and Innovations
Active materials science and regulatory chemistry are converging to redefine performance benchmarks, while procurement sophistication among institutional buyers is compressing switching costs between suppliers.
Superabsorbent polymer gel formulations with tunable phase-change temperatures are displacing saline-based alternatives in pharmaceutical cold chain applications. Biopharmaceutical third-party logistics providers are specifying these materials for validated shipping lane qualification. The technology is displacing commodity gel packs from high-margin healthcare contracts where temperature excursion documentation carries compliance liability.
REACH framework amendments on microplastic release and end-of-life disposal pathways are reshaping material sourcing decisions for devices entering European healthcare channels. Suppliers must now document polymer biodegradation profiles and recycling stream compatibility alongside traditional performance metrics. Small-format instant cold packs for retail pharmacy distribution face the most acute reformulation pressure under these provisions.
Hospital systems and integrated delivery networks are consolidating temperature-assurance procurement through sole-source agreements with validated packaging partners. Group purchasing organizations are unbundling cold chain components from broader medical-surgical contracts, creating direct negotiation relationships with specialized gel pack formulators. This pattern is most visible in United States metropolitan health systems with centralized pharmacy operations and internal courier networks.
Disposable Icepacks Market Segmentation
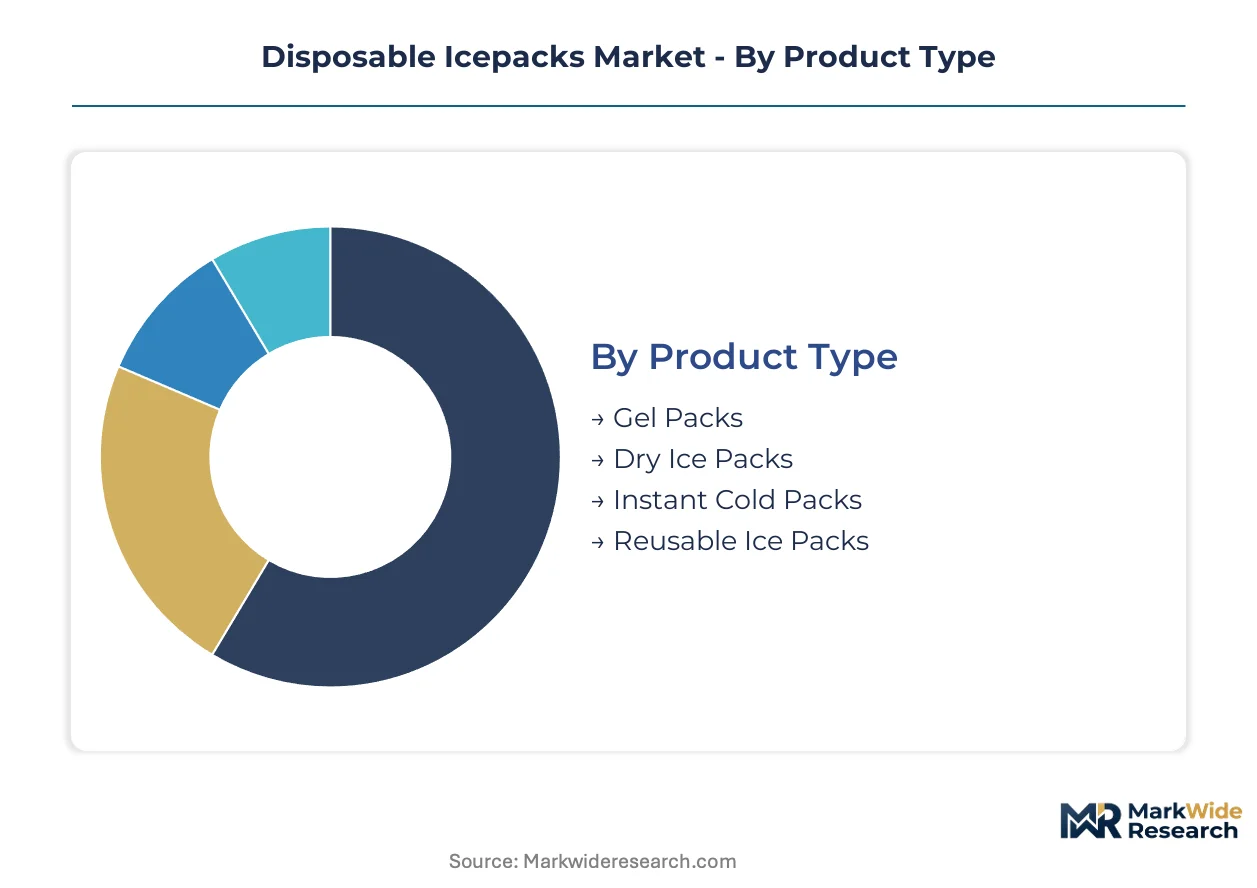
Segmentation in the disposable icepacks market reveals how polymer chemistry capabilities and regulatory compliance documentation concentrate margin pools away from commodity assemblers. Understanding these divides helps identify where formulation expertise commands pricing power versus where volume scale dominates procurement decisions.
Product Type:
Gel packs capture the deepest margin pools due to pharmaceutical validation requirements, while instant formats compete on convenience premiums in consumer channels.
- Gel Packs:Sealed polymer bladders containing superabsorbent polymer or saline-based phase-change gels engineered for precise thermal maintenance. Hospital systems and biopharmaceutical third-party logistics providers in the United States specify these for FDA 21 CFR Part 211 compliant cold chain documentation, where temperature excursion liability justifies material cost premiums.
- Dry Ice Packs:Sublimation cells utilizing solid carbon dioxide for ultra-low temperature maintenance in frozen vaccine and cell therapy distribution. Specialist pharmaceutical logistics providers with OSHA-trained personnel drive demand, though handling complexity restricts adoption beyond validated shipping lanes for CAR-T therapies.
- Instant Cold Packs:Endothermic reaction devices requiring no preconditioning, activated by mechanical disruption of internal chemical chambers. Sports medicine and retail pharmacy channels prize the convenience factor.
- Reusable Ice Packs:Durable-phase material formats designed for multiple freeze-thaw cycles, competing on per-use economics against single-use alternatives in institutional settings with established cold storage infrastructure.
Gel packs hold installed capacity across pharmaceutical contracts. Dry ice packs are rotating up the share rankings in cell therapy logistics.
End User:
Healthcare procurement sophistication is splitting the customer base between institutions demanding validation documentation and volume buyers prioritizing unit economics.
- Healthcare Facilities:Hospital systems and integrated delivery networks with centralized pharmacy operations. These buyers unbundle temperature-assurance procurement from broader medical-surgical contracts, creating direct negotiation relationships with specialized formulators who can supply FDA-compliant stability documentation.
- Food Delivery Services:Meal-kit platforms and perishable grocery subscription services standardizing instant cold pack specifications. Subscriber retention metrics and spoilage reduction targets drive procurement decisions toward reliable single-use formats.
- Sports Teams:Professional and amateur athletic organizations utilizing instant cold packs for sideline injury management. Convenience and rapid deployment override cost considerations in this segment.
- Retail Providers:Drugstore chains and urgent care clinics administering vaccines and handling minor trauma. This channel opens direct procurement relationships that bypass traditional hospital supply aggregators.
Healthcare facilities anchor contract density. Food delivery services are climbing the fastest as platform consolidation standardizes packaging specifications.
Material:
Regulatory pressure on end-of-life disposal is reshaping material selection criteria, with REACH and emerging state-level extended producer responsibility legislation forcing formulation pivots.
- Polyethylene:The dominant barrier film for gel pack outer layers, valued for heat-seal reliability and moisture resistance. California and New York packaging waste rules are pressuring suppliers toward recyclable or biodegradable alternatives ahead of federal action.
- Gel-Based:Superabsorbent polymer formulations with tunable phase-change temperatures displacing saline alternatives. EPA Resource Conservation and Recovery Act non-toxic standards accelerate substitution of legacy chemical packs in United States healthcare procurement.
- PVC:Alternative barrier film with distinct heat-seal characteristics, facing REACH restrictions on plasticizer content in European healthcare channels. Multinational suppliers bear dual formulation burdens serving multiple jurisdictions.
- Non-Toxic Components:Formulation specifications governing gel chemistry and reaction chemicals to meet workplace safety and environmental disposal standards. OSHA hazard communication requirements influence handling protocols.
Polyethylene holds installed capacity across high-volume production lines. Gel-based materials are gaining share fastest as pharmaceutical validation requirements tighten.
Application:
Cold chain logistics commands the most stringent performance specifications, while injury treatment and emergency care prioritize speed of deployment over thermal precision.
- Cold Chain Logistics:Temperature-controlled distribution for pharmaceuticals, biologics, and perishables requiring documented thermal performance. Biopharmaceutical third-party logistics providers specify phase-change materials for validated shipping lane qualification, where excursion documentation carries compliance liability.
- Injury Treatment:Immediate cooling therapy for musculoskeletal trauma and post-surgical recovery. Sports medicine and physical therapy channels drive volume for instant formats requiring no preconditioning.
- Food Preservation:Maintenance of safe temperature zones for perishable goods during transport and temporary storage. Meal-kit and grocery delivery platforms standardize specifications to reduce spoilage and protect subscriber retention.
- Emergency Care:Pre-hospital and acute care settings requiring rapid cooling intervention. First responder kits and emergency department protocols favor instant activation and disposable hygiene.
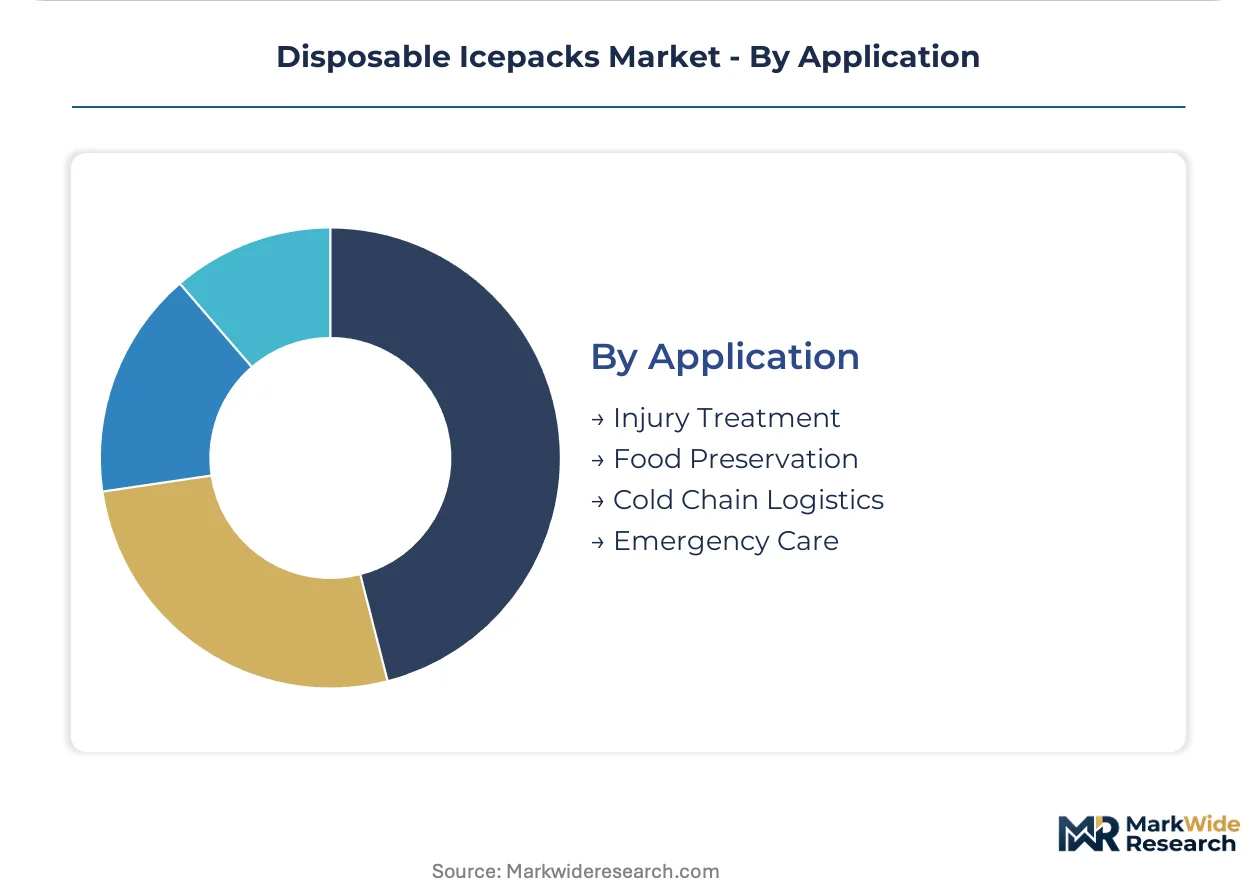
Cold chain logistics holds installed capacity across validated pharmaceutical contracts. Emergency care is rotating up the share rankings as urgent care clinic expansion broadens the addressable channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and EPA standards in the United States anchor regulatory gravity for disposable icepacks, with state-level extended producer responsibility legislation in California and New York now forcing material pivots ahead of federal packaging waste rules.
United States
Hospital systems and biopharmaceutical third-party logistics providers drive concentrated procurement volume. FDA 21 CFR Part 211 guidelines govern pharmaceutical cold chain packaging validation, requiring extensive stability documentation. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical logistics hubs concentrate validated gel pack demand for cell therapy distribution networks.
Germany
REACH framework amendments on microplastic release reshape material sourcing for healthcare channels. ECHA restrictions on plasticizer content in PVC barrier films create dual formulation burdens for suppliers serving European markets. The Rhine-Ruhr industrial belt hosts specialized polymer chemistry operations tuning superabsorbent gel formulations for pharmaceutical compliance.
China
Domestic cold chain infrastructure expansion pulls demand for instant and gel-based formats in perishable food logistics. NMPA pharmaceutical packaging standards increasingly align with FDA thermal validation protocols for export-oriented biopharma manufacturers. The Yangtze River Delta cluster concentrates polyethylene film production and automated filling equipment manufacturing.
India
Vaccine distribution networks and expanding retail pharmacy chains generate volume for single-use temperature-control devices. CDSCO medical device regulations and FSSAI food safety standards create overlapping compliance requirements for dual-use pack suppliers. The Mumbai-Pune pharmaceutical corridor and Bangalore biotech cluster drive specialized cold chain procurement.
Japan
Aging demographics and home healthcare expansion sustain demand for instant cold packs in retail pharmacy channels. PMDA quality management system requirements for medical device packaging extend development timelines for new entrants. The Osaka-Kobe industrial zone maintains precision polymer processing capabilities for phase-change material formulations.
Disposable Icepacks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer chemistry capabilities concentrating advantage among formulators with in-house gel engineering. The market structure separates healthcare-validated suppliers from commodity assemblers serving consumer channels. Three archetypes dominate: integrated healthcare distributors, cold chain technology specialists, and scale-driven polymer converters. Competitive moves center on sole-source hospital system contracts and biodegradable film substitution ahead of regulatory deadlines.
Within the integrated healthcare tier, Cardinal Health exemplifies institutional contract density through distribution network leverage. Cold chain technology specialists include Cryopak and Cold Chain Technologies, occupying positions where validated temperature-assurance documentation commands compliance premiums. These three anchors represent distinct competitive vectors: healthcare distribution integration, pharmaceutical logistics specialization, and phase-change material production scale.
| Leading Market Players |
|---|
| Cardinal Health |
| TECHNI ICE |
| Arctic Ice LLC |
| 3M Co. |
| Cryopak |
| Cold Chain Technologies |
| Dynarex |
| INTCO Medical |
| ThermoSafe Solutions |
| Others |
Pricing and Supply Chain Analysis
FDA 21 CFR Part 211 validation requirements gate both supplier qualification and price differentiation in pharmaceutical cold chain procurement, compressing margin pools for commodity assemblers while rewarding formulators with in-house gel engineering capabilities.
Pricing Analysis
Geographic price spreads widen between United States healthcare contracts and Asian food logistics procurement, with FDA-compliant gel packs commanding material cost premiums against instant formats. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical documentation from commodity convenience packs. Cost compression in high-volume polyethylene formats is intensifying because resin price volatility from petrochemical feedstock disruptions squeezes assembler margins. Hospital systems with centralized pharmacy operations demonstrate lowest price sensitivity, while meal-kit platforms prioritize unit economics above performance specifications.
Supply Chain Analysis
Inventory lead times for superabsorbent polymer feedstocks extend development timelines for novel biodegradable film formulations. Manufacturing gravity centers on China for polyethylene film production and automated filling equipment, the United States for pharmaceutical-grade gel compounding, and Germany for REACH-compliant barrier material engineering. Raw material sourcing draws from petrochemical resin streams, SAP chemical intermediates, and dry ice sublimation cells. Single-source vulnerability concentrates in specialized phase-change material formulators with FDA validation histories. Distribution runs through healthcare group purchasing organizations, biopharmaceutical third-party logistics providers, and direct platform procurement for food delivery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital systems consolidating temperature-assurance procurement through sole-source agreements, fragmenting contract access for commodity suppliers.
For Market Incumbents: Compound institutional contract density by embedding gel engineering teams within hospital pharmacy operations and securing exclusive validation documentation rights. Backward integration into superabsorbent polymer production hedges against feedstock cost volatility. Prioritize biodegradable film R&D ahead of California and New York extended producer responsibility deadlines. For New Entrants and Emerging Players: Differentiate on compostable barrier materials for retail pharmacy channels where sustainability specifications outpace incumbent reformulation velocity. Target urgent care clinic networks bypassing traditional hospital supply aggregators. Lead with direct procurement relationships and rapid customization capabilities against validated-packaging incumbents. For Investors and Strategic Acquirers: EPA Resource Conservation and Recovery Act amendments reshape the acquisition landscape toward formulators with non-toxic gel certification and documented biodegradation profiles. Five-to-ten year viability favors mid-cap specialists with captive polymer chemistry capabilities over commodity assemblers. Watch for state-level packaging waste rule accelerations as inflection signals for biodegradable film substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Substitution | California EPR legislation creates first-mover advantage ahead of federal packaging waste rules. |
| Cell Therapy Logistics Specialization | Cryogenic format development captures CAR-T distribution networks requiring ultra-low temperature validation. |
| Retail Pharmacy Channel Expansion | Direct procurement at drugstore chains bypasses hospital supply aggregators and GPO contracts. |
| Backward Integration into SAP Production | In-house superabsorbent polymer compounding hedges resin cost volatility and secures formulation IP. |
| Hospital System Sole-Source Agreements | Embedded pharmacy operations create switching costs and multi-year contract lock-in. |
Research Methodology
The analysis maps gel pack, instant cold pack, dry ice pack, and reusable format sub-sectors, each validated through cold chain logistics directors, hospital pharmacy procurement managers, polymer chemistry formulators, and food delivery platform supply chain leads. Primary interviews with biopharmaceutical third-party logistics providers, GPO contracts managers, and retail pharmacy category buyers combined with secondary validation from FDA 21 CFR Part 211 guidance documents, EPA Resource Conservation and Recovery Act provisions, REACH framework amendments, and customs trade data for polyethylene resin flows. Bottom-up volume modeling across end-user segments triangulated against top-down market sizing from production capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, material composition, and application with regional regulatory cluster overlays. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Forecast inputs incorporated pharmaceutical cold chain lane qualification trends and state-level extended producer responsibility legislative trajectories.
Material uncertainties — regulatory acceleration on biodegradable mandates, polymer resin supply disruptions, and cell therapy distribution network expansion rates — sit outside the modeled envelope. Forecasts reflect assumptions about validation documentation intensity and formulation substitution timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cork Packaging Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Global Strapping Market