
 Cold Waxed Paper Cups Market | 2026-2036
Cold Waxed Paper Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Waxed Paper Cups Market Outlook
North American specialty paper converters is repositioning capacity toward cold waxed cupstock as quick-service chains phase out polyethylene-lined alternatives. Dart Container Corporation leverages its integrated pulp-to-cup manufacturing footprint across the southeastern United States to sustain cost leadership in high-volume foodservice contracts. Huhtamäki Oyj anchors European supply through its molded fiber technology leadership, while Graphic Packaging International competes via coated recycled board innovations that reduce virgin pulp dependency.
Cold waxed paper cups comprise single-use beverage containers manufactured from bleached or unbleached kraft paper substrate coated with refined paraffin or vegetable-based wax emulsions, typically achieving moisture resistance thresholds of 30-60 minutes for chilled liquids without polyethylene lamination. The single wall category dominates institutional and quick-service channels where cost minimization governs procurement, while double wall variants command premium placement in specialty cafés where thermal insulation and tactile quality support brand differentiation. Ripple wall configurations occupy a narrowing niche between these tiers, and food trucks represent the fastest-growing end user segment as mobile operators prioritize lightweight, leak-resistant disposables under space-constrained service conditions.
The FDA regulates wax and paper food contact substances under 21 CFR 176.170, while EPA guidelines on municipal composting determine regional end-of-life viability for waxed paper products. BIS certification requirements in India and GB standards in China create divergent compliance pathways for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and wax composition rules that will determine which coating chemistries retain market access across major economies.
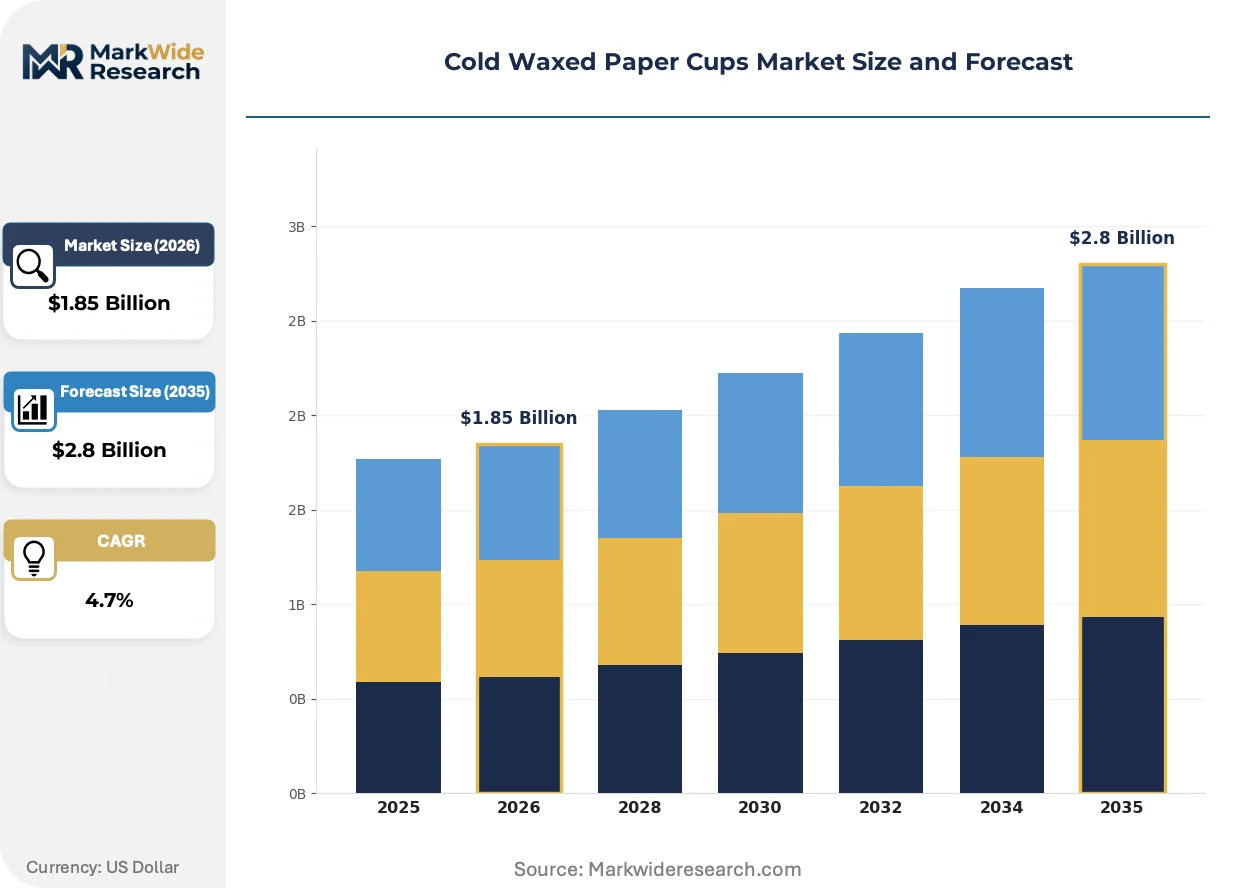
Market Dynamics
Quick-service chains across North America are accelerating polyethylene phase-outs under municipal composting mandates and EPR frameworks, compressing procurement timelines for waxed paper alternatives and forcing converters to requalify cupstock specifications at unprecedented speed.
Growth Catalysts
- EU Single-Use Plastics Directive:The prohibition on plastic-lined foodservice containers across member states is redirecting institutional procurement toward paraffin and vegetable-wax coated alternatives.
- Quick-service restaurant chains:Drive-thru and grab-and-go beverage programs in the United States are standardizing cold waxed cupstock for chilled fountain drinks and iced coffee.
- Municipal composting infrastructure:Cities including Seattle, San Francisco, and Austin operate industrial facilities that accept waxed paper in organic waste streams, creating closed-loop end-of-life pathways.
Market Restraints
- Paraffin feedstock volatility:Refined petroleum wax pricing tracks crude oil indices, exposing converters to margin compression during energy market spikes.
- Technical performance ceiling:Cold waxed barriers achieve 30-60 minute moisture resistance versus polyethylene's multi-hour durability, limiting adoption in extended-hold applications.
- Regional supply concentration:Integrated pulp-to-cup manufacturing clusters in the southeastern United States dominate North American capacity, creating logistics disadvantages for West Coast and Midwest buyers.
Strategic Opportunities
- India BIS certification pathway:Export-oriented converters can capture institutional catering demand as the Food Safety and Standards Authority of India tightens food contact material standards.
- Food truck and mobile catering:Lightweight, leak-resistant single-wall formats address space-constrained service environments where storage volume governs procurement decisions.
- Vegetable-based wax emulsions:Convergence of soy and carnauba coating chemistries with industrial composting certifications opens premium positioning in specialty café channels.
Industry Challenges
- Compostability certification timelines:Third-party validation through BPI or CMA protocols requires 12-18 month testing cycles that delay product launches.
- Legacy equipment retrofit costs:Converters operating polyethylene lamination lines face capital expenditure burdens to install wax coating and curing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Waxed Paper Cups Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Ripple Wall, Others Capacity: 8 oz, 12 oz, 16 oz, 24 oz End User: Restaurants, Cafés, Catering Services, Food Trucks Distribution Channel: Online Retail, Offline Retail, Wholesale, Foodservice |
| Companies Covered | BM Packaging, Sanpac, Hefei Hyde Environment Protection Technology Co. Ltd., Jaya Enterprises, Meru Industries, Tidi Products, Dart Container Corporation, Huhtamäki Oyj, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Waxed Paper Cups Market Strategic Shifts
Coating application technologies and regulatory compliance frameworks are actively reshaping how cold waxed paper cups achieve moisture resistance, with automation and material science convergence compressing development cycles.
Precision wax deposition systems using closed-loop temperature control and ultrasonic spray nozzles are automating coating uniformity to within 2-gram variance per square meter. Quick-service chains with centralized procurement functions are adopting these specifications for fountain beverage programs. The technology is automating quality assurance workflows that previously required manual caliper testing, reducing batch rejection rates and enabling just-in-time cupstock supply.
The EPA's municipal composting guidelines and state-level extended producer responsibility frameworks are tightening contamination thresholds for food-soiled paper products. Industrial composting facilities in Oregon, Vermont, and Massachusetts now reject loads exceeding 1% non-compostable content. Quick-service operators in these states are responding by specifying BPI-certified wax formulations and requiring chain-of-custody documentation from converters.
Consolidated procurement through group purchasing organizations is displacing direct mill relationships for mid-sized restaurant chains. Foodservice distribution giants including Sysco and US Foods are bundling cold waxed cups with broadline supply contracts, compressing price discovery and locking smaller converters out of multi-year agreements. This concentration is most visible in the southeastern United States, where regional distributors have consolidated warehousing networks to serve quick-service density along interstate corridors.
Cold Waxed Paper Cups Market Segmentation
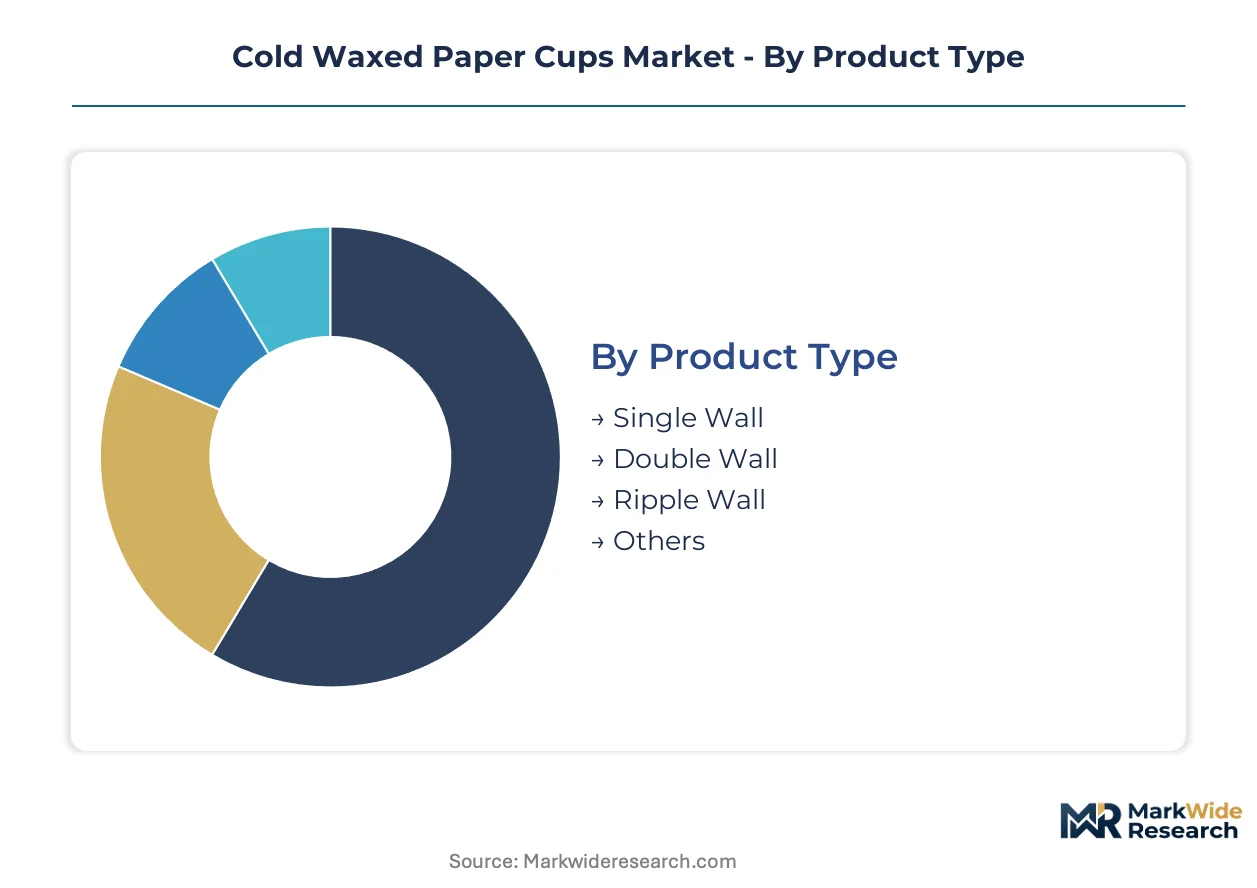
Cold waxed paper cup procurement splits sharply between cost-driven institutional buyers and premium-positioned specialty operators. Each segmentation dimension reveals distinct margin structures and technical requirements that govern converter capacity allocation.
Product Type:
Volume concentration sits with single-wall formats while premium capture belongs to insulated variants.
- Single Wall:Unbleached or bleached kraft paper substrate with paraffin or vegetable wax emulsion coating achieves 30-60 minute moisture resistance. Quick-service fountain beverage programs in the United States specify this format under centralized procurement contracts where unit cost minimization overrides performance margins.
- Double Wall:Dual substrate layers with interstitial air gap provide thermal insulation and structural rigidity for extended hold times. Specialty cafés in Seattle and San Francisco command this configuration for iced coffee programs where tactile quality supports brand differentiation and justifies premium pricing.
- Ripple Wall:Corrugated outer sleeve creates intermediate insulation with reduced material versus double wall. Food trucks in Austin and Portland favor this format for space-constrained storage.
- Others:Includes custom-embossed and seasonal-printed variants for limited promotional runs.
Today's leader: Single Wall. Tomorrow's challenger: Double Wall.
Capacity:
Procurement patterns track beverage program sizing across institutional and specialty channels.
- 8 oz:Compact format targets espresso-based beverages and children's portions. European quick-service chains specify this capacity for compliance with EU Single-Use Plastics Directive portion guidance.
- 12 oz:Standard fountain drink specification dominates US drive-thru volumes. Municipal composting infrastructure in San Francisco and Austin supports end-of-life pathways for this high-turnover format.
- 16 oz:Primary iced coffee and large fountain format. Food trucks expanding most quickly specify this capacity for margin capture per transaction.
- 24 oz:Extra-large format for cinema and stadium concessions where extended hold times stress wax barrier performance.
12 oz commands current procurement volume. 16 oz shows steepest expansion trajectory among mobile operators.
End User:
Customer-type segmentation reveals divergent technical specifications and certification requirements.
- Restaurants:Full-service and fast-casual operators with BPI-certified composting mandates in Oregon and Vermont drive specification for vegetable-based wax formulations with chain-of-custody documentation.
- Cafés:Third-wave coffee operators in specialty markets prioritize double-wall tactile quality and custom print capabilities for brand visibility.
- Catering Services:Institutional volume buyers leverage group purchasing organization contracts through Sysco and US Foods bundling arrangements.
- Food Trucks:Mobile operators gaining share fastest prioritize lightweight single-wall formats with leak resistance under space-constrained service conditions.
Restaurants anchor current demand. Food trucks represent the fastest-growing end user category.
Distribution Channel:
Channel structure determines price discovery mechanisms and converter access to multi-year agreements.
- Online Retail:E-commerce platforms serve small-batch specialty buyers and independent operators with minimum order quantities below wholesale thresholds.
- Offline Retail:Cash-and-carry restaurant supply stores cater to immediate-need procurement with limited SKU depth.
- Wholesale:Regional distributors in the southeastern United States consolidate warehousing networks to serve quick-service density along interstate corridors.
- Foodservice:Broadline distribution through national networks bundles cold waxed cups with protein and produce contracts, compressing direct mill relationships.
Foodservice dominates contract value. Online Retail captures emerging specialty demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as converters relocate capacity toward jurisdictions with streamlined compostability certification pathways and lower feedstock costs. Wax coating specialists are migrating from high-compliance-cost markets to emerging manufacturing hubs where municipal waste policies still permit paraffin-based formulations.
United States
Quick-service fountain beverage programs in Texas and Florida drive procurement volume for single-wall formats. The EPA's municipal composting guidelines and state-level extended producer responsibility frameworks in Oregon and Vermont tighten contamination thresholds. Integrated pulp-to-cup manufacturing clusters across Georgia and Alabama dominate North American capacity.
Germany
Specialty café operators in Berlin and Munich command premium double-wall specifications for iced coffee programs. The EU Single-Use Plastics Directive prohibits plastic-lined alternatives across member states. Industrial composting facilities in Bavaria and Baden-Württemberg accept BPI-certified wax formulations with chain-of-custody documentation.
India
Institutional catering demand in Maharashtra and Karnataka accelerates as food contact material standards tighten. The Food Safety and Standards Authority of India enforces BIS certification requirements for imported cupstock. Export-oriented converters in Gujarat and Tamil Nadu reposition capacity to capture mid-tier restaurant contracts.
China
Manufacturing scale in Guangdong and Zhejiang provinces supplies global private-label demand for unbleached kraft substrates. GB standards for food contact paper products create divergent compliance pathways versus Western markets. Molded fiber technology hubs in Jiangsu province serve European quick-service chains through indirect export channels.
Brazil
Mobile foodservice expansion in São Paulo and Rio de Janeiro prioritizes lightweight single-wall formats under space-constrained conditions. ANVISA regulates food contact substances with phased alignment to Mercosur technical standards. Regional distributors in Minas Gerais consolidate warehousing networks to serve interstate quick-service corridors.
Cold Waxed Paper Cups Market Competitive Environment
Southeastern United States producers anchor the scale-driven tier; European specialists hold the premium-certified segment. The vendor base splits between integrated pulp-to-cup manufacturers and independent converters sourcing cupstock from merchant suppliers. Three archetypes dominate: vertically integrated giants with captive forestry assets, technology-licensing specialists with proprietary coating systems, and regional fabricators serving foodservice distribution bundles. Capacity expansion and certification pre-qualification constitute the dominant competitive moves as procurement timelines compress.
Among North American integrated manufacturers, Dart Container Corporation exemplifies the scale-driven archetype with southeastern U.S. manufacturing concentration. Huhtamäki Oyj and Graphic Packaging International occupy positions within the premium technology tier, representing contrasting approaches to substrate innovation and coating chemistry. These three anchors illustrate how geographic clustering and technical specialization stratify competitive positioning across institutional and specialty channels.
| Leading Market Players |
|---|
| BM Packaging |
| Sanpac |
| Hefei Hyde Environment Protection Technology Co. Ltd. |
| Jaya Enterprises |
| Meru Industries |
| Tidi Products |
| Dart Container Corporation |
| Huhtamäki Oyj |
| Graphic Packaging International |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement consolidation through Sysco and US Foods bundling contracts is compressing price discovery mechanisms and forcing converters to absorb margin erosion or risk volume loss to southeastern U.S. integrated manufacturers.
Pricing Analysis
Distributor margin layers in foodservice channels absorb 15-25 points before reaching end-users, with three-tier pricing structure across premium, standard, and economy levels separating BPI-certified vegetable-wax formulations from paraffin-based commodity grades. Price differentiation hinges on certification tier and volume scale, with pricing pressure stemming from petroleum wax feedstock volatility tracking crude indices. Institutional buyers through GPO contracts exhibit highest price sensitivity, while specialty cafés in Seattle and San Francisco tolerate premium positioning for tactile quality.
Supply Chain Analysis
Workforce availability constraints in Georgia and Alabama pulp-to-cup manufacturing clusters are tightening operational flexibility as integrated producers expand coating capacity. Supply concentrates in the United States, China, and India, with raw material dependencies spanning bleached kraft pulp, refined paraffin, and soy-based wax emulsions. Tariff exposure on Chinese cupstock imports creates structural risk for independent converters lacking captive forestry assets. Distribution runs through regional foodservice distributors consolidating warehousing networks along interstate corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
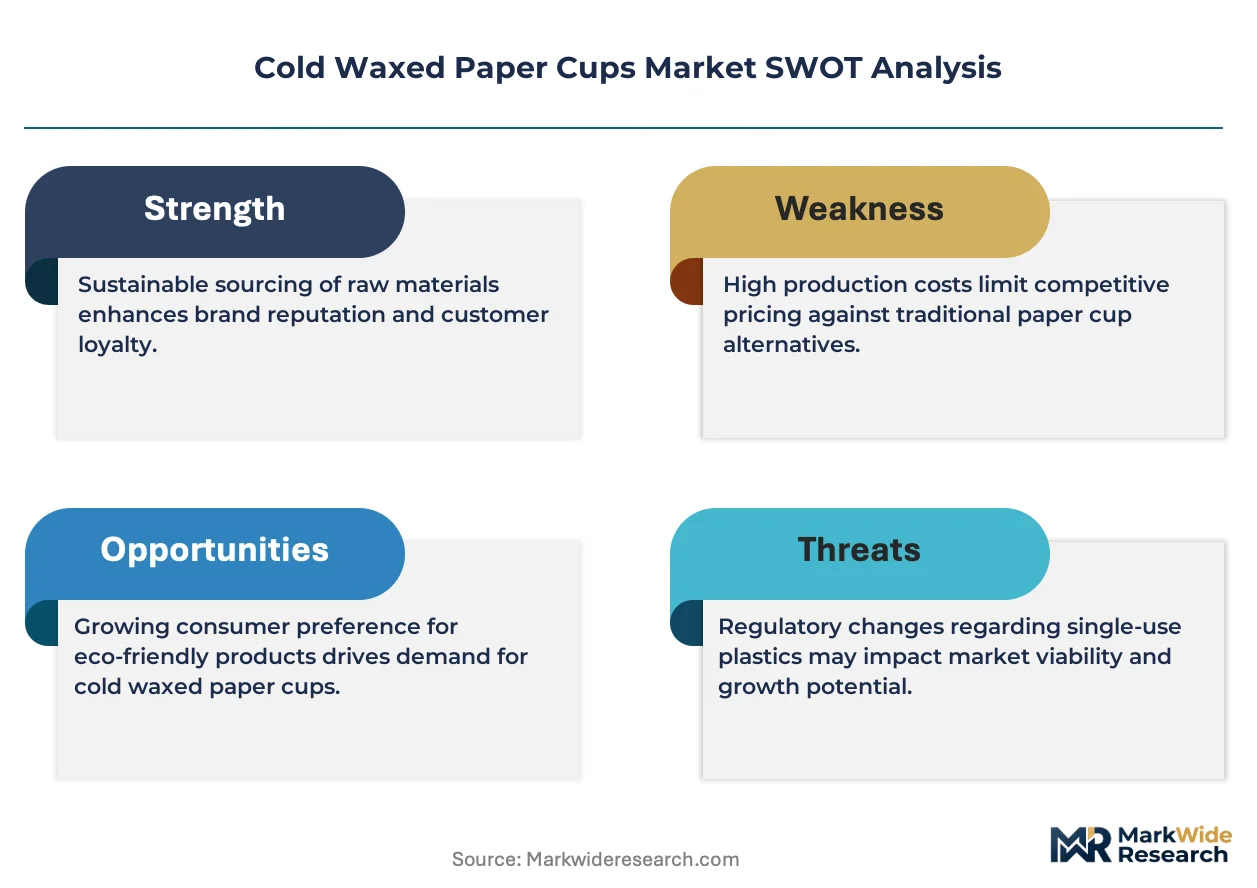
Cold waxed paper cups function as a stable compounder anchored by municipal composting infrastructure expansion and regulatory phase-outs of polyethylene-lined alternatives across North American and European foodservice channels.
For Market Incumbents: Acquire BPI-certified coating formulation capabilities to defend share against vegetable-wax specialists capturing premium café contracts. Expand thermal curing capacity in Georgia and Alabama manufacturing clusters to service compressed procurement timelines from quick-service chains phasing out plastic-lined alternatives. Certification investment represents the critical lever for retaining multi-year foodservice distribution agreements. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive across member states opens a window for paraffin-to-vegetable-wax conversion specialists to capture institutional catering demand. Target food truck and mobile catering segments in Austin and Portland where lightweight single-wall specifications and space-constrained storage requirements favor nimble suppliers over integrated giants. White-label manufacturing for regional distributors offers the most penetrable go-to-market pathway. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing BIS certification pathways for Indian institutional catering expansion. Long-term viability over a 5-10 year window favors asset-light coating technology licensors over capital-intensive pulp-to-cup integrated producers. Watch municipal composting contamination threshold tightening in Oregon, Vermont, and Massachusetts as the inflection signal for vegetable-wax formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive kraft fiber sourcing insulates Georgia and Alabama converters from merchant pulp price volatility. |
| BPI Certification Investment | Third-party compostability validation unlocks municipal organic waste stream access in Seattle and San Francisco. |
| Precision Wax Deposition Automation | Ultrasonic spray nozzle systems reduce batch rejection rates for just-in-time quick-service supply contracts. |
| Vegetable-Wax Formulation Development | Soy and carnauba coating chemistries command premium positioning in specialty café channels with EPR compliance. |
| Foodservice Distribution Partnership | Sysco and US Foods bundling arrangements lock in multi-year volume commitments from mid-sized restaurant chains. |
Study Parameters
Direct dialogue with specialty paper converters, quick-service procurement directors, municipal composting facility operators, and foodservice distribution category managers grounded qualitative findings in operational reality. Secondary validation drew from EPA municipal composting guidelines, FDA food contact substance filings under 21 CFR 176.170, BPI certification databases, and state-level extended producer responsibility framework documents. Bottom-up cupstock demand modeling and top-down foodservice packaging spend analysis provided cross-referenced triangulation.
Segment-level projections across product type, capacity tier, end user category, and distribution channel structure were generated through the analytical framework over the projection horizon. CAGRs were derived from historical volume trajectories adjusted for regulatory phase-out schedules and infrastructure buildout timelines. Forecast inputs incorporated quick-service fountain beverage program standardization rates and municipal composting facility acceptance threshold evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under paraffin feedstock price spikes or accelerated polyethylene substitution mandates. Material deviation in EU Single-Use Plastics Directive enforcement rigor or EPA composting guideline revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market