
 Germany Rigid Plastic Packaging Market | 2026-2036
Germany Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Rigid Plastic Packaging Market Insights
Digital printing integration with lightweight barrier films is rewriting production economics for German converters. Alpla Group leverages in-house recycling infrastructure to secure post-consumer resin flows. Retal Group anchors its position through dedicated preform manufacturing for beverage brand owners. Amcor Group GmbH differentiates via multi-layer oxygen-scavenging technologies for sensitive food applications.
Germany Rigid Plastic Packaging comprises injection-molded, blow-molded, or thermoformed polymer structures engineered to dimensional stability above 25 kPa compressive load, serving containment, protection, and shelf-life extension functions across supply chains. Polypropylene dominates material demand owing to its thermal resistance and established mechanical recycling pathways in German sorting facilities. Bottles capture the largest product volume pool, while trays represent the fastest structural expansion driven by modified-atmosphere requirements in fresh protein retail. The food and beverage end-user segment commands the deepest margin pool due to stringent migration limits and qualification cycles.
Germany's Packaging Act, administered by the Central Agency Packaging Register, mandates minimum recycled content thresholds and dual-system participation fees that reshape material selection at the design stage. KBA enforcement of transport safety regulations for industrial chemicals further constrains UN-certified container specifications. REACH compliance through ECHA substance authorization processes adds testing burden for colorants and additives. Stakeholders must monitor forthcoming EU Packaging and Packaging Waste Regulation revisions to calibrate capital allocation between mechanical recycling upgrades and bio-based polymer pilot lines.
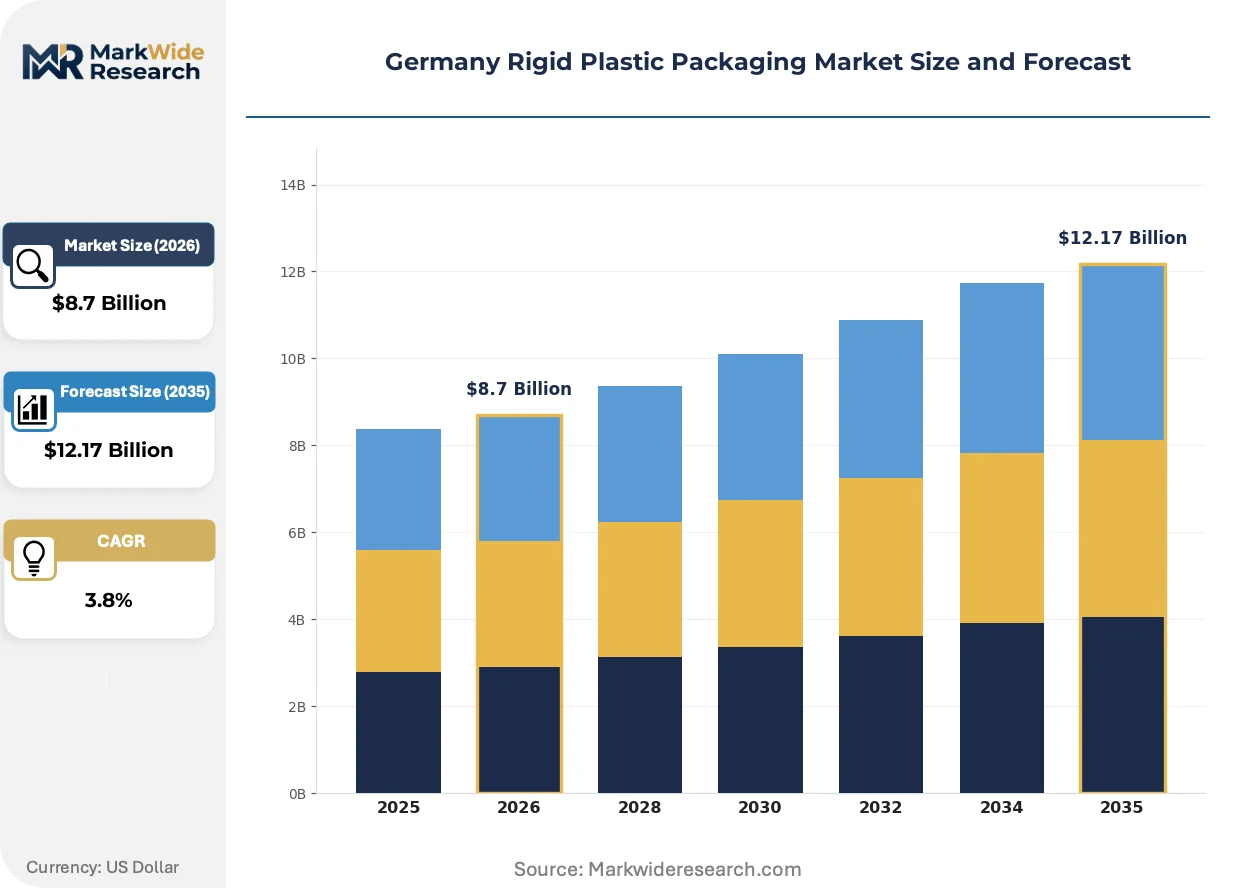
Market Dynamics
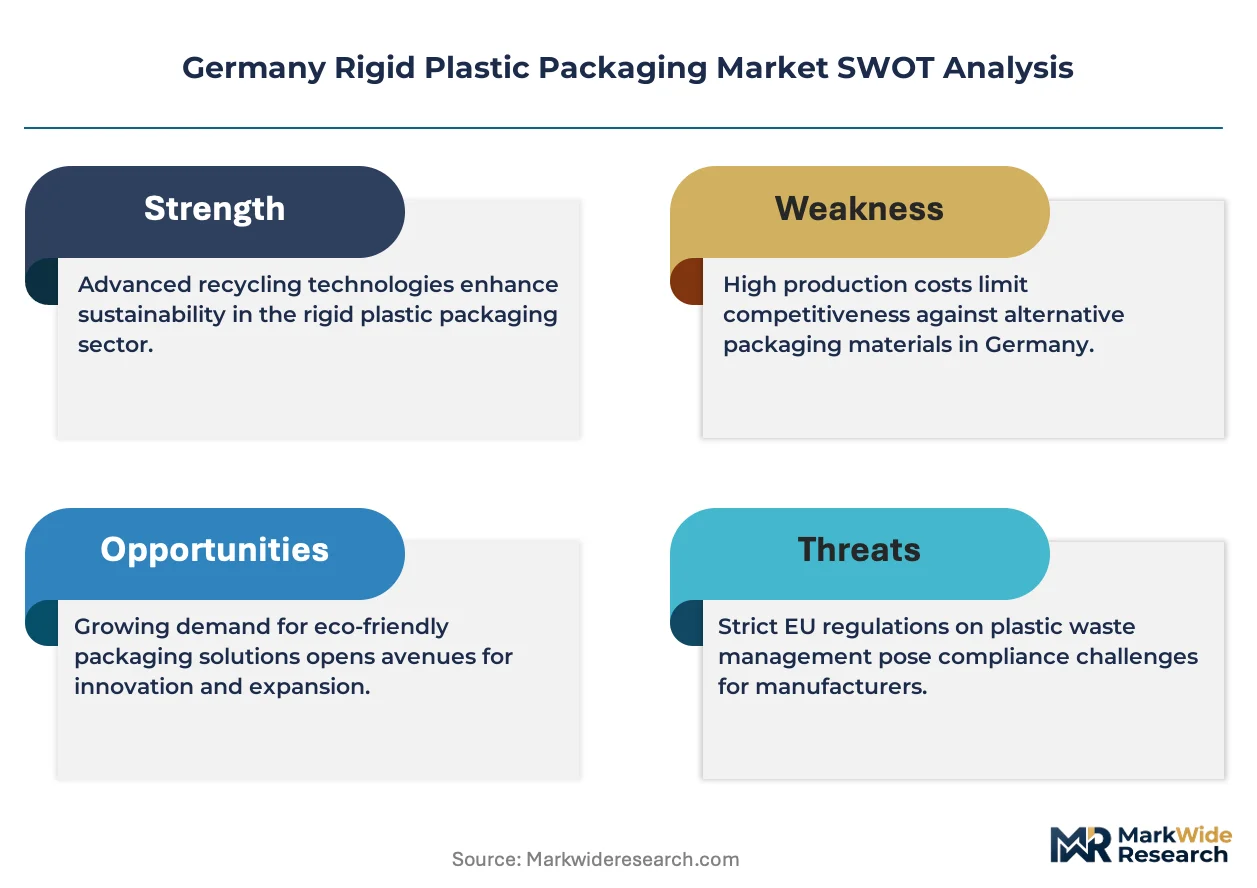
Germany's Packaging Act mandates minimum recycled content thresholds and dual-system participation fees, forcing converters to redesign material specifications around mechanically recycled polypropylene availability and sorting infrastructure capabilities.
Growth Catalysts
- Extended Producer Responsibility:Germany's Central Agency Packaging Register enforces fee modulation based on recyclability, incentivizing mono-material designs that flow through existing German sorting infrastructure.
- Modified-Atmosphere Packaging:Fresh protein retailers in North Rhine-Westphalia demand high-barrier trays, expanding thermoformed polypropylene volumes for case-ready meat applications.
- Digital Print Integration:Short-run customization capabilities enable beverage brand owners to compress SKU launch cycles and reduce pre-printed inventory obsolescence.
Market Restraints
- Post-Consumer Resin Scarcity:German mechanical recycling capacity constraints limit food-grade rPP availability, forcing converters to absorb premium pricing or dilute recycled content claims.
- Feedstock Volatility:Naphtha-linked polypropylene pricing exposes margin compression during crude oil spikes, particularly for non-integrated converters lacking backward integration into propylene supply.
- Multi-Layer Incompatibility:Oxygen-scavenging barrier films incorporating EVOH or PA layers fragment in German optical sorting streams, creating regulatory non-compliance risk under Packaging Act recyclability audits.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis-based polypropylene regeneration offers food-contact approval pathways unavailable to mechanical recycling, with pilot investments clustering in Rhineland chemical corridors.
- Refill Infrastructure:Beverage brand owners test standardized bottle pooling systems in Berlin and Hamburg, creating captive demand for durable PET designs with 20+ use cycles.
- Pharmaceutical Compliance:EMA serialization mandates drive demand for tamper-evident rigid containers with integrated track-and-trace features, a segment with qualification barriers protecting margin pools.
Industry Challenges
- Migration Testing Bottlenecks:EFSA compliance for recycled content in food-contact applications requires 12-18 month validation cycles, delaying product launches and freezing formulation experimentation.
- Sortation Technology Gaps:Near-infrared detection failures for black polypropylene trays result in manual sorting labor costs that erode mechanical recycling economics at German facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Rigid Plastic Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Material: Polypropylene, Polyethylene, Polystyrene, Polyvinyl Chloride End User: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | Alpla Group, Retal Group, Amcor Group GmbH, Berlin Packaging, Mauser Packaging Solutions, Berry Global Inc., Frapak Packaging, Schutz GmbH & Co KGaA, AptarGroup Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Rigid Plastic Packaging Market Trends and Innovations
Digital manufacturing technologies and regulatory pressure on circularity metrics are compressing traditional converter business models while opening margin pools for technology-integrated specialists.
Mono-material barrier structures incorporating nucleating agents and mineral fillers are rendering obsolete multi-layer laminate designs in fresh produce applications. Discounters Aldi and Lidl specify these structures for private-label salad trays, forcing incumbent converters to retool thermoforming lines or exit the segment.
REACH authorization processes through ECHA for colorants and additives extend qualification timelines by 8-14 months. Brand owners respond by narrowing approved substance lists, which locks converters into specified supply chains and restricts formulation flexibility for custom color matching.
Direct-to-retailer procurement contracts displace traditional distributor networks for standard bottle formats. Bavarian dairy cooperatives now source preforms through digital tender platforms, compressing converter margins but rewarding scale-efficient producers with volume guarantees and reduced customer acquisition costs.
Germany Rigid Plastic Packaging Market Segmentation
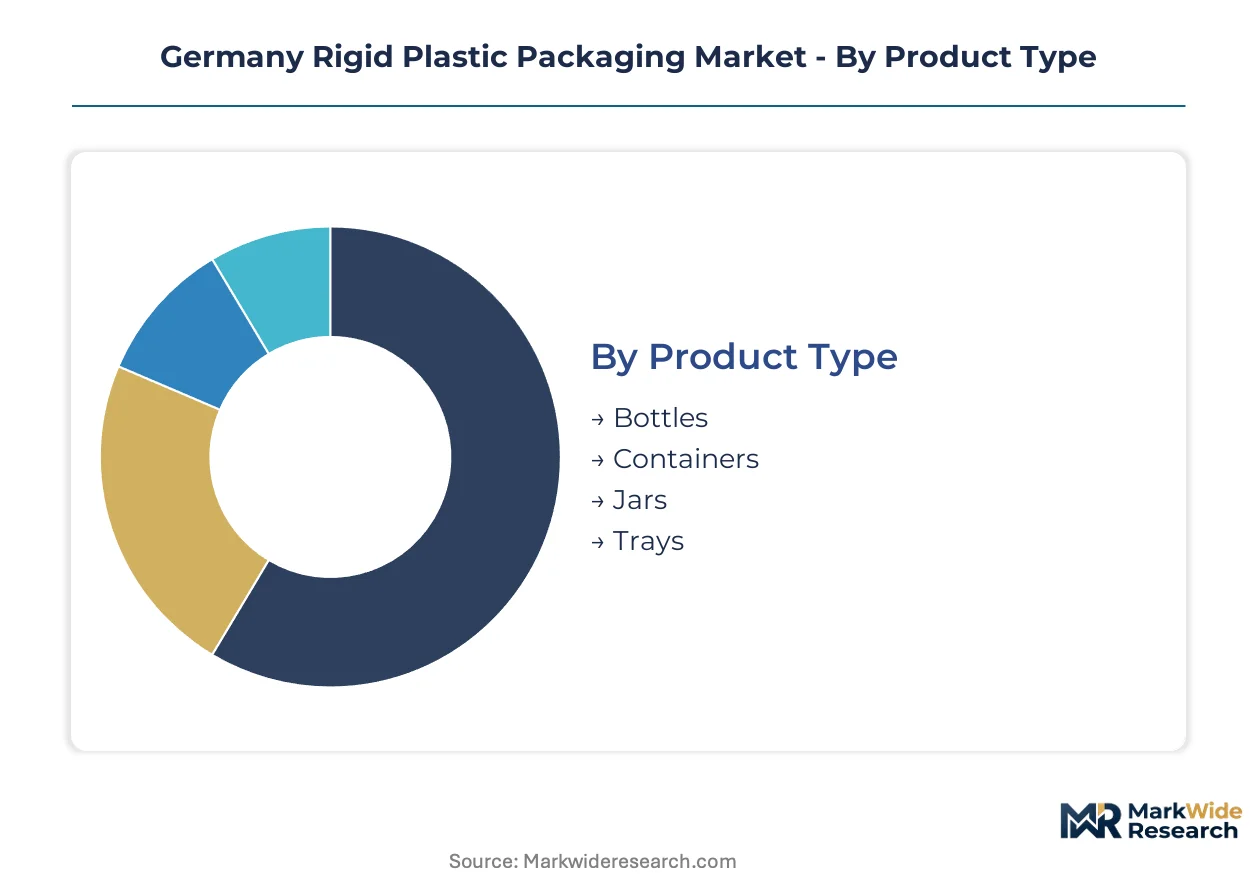
German converters calibrate production lines around four distinct product architectures, each demanding specialized thermoforming or blow-molding configurations. Material selection and end-use specifications further subdivide procurement patterns, creating discrete margin pools that resist cross-segment arbitrage.
Product Type:
Volume concentration across container geometries determines converter capital allocation and mold investment cycles.
- Bottles:Blow-molded PET and HDPE structures dominate beverage and personal care containment, with North Rhine-Westphalia's industrial corridor hosting the densest converter networks. KBA transport safety regulations constrain UN-certified designs for chemical applications, preserving specialized margin pools.
- Trays:Thermoformed polypropylene structures with modified-atmosphere barrier properties serve fresh protein retail in Aldi and Lidl supply chains. These formats gain share fastest as case-ready meat specifications displace traditional overwrap packaging.
- Containers:Injection-molded rectangular formats with tamper-evident closures address industrial chemical and pharmaceutical compliance requirements.
- Jars:Wide-mouth designs with induction seals concentrate in condiment and dairy applications requiring spoon-access functionality.
Bottles hold installed capacity. Trays are rotating up the share rankings.
Material:
Polymer selection balances thermal performance against mechanical recycling pathway compatibility under Germany's Packaging Act.
- Polypropylene:Semi-crystalline thermoplastic with 160°C melting point enables hot-fill applications and established mechanical recycling flows through German sorting infrastructure. North Rhine-Westphalia's fresh protein retailers specify homopolymer grades for tray thermoforming.
- Polyethylene:LDPE and HDPE variants serve squeeze bottles and industrial drum applications where flexibility or impact resistance outweighs thermal demands.
- Polystyrene:Crystal and high-impact grades retain niche positions in pharmaceutical vial and diagnostic tray segments despite limited recycling economics.
- Polyvinyl Chloride:Plasticized formulations persist in medical blister packs and chemical-resistant industrial containers, constrained by REACH authorization burdens for plasticizer substances.
Polypropylene captures the deepest margin pool. Polyethylene maintains volume scale in commodity applications.
End User:
Customer qualification requirements and migration testing protocols create distinct competitive moats across demand verticals.
- Food & Beverage:EFSA compliance for food-contact applications demands 12-18 month validation cycles, freezing formulation experimentation and locking converters into approved substance lists. Discounter procurement concentration in Bavaria and North Rhine-Westphalia compresses margins for standard formats.
- Pharmaceuticals:EMA serialization mandates drive tamper-evident rigid containers with integrated track-and-trace features, protecting margin pools through qualification barriers.
- Personal Care:Brand owner specification of post-consumer resin content for shampoo and cosmetic bottles channels demand toward mechanically recycled polypropylene with documented provenance.
- Industrial:KBA enforcement of transport safety regulations constrains UN-certified container specifications for chemical logistics, preserving specialized converter relationships.
Food & Beverage commands volume concentration. Pharmaceuticals is climbing the fastest on value per kilogram metrics.
Distribution Channel:
Channel configuration determines order fragmentation, inventory carrying costs, and converter customer acquisition economics.
- Supermarkets:Discounter direct procurement contracts for standard bottle formats displace traditional distributor networks, compressing converter margins but rewarding scale-efficient producers with volume guarantees.
- Online:E-commerce fulfillment requirements for durable secondary packaging create demand for corrugated-compatible rigid designs with stack strength above 25 kPa.
- Convenience Stores:Small-format retail drives single-serve and impulse-size packaging specifications with higher unit value but lower volume per SKU.
- Specialty Retailers:Premium cosmetic and pharmaceutical channels sustain custom color matching and short-run digital print capabilities with extended lead time tolerance.
Supermarkets anchor volume throughput. Online is gaining share fastest as fulfillment infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rigid plastic packaging exports flow primarily into neighboring EU member states, with France, the Netherlands, and Poland absorbing the largest volumes of converted bottles and thermoformed trays.
North Rhine-Westphalia
The industrial corridor between Cologne and Düsseldorf concentrates the densest converter networks serving Aldi and Lidl headquarters. KBA transport safety regulations enforce UN-certified specifications for chemical containers manufactured in Leverkusen and Duisburg. Sorting infrastructure in the Rhine-Ruhr metropolitan region processes the majority of Germany's post-consumer polypropylene streams.
Bavaria
Dairy cooperatives and beverage brand owners in Munich and Nuremberg drive demand for blow-molded PET bottles and preform supply. EFSA compliance requirements for food-contact applications extend qualification timelines for converters supplying Bavarian processors. The Nuremberg metropolitan area hosts specialized pharmaceutical packaging operations serving EMA serialization mandates.
Baden-Württemberg
Automotive chemical suppliers in Stuttgart demand industrial-grade HDPE containers with impact resistance specifications. REACH authorization processes through ECHA for colorants and additives constrain formulation flexibility for converters in Mannheim and Karlsruhe. The region's mechanical recycling facilities struggle with near-infrared detection of black polypropylene trays.
Hamburg
Port logistics and refill infrastructure pilots create captive demand for durable PET bottle pooling systems. Beverage brand owners test standardized returnable formats with 20+ use cycles in the metropolitan area. Chemical recycling pilot investments cluster along the Elbe River corridor targeting pyrolysis-based polypropylene regeneration.
Berlin-Brandenburg
E-commerce fulfillment centers drive specifications for corrugated-compatible rigid designs with stack strength above 25 kPa. The region's online retail infrastructure scales fastest, displacing traditional supermarket procurement patterns. Digital printing integration with lightweight barrier films rewrites production economics for local converters.
Germany Rigid Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated resin-to-converter operations capture margin through captive supply chains, while independent specialists survive through qualification barriers in pharmaceutical and food-contact segments. Strategic archetypes include backward-integrated resin processors, technology-licensed barrier specialists, and scale-efficient commodity producers. Dominant competitive moves center on mechanical recycling infrastructure acquisitions and digital manufacturing capability partnerships.
Among Austria-based integrated operators, Alpla Group anchors the resin-processing tier through in-house recycling infrastructure. Retal Group, a Luxembourg-structured specialist, occupies a position in preform manufacturing for beverage applications. Amcor Group GmbH, operating under Swiss-Australian parentage, exemplifies multi-layer barrier technology specialization for sensitive food segments. These three entities represent distinct competitive vectors: captive resin flows, dedicated preform scale, and oxygen-scavenging innovation.
| Leading Market Players |
|---|
| Alpla Group |
| Retal Group |
| Amcor Group GmbH |
| Berlin Packaging |
| Mauser Packaging Solutions |
| Berry Global Inc. |
| Frapak Packaging |
| Schutz GmbH & Co KGaA |
| AptarGroup Inc. |
| Others |
Pricing and Supply Chain Analysis
North Rhine-Westphalia's converter corridor between Cologne and Düsseldorf channels polypropylene resin flows through dense blow-molding and thermoforming capacity, concentrating pricing power among integrated operators with captive mechanical recycling infrastructure. The Packaging Act's dual-system participation fees and minimum recycled content thresholds feed directly into material selection costs, forcing non-integrated converters to absorb premiums or dilute compliance claims.
Pricing Analysis
Current-generation mono-material barrier structures command premiums over multi-layer laminate designs facing recyclability audit failures, while next-generation chemically recycled polypropylene awaits food-contact approval pathways. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated food-contact grades from industrial applications and commodity personal care formats. Cost compression in standard bottle segments intensifies because direct-to-retailer procurement contracts displace distributor markups. Discounter buyers in Bavaria and North Rhine-Westphalia exhibit highest price sensitivity, while pharmaceutical qualification barriers protect margin pools for tamper-evident container specialists.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation revisions function as de facto export controls on non-compliant packaging flows into German distribution channels. Polypropylene resin supply concentrates in Belgium, the Netherlands, and Germany's own chemical corridor, with naphtha-linked pricing tethered to crude volatility. Post-consumer resin availability rests on Rhineland sorting infrastructure struggling with near-infrared detection of black tray formats. Single-source vulnerability runs through centralized mechanical recycling capacity for food-grade rPP. Distribution runs through direct procurement contracts with Aldi and Lidl headquarters displacing traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's rigid plastic packaging sector faces high-growth disruption as chemical recycling scale-up and EFSA validation timelines for post-consumer resin create divergent competitive futures. The Packaging Act's enforcement trajectory and forthcoming EU regulation revisions constitute the decisive regulatory inflection.
For Market Incumbents: Build certification moats around EFSA-validated food-contact formulations before validation cycles lengthen further. Secure backward integration into pyrolysis-based polypropylene regeneration in Rhineland chemical corridors to escape mechanical recycling capacity constraints. Channel control through digital tender platforms for Bavarian dairy cooperatives protects volume guarantees against price erosion. Threat of substitute fiber-based packaging in fresh produce segments demands barrier performance investment to preserve tray market share. For New Entrants and Emerging Players: Berlin-Brandenburg's e-commerce fulfillment infrastructure offers underpenetrated demand for corrugated-compatible rigid designs with stack strength specifications above 25 kPa. Pharmaceutical serialization mandates in Nuremberg create qualification-barrier entry points for tamper-evident container specialists. Target chemical recycling pilot partnerships along Hamburg's Elbe River corridor for food-contact approval differentiation. Go-to-market angle: direct digital print integration with lightweight barrier films for short-run SKU compression. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with long-term direct procurement contracts with discounter headquarters and beverage brand owners. Five-to-ten-year viability favors specialists with integrated recycling infrastructure or pharmaceutical qualification assets over commodity bottle producers facing margin compression. Acquisition target archetype: mid-scale thermoforming operations with modified-atmosphere tray expertise and Aldi or Lidl supply relationships. Signal to watch: EFSA approval timelines for chemically recycled polypropylene as margin inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Infrastructure Acquisition | Captive post-consumer resin flows secure Packaging Act compliance and insulate against rPP scarcity premiums. |
| Chemical Recycling Pilot Scale-Up | Pyrolysis-based polypropylene regeneration unlocks food-contact approval pathways unavailable to mechanical recycling. |
| Digital Print Manufacturing Partnership | Short-run customization capabilities compress SKU launch cycles for beverage brand owners in North Rhine-Westphalia. |
| Pharmaceutical Qualification Investment | EMA serialization mandates protect margin pools through tamper-evident container qualification barriers. |
| Direct Retailer Procurement Contracting | Volume guarantees with Aldi and Lidl headquarters reduce customer acquisition costs and stabilize throughput. |
Research Methodology
A standing panel of converter operations managers, brand owner procurement leads, Central Agency Packaging Register administrators, and mechanical recycling facility engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ZSVR compliance filings, EFSA migration testing databases, ECHA REACH authorization records, and German customs trade statistics. Bottom-up capacity and throughput estimates triangulated against top-down packaging consumption models derived from retail sector procurement data.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product architecture, polymer grade, end-use qualification tier, and regional production cluster. CAGRs derived from installed capacity expansion timelines, EFSA validation cycle durations, and discounter procurement contract renewal patterns. Industry-specific forecast inputs included near-infrared sortation technology deployment rates and chemical recycling pilot investment flows.
Practitioners should monitor EFSA approval timelines for chemically recycled polypropylene, EU Packaging and Packaging Waste Regulation revision schedules, and black polypropylene tray detection technology deployment for early signals of forecast revision. Forecasts reflect assumptions around mechanical recycling capacity expansion and dual-system fee modulation trajectories. Material shifts in chemical recycling food-contact approval pathways or Packaging Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market