
 Middle East and Africa Paper Packaging Market | 2026-2036
Middle East and Africa Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Paper Packaging Market Foresight
Food and beverage demand is repositioning the Middle East and Africa paper packaging landscape toward higher-barrier board grades and grease-resistant coatings. Hotpack Packaging LLC leverages its UAE manufacturing base to supply quick-service restaurant chains across the Gulf with customized paperboard solutions. United Carton Industries Company anchors Saudi Arabia's corrugated segment through large-format box production for fresh produce exports. Gulf East Paper and Plastic Industries LLC differentiates by competing across both paper and flexible formats, giving it channel control in markets where buyers seek consolidated sourcing.
Middle East and Africa paper packaging comprises fiber-based containers, carriers, and wraps manufactured from virgin or recycled pulp, typically ranging from 150 to 450 grams per square meter in basis weight depending on end-use performance requirements. The primary commercial purpose is to protect, transport, and display goods while substituting for polymer-based alternatives in retail and foodservice channels. Corrugated boxes dominate volume throughput across the region due to e-commerce fulfillment expansion and agricultural export packaging needs. Kraft paper grades sustain margin pools in industrial wrapping and protective applications where tear strength and moisture resistance command price premiums. Recycled paper feedstock is gaining structural share as mill investments in Egypt and Morocco improve de-inking and pulping yields for containerboard production.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and South Africa's National Regulator for Compulsory Specifications shape product safety and fiber sourcing rules that govern market access for imported board and domestic converters. The UAE's technical regulations on paper and cardboard products for food contact, aligned with Gulf Standardization Organization frameworks, mandate migration testing that favors suppliers with certified laboratory networks. Egypt's Ministry of Trade and Industry enforces import substitution policies through local content requirements on government-procured packaging materials. Stakeholders must monitor how diverging national standards for recycled fiber content and chemical migration limits will fragment compliance costs across the region's fragmented regulatory landscape.
Market Dynamics
Saudi Arabia's extended producer responsibility framework and South Africa's packaging waste regulations are forcing converters to reengineer supply chains around certified recycled fiber streams and localized de-inking capacity.
Growth Catalysts
- E-commerce fulfillment surge:Last-mile delivery networks across the Gulf Cooperation Council corridor are demanding higher-grade corrugated specifications for damage reduction in ambient temperature conditions.
- Saudi Standards, Metrology and Quality Organization mandates:Food-contact migration testing requirements are filtering import volumes toward domestic converters with certified laboratory infrastructure.
- Agricultural export packaging:Egyptian citrus and Moroccan tomato shippers are specifying moisture-resistant kraft liners to meet European retail chain compliance windows.
Market Restraints
- Recycled pulp supply concentration:Containerboard mills in Egypt and Morocco face yield limitations from inconsistent post-consumer fiber collection infrastructure.
- Hot-climate barrier coating costs:Grease-resistant and moisture-barrier treatments add 15-25% material cost premiums versus standard board grades.
- Import substitution enforcement:Egypt's Ministry of Trade and Industry local content rules restrict government procurement to domestic converters regardless of quality differentials.
Strategic Opportunities
- Ethiopia and Kenya underpenetration:East African quick-service restaurant chains lack regional suppliers for customized paperboard packaging, creating first-mover windows for Gulf-based converters.
- Dual-format bundling:Foodservice distributors in the UAE are consolidating procurement across paper and flexible formats, rewarding suppliers with cross-category production capability.
- South Africa EPR credit trading:Extended producer responsibility regulations enable packaging producers to monetize recycling certificates from post-industrial fiber recovery investments.
Industry Challenges
- De-inking technician scarcity:Containerboard mills struggle to hire process engineers with experience in high-contaminant fiber streams common to regional waste collection systems.
- Gulf Standardization Organization alignment lag:Divergent national implementation timelines for food-contact migration limits create multi-jurisdiction compliance testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Paper Packaging Market |
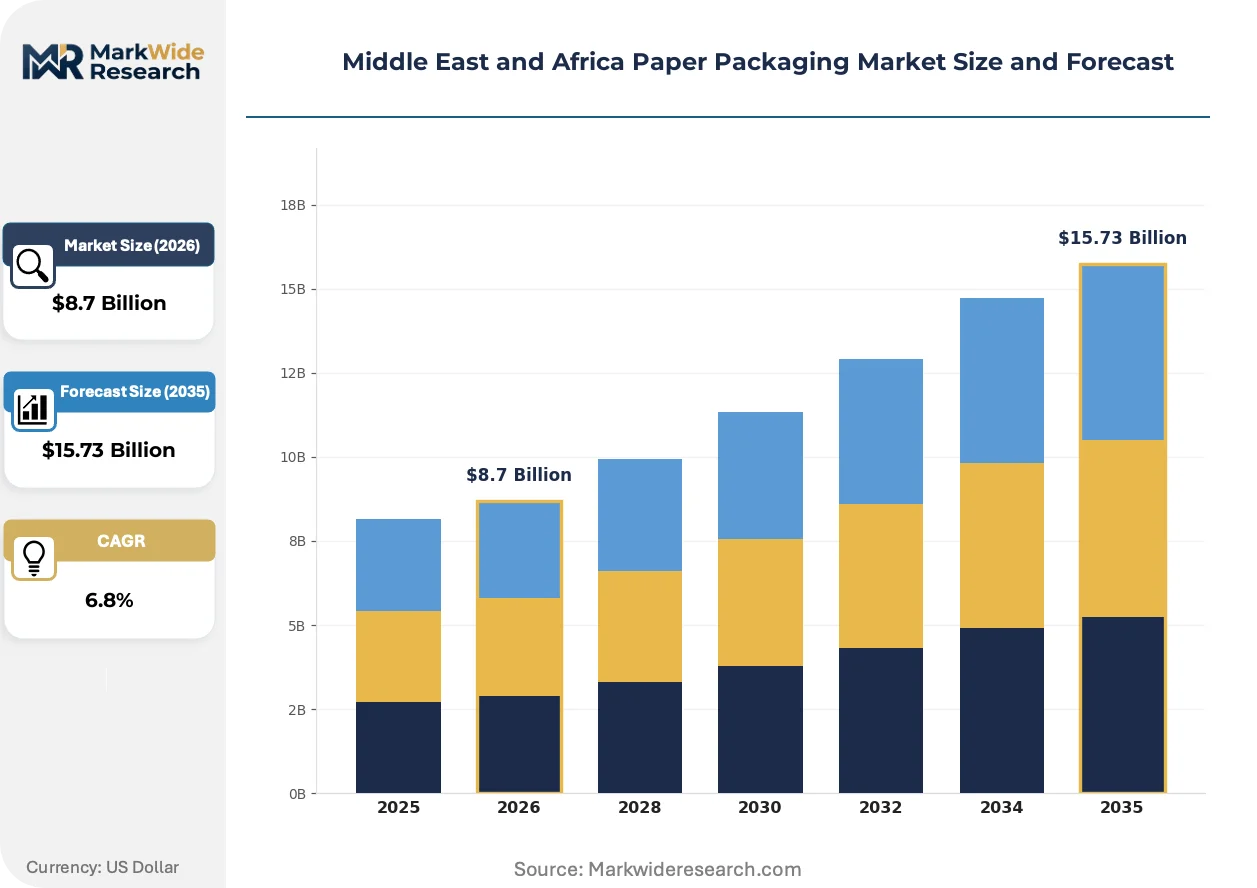
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxboard, Corrugated Boxes, Paper Bags, Wrapping Paper End Use Industry: Food & Beverage, Consumer Goods, Healthcare, Electronics Material: Kraft Paper, Recycled Paper, Solid Bleached Board, Coated Paper Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Hotpack Packaging LLC, United Carton Industries Company (UCIC), Gulf East Paper and Plastic Industries LLC, Shuaiba Industrial Company (KPSC), Tarboosh Packaging Co. LLC, Arabian Packaging Co. LLC, International Packaging Company LLC, Green Bags UAE, ENPI Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Paper Packaging Market Shifts & Advancements
Barrier coating chemistry and digital print integration are compressing production lead times while regulatory alignment pressures are standardizing compliance protocols across Gulf Cooperation Council markets.
Water-based barrier coatings are converging with nanocellulose reinforcement to replace polyethylene laminates in hot-food applications. Quick-service restaurant chains in Saudi Arabia and the UAE are specifying these grades for takeaway containers within 18-month procurement cycles. The technology is converging with existing folding carton production lines, allowing converters to serve food-contact and industrial accounts from shared asset bases without dedicated barrier-coating investments.
South Africa's extended producer responsibility regulations for packaging waste mandate minimum recycled content thresholds and producer-funded collection infrastructure. The framework compels brand owners to contract exclusively with certified converters or face non-compliance penalties. Fresh produce exporters in the Western Cape are responding by sourcing corrugated from mills with verified post-consumer fiber chains to secure EPR credit eligibility.
Consolidated sourcing mandates from pan-Gulf foodservice distributors are compressing supplier rosters and lengthening contract tenures. Buyers now require single-source accountability across paperboard, flexible films, and disposable tableware categories. This pattern is most visible in Dubai and Riyadh, where procurement teams at regional quick-service restaurant headquarters are eliminating fragmented vendor management overhead.
Middle East and Africa Paper Packaging Market Segmentation
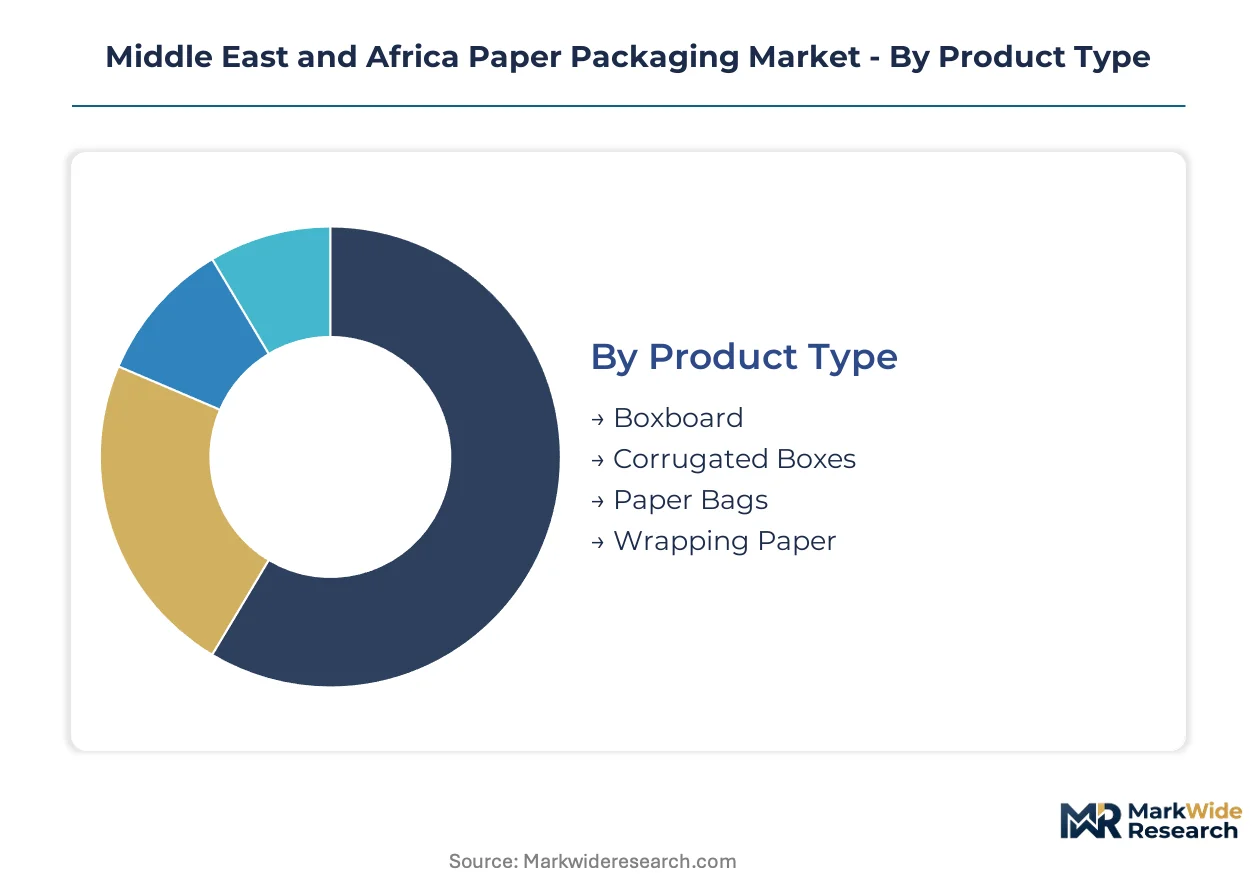
Segmentation reveals how Middle East and Africa paper packaging demand fragments across substrate specifications, end-use performance requirements, and channel access patterns. Understanding these divisions exposes where converter capacity investments align with buyer procurement priorities.
Product Type:
Supply concentration in containerboard and folding carton capacity shapes competitive positioning across the Gulf Cooperation Council corridor.
- Corrugated Boxes:Multi-layer fluted board construction provides stacking strength for ambient-temperature e-commerce fulfillment and agricultural export logistics. Saudi Arabian and UAE converters are expanding large-format production lines to capture fresh produce shipping demand from Egyptian citrus and Moroccan tomato exporters.
- Boxboard:Solid fiber construction ranging from 200-400 gsm supports folding carton applications for quick-service restaurant packaging and retail shelf display. South African mills with certified post-consumer fiber chains are capturing EPR credit eligibility from Western Cape produce exporters.
- Paper Bags:Single-ply or multi-ply kraft constructions serve grocery retail and foodservice carry-out applications.
- Wrapping Paper:Lightweight kraft grades provide industrial protective wrapping and decorative retail packaging functions.
Corrugated boxes absorb the bulk of installed capacity; boxboard is expanding most quickly.
End Use Industry:
Application-specific barrier requirements and migration testing protocols fragment converter specialization across regional markets.
- Food & Beverage:Grease-resistant and moisture-barrier coated boards for hot-food contact applications dominate procurement volumes. Saudi Standards, Metrology and Quality Organization migration testing mandates are filtering import volumes toward domestic Gulf converters with certified laboratory infrastructure.
- Consumer Goods:Folding cartons and rigid boxes for personal care and household products require print-quality surfaces and structural integrity for retail shelf presence.
- Healthcare:Sterile barrier systems and pharmaceutical folding cartons demand compliance with Gulf Standardization Organization food-contact alignment for primary packaging.
- Electronics:Anti-static corrugated and molded pulp protective formats serve last-mile delivery damage reduction requirements.
Food and beverage commands the dominant share of coated board consumption; consumer goods drives premium print specification demand.
Material:
Feedstock sourcing strategies diverge between virgin fiber integration and de-inking yield optimization across regional mill investments.
- Recycled Paper:Post-consumer fiber streams processed through improved de-inking capacity in Egypt and Morocco are gaining structural share in containerboard production. South Africa's extended producer responsibility regulations mandate minimum recycled content thresholds for EPR credit eligibility.
- Kraft Paper:Unbleached virgin pulp provides tear strength and moisture resistance for agricultural export liners and industrial wrapping applications.
- Solid Bleached Board:Bleached chemical pulp delivers high-print-quality surfaces for premium food and cosmetic folding cartons.
- Coated Paper:Clay or polymer surface treatments enhance barrier properties and print reproduction for food-contact applications.
Recycled paper is climbing the fastest as mill investments improve yield; kraft paper sustains margin pools in export logistics.
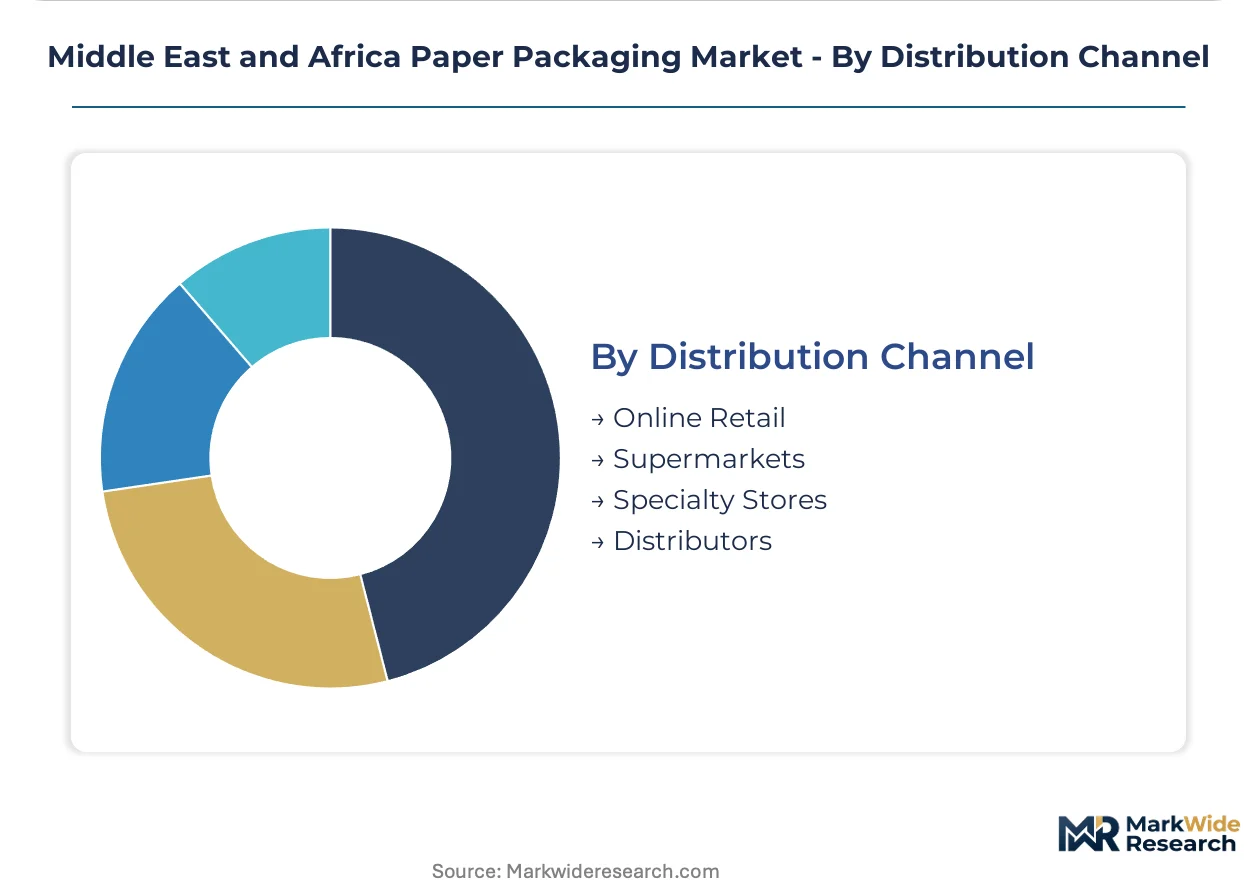
Distribution Channel:
Channel control patterns reflect consolidated procurement mandates from pan-Gulf foodservice distributors and fragmented retail access across North and East Africa.
- Distributors:Regional packaging distributors aggregate volume across fragmented quick-service restaurant and retail accounts, consolidating procurement for buyers seeking single-source accountability. Dubai and Riyadh procurement teams are eliminating fragmented vendor management overhead through distributor consolidation.
- Online Retail:E-commerce platform packaging specifications are driving corrugated grade standardization for last-mile damage reduction.
- Supermarkets:Private-label and fresh produce packaging requirements favor converters with certified recycled fiber chains.
- Specialty Stores:Premium and artisanal retail channels demand customized print and structural formats in lower volumes.
Distributors capture the largest volume aggregation role; online retail is gaining share fastest as e-commerce fulfillment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production capacity lags behind consumption across most of the Middle East and Africa, forcing Gulf states to import board grades while North African mills struggle with fiber yield constraints. This imbalance is reshaping investment patterns toward localized converting capacity.
Saudi Arabia
Domestic demand for corrugated containers is accelerating as fresh produce exporters require moisture-resistant kraft liners for European retail compliance. The Saudi Standards, Metrology and Quality Organization enforces food-contact migration testing that filters import volumes toward domestic converters with certified laboratory infrastructure. Jeddah and Riyadh industrial zones are attracting folding carton investments from regional quick-service restaurant suppliers seeking proximity to procurement headquarters.
United Arab Emirates
Pan-Gulf foodservice distributors are consolidating procurement across paperboard and flexible formats, compressing supplier rosters toward converters with cross-category capability. The country's national standardization body aligns with Gulf Standardization Organization frameworks for food-contact technical regulations. Dubai's Jebel Ali industrial corridor hosts converting capacity serving quick-service restaurant chains across the GCC corridor with customized paperboard solutions.
South Africa
Extended producer responsibility regulations mandate minimum recycled content thresholds and producer-funded collection infrastructure for packaging waste compliance. The National Regulator for Compulsory Specifications shapes fiber sourcing rules that govern market access for imported board and domestic converters. Johannesburg and Durban are seeing investment in recycled-content board mills as converters reengineer supply chains around certified post-consumer fiber streams.
Egypt
Import substitution policies enforced by the Ministry of Trade and Industry restrict government procurement to domestic converters regardless of quality differentials. Citrus exporters are specifying moisture-resistant kraft liners to meet European retail chain compliance windows. Containerboard mills near Alexandria and Cairo face yield limitations from inconsistent post-consumer fiber collection infrastructure despite improved de-inking investments.
Morocco
Tomato shippers to European markets are driving demand for agricultural export packaging with barrier-coated board specifications. The country's national industrial development programs support mill investments in de-inking and pulping yields for containerboard production. Casablanca-Rabat industrial zones are concentrating converting capacity serving both domestic food processors and export logistics providers.
Middle East and Africa Paper Packaging Market Competitive Landscape
Top-tier vendors anchor the Gulf Cooperation Council corridor with integrated converting and distribution networks, while mid-scale specialists compete on recycled fiber certification and barrier coating specialization. The vendor base clusters around three strategic archetypes: Gulf-based integrated converters with pan-regional distribution, North African mill-dependent players leveraging proximity to European export markets, and South African EPR-credit-eligible suppliers with verified post-consumer fiber chains. Dominant competitive moves include capacity expansion in Jeddah and Dubai industrial zones, and portfolio diversification into water-based barrier coatings for hot-food applications.
Among UAE-based converters, Hotpack Packaging LLC and Gulf East Paper and Plastic Industries LLC represent the cross-category bundling archetype serving consolidated procurement mandates from pan-Gulf foodservice distributors. United Carton Industries Company anchors the large-format corrugated segment for Saudi Arabian fresh produce export logistics. These three entities exemplify how geographic positioning within the GCC corridor intersects with format diversification strategy to capture procurement consolidation trends.
| Leading Market Players |
|---|
| Hotpack Packaging LLC |
| United Carton Industries Company (UCIC) |
| Gulf East Paper and Plastic Industries LLC |
| Shuaiba Industrial Company (KPSC) |
| Tarboosh Packaging Co. LLC |
| Arabian Packaging Co. LLC |
| International Packaging Company LLC |
| Green Bags UAE |
| ENPI Group |
| Others |
Supply & Pricing Matrix
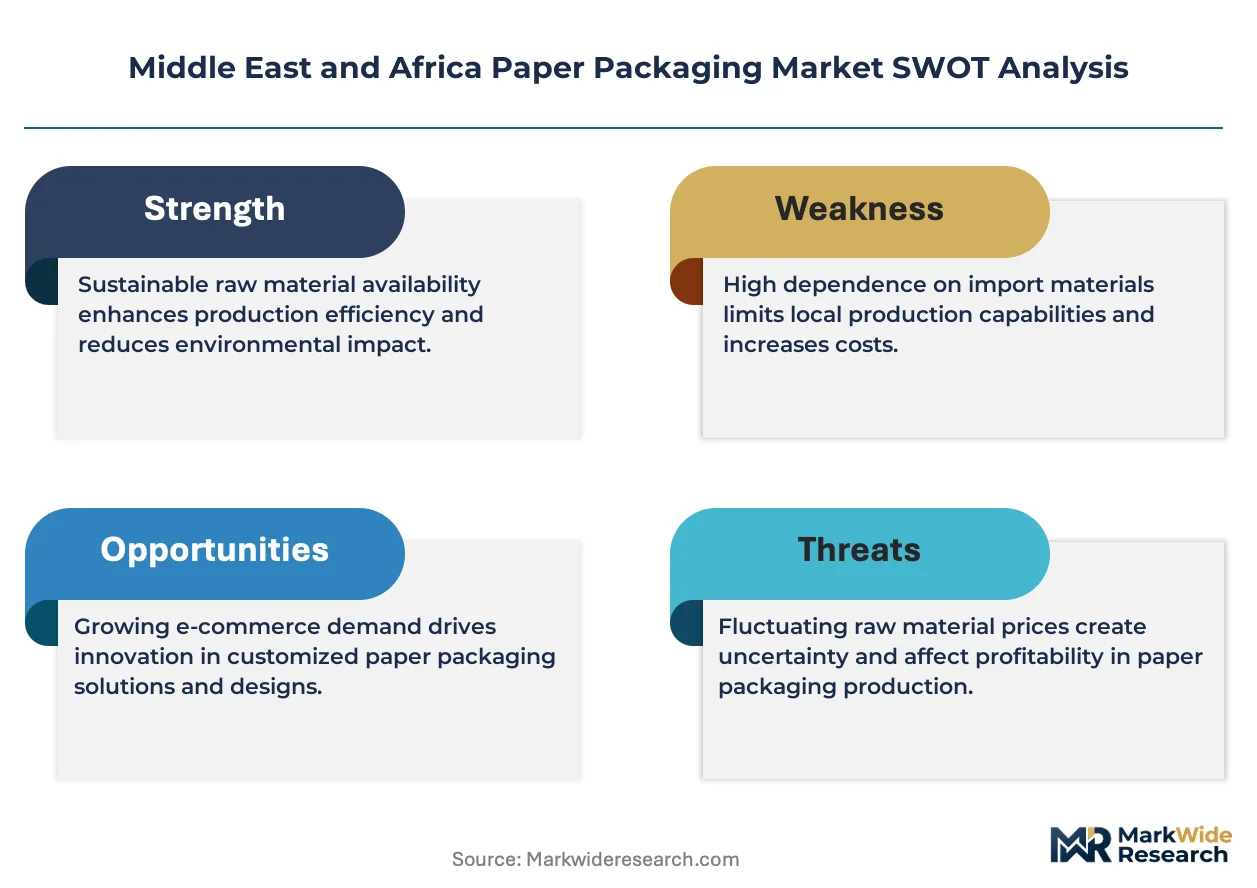
Saudi Arabia's extended producer responsibility framework gates both qualified supply and premium-tier pricing access, as converters without certified recycled fiber chains face exclusion from government procurement and forfeit EPR credit eligibility that subsidizes competitive positioning.
Pricing Analysis
Margin tightening in standard-grade containerboard reflects yield limitations from inconsistent post-consumer fiber collection infrastructure across Egypt and Morocco. Three-tier pricing structure across premium barrier-coated, standard food-grade, and economy industrial grades differentiates on migration testing certification and volume scale. Cost-down pressure on economy grades accelerates because import substitution enforcement restricts government procurement to domestic converters regardless of quality differentials. Quick-service restaurant chains in the Gulf Cooperation Council corridor demonstrate lowest price sensitivity due to consolidated sourcing mandates, while fragmented North African agricultural exporters negotiate hardest on per-unit basis.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from pan-Gulf foodservice distributors consolidating procurement across paperboard and flexible formats. Geographic supply concentration centers on Saudi Arabia, the United Arab Emirates, and South Africa, where Jeddah, Dubai, and Johannesburg industrial zones anchor converting capacity. Raw material dependencies draw from imported bleached chemical pulp, regional kraft linerboard, and post-consumer recovered fiber streams. Single-source vulnerability in certified laboratory infrastructure for Saudi Standards, Metrology and Quality Organization migration testing creates compliance bottlenecks that filter import volumes toward domestic Gulf converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, where South Africa's extended producer responsibility regulations erect a barrier-to-entry moat that rewards converters with verified post-consumer fiber chains and penalizes uncertified competitors.
For Market Incumbents: Cement dominance in the Gulf Cooperation Council corridor by expanding water-based barrier coating capacity to capture quick-service restaurant procurement consolidation. Deepen backward integration into de-inking operations near Johannesburg and Durban to secure EPR credit eligibility against emerging mill investments in Egypt and Morocco.
For New Entrants and Emerging Players: Enter via East African quick-service restaurant supply gaps in Ethiopia and Kenya, where regional converters lack customized paperboard packaging capability. Target agricultural export logistics from Moroccan tomato and Egyptian citrus shippers as the most penetrable segment, leveraging proximity to European retail compliance windows as the go-to-market angle.
For Investors and Strategic Acquirers: Gulf Standardization Organization alignment lag is the leading indicator that multi-jurisdiction compliance testing burdens will consolidate supplier rosters toward converters with cross-category production capability. Acquisition target archetypes are mid-scale UAE-based players with certified laboratory networks and folding carton flexibility. Watch for de-inking technician scarcity signals as inflection points for automation investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Capacity Expansion | Captures quick-service restaurant procurement cycles in Saudi Arabia and the UAE with grease-resistant board specifications. |
| Recycled Fiber Certification Investment | Secures EPR credit eligibility under South Africa's extended producer responsibility framework for Western Cape produce exporters. |
| Cross-Format Production Integration | Meets consolidated sourcing mandates from pan-Gulf foodservice distributors eliminating fragmented vendor management overhead. |
| Regional De-Inking Mill Investment | Reduces yield limitations from inconsistent post-consumer fiber collection infrastructure near Alexandria and Cairo. |
| Certified Laboratory Network Expansion | Filters import volumes toward domestic converters meeting Saudi Standards, Metrology and Quality Organization migration testing requirements. |
Research Methodology
Trade statistics from regional customs authorities, mill capacity disclosures from packaging industry associations, and regulatory filings from Saudi Standards, Metrology and Quality Organization formed the secondary backbone. Primary interviews with corrugated plant managers, quick-service restaurant procurement directors, de-inking process engineers, agricultural export logistics coordinators, and EPR compliance officers at brand owners combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across installed capacity, fiber input costs, and converter margin structures established baseline trajectories. Segmentation dimensions modeled include product type, end-use industry performance requirements, material feedstock sourcing strategy, and distribution channel concentration throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce fulfillment expansion rates and agricultural export volume trends as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent national implementation timelines for Gulf Standardization Organization food-contact alignment. Periodic stress-testing of base assumptions is recommended against recycled pulp supply concentration risks and hot-climate barrier coating cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Envelope Paper Market