
 Global Corrugated Board Packaging Market | 2026-2036
Global Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corrugated Board Packaging Market Analysis
E-commerce logistics is restructuring corrugated demand as fulfillment networks shift from bulk B2B shipments toward individual parcel formats. DS Smith Plc specializes in recycled-content packaging systems for online retail chains across Europe. International Paper Company dominates North American containerboard supply through integrated pulp-to-box manufacturing. Mondi Group Plc extends its corrugated footprint into emerging African and Middle Eastern markets via regional mill investments.
Corrugated board consists of fluted paper medium sandwiched between flat linerboard sheets, typically manufactured through steam-heated corrugating rollers at speeds exceeding 300 meters per minute to produce compressive strength ratings between 150 and 275 psi for standard single-wall grades. Its primary purpose is protective containment and stackable distribution of goods across supply chains. Double wall and triple wall configurations lead in heavy-duty shipping and export applications where stacking strength determines freight economics. Die-cut formats represent the fastest-growing product category as brand owners demand shelf-ready retail packaging that eliminates secondary display assembly.
The EPA regulates recycled fiber content thresholds and wastewater discharge from corrugated mills under Clean Water Act permits, while the EU Green Deal mandates extended producer responsibility schemes that elevate fiber recovery targets above plastic alternatives. China's MEE enforces stricter VOC emission limits on printing and adhesive operations at packaging plants, reshaping capital allocation toward water-based ink systems. Stakeholders must monitor how diverging national recycling infrastructure investments determine regional cost competitiveness for post-consumer fiber sourcing.
Market Dynamics
E-commerce fulfillment networks are compressing order batch sizes from pallet-scale B2B shipments to single-unit parcel flows, forcing corrugated converters to retool for short-run die-cut production with rapid changeover capabilities.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes elevate fiber recovery targets above plastic alternatives, accelerating substitution in food contact and retail display applications.
- India manufacturing clustering:Industrial corridor development around Mumbai, Delhi, and Chennai concentrates corrugated demand from automotive, electronics, and pharmaceutical exporters seeking compliant export packaging.
- Water-based ink systems:China's MEE enforcement of stricter VOC emission limits drives capital migration toward compliant printing technologies, opening retrofit service markets.
Market Restraints
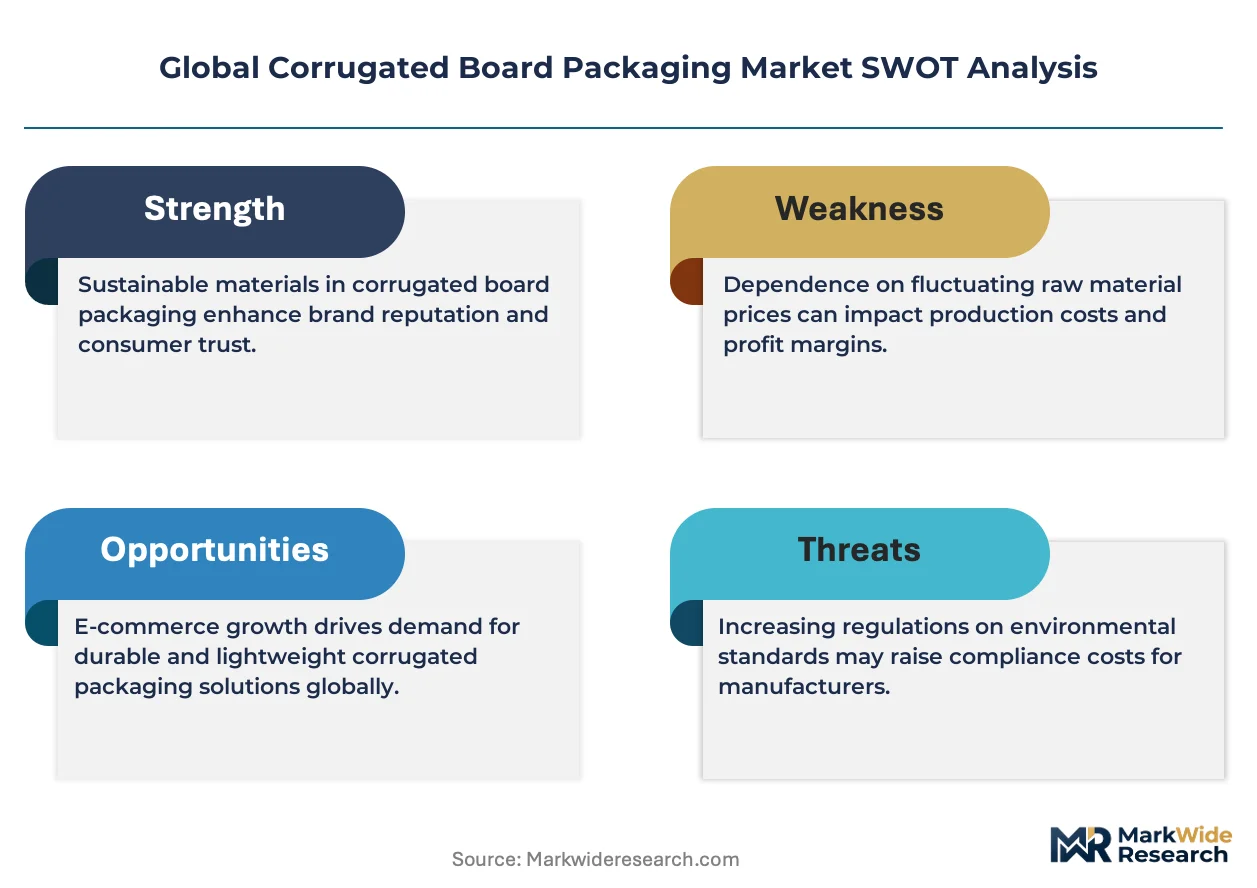
- Recycled fiber cost volatility:Post-consumer OCC (old corrugated containers) pricing fluctuates with municipal collection infrastructure investments, squeezing converter margins when recovery rates lag demand.
- Linerboard supply concentration:Integrated pulp-to-box producers control North American kraft linerboard supply, limiting independent converter bargaining power during capacity tightness.
- Plastic barrier coatings:Polyethylene-laminated corrugated retains moisture resistance advantages for fresh produce and frozen goods, slowing fiber substitution in wet-food logistics.
Strategic Opportunities
- Saudi Arabia logistics corridor expansion:Red Sea port modernization and domestic manufacturing zones under Vision 2030 create demand for heavy-duty triple-wall export packaging with ISPM-15 compliance.
- Smart packaging sensor integration:RFID-enabled corrugated tracking tags converge with IoT logistics platforms, enabling condition-monitoring premiums in pharmaceutical and high-value electronics cold chains.
- German battery cell manufacturing:Gigafactory construction around Salzgitter and Heide requires flame-retardant corrugated formats for lithium-ion cell transport and UN 38.3 certification support.
Industry Challenges
- Die-cutting tooling specialization:Short-run e-commerce formats demand rapid knife-change expertise that legacy flexo-folder-gluer operators lack, widening plant productivity gaps.
- Water treatment capex burdens:Clean Water Act permit compliance for dissolved solids and BOD discharge requires anaerobic digester or membrane bioreactor investments that strain mid-cap mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corrugated Board Packaging Market |
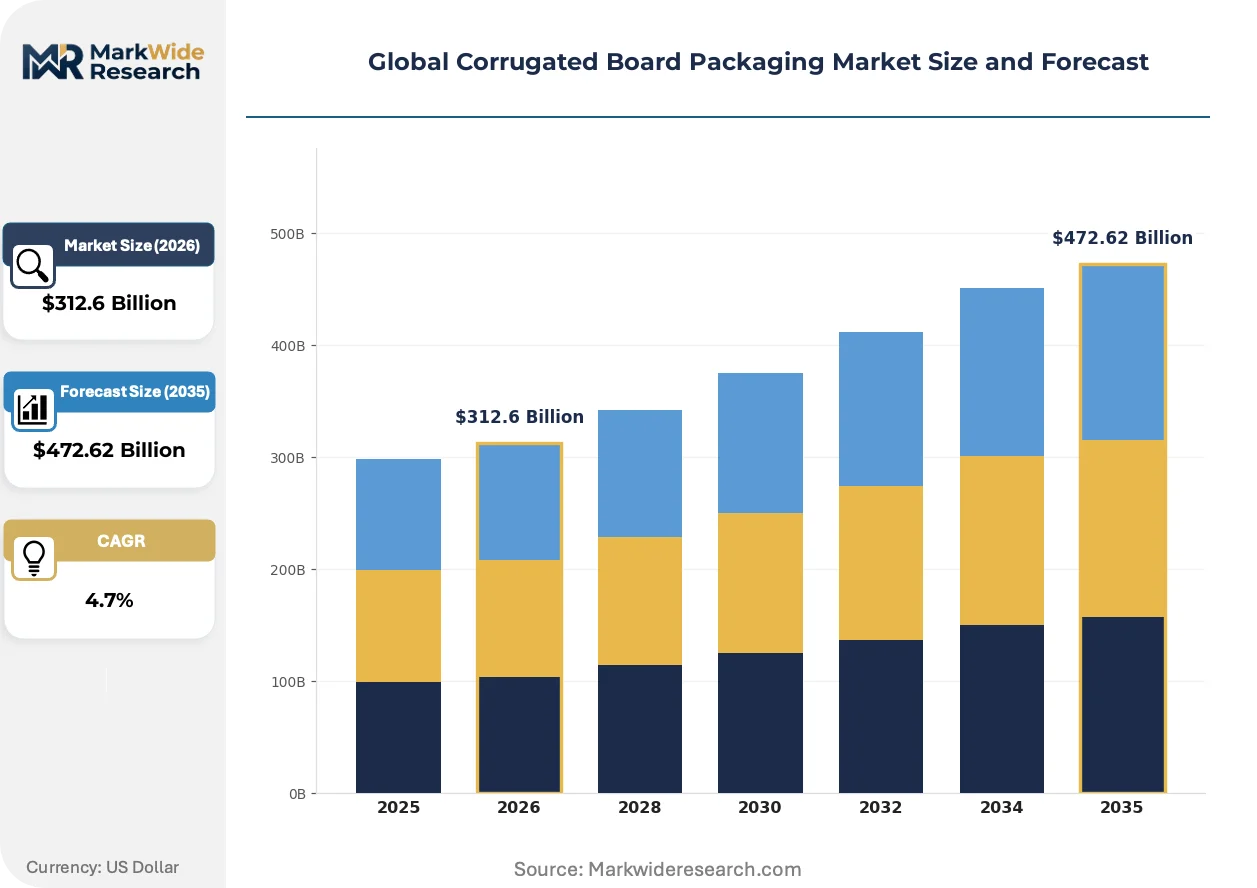
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Faced, Double Wall, Triple Wall, Die-Cut End User: Food & Beverage, Electronics, Personal Care, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors Application: Shipping, Storage, Retail Packaging, Export |
| Companies Covered | DS Smith Plc, Packaging Corporation of America, Smurfit Kappa Group, Cascades Inc., Rengo Co. Ltd., International Paper Company, Mondi Group Plc, Georgia-Pacific LLC, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corrugated Board Packaging Market Emerging Trajectories
Digital printing and automation are collapsing minimum order quantities while regulatory pressure on plastic packaging accelerates fiber-based innovation cycles across protective and display applications.
Nanocellulose barrier coatings are absorbing moisture-protection functions previously served by polyethylene laminates. Food exporters in the Netherlands and Belgium are piloting these formats for chilled meat and seafood shipments. The technology is absorbing share from conventional plastic-lined board as shelf-life validation completes and coating speeds match existing corrugator lines.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) in food contact materials are eliminating grease-resistant fluorinated treatments from European corrugated supply chains. German and French converters are migrating to bio-based wax and clay alternatives for pizza boxes and bakery trays. Bakery chains and QSR operators face reformulation deadlines that compress supplier qualification timelines.
Subscription box procurement models are consolidating corrugated specification authority with third-party logistics providers rather than brand marketing departments. Fulfillment operators in Poland and the Czech Republic now dictate board grade, print coverage, and dimensional standards across multiple consumer verticals. This concentration shifts margin pressure upstream to converters while standardizing format specifications regionally.
Global Corrugated Board Packaging Market Segmentation
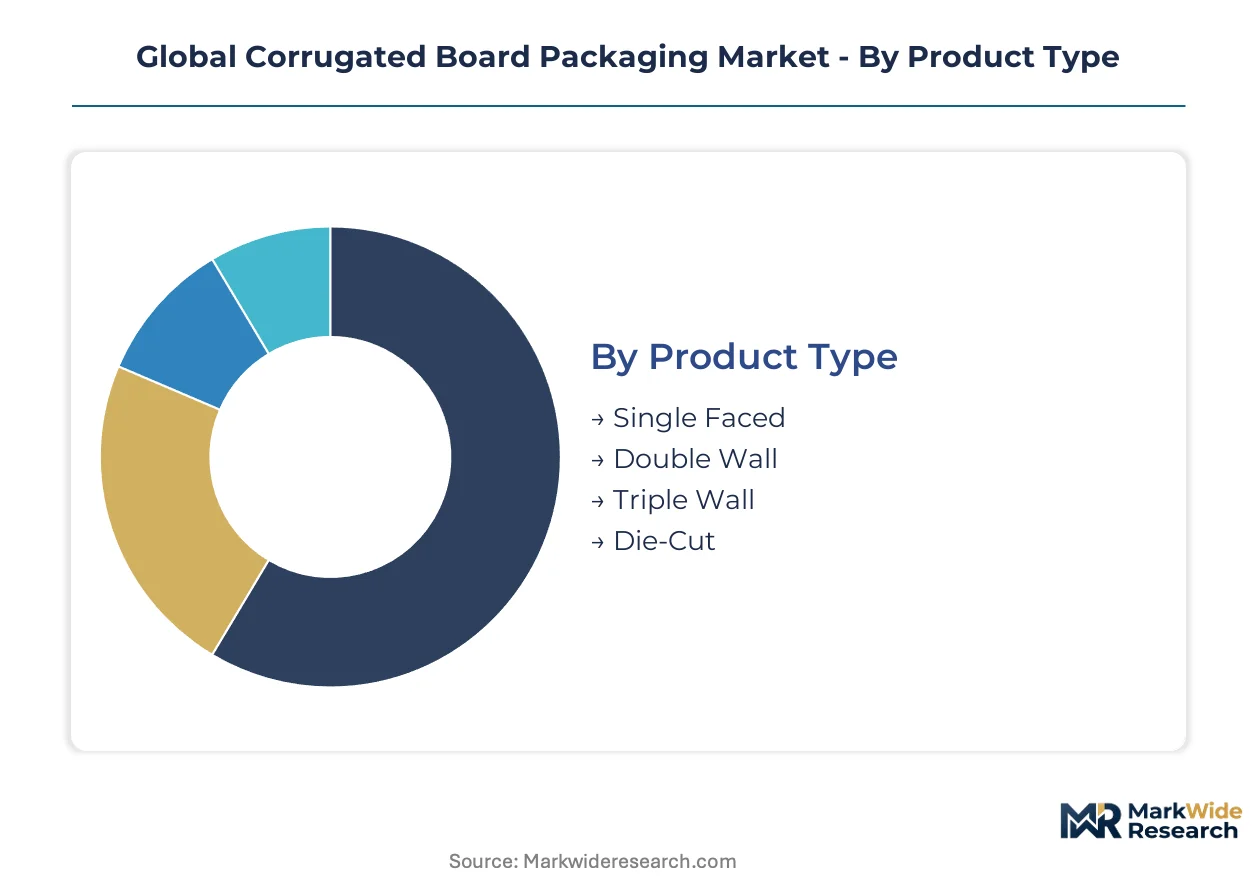
Corrugated board segmentation reveals how capital deployment, regulatory exposure, and end-use durability requirements fragment manufacturing strategies. Product configuration determines corrugator investment scale, while end-user concentration shapes regional mill siting decisions.
Product Type:
Capital intensity escalates sharply with wall count and precision cutting capability, separating commodity producers from specialty converters.
- Single Faced:One flat linerboard bonded to a single fluted medium creates lightweight cushioning for interior protective wraps and void fill. Demand concentrates in German automotive component supply chains where just-in-time delivery requires collapsible, low-cube packaging formats that minimize inbound freight costs from Eastern European supplier parks.
- Double Wall:Two fluted mediums separated by three linerboard layers deliver stacking strength for warehouse palletization and medium-duty distribution. E-commerce fulfillment centers in Poland and the Czech Republic specify this grade for parcel shipments between 15 and 30 kilograms, balancing protection against dimensional weight pricing penalties from courier networks.
- Triple Wall:Heavy-duty export applications including machinery and automotive parts bound for Saudi Arabia's Red Sea ports.
- Die-Cut:Shelf-ready retail formats with pre-scored folding lines and window cutouts for Belgian and Dutch food exporters seeking display-ready delivery.
Double wall absorbs the bulk of installed capacity; die-cut is expanding most quickly.
End User:
Regulatory stringency and contamination risk separate food-grade specifications from industrial tolerances, driving divergent certification requirements.
- Food & Beverage:Direct-contact corrugated for fresh produce and chilled meat demands EU-compliant barrier coatings and migration-tested adhesives. Dutch and Belgian exporters pilot nanocellulose moisture barriers to replace polyethylene laminates under EFSA scrutiny, while German bakery chains face REACH-mandated PFAS phaseouts for grease-resistant pizza boxes.
- Electronics:Anti-static and shock-dampening specifications dominate semiconductor and consumer device shipments from Indian manufacturing clusters around Mumbai and Chennai. Water-based ink systems from China's MEE compliance drive are penetrating this segment as brand owners demand VOC-free printing for premium unboxing experiences.
- Personal Care:Subscription box consolidation in Polish fulfillment networks standardizes board grades across cosmetics and household goods.
- Pharmaceuticals:Temperature-validated cold chain formats with RFID integration for EU GDP compliance.
Food and beverage commands the largest share of food-grade certified capacity; pharmaceuticals is climbing the fastest on cold-chain validation premiums.
Distribution Channel:
Channel selection determines specification authority, with direct relationships enabling custom engineering and aggregated procurement driving standardization.
- Direct Sales:Converter-to-brand relationships for high-volume automotive and electronics manufacturers permit collaborative design of part-specific dunnage and returnable loops. German battery gigafactories around Salzgitter negotiate directly for UN 38.3 certified flame-retardant formats.
- Online Retail:Third-party logistics providers in Poland and the Czech Republic now dictate corrugated specifications across multiple consumer verticals, consolidating procurement power and squeezing converter margins through standardized format mandates.
- Wholesalers:Inventory buffering for small-batch industrial users in Indian pharmaceutical corridors.
- Distributors:Regional stockholding for fragmented agricultural and fresh produce shippers.
Direct sales retains the deepest engineering relationships; online retail is gaining share fastest on fulfillment network consolidation.
Application:
Application context determines whether strength, print quality, or disposability receives priority in specification trade-offs.
- Shipping:Parcel-grade single and double wall formats optimized for automated sortation compatibility and drop-test survival. E-commerce volume through Saudi Arabia's Vision 2030 logistics corridors is accelerating demand for ISPM-15 compliant heat-treated board for cross-border flows.
- Storage:Warehouse palletization demands compressive strength ratings that favor double and triple wall configurations for Indian electronics exporters stockpiling inventory near Mumbai and Chennai ports.
- Retail Packaging:Shelf-ready die-cut formats with high-graphic print coverage for Belgian supermarket chains.
- Export:Heavy-duty triple wall with ISPM-15 phytosanitary certification for Saudi Red Sea port modernization projects.
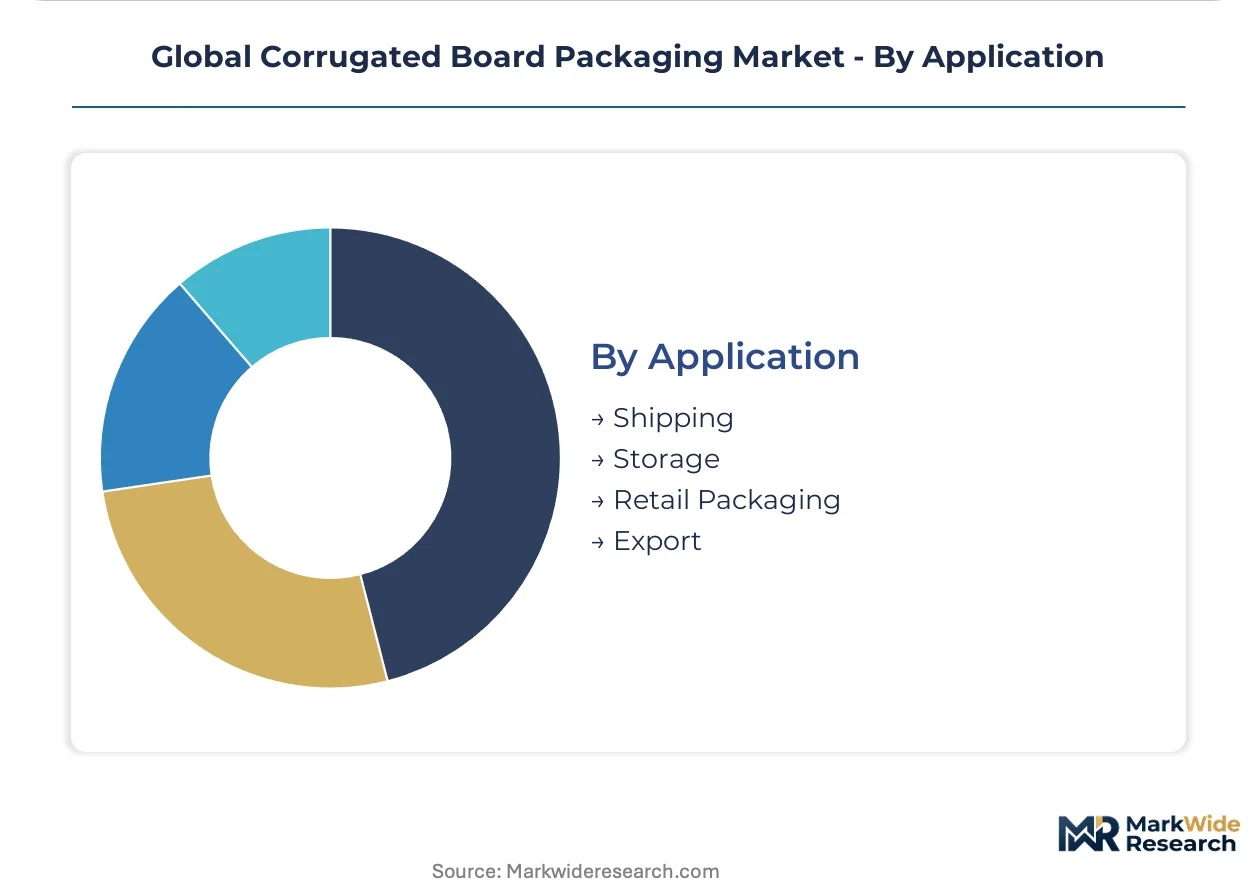
Shipping dominates volume throughput; retail packaging is expanding most quickly on brand owner demand for display-ready delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces nearly half of global containerboard output yet Germany and the United States remain the largest per-capita consumers of high-specification corrugated formats. This production-consumption divide shapes trade flows, mill investment patterns, and regional specialization in linerboard versus converting capacity.
China
E-commerce parcel volume through Alibaba and JD.com logistics networks drives demand for lightweight single-wall formats optimized for automated sortation. The MEE enforces stricter VOC emission limits on printing operations, accelerating water-based ink adoption in Zhejiang and Guangdong provinces. Manufacturing clusters around Shenzhen and Dongguan retool for short-run die-cut production to serve cross-border direct-to-consumer exports.
Germany
Battery gigafactory construction around Salzgitter and Heide requires flame-retardant corrugated for lithium-ion cell transport under UN 38.3 protocols. REACH restrictions on PFAS eliminate grease-resistant fluorinated treatments, forcing bakery chains toward bio-based wax alternatives. Industrial packaging demand concentrates in Baden-Württemberg automotive supplier parks serving just-in-time delivery to assembly plants.
United States
EPA Clean Water Act permits regulate dissolved solids discharge from integrated pulp-to-box mills in the Southeast. E-commerce fulfillment networks compress order batch sizes from pallet-scale B2B to single-unit parcels, reshaping converter equipment in Indiana and Ohio. International Paper and Georgia-Pacific control kraft linerboard supply, limiting independent converter bargaining power during capacity tightness.
India
Industrial corridor development around Mumbai, Delhi, and Chennai concentrates demand from automotive, electronics, and pharmaceutical exporters. BIS certification requirements for food-grade corrugated tighten specification compliance for domestic dairy and processed food distribution. Electronics manufacturing clusters in Tamil Nadu specify anti-static board formats for semiconductor shipments to European and North American markets.
Saudi Arabia
Red Sea port modernization and domestic manufacturing zones under Vision 2030 create demand for heavy-duty triple-wall export packaging with ISPM-15 phytosanitary compliance. Logistics corridor expansion through Jeddah and King Abdullah Economic City attracts converter investment for regional distribution hub serving African and Levantine markets. SFDA regulations on pharmaceutical cold chain packaging drive temperature-validated format adoption for vaccine and biologic distribution.
Global Corrugated Board Packaging Market Vendor Landscape
Top-tier vendors anchor integrated pulp-to-box manufacturing, while mid-cap converters compete on die-cutting specialization and regional logistics proximity. The vendor base stratifies across three tiers: multinational integrated producers with captive fiber supply, regional converters with short-run flexibility, and niche specialists in barrier-coated or flame-retardant formats. Two dominant competitive moves are reshaping positions: capacity expansion in emerging markets and strategic partnerships with third-party logistics providers to secure e-commerce volume commitments.
Among North American integrated producers, International Paper Company and Georgia-Pacific LLC occupy positions defined by captive linerboard supply and scale economics. DS Smith Plc and Mondi Group Plc exemplify European-based specialists expanding through recycled-content systems and regional mill investments. WestRock Company and Smurfit Kappa Group sit within the tier pursuing consolidation synergies across corrugated and consumer packaging portfolios.
| Leading Market Players |
|---|
| DS Smith Plc |
| Packaging Corporation of America |
| Smurfit Kappa Group |
| Cascades Inc. |
| Rengo Co. Ltd. |
| International Paper Company |
| Mondi Group Plc |
| Georgia-Pacific LLC |
| WestRock Company |
| Others |
Supply Flow & Price Mechanics
Old corrugated container (OCC) index movements cascade through converter pricing tiers, with post-consumer fiber volatility compressing margins for independent operators while integrated producers capture spread advantages through captive pulp supply.
Pricing Analysis
Margin tightening in standard-grade board reflects OCC cost pass-through limitations during municipal collection shortfalls. Three-tier pricing structure across premium, standard, and economy levels separates food-grade certified formats with EFSA migration testing from industrial tolerances and generic shipping grades. Cost-down pressure on die-cut formats accelerates because Polish fulfillment networks consolidate procurement authority across multiple consumer verticals. Brand owners exhibit lowest price sensitivity for pharmaceutical cold-chain formats with GDP compliance, while agricultural shippers face acute elasticity.
Supply Chain Analysis
Regional distribution centers in Jeddah and King Abdullah Economic City anchor hub-and-spoke patterns for Red Sea corridor exports. Manufacturing concentrates in China, Germany, and the United States, with linerboard supply drawing from integrated pulp-to-box mills in the US Southeast and recycled fiber systems in Europe. Feedstock risk centers on single-source dependency for kraft linerboard from International Paper and Georgia-Pacific during capacity tightness. Distribution runs through converter-to-brand direct sales for automotive and battery manufacturers, with third-party logistics providers intermediating e-commerce volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated board packaging is becoming a vertical-integration race, with players pursuing upstream control over recycled fiber supply to defend margin structures against OCC volatility.
For Market Incumbents: Hedge fiber cost exposure through backward integration into municipal collection partnerships or long-term OCC offtake agreements with European waste management operators. Defend market position by accelerating water-based ink retrofit capabilities ahead of China's MEE enforcement timelines, locking in brand owner compliance preferences.
For New Entrants and Emerging Players: E-commerce platform partnerships offer the most penetrable route for mid-cap converters lacking integrated fiber supply. Target Saudi Arabia's Vision 2030 logistics corridor expansion for heavy-duty triple-wall formats with ISPM-15 certification, where incumbent presence remains thin. Pursue die-cutting specialization for short-run pharmaceutical and electronics formats as the go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European converters with food-grade certification infrastructure in Germany and the Netherlands. Long-term viability hinges on barrier-coating R&D capabilities displacing polyethylene laminates. Watch nanocellulose shelf-life validation completion as the inflection signal for premium format adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | Captive OCC sourcing insulates margins from municipal collection volatility in European markets. |
| Water-Based Ink System Retrofit | MEE compliance in Zhejiang and Guangdong provinces opens brand owner specification locks. |
| Die-Cutting Automation Investment | Short-run flexibility captures Polish fulfillment network volume consolidating procurement authority. |
| Nanocellulose Barrier Coating Development | Moisture protection validation displaces polyethylene laminates for Dutch and Belgian food exporters. |
| ISPM-15 Certified Triple-Wall Capacity | Phytosanitary compliance secures Saudi Red Sea port modernization contracts under Vision 2030. |
Methodological Framework
Multi-period observation of OCC pricing indices, corrugator utilization rates, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with mill operations directors, converter procurement leads, brand owner packaging engineers, and third-party logistics specification managers. Secondary validation drew from EPA Clean Water Act permit databases, EU ECHA REACH substance restrictions, China's MEE emission standards, trade flow customs records, and integrated producer SEC disclosures. Bottom-up capacity modeling and top-down demand segmentation were triangulated against shipment data.
Segment-weighting across product configuration, end-use regulatory tier, and distribution channel concentration shaped the analytical framework throughout the forecast period. CAGRs were derived from installed capacity expansion schedules, e-commerce parcel volume trajectories, and fiber substitution elasticity assumptions. Corrugator line speed capabilities, barrier coating validation timelines, and fulfillment network consolidation patterns served as industry-specific forecast inputs.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time OCC spot pricing and converter contract terms introduce uncertainty bands around margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Fluting Paper Market