
 Global Disposable Plates Market | 2026-2036
Global Disposable Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Plates Market Analysis
Subscription-based replenishment programs for foodservice operators is hardening how disposable plates get sold, shifting transactions from spot purchasing to contracted volume commitments. Huhtamaki Oyj leverages its European manufacturing footprint to anchor institutional clients with predictable supply terms. Dart Container Corporation sustains dominance in North American quick-service channels through captive foam production capacity. Vegware Ltd competes by specializing exclusively in plant-fiber compostable lines, avoiding direct overlap with petroleum-based portfolios.
Disposable plates are single-use foodservice vessels manufactured from molded pulp, extruded foam, pressed paperboard, or thermoformed resins, engineered to meet FDA or EFSA food-contact migration limits for aqueous and fatty foods across defined temperature ranges. Their primary commercial purpose is to eliminate washing infrastructure and labor costs in high-volume food preparation and temporary dining environments. Sugarcane bagasse and bamboo fiber segments are capturing margin pools as EU Green Deal procurement rules and municipal composting infrastructure expand addressable volume. Plastic plate demand is mature in North America but still occupies institutional channels where cost-per-unit thresholds override material preference. Online retail and wholesale distribution channels are diverging, with e-commerce platforms targeting small restaurant replenishment while broadline distributors control stadium and hospital contracts.
FDA food-contact substance notifications, EU REACH restrictions on intentionally added microplastics, and EFSA migration testing protocols collectively determine which material formulations achieve commercial scale in regulated markets. BIS certification requirements in India and China's GB standards for food-contact plastics add compliance layers for exporters targeting those manufacturing bases. Stakeholders must monitor how compostability certification schemes from BPI and TÜV Austria interact with municipal waste stream capabilities to determine realizable pricing premiums.
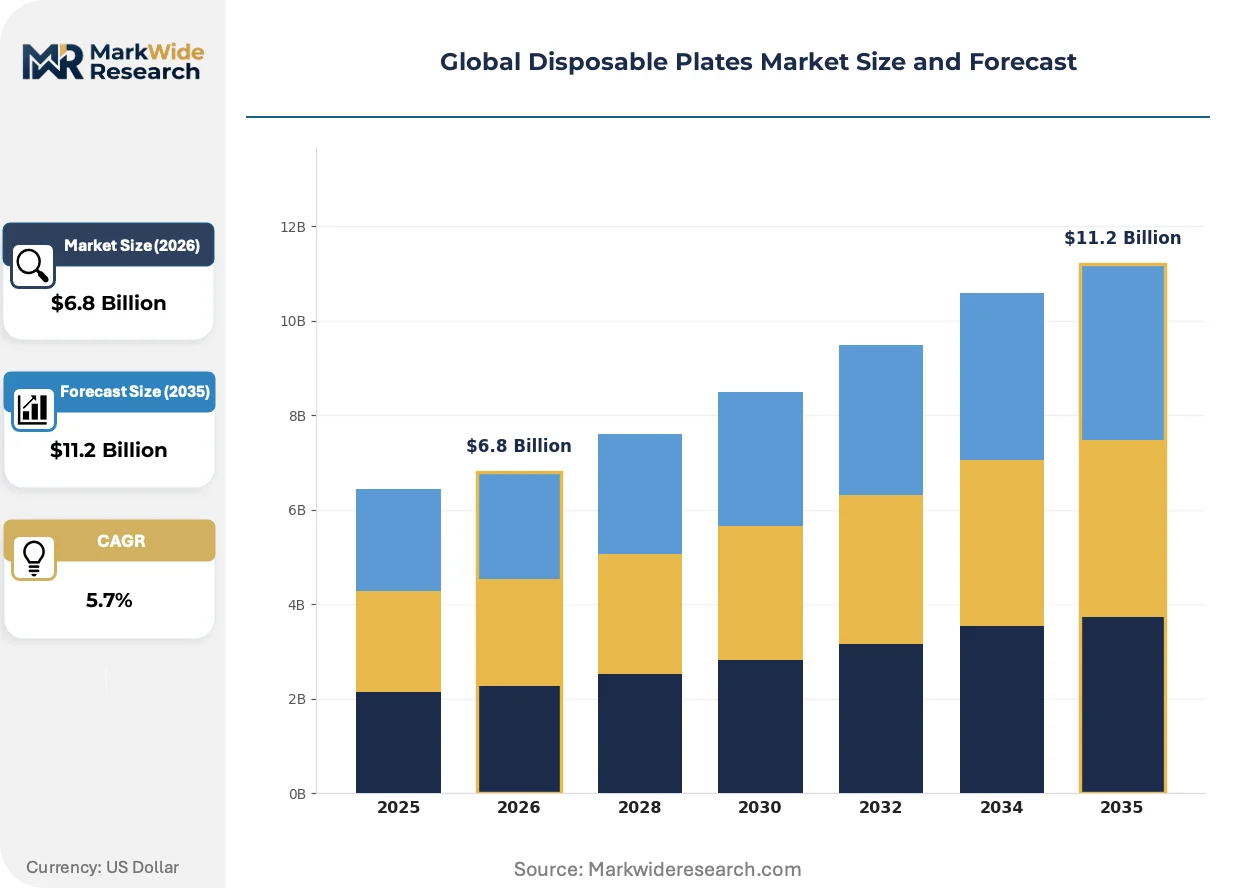
Market Dynamics
Subscription-based replenishment programs for foodservice operators are hardening how disposable plates get sold, shifting transactions from spot purchasing to contracted volume commitments with predictable supply terms.
Growth Catalysts
- EU Single-Use Plastics Directive:Binding sustainability mandates in Germany and France are forcing foodservice distributors to expand compostable serveware procurement, creating guaranteed demand pools for certified bagasse and bamboo fiber products.
- Municipal composting infrastructure:Expanded collection and processing capacity in urban waste streams is enabling realizable pricing premiums for BPI and TÜV Austria certified plates, converting environmental compliance into commercial margin.
- Quick-service restaurant labor models:Elimination of washing infrastructure and back-of-house labor costs in high-volume food preparation environments sustains structural demand for single-use vessels regardless of material substrate.
Market Restraints
- Petroleum-based resin cost volatility:Thermoformed polystyrene and polypropylene plate margins remain exposed to upstream petrochemical feedstock fluctuations, compressing price competitiveness against plant-fiber alternatives during oil price spikes.
- Compostability certification fragmentation:Divergent municipal waste stream capabilities across jurisdictions create geographic pockets where certified compostable plates receive no processing benefit, limiting addressable premium markets.
- Legacy foam production concentration:Captive North American extruded polystyrene capacity anchors institutional channel cost thresholds, delaying material substitution in price-sensitive healthcare and correctional foodservice contracts.
Strategic Opportunities
- India BIS certification pathway:Exporters targeting Indian food-contact manufacturing bases face underpenetrated demand from institutional catering and airline meal services seeking compliant molded pulp alternatives to plastic.
- E-commerce replenishment platforms:Direct-to-restaurant digital channels are capturing small operator volume previously served by broadline distributors, enabling disintermediation and recurring revenue capture.
- China GB standards alignment:Convergence between EU EFSA migration protocols and China's GB food-contact plastics standards creates unified formulation pathways for exporters serving both regulatory zones with single SKUs.
Industry Challenges
- EFSA migration testing timeline:Novel bio-based coatings and barrier layers require extended food-contact substance notification periods, delaying commercial launch windows for next-generation compostable plates.
- Supply chain reconfiguration friction:Transitioning from petroleum-based to agricultural fiber feedstocks demands new supplier qualification, inventory management, and quality control protocols across contract manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Plates Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Bamboo, Sugarcane End User: Restaurants, Catering Services, Events, Households Product Design: Round, Square, Compartmentalized, Eco-friendly Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Dart Container Corporation, Huhtamaki Oyj, Pactiv Evergreen Inc., Genpak LLC, Novolex Holdings, You Cheng, Dispo International, Vegware Ltd, Duni AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Plates Market Emerging Trajectories
Material science advances and regulatory convergence are compressing development cycles for next-generation food-contact barriers, while distribution channel fragmentation creates parallel pathways to market.
Barrier-coated molded pulp technology is absorbing moisture and grease resistance functions previously requiring plastic lamination. Stadium and hospital foodservice contractors are piloting these vessels for hot protein service. The technology is absorbing share from laminated paperboard in temperature-critical applications where compostability certification commands procurement preference.
REACH restrictions on intentionally added microplastics are tightening formulation space for conventional plastic plates across EU member states. Industrial consequence includes accelerated R&D spending on bio-based alternatives and reformulation of existing product lines to maintain market access. Quick-service channels in France and Germany are responding with explicit compostable procurement mandates in distributor contracts.
Foodservice operators are consolidating purchasing through contracted volume commitments rather than spot market transactions. Broadline distributors controlling stadium and hospital contracts face disintermediation pressure from manufacturer-direct subscription programs. This pattern is most visible in North American institutional channels where predictable usage volumes support inventory pre-positioning and just-in-time replenishment logistics.
Global Disposable Plates Market Segmentation
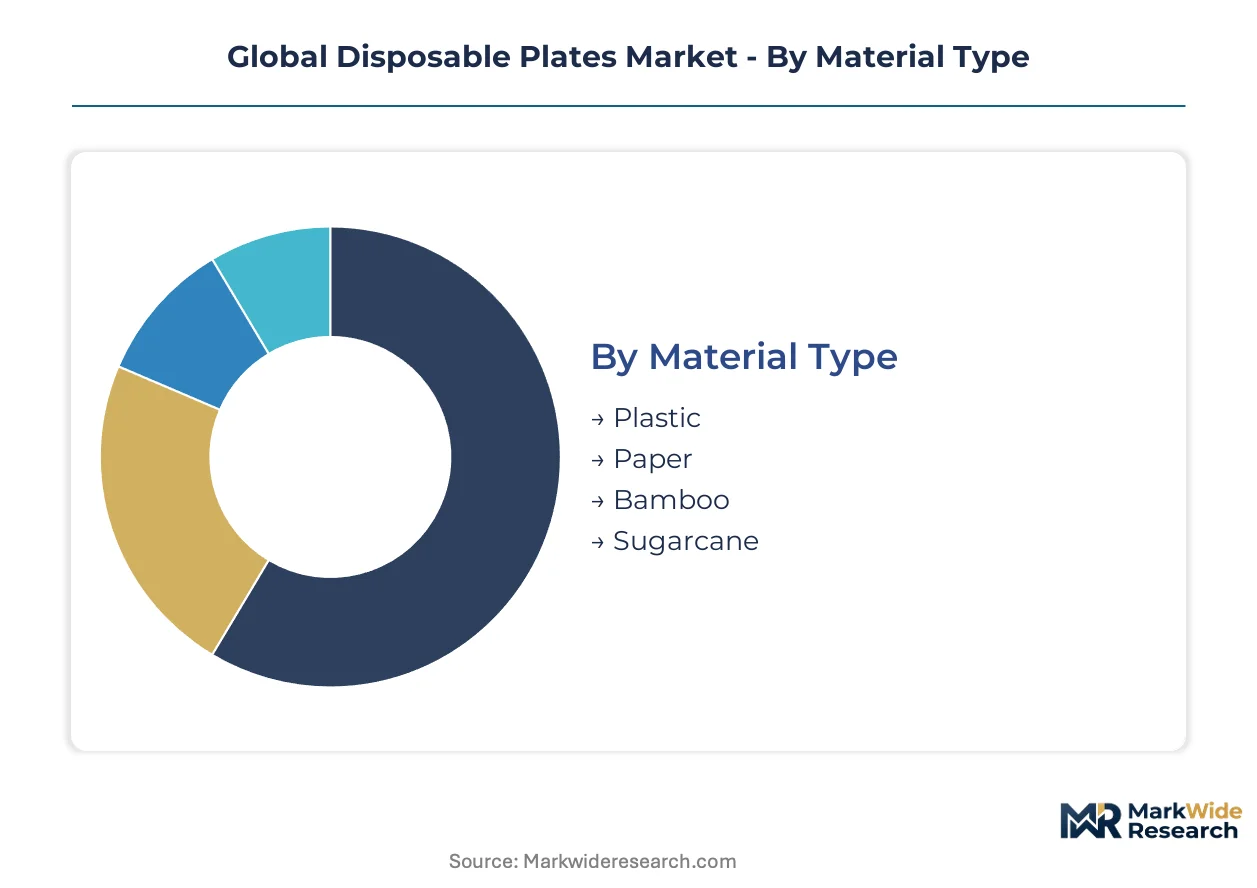
Material substrate and distribution channel configurations determine margin capture and regulatory compliance pathways for disposable plate manufacturers. Segmentation reveals how compostable alternatives command procurement premiums in institutional channels while petroleum-based products retain cost-sensitive volume.
Material Type:
Standalone single-material plates dominate foodservice procurement, while hybrid barrier constructions serve embedded temperature-critical applications requiring grease resistance.
- Plastic:Thermoformed polystyrene and polypropylene formulations engineered for FDA and EFSA migration compliance. Demand concentrates in North American healthcare and correctional foodservice contracts where cost-per-unit thresholds override material preference.
- Sugarcane:Molded bagasse fiber processed from post-extraction cane pulp, achieving BPI and TÜV Austria compostability certification. Procurement is accelerating in Germany and France where EU Single-Use Plastics Directive mandates bind distributor sourcing decisions.
- Paper:Pressed paperboard with laminated or aqueous barrier coatings for moisture resistance.
- Bamboo:Rapid-renewable grass fiber with natural antimicrobial properties, processed into molded pulp vessels.
Plastic leads volumes today; sugarcane is gaining share fastest.
End User:
Volume concentration varies sharply between contracted institutional procurement and fragmented consumer purchasing.
- Restaurants:Quick-service operators eliminating back-of-house washing infrastructure through standardized single-use vessel programs. Chains in the US and France are mandating compostable procurement in distributor contracts.
- Catering Services:Event and institutional foodservice contractors managing variable guest counts with zero washing logistics. Operators across Germany face binding sustainability mandates under EU Green Deal procurement rules.
- Events:Temporary dining environments including stadiums, festivals, and corporate gatherings.
- Households:Consumer retail purchasing for home entertaining and convenience dining.
Restaurants dominate absolute consumption; catering services show the steepest expansion trajectory.
Product Design:
Geometric and functional specifications align with food presentation requirements and waste stream compatibility.
- Round:Conventional circular geometry optimized for automated manufacturing and stacking logistics. Universal acceptance across quick-service and institutional channels maintains baseline volume.
- Compartmentalized:Multi-section designs separating proteins, starches, and sauces for dietary and portion control. Hospital and school foodservice contractors in France specify these for patient and student meal programs.
- Square:Angular geometry maximizing storage density and contemporary presentation aesthetics.
- Eco-friendly:Designs emphasizing reduced material mass, unbleached fiber visibility, and compostability certification compatibility.
Round configurations anchor production volumes; compartmentalized designs are climbing the fastest.
Distribution Channel:
Channel selection determines customer reach, margin retention, and inventory positioning economics.
- Wholesale:Broadline distributors controlling stadium, hospital, and correctional contracts through volume commitments and just-in-time replenishment logistics. Huhtamaki Oyj anchors institutional clients with predictable supply terms through this channel.
- Online Retail:Direct-to-restaurant digital platforms capturing small operator volume previously served by distributors. E-commerce enables disintermediation and recurring revenue capture for replenishment programs.
- Supermarkets:Retail shelf placement targeting household consumers and small foodservice operators.
- Convenience Stores:Limited-assortment retail for immediate-need purchasing and emergency replenishment.
Wholesale channels command the largest volume flows; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France enforce stricter compostable procurement rules than the United States, where cost-driven healthcare contracts still favor conventional materials. This regulatory divergence is fragmenting manufacturer strategies across three continents.
United States
Quick-service restaurant chains drive volume through standardized single-use vessel programs. FDA food-contact substance notifications govern which formulations achieve commercial scale. Georgia and Michigan host concentrated foam production capacity serving institutional healthcare and correctional foodservice contracts.
Germany
Catering services and institutional foodservice contractors face binding sustainability mandates under EU Green Deal procurement rules. ECHA REACH restrictions on intentionally added microplastics accelerate bagasse and bamboo fiber substitution. The Rhine-Ruhr industrial corridor anchors compostable plate manufacturing for distributor networks.
France
Hospital and school foodservice contractors specify compartmentalized designs for patient and student meal programs. ANSM enforces strict food-contact compliance alongside EU Single-Use Plastics Directive implementation. The Île-de-France region concentrates demand from Paris metropolitan catering and event services.
China
GB standards for food-contact plastics create unified formulation pathways for exporters serving both Asian and European regulatory zones. MIIT oversees industrial compliance while municipal composting pilots expand in tier-one cities. The Yangtze River Delta hosts molded pulp manufacturing clusters supplying airline meal services.
India
Institutional catering and airline meal services seek BIS-certified molded pulp alternatives to plastic in underpenetrated demand segments. FSSAI coordinates with BIS on food-contact safety protocols. Maharashtra and Gujarat industrial zones develop export-oriented bagasse processing capacity for Middle Eastern and Southeast Asian markets.
Global Disposable Plates Market Vendor Landscape
Top-tier vendors anchor contracted institutional supply, while mid-cap specialists capture premium compostable niches. The market structure reflects petroleum-based legacy capacity competing against agricultural fiber entrants. Three archetypes dominate: diversified packaging conglomerates with captive resin production, pure-play compostable specialists, and regional distributors with private-label manufacturing. Capacity expansion and certification portfolio diversification represent the dominant competitive moves as regulatory windows narrow.
Within the diversified packaging tier, Dart Container Corporation and Huhtamaki Oyj occupy positions reflecting divergent geographic footprints and material strategies. Dart exemplifies North American scale-driven production anchored in foam technology. Huhtamaki represents European-centric supply chain integration with institutional contract anchoring. Vegware Ltd sits within the pure-play compostable specialist archetype, avoiding direct portfolio overlap with petroleum-based competitors.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Huhtamaki Oyj |
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Novolex Holdings |
| You Cheng |
| Dispo International |
| Vegware Ltd |
| Duni AB |
| Others |
Supply Flow & Price Mechanics
Captive bagasse processing in India and Thailand anchors cost positions for compostable plate manufacturers serving EU markets, while petroleum-based competitors in the United States defend margins through backward integration into resin production. This divergence in integration depth creates pricing power asymmetries that favor agricultural fiber entrants during oil price volatility but exposes them to agricultural commodity swings.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for BPI-certified compostable plates as EFSA-compliant domestic supply reduces import dependency. Three-tier pricing structure across certified compostable, standard molded pulp, and conventional plastic tiers reflects certification grade and volume scale differentials. Cost compression in the plastic tier is intensifying because polystyrene resin feedstock volatility compresses margins against plant-fiber alternatives. Healthcare and correctional foodservice contractors in the United States remain most price-sensitive, while catering services in France and Germany accept premiums for EU Green Deal compliance.
Supply Chain Analysis
Freight cost differentials between Asian agricultural fiber sources and European manufacturing hubs are narrowing as Rhine-Ruhr compostable plate capacity scales. Supply concentrates in China, India, and Germany for molded pulp processing, with bagasse feedstock drawing from Guangxi cane regions and Maharashtra industrial zones. Raw material dependencies rest on sugarcane bagasse, bamboo fiber, and polystyrene resin supplies. Single-source vulnerability in EU composting infrastructure certification creates bottleneck risk for premium tier access. Distribution runs through broadline foodservice distributors controlling stadium and hospital contracts, with e-commerce platforms capturing disintermediated small restaurant volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers can exploit arbitrage between India's BIS certification pathway and Europe's EFSA migration protocols, converting lower compliance costs in Asian manufacturing bases into margin capture across regulated European procurement channels.
For Market Incumbents: Cement institutional contract renewals by embedding subscription-based replenishment logistics that lock out competitors through inventory pre-positioning at distributor warehouses. Add captive compostable capacity in the Rhine-Ruhr corridor to defend against bagasse specialists capturing EU Green Deal procurement mandates. Prioritize BPI and TÜV Austria certification portfolio expansion to maintain premium tier access as REACH microplastic restrictions tighten formulation space for conventional plastics. For New Entrants and Emerging Players: Launch via direct-to-restaurant e-commerce platforms targeting quick-service operators in tier-two French and German cities where broadline distributor coverage remains fragmented. Exploit underpenetrated airline catering segments in India seeking BIS-certified molded pulp alternatives to plastic meal service vessels. Lead with aqueous barrier-coated molded pulp technology that absorbs moisture resistance functions without plastic lamination, converting compostability certification into procurement preference in temperature-critical applications. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap compostable specialists because certification fragmentation and municipal waste stream capability gaps create local market pockets where regional scale commands pricing power. Target acquisition profiles emphasizing TÜV Austria or BPI certification portfolios paired with established distributor relationships in France or Germany. Watch for inflection signals in municipal composting infrastructure buildout rates across EU member states, as processing capacity expansion converts certification premiums into realized margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Processing | Captive agricultural fiber supply secures cost positions against resin volatility for EU-facing manufacturers. |
| BPI Certification Portfolio Expansion | Multi-jurisdiction compostability credentials unlock premium pricing in Germany and France procurement channels. |
| Direct-to-Restaurant E-Commerce Launch | Digital disintermediation captures small operator volume previously locked in broadline distributor relationships. |
| Rhine-Ruhr Manufacturing Footprint Expansion | Proximity to EU institutional demand reduces freight costs and accelerates just-in-time replenishment logistics. |
| Aqueous Barrier Coating R&D Investment | Moisture-resistant molded pulp technology displaces laminated paperboard in stadium and hospital hot protein service. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with foodservice distributors, procurement managers at quick-service restaurant chains, composting facility operators, and regulatory compliance officers with secondary validation. Secondary sources include FDA food-contact substance notification databases, ECHA REACH restriction filings, BPI and TÜV Austria certification registries, and EU Green Deal procurement directive documentation. Bottom-up volume modeling triangulates against top-down market sizing across material substrate and end-use dimensions.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include material type, end-user category, product design configuration, and distribution channel structure, with additional granularity on regulatory compliance tier. CAGRs derive from regression analysis of historical procurement patterns against policy implementation timelines. Industry-specific forecast inputs incorporate EFSA migration testing approval timelines and municipal composting infrastructure buildout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical feedstock price swings or accelerated EU Single-Use Plastics Directive enforcement. Forecasts reflect assumptions on certification scheme harmonization and waste stream capability convergence. A model refresh is warranted upon material change in REACH microplastic restriction scope or BIS certification requirement alignment with EFSA protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Disposable Cups Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Fresh Food Packaging Market