
 Middle East and Africa Corrugated Box Market | 2026-2036
Middle East and Africa Corrugated Box Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Corrugated Box Market Foresight
EU Green Deal export compliance requirements for packaging recyclability are shifting procurement standards for corrugated suppliers serving European-bound goods from MEA manufacturing zones. DS Smith leverages integrated paper-to-box operations across North African production hubs to sustain cost advantages. Mondi anchors its regional competitiveness through specialty kraftliner supply chains. Smurfit Kappa competes via automated corrugator investments that reduce conversion waste.
Corrugated boxes in the Middle East and Africa context are paper-based containers constructed from fluted medium sandwiched between linerboards, with burst strengths typically ranging from 150 to 275 lb per square inch depending on wall configuration, designed primarily for protective shipping and retail-ready display. Single wall configurations dominate volume throughput in food and beverage distribution due to their cost efficiency for lightweight consumer goods. Double wall segments command stronger positions in electronics and pharmaceutical end uses where stacking strength and moisture resistance carry premium value. Recycled paper material streams are gaining share as multinational buyers enforce post-consumer content thresholds across their MEA supplier networks.
Saudi Food and Drug Authority serialization rules and UAE's adoption of ISO 22000 food safety frameworks are tightening substrate traceability and print registration standards for pharmaceutical and food-grade corrugated applications. Egypt's environmental regulator is advancing industrial waste recycling quotas that reshape pulp sourcing economics for Nile Delta converters. Stakeholders must weigh certification investments against the contract consolidation patterns of multinational fast-moving consumer goods brands expanding their regional fulfillment footprints.
Market Dynamics
E-commerce fulfillment networks across the Gulf Cooperation Council corridor are compressing order-to-delivery timelines, forcing corrugated suppliers to integrate pre-print and die-cutting capabilities closer to last-mile distribution nodes.
Growth Catalysts
- SFDA Pharmaceutical Serialization:Saudi Arabia's track-and-trace mandates for drug packaging are elevating print registration and substrate traceability standards, pulling premium-grade box demand from healthcare logistics providers.
- EU Green Deal Export Compliance:Recyclability thresholds for packaging bound to European markets are redirecting procurement specifications across North African manufacturing zones toward post-consumer fiber content.
- ISO 22000 Adoption:UAE food safety frameworks are tightening hygiene and material certification requirements for corrugated containers serving retail grocery and foodservice distribution.
Market Restraints
- Recycled Pulp Supply Concentration:Egypt's industrial waste recycling quotas have tightened feedstock availability for Nile Delta converters, elevating input cost volatility against virgin kraftliner alternatives.
- Energy-Intensive Conversion:Natural gas and electricity account for substantial shares of corrugator operating costs across the region, exposing margins to utility tariff fluctuations.
- Plastic Crate Substitution:Reusable rigid packaging is capturing share in closed-loop beverage and dairy distribution where return logistics infrastructure exists.
Strategic Opportunities
- East African Underpenetration:Kenya and Ethiopia's expanding consumer goods manufacturing bases lack sufficient domestic corrugated capacity, creating import substitution openings for Gulf-based producers with logistics integration.
- Smart Packaging Convergence:Integration of RFID and printed electronics into corrugated substrates is enabling real-time shipment tracking for high-value pharmaceutical and electronics consignments.
- Direct-to-Consumer Channel Expansion:Subscription box services and meal-kit delivery platforms are generating demand for custom-printed, retail-ready corrugated formats with shorter run lengths.
Industry Challenges
- Skilled Print Technician Scarcity:High-speed flexographic press operation and color management expertise remain concentrated among a limited workforce pool across the region.
- Certification Timeline Compression:Pharmaceutical and food-grade substrate qualifications require extended validation cycles that delay contract awards from multinational FMCG brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Corrugated Box Market |
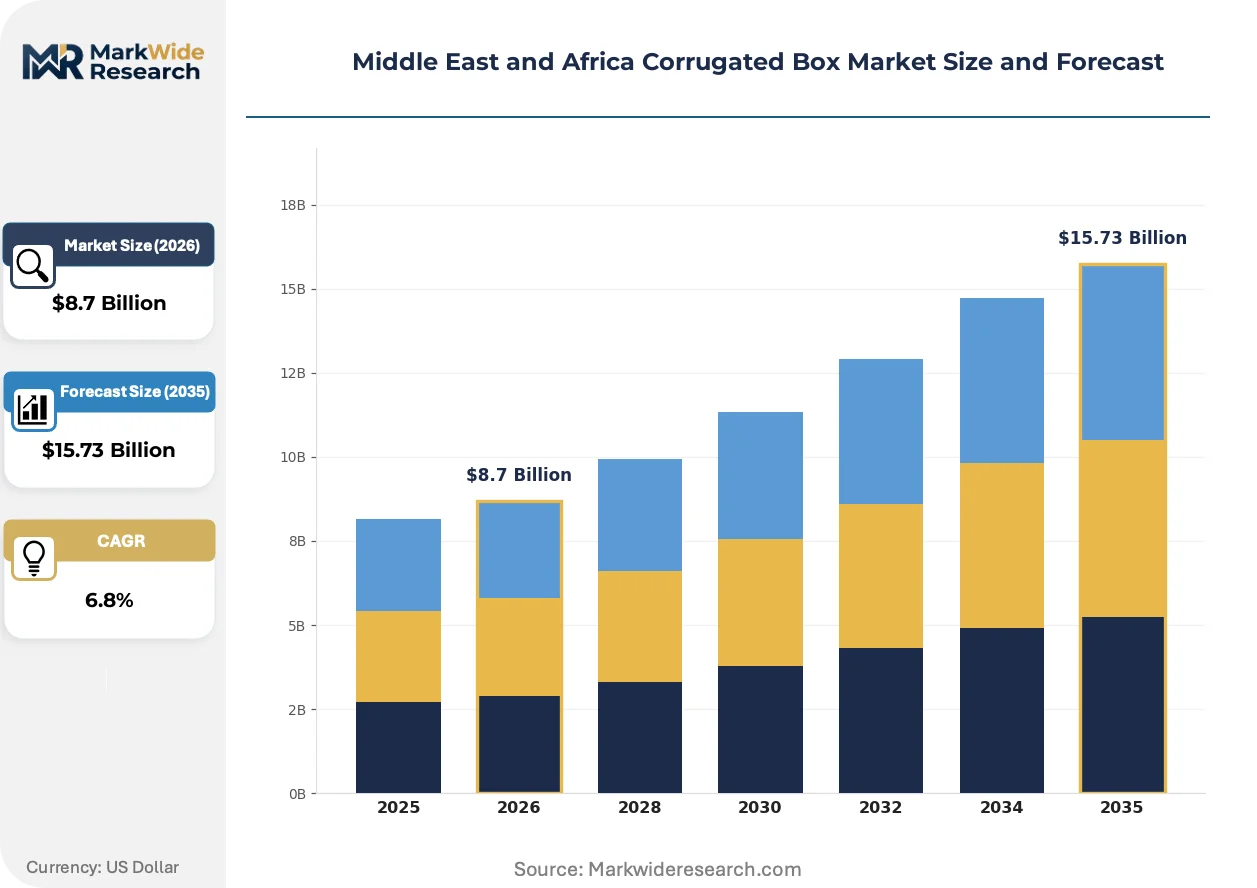
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut Material: Recycled Paper, Virgin Fiber, Combined Board, Others End User: Food & Beverage, Electronics, Pharmaceuticals, Personal Care Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retailers |
| Companies Covered | Arabian Packaging Co LLC, United Carton Industries Company, Napco National, Queenex Corrugated Carton Factory LLC, DS Smith, Mondi, International Paper, Smurfit Kappa, WestRock Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Corrugated Box Market Shifts & Advancements
Digital print technologies and automated finishing systems are restructuring production economics for corrugated converters serving fragmented, short-run demand from regional e-commerce and specialty food brands.
Water-based flexographic inks with low-VOC formulations are expanding into pharmaceutical and food-contact applications where odor migration and chemical safety carry compliance weight. Gulf-based converters serving healthcare logistics providers are adopting these ink systems to meet SFDA and MOHAP substrate safety requirements. The shift is expanding into premium retail-ready packaging segments previously dominated by offset-laminated alternatives.
EU Green Deal packaging recyclability mandates are restructuring export-oriented supply chains across North African production hubs. Suppliers serving European-bound automotive and electronics components must now document fiber sourcing and post-consumer content thresholds. Egyptian and Moroccan converters are responding by securing FSC chain-of-custody certifications and integrating de-inking capabilities for recycled linerboard production.
Consolidated procurement by multinational FMCG brands is compressing supplier bases and elevating performance-based contract terms. Regional fulfillment footprint expansions by consumer goods giants are concentrating volume with converters offering integrated design, pre-press, and just-in-time delivery capabilities. The pattern is most visible in Saudi Arabia and UAE where retail modernization and hypermarket channel growth are synchronizing packaging demand with distribution center replenishment cycles.
Middle East and Africa Corrugated Box Market Segmentation
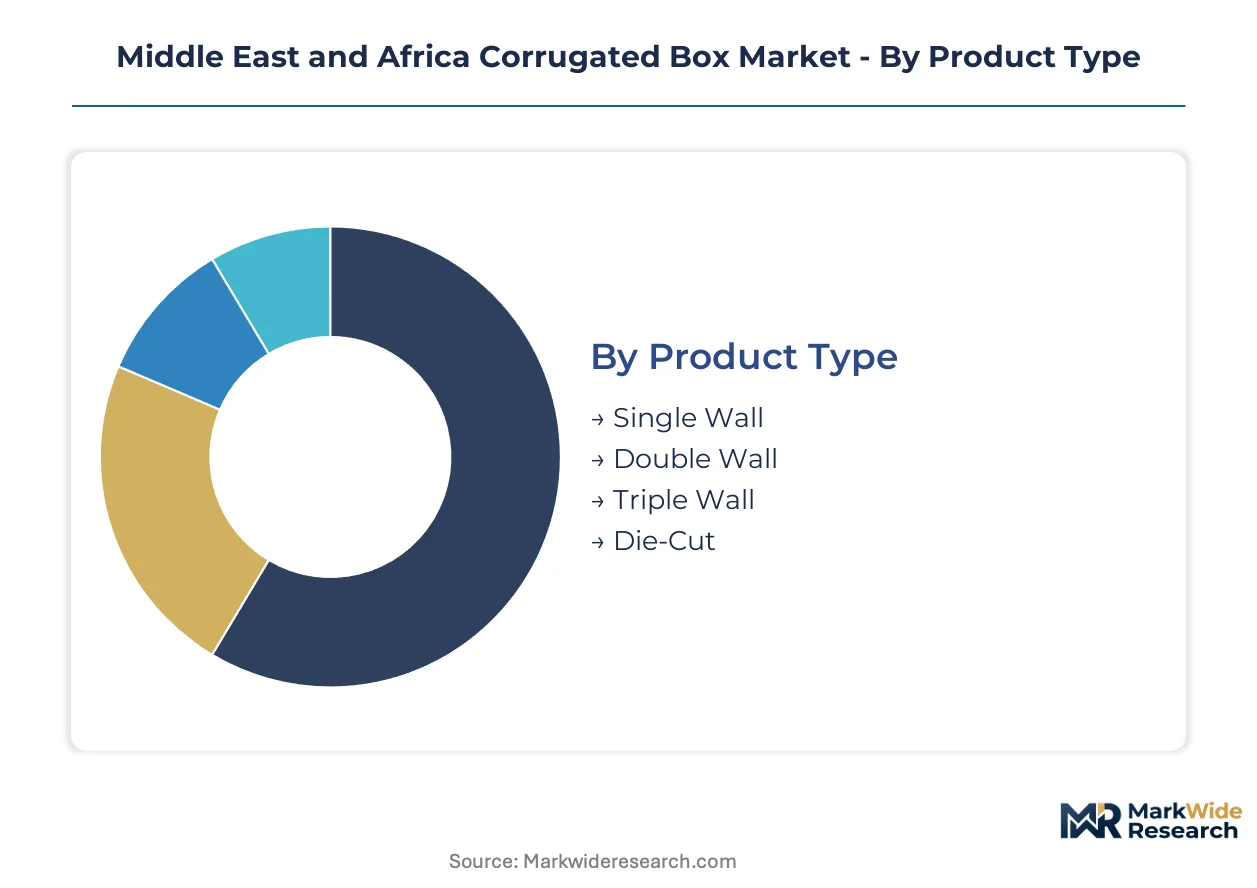
Corrugated box segmentation in the Middle East and Africa reveals how supply concentration and end-use requirements reshape procurement priorities. Gulf-based converters align production configurations with pharmaceutical serialization mandates and e-commerce fulfillment compression.
Product Type:
Supply concentration across Nile Delta and Jeddah industrial corridors favors converters with flexible wall-configuration capabilities.
- Single Wall:Constructed from one fluted medium layer between two linerboards with burst strengths typically at 150-200 lb per square inch. Saudi Arabian food and beverage distributors dominate volume throughput for lightweight consumer goods where cost efficiency outweighs stacking performance.
- Double Wall:Features two fluted layers and three linerboards delivering 200-275 lb per square inch burst resistance. UAE pharmaceutical logistics providers and electronics manufacturers in Dubai Silicon Oasis specify this configuration for moisture resistance and pallet stacking integrity.
- Triple Wall:Heavy-duty construction for industrial machinery and automotive components requiring maximum load-bearing capacity.
- Die-Cut:Custom-shaped formats with pre-scored folding lines for retail-ready display and subscription box applications.
Today's leader: Single Wall. Tomorrow's challenger: Die-Cut.
Material:
Cost tier differentiation separates premium-grade pharmaceutical substrates from economy food-grade alternatives.
- Recycled Paper:Post-consumer fiber content rising across North African export hubs serving EU Green Deal compliance. Egyptian converters face feedstock volatility under industrial waste recycling quotas.
- Virgin Fiber:Unbleached kraftliner from Scandinavian and South American pulp imports anchors premium pharmaceutical and food-contact applications where SFDA traceability requirements demand consistent substrate documentation.
- Combined Board:Hybrid construction blending recycled medium with virgin linerboard for mid-tier cost-performance positioning.
- Others:Specialty treated boards including moisture-resistant and anti-static variants for electronics and chemical shipments.
Virgin Fiber commands premium pricing. Recycled Paper climbs fastest on sustainability procurement shifts.
End User:
Application-specific certification requirements fragment supplier capabilities across hygiene-sensitive sectors.
- Food & Beverage:ISO 22000 frameworks in UAE and Saudi Arabia mandate hygiene certification for corrugated contact surfaces. Single wall formats dominate dairy, bakery, and ambient grocery distribution with high volume velocity.
- Electronics:Anti-static and cushioning specifications from Dubai and Riyadh distribution centers drive double wall adoption with custom die-cut inserts for device protection.
- Pharmaceuticals:SFDA serialization mandates elevate print registration and substrate traceability standards for Saudi healthcare logistics.
- Personal Care:Retail-ready formats with high-graphic pre-print for hypermarket shelf presentation in UAE and Qatar.
Food & Beverage holds volume dominance. Pharmaceuticals posts steepest expansion trajectory on regulatory upgrading.
Distribution Channel:
Customer type determines fulfillment speed requirements and order fragmentation tolerance.
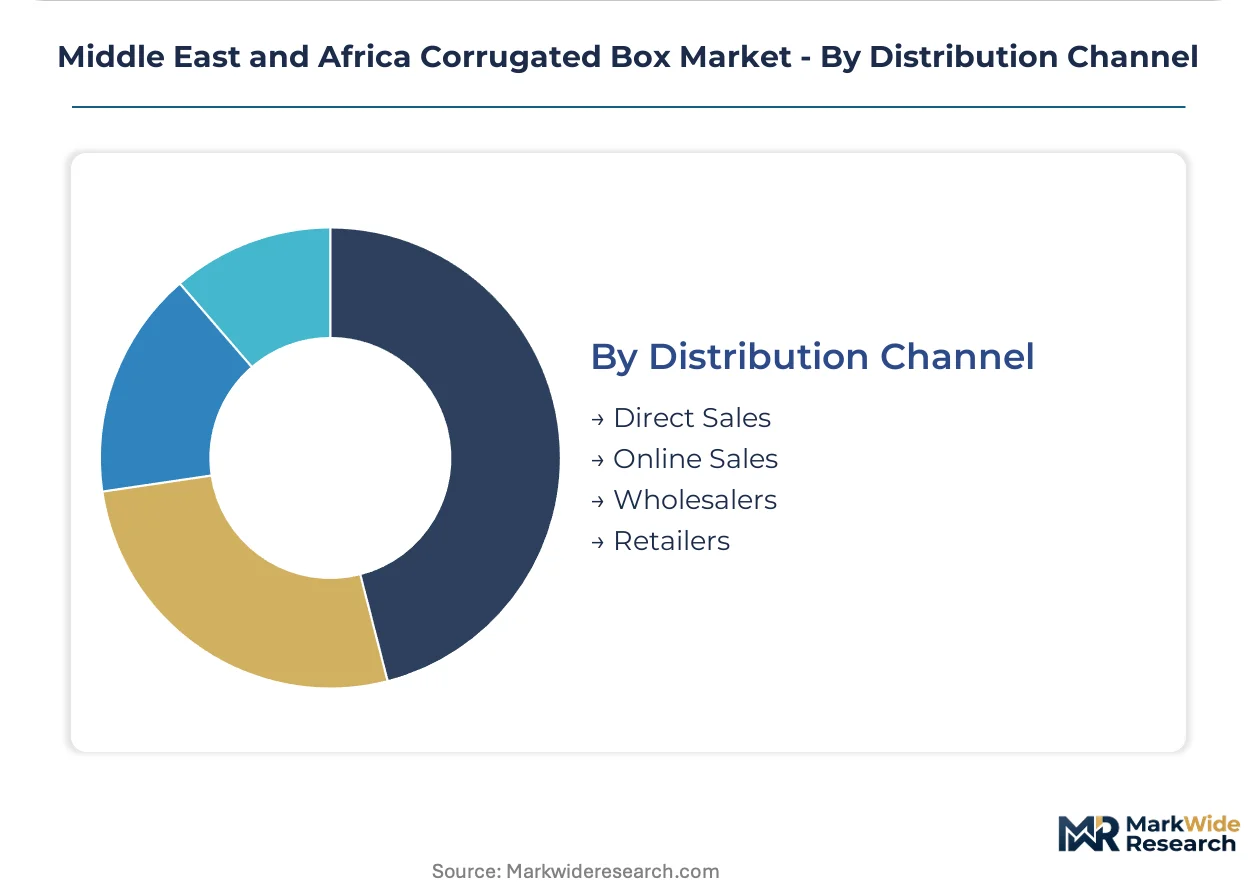
- Direct Sales:Long-term contracts with multinational FMCG brands and pharmaceutical distributors specifying just-in-time delivery from integrated design-to-delivery converters.
- Online Sales:Digital procurement portals gaining traction among mid-sized food manufacturers and e-commerce fulfillment operators seeking short-run flexibility.
- Wholesalers:Stock-and-sell intermediaries serving fragmented retail and small manufacturing bases across East Africa and Levant markets.
- Retailers:Hypermarket chains and grocery cooperatives in Saudi Arabia and UAE consolidating packaging procurement with private-label specifications.
Direct Sales anchors contract value. Online Sales expands most quickly on digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corrugated box manufacturing in the Middle East and Africa traces its industrial scaling to Jeddah's Red Sea port infrastructure development during the 1970s petrochemical expansion, when Saudi Arabia first established integrated paper-to-box conversion corridors to serve domestic consumer goods distribution.
Saudi Arabia
Pharmaceutical serialization mandates from the Saudi Food and Drug Authority are pulling premium-grade substrate demand through Riyadh and Jeddah logistics hubs. The SFDA's track-and-trace regulations for drug packaging require consistent fiber documentation and print registration precision that elevate procurement standards for healthcare distributors. Yanbu and Jubail industrial cities host concentrated converter operations serving both domestic FMCG brands and Red Sea export routes.
United Arab Emirates
E-commerce fulfillment compression across Dubai and Abu Dhabi is forcing corrugated suppliers to relocate pre-print and die-cutting capabilities closer to last-mile distribution nodes. The UAE's adoption of ISO 22000 food safety frameworks mandates hygiene certification for corrugated contact surfaces in retail grocery distribution. Dubai Silicon Oasis anchors electronics manufacturing demand for double-wall configurations with anti-static specifications.
Egypt
Nile Delta converters face feedstock volatility under industrial waste recycling quotas advanced by the country's environmental regulator. Post-consumer fiber content requirements for EU-bound exports are redirecting procurement specifications toward FSC chain-of-custody certifications. 10th of Ramadan City and Sadat City industrial zones concentrate de-inking capabilities for recycled linerboard production serving European automotive and electronics component supply chains.
South Africa
Johannesburg and Cape Town distribution centers are consolidating packaging procurement with private-label specifications from hypermarket chains expanding their regional fulfillment footprints. The country's national environmental regulator has tightened industrial waste management standards that reshape pulp sourcing economics for corrugated converters. Durban's port infrastructure supports import substitution strategies for East African consumer goods manufacturers lacking sufficient domestic capacity.
Kenya
Nairobi and Mombasa's expanding consumer goods manufacturing bases are generating import substitution openings for Gulf-based producers with integrated logistics capabilities. The country's central agricultural regions drive demand for single-wall formats in dairy and produce distribution where cost efficiency outweighs stacking performance. Athi River industrial corridor hosts emerging converter investments targeting subscription box services and meal-kit delivery platforms.
Middle East and Africa Corrugated Box Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa corrugated box landscape. Integrated paper-to-box operators with captive pulp supply command cost advantages in North African export hubs, while specialized converters with flexible short-run capabilities capture e-commerce and specialty food brand demand. Three archetypes dominate: multinational integrated producers with regional production footprints, mid-scale national champions serving domestic FMCG consolidation, and flexible specialists targeting digital print and rapid-turnaround fulfillment. Competitive dynamics center on automated corrugator investments that reduce conversion waste and strategic partnerships with pharmaceutical logistics providers seeking serialization-compliant substrate supply.
Among multinational integrated producers, DS Smith, Mondi, and Smurfit Kappa occupy positions representing distinct strategic orientations toward the regional market. DS Smith exemplifies the integrated paper-to-box archetype with operations spanning North African production hubs. Mondi anchors specialty kraftliner supply chain positioning that serves premium pharmaceutical and food-contact applications. Smurfit Kappa represents automated conversion infrastructure investment strategies targeting waste reduction and throughput efficiency in high-volume corridors.
| Leading Market Players |
|---|
| Arabian Packaging Co LLC |
| United Carton Industries Company |
| Napco National |
| Queenex Corrugated Carton Factory LLC |
| DS Smith |
| Mondi |
| International Paper |
| Smurfit Kappa |
| WestRock Company |
| Others |
Supply & Pricing Matrix
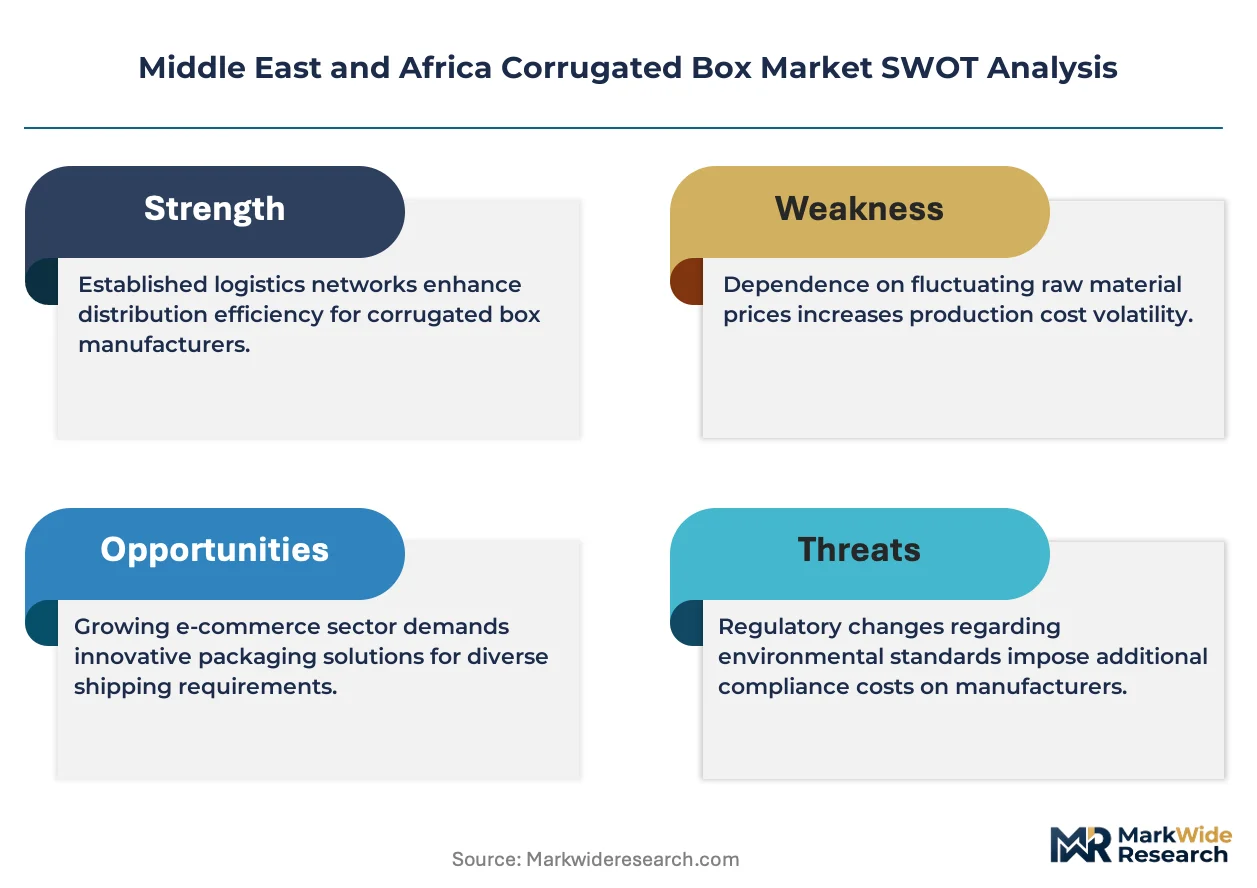
Scandinavian and South American kraftliner imports flow through Jeddah and Yanbu ports into virgin fiber pricing tiers that anchor premium pharmaceutical substrate costs, while Egyptian recycled pulp volatility under industrial waste quotas compresses margins for Nile Delta converters serving EU-bound exports.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Virgin fiber substrates with SFDA traceability documentation command substantial premiums from Saudi healthcare logistics providers, while recycled-content boards face price erosion from feedstock cost volatility. Pharmaceutical distributors exhibit the lowest price sensitivity due to serialization compliance requirements, whereas East African food manufacturers prioritize cost efficiency above performance specifications.
Supply Chain Analysis
Closed-loop beverage crate return systems in Saudi Arabia and UAE reduce corrugated demand in dairy distribution channels. Raw material supply concentrates in Egypt, Saudi Arabia, and Morocco, with Scandinavian pulp imports anchoring premium grades. Natural gas and electricity feedstock dependencies expose margins to utility tariff fluctuations. Distribution runs through Red Sea port infrastructure and Gulf Cooperation Council logistics corridors serving last-mile e-commerce nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA pharmaceutical serialization mandates compound regulatory value into substrate traceability, elevating procurement standards and pricing power for compliant suppliers across Saudi Arabia and UAE.
For Market Incumbents: Anchor market position through automated corrugator investments that reduce conversion waste and secure FSC chain-of-custody certifications for EU export eligibility. DS Smith and Mondi demonstrate how integrated paper-to-box operations sustain cost advantages against emerging flexible converters. Certification timeline compression from multinational FMCG brands demands pre-qualified substrate documentation to defend contract renewals. For New Entrants and Emerging Players: Capture white-space opportunity in Kenya and Ethiopia's underpenetrated consumer goods manufacturing bases where domestic corrugated capacity lags demand growth. Subscription box services and meal-kit delivery platforms generate fragmented short-run demand that automated finishing systems can serve profitably. Partner with Gulf-based logistics integrators to bypass capital-heavy pulp sourcing infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where certification investments and automated infrastructure create performance gaps between national champions and sub-scale converters. Mid-scale Egyptian and Moroccan producers with de-inking capabilities and FSC certifications represent attractive acquisition targets for EU export positioning. Monitor EU Green Deal packaging recyclability mandate enforcement intensity as inflection indicator for recycled fiber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Corrugator Investment | Reduces conversion waste and improves throughput for high-volume Gulf Cooperation Council corridors. |
| FSC Chain-of-Custody Certification | Enables EU Green Deal compliance for Egyptian and Moroccan export-oriented converters. |
| Digital Print Capability Expansion | Captures short-run e-commerce and specialty food brand demand with rapid turnaround. |
| Pre-Print and Die-Cutting Proximity | Compresses order-to-delivery timelines for UAE and Saudi last-mile distribution nodes. |
| Pharmaceutical Substrate Qualification | Secures long-term contracts with SFDA-compliant healthcare logistics providers in Riyadh and Jeddah. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corrugated plant managers, procurement leads at multinational FMCG brands, pharmaceutical logistics operators, and distribution channel partners with secondary validation from customs and trade data, SEC filings of integrated producers, and industrial production statistics. Bottom-up volume estimates from converter capacity and utilization rates triangulated against top-down demand modeling from end-use sector consumption patterns.
Comparable historical reference periods anchored the projection framework across the analysis window, with segmentation dimensions spanning wall configuration, material grade, end-use application, and distribution channel. CAGRs derived from regression analysis of correlated macroeconomic and sector-specific demand drivers incorporated e-commerce penetration rates, pharmaceutical serialization compliance timelines, and EU export volume trajectories as industry-specific inputs.
Underlying measurement precision varies by segment; pharmaceutical and food-grade certified substrates carry tighter precision than commodity recycled board categories. Forecasts reflect assumptions about regulatory enforcement continuity and pulp feedstock availability that could revise if Egypt's industrial waste quotas tighten further or EU Green Deal thresholds escalate. Practitioners should monitor SFDA serialization rollout pace and EU packaging recyclability mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Paper Packaging Materials Market