
 Transfer Paper Market | 2026-2036
Transfer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Transfer Paper Market Outlook
DIY crafters and small-batch apparel decorators is redrawing demand patterns across the transfer paper value chain. Neenah Performance Materials anchors North American supply through its coated specialty paper mills. Felix Schoeller Group leverages European manufacturing scale to serve premium sublimation grades. Guangzhou Elephant Digital Technology Co. Ltd dominates cost-competitive inkjet transfer segments in Asia.
Transfer paper consists of a base sheet, typically woodfree or coated paper, bearing a release coating of silicone or polymer that enables clean image transfer under heat and pressure. Its primary commercial purpose is to carry pigmented or dye-based designs from printer to substrate without distortion during the thermal transfer process. Sublimation transfer paper commands the fastest expansion as polyester textile decoration scales, while heat transfer sheets occupy mature volume pools in cotton apparel. Inkjet-compatible coatings retain margin concentration due to ongoing reformulation demands for pigment ink adhesion.
EPA oversees volatile organic compound limits in coating solvents stateside, while REACH governs chemical safety for European import grades. China's SAMR enforces GB standards on paper product safety that affect export-bound coating formulations. Stakeholders must track evolving chemical disclosure rules across these jurisdictions to secure sustained market access.
Market Dynamics
Polyester textile decoration is compressing heat transfer cycles while REACH chemical restrictions force coating reformulation across European supply chains. These dual pressures are redrawing competitive positioning between sublimation-grade specialists and commodity sheet producers.
Growth Catalysts
- Direct-to-garment print shop expansion:United States-based decorators are scaling small-batch polyester production, pulling premium sublimation sheet volume through specialized distributors.
- GB standards alignment:China's SAMR enforcement on paper product safety is accelerating coating chemistry upgrades among export-oriented mills serving European buyers.
- Silicone release coating advances:Reformulated polymer layers are improving transfer fidelity at lower temperatures, enabling heat-sensitive synthetic substrates.
Market Restraints
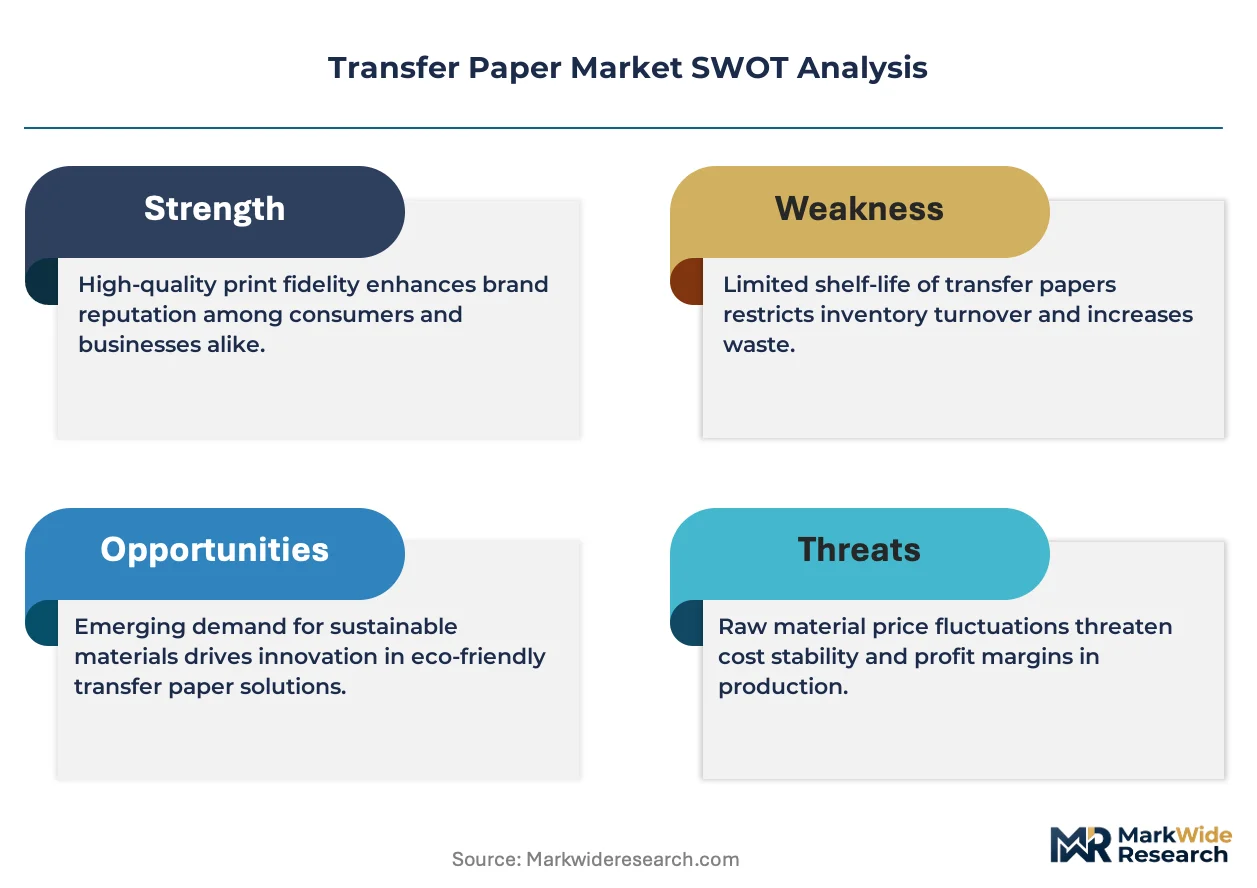
- Pulp input cost volatility:Woodfree base sheet producers face margin compression from northern European pulp supply concentration and energy-intensive coating drying requirements.
- Substitution by direct-to-film systems:PET film carriers with hot-peel release layers are capturing share in cotton apparel decoration, displacing traditional coated paper in high-wash-count applications.
- REACH registration timelines:ECHA chemical disclosure requirements for silicone release agents create 18-24 month product requalification cycles that freeze formulation portfolios.
Strategic Opportunities
- India textile cluster penetration:Tiruppur and Surat apparel hubs remain underpenetrated by organized transfer paper distribution, presenting first-mover channel buildout potential.
- Recycled-content coating mandates:EU Green Deal circular economy requirements are creating specification windows for post-industrial silicone recovery in release layers.
- Inkjet-sublimation convergence:Water-based pigment ink compatibility with low-temperature sublimation is opening home-decor applications on coated ceramics and rigid substrates.
Industry Challenges
- Coating technician scarcity:Formulation chemistry expertise for multi-layer release systems is concentrating among aging specialists in German and Japanese technical centers.
- Legacy press integration:Small-batch decorators operating 15-year-old heat presses face calibration drift that degrades transfer yield on newer fast-release coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfer Paper Market |
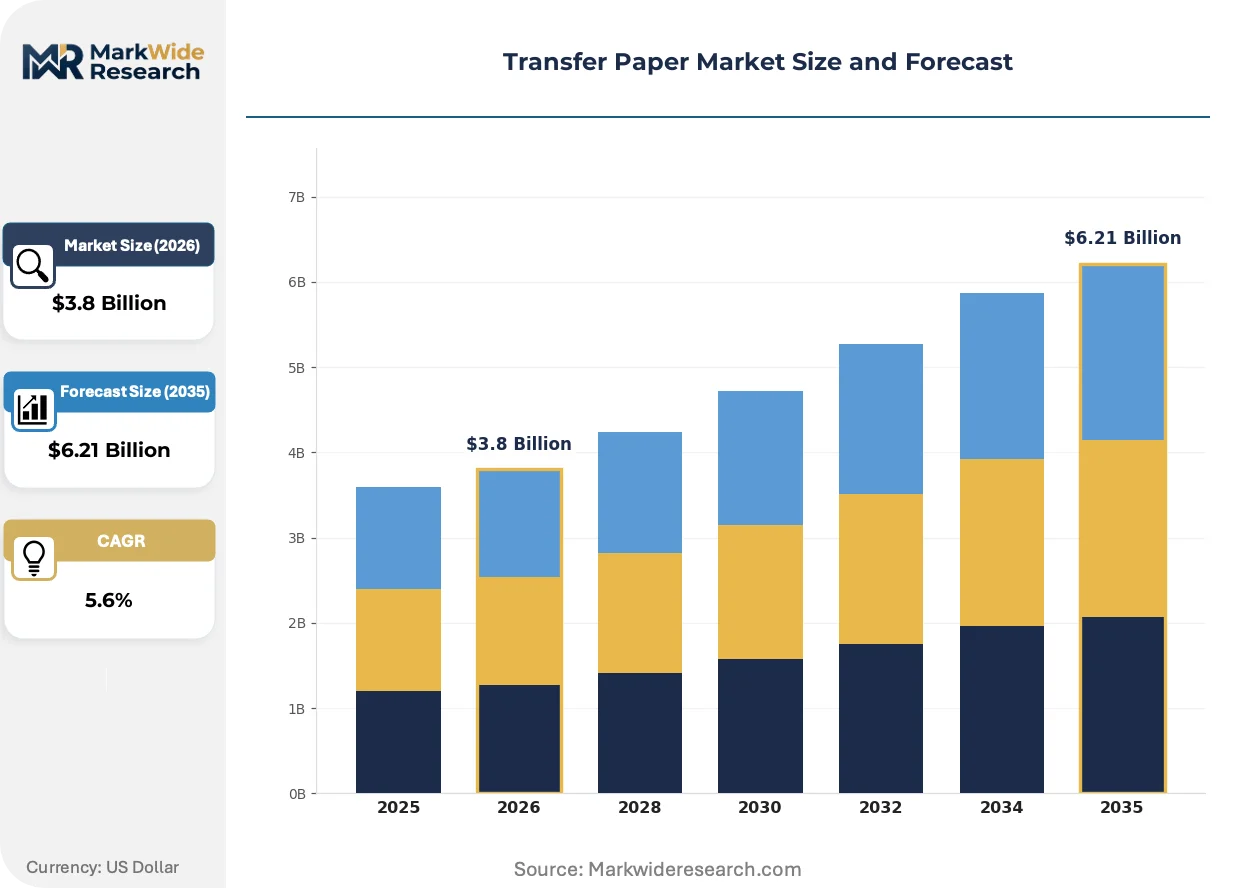
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Sublimation, Heat Transfer End User: Textile Industry, DIY Crafts, Commercial Printing, Home Use Application: Apparel Decoration, Signage, Craft Projects, Custom Merchandise Technology: Digital Printing, Screen Printing, Offset Printing, Dye Sublimation |
| Companies Covered | Felix Schoeller Group, Neenah Performance Materials, One Step Papers LLC, Guangzhou Elephant Digital Technology Co. Ltd, PG Paper Company, Stahls' Transfer Paper Experts, Pudumjee Paper Products, Paper N Films International, Miroglio Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfer Paper Market Strategic Shifts
Active coating layer engineering is compressing thermal transfer windows while regulatory disclosure requirements reshape raw material sourcing. These developments are forcing simultaneous investment in formulation R&D and supply chain transparency systems.
Nano-scale ceramic particle coatings are miniaturizing thermal mass in release layers, enabling sub-180°C transfer temperatures for heat-sensitive polyester blends. Athletic wear decorators in Italy and Vietnam are adopting these sheets for stretch-fabric applications where traditional coatings cause dye migration. The technology is miniaturizing the temperature differential between sublimation and heat transfer processes, collapsing equipment specification boundaries.
REACH SVHC candidate list expansion is forcing silicone fluid suppliers to document full substance composition down to 0.1% weight thresholds. Coating mills serving European textile printers must now maintain batch-level chemical passports that trace through three supply tiers. German and Dutch import distributors are consolidating supplier bases to reduce disclosure audit burdens, favoring vertically integrated coating producers with captive silicone synthesis.
Short-run digital decorators are unbundling from minimum-order coating contracts, instead procuring cut-sheet assortments through Amazon Business and specialized craft distributors. This channel pivot fragments volume concentration previously captured by regional paper merchants. United States hobbyist communities and Etsy-based apparel sellers represent the most visible expression of this procurement pattern shift, with comparable dynamics emerging in United Kingdom maker spaces.
Transfer Paper Market Segmentation
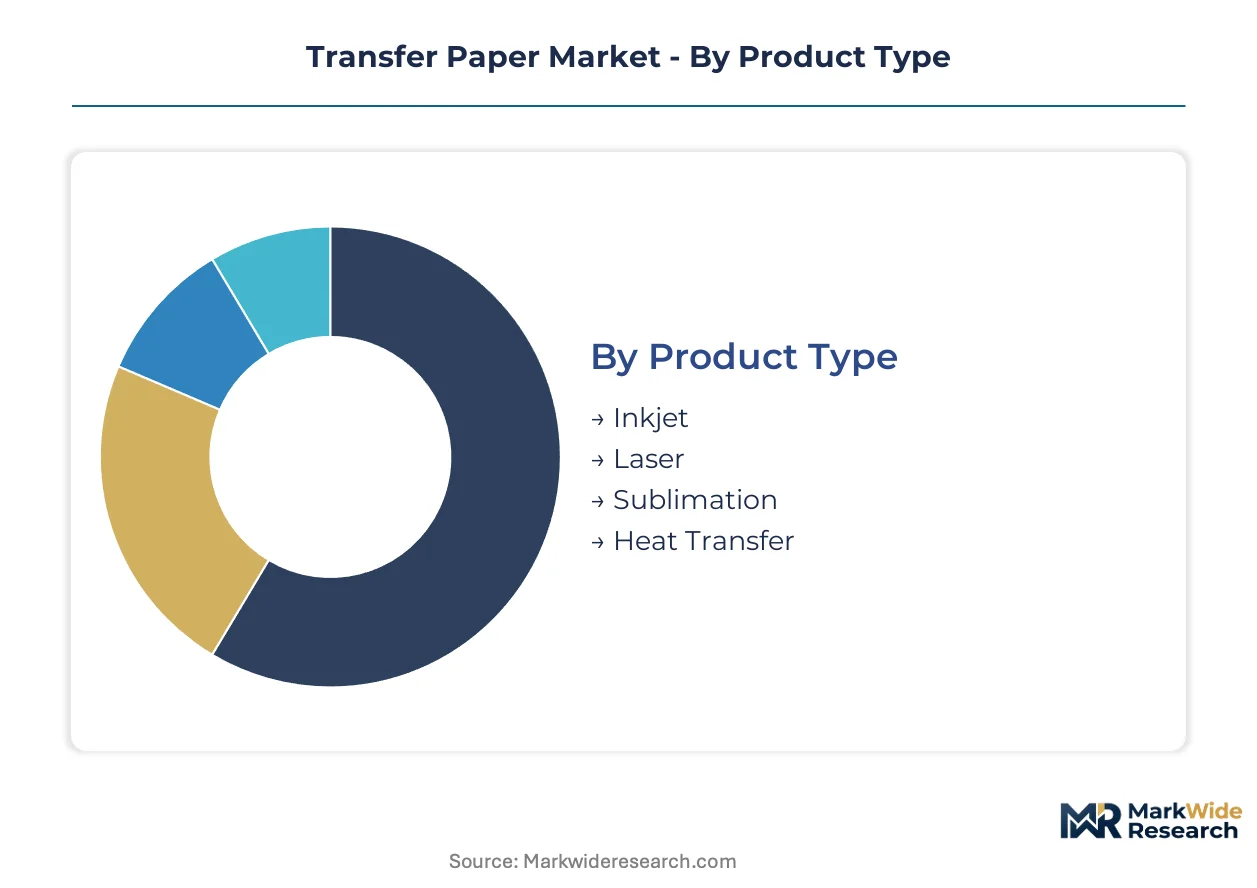
Transfer paper segmentation reveals how coating chemistry and printer compatibility partition value capture across the value chain. Regulatory pressure on silicone release agents and ink adhesion specifications now shapes segment profitability more than base paper sourcing alone.
Product Type:
REACH chemical restrictions in Europe and evolving GB standards in China are tightening coating chemistry requirements differently across printable surfaces.
- Sublimation:Polyester-specific dye carriers use low-viscosity silicone release layers engineered for 200°C transfer windows. United States direct-to-garment print shops are scaling small-batch production, pulling premium sheet volume through specialized distributors serving hobbyist communities.
- Heat Transfer:Cotton-compatible coatings employ thicker polymer barriers to prevent dye bleed on natural fibers. Mature volume pools in North American cotton apparel decoration face displacement from PET film alternatives in high-wash-count applications.
- Inkjet:Microporous coatings optimize water-based pigment absorption for desktop printer compatibility.
- Laser:Heat-resistant polymer overlays prevent toner offset during fuser passage through office equipment.
Established volume favors Heat Transfer; emerging adoption favors Sublimation.
End User:
Procurement scale and technical specification intensity separate commercial operations from consumer purchasers.
- DIY Crafts:Cut-sheet assortments through Amazon Business and craft distributors serve Etsy-based apparel sellers and maker spaces. Channel fragmentation is unbundling volume concentration previously captured by regional paper merchants.
- Textile Industry:Tiruppur and Surat apparel hubs in India remain underpenetrated by organized distribution, presenting first-mover channel buildout potential for coating mills with export-grade certification.
- Commercial Printing:Roll-fed coating contracts with 90-day minimums dominate procurement for high-volume decorators.
- Home Use:Individual crafters prioritize single-pack availability over unit economics.
Commercial Printing commands margin concentration; DIY Crafts exhibits the steepest expansion trajectory.
Application:
Temperature sensitivity and substrate rigidity dictate coating formulation architecture across use cases.
- Apparel Decoration:Athletic wear decorators in Italy and Vietnam are adopting nano-ceramic particle coatings for stretch-fabric applications where traditional layers cause dye migration. Sub-180°C transfer temperatures enable heat-sensitive polyester blends.
- Signage:Rigid substrate compatibility requires modified release chemistry for aluminum and acrylic surfaces.
- Craft Projects:Multi-surface versatility drives demand for general-purpose coatings with broader temperature tolerance.
- Custom Merchandise:Short-run digital decorators favor cut-sheet procurement over roll-stock commitments.
Apparel Decoration anchors revenue; Custom Merchandise is climbing the fastest.
Technology:
Print method compatibility determines coating porosity, thermal resistance, and release kinetics.
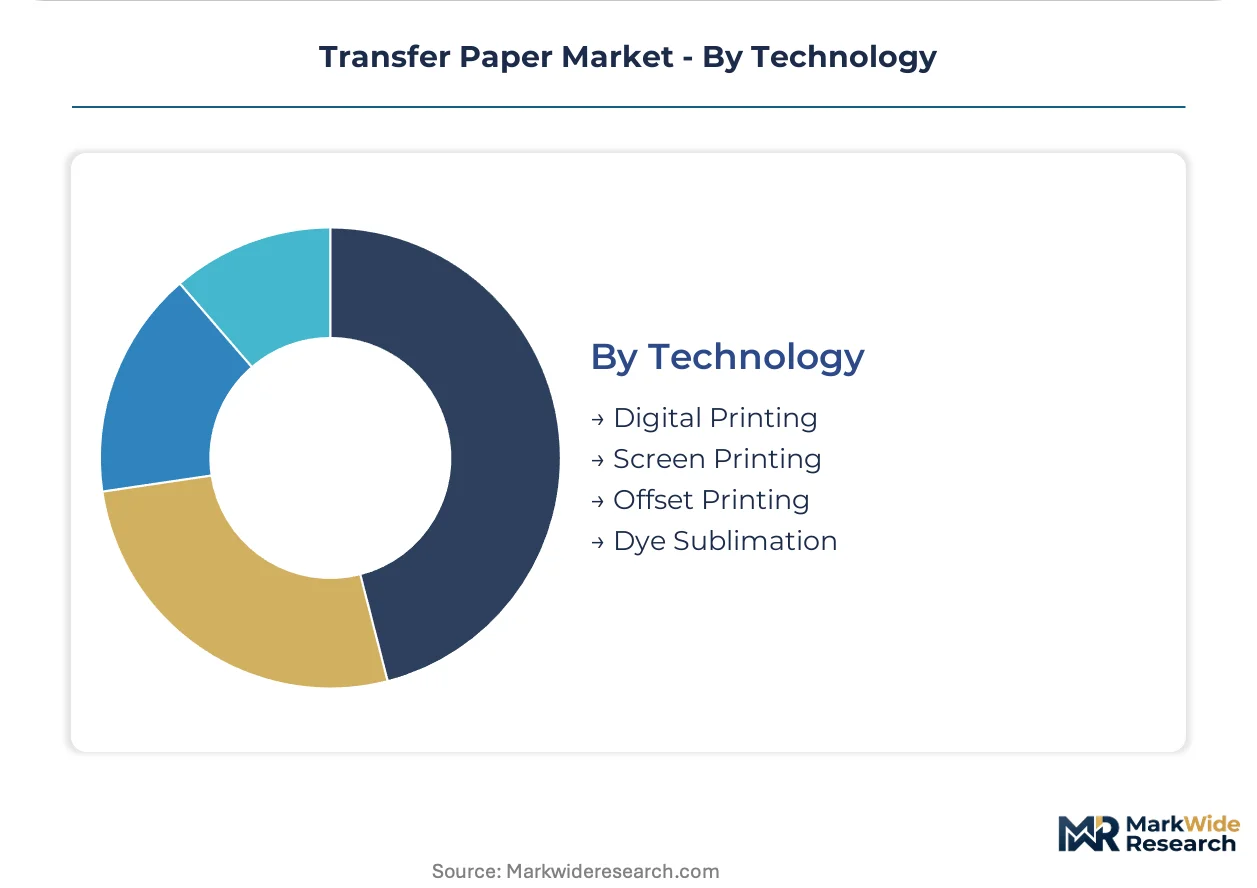
- Dye Sublimation:Gas-phase dye transfer demands precise coating permeability for polyester fiber penetration. Water-based pigment ink compatibility with low-temperature sublimation is opening home-decor applications on coated ceramics.
- Digital Printing:Piezoelectric drop-on-demand systems require rapid-dry surface chemistry.
- Screen Printing:Thicker ink deposits necessitate robust release layers for clean transfer.
- Offset Printing:Oil-based ink systems impose distinct adhesion requirements on coating formulations.
Screen Printing holds legacy volume; Dye Sublimation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch coating mills export REACH-certified sublimation grades to United States textile printers, establishing the primary transatlantic trade corridor in premium transfer paper.
United States
Direct-to-garment print shops in North Carolina and California are scaling small-batch polyester production for Etsy-based apparel sellers. EPA volatile organic compound limits constrain coating solvent formulations for domestic mills. Dallas-Fort Worth distributors serve hobbyist communities with cut-sheet assortments through Amazon Business channels.
Germany
Specialized coating producers supply premium sublimation grades to Italian athletic wear decorators. ECHA chemical disclosure requirements for silicone release agents enforce batch-level substance passports. The Ruhr industrial cluster concentrates formulation chemistry expertise for multi-layer release systems.
China
Cost-competitive inkjet transfer segments dominate export volumes to European and North American buyers. SAMR GB standards on paper product safety accelerate coating chemistry upgrades among export-oriented mills. Guangzhou manufacturers anchor supply for digital textile printing equipment OEMs.
India
Tiruppur and Surat apparel hubs remain underpenetrated by organized transfer paper distribution despite expanding polyester decoration capacity. BIS certification requirements for imported paper products create qualification barriers for unbranded Asian suppliers. Maharashtra-based commercial printers are piloting low-temperature sublimation for cotton-polyester blends.
Vietnam
Stretch-fabric athletic wear producers in Ho Chi Minh City and Hanoi are adopting nano-ceramic particle coatings for sub-180°C transfer applications. The country's national standards body enforces evolving chemical safety protocols on imported coating materials. Da Nang textile parks attract decorators serving European fast-fashion brands with short-run digital production.
Transfer Paper Market Competitive Environment
Listed leaders compete with private specialists across coating chemistry capabilities, creating a tiered structure where scale and specialization segment competitive space. Consolidation concentrates among European and North American mills with captive silicone synthesis, while Asian producers fragment across cost-driven inkjet segments. Strategic archetypes include vertically integrated coating specialists, regional paper merchants with conversion capabilities, and digital equipment OEMs with captive paper supply. Dominant competitive moves encompass geographic expansion into underpenetrated textile clusters and portfolio diversification toward low-temperature sublimation formulations.
Among United States-based coated specialty paper producers, Neenah Performance Materials occupies a position exemplifying North American supply anchoring. Felix Schoeller Group represents European manufacturing scale serving premium sublimation grades. Guangzhou Elephant Digital Technology Co. Ltd sits within the cost-competitive inkjet transfer segment dominating Asian supply.
| Leading Market Players |
|---|
| Felix Schoeller Group |
| Neenah Performance Materials |
| One Step Papers LLC |
| Guangzhou Elephant Digital Technology Co. Ltd |
| PG Paper Company |
| Stahls' Transfer Paper Experts |
| Pudumjee Paper Products |
| Paper N Films International |
| Miroglio Group |
| Others |
Value Chain & Pricing Dynamics
REACH chemical disclosure requirements gate both European market access and price stratification across coating tiers. Mills lacking batch-level substance passports face automatic disqualification from premium distribution channels regardless of unit cost position.
Pricing Analysis
Next-generation nano-ceramic coatings command substantial premiums over conventional silicone release layers and legacy heat-transfer formulations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with REACH-compliant European grades fetching the highest unit economics. Cost compression in commodity inkjet segments is intensifying because Guangzhou-based producers are flooding cut-sheet channels through Amazon Business. Small-batch decorators operating legacy heat presses exhibit the greatest price sensitivity, while Italian athletic wear producers prioritize transfer fidelity over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor premium sublimation-grade coating production for European and North American textile printers. Base sheet supply draws from northern European pulp mills, while silicone fluid feedstocks rest on German and Japanese specialty chemical producers. Single-source vulnerability concentrates in REACH-certified release agent synthesis, where ECHA registration timelines freeze alternative supplier qualification. Distribution runs through specialized paper merchants in Dallas-Fort Worth and regional distributors serving Tiruppur apparel hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for multi-layer release systems is concentrating among aging specialists in Ruhr industrial clusters and Japanese technical centers, creating a narrow pipeline of qualified coating technicians. This capability scarcity threatens succession planning across premium coating mills.
For Market Incumbents: Fortify captive silicone synthesis capabilities to reduce REACH disclosure audit burdens and secure batch-level substance traceability. Invest in low-temperature sublimation R&D to defend against nano-ceramic coating specialists capturing athletic wear volume. Channel control through specialized distributors serving United States direct-to-garment print shops remains critical as Amazon Business fragments procurement patterns. For New Entrants and Emerging Players: Lead with underpenetrated Indian textile clusters, specifically Tiruppur and Surat apparel hubs where organized transfer paper distribution remains sparse. Target home-decor applications on coated ceramics where water-based pigment ink compatibility with low-temperature sublimation is opening new substrate categories. Pursue cut-sheet assortment strategies through craft distributors and maker space channels rather than competing for roll-fed coating contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-certified coating production as ECHA disclosure requirements demand batch-level chemical passport systems. Long-term viability favors vertically integrated mills with captive silicone fluid synthesis and established European regulatory compliance. Acquisition target archetypes include German and Dutch coating specialists with formulation chemistry expertise and established Italian athletic wear customer relationships. Watch for inflection in India's BIS certification enforcement on imported paper products, which would accelerate consolidation among export-oriented Asian mills.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Synthesis | ECHA REACH disclosure requirements favor mills with captive release agent production and batch-level traceability systems. |
| Low-Temperature Sublimation Formulation Development | Nano-ceramic particle coatings are compressing thermal transfer windows for heat-sensitive polyester blends in Italian athletic wear. |
| Channel Buildout in Indian Textile Clusters | Tiruppur and Surat apparel hubs remain underpenetrated by organized distribution despite expanding polyester decoration capacity. |
| Cut-Sheet Assortment Expansion | Amazon Business and craft distributors are capturing hobbyist community procurement previously concentrated through regional paper merchants. |
| REACH Compliance Certification Investment | German and Dutch import distributors are consolidating supplier bases to reduce disclosure audit burdens on silicone release agents. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, chemical industry association reports, and SEC filings from coated specialty paper producers. Primary interviews engaged coating mill technical directors, silicone fluid procurement leads at release layer specialists, distribution channel partners serving United States direct-to-garment print shops, and regulatory affairs managers navigating ECHA REACH registration timelines. Secondary validation drew from EPA volatile organic compound enforcement records, SAMR GB standards documentation, and BIS certification requirement updates. Bottom-up volume estimates from coating capacity and utilization rates triangulate against top-down demand aggregation across end-use segments.
Segmentation dimensions modeled include coating chemistry type, printer compatibility, substrate application, and regional regulatory cluster. CAGRs were derived through trend extrapolation of historical volume patterns adjusted for technology substitution effects and regulatory phase-in schedules. Forecast inputs incorporate pulp input cost trajectories, REACH SVHC candidate list expansion timelines, and digital textile printing equipment installation rates across United States and European geographies. Outputs reflect constant-currency valuation across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained polyester textile decoration growth or accelerated direct-to-film substitution would require recalibration. Forecasts reflect assumptions regarding ECHA enforcement consistency, SAMR GB standards alignment pace, and hobbyist community procurement channel stability. Specific risks that could revise projections include REACH registration timeline extensions, India's BIS certification barrier intensification, and nano-ceramic coating cost curves achieving parity with conventional silicone release layers. Recalibration cycles align with material shifts in regulatory enforcement patterns and technology substitution thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Middle East and Africa Coated Paper Market