
 Latin America Paper Packaging Market | 2026-2036
Latin America Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Paper Packaging Market Foresight
Brazil is rewriting competitive dynamics across Latin American paper packaging through sustained capacity additions in bleached eucalyptus kraft pulp. Suzano leverages vertical integration from plantation to converted boxboard, securing cost advantages in corrugated supply. Klabin anchors regional kraft paper output with integrated forestry operations in Paraná state. Smurfit Westrock competes through containerboard scale and recycling network density across multiple Latin American markets.
Latin America paper packaging comprises fiber-based containers, wraps, and structural boards manufactured from virgin or recycled pulp slurries, typically ranging from 150 to 450 grams per square meter in basis weight, engineered to protect, display, or transport goods through distribution channels. Corrugated packaging dominates volume flows due to e-commerce fulfillment expansion and agricultural export requirements. Paperboard captures premium margin pools in pharmaceutical and personal care folding cartons where print fidelity and barrier coatings command pricing power. Kraft paper sustains industrial bulk packaging demand across grain, cement, and chemical sectors.
Brazil's IBAMA, Mexico's SEMARNAT, and Chile's SMA enforce forestry certification and emissions standards that shape pulp sourcing compliance costs and mill permitting timelines. ANVISA in Brazil and COFEPRIS in Mexico impose pharmaceutical contact-material rules that redirect specialty paperboard demand toward certified substrate grades. Stakeholders must monitor how pending extended producer responsibility frameworks across Colombia, Peru, and Chile alter collection infrastructure investments and recycled fiber availability.
Market Dynamics
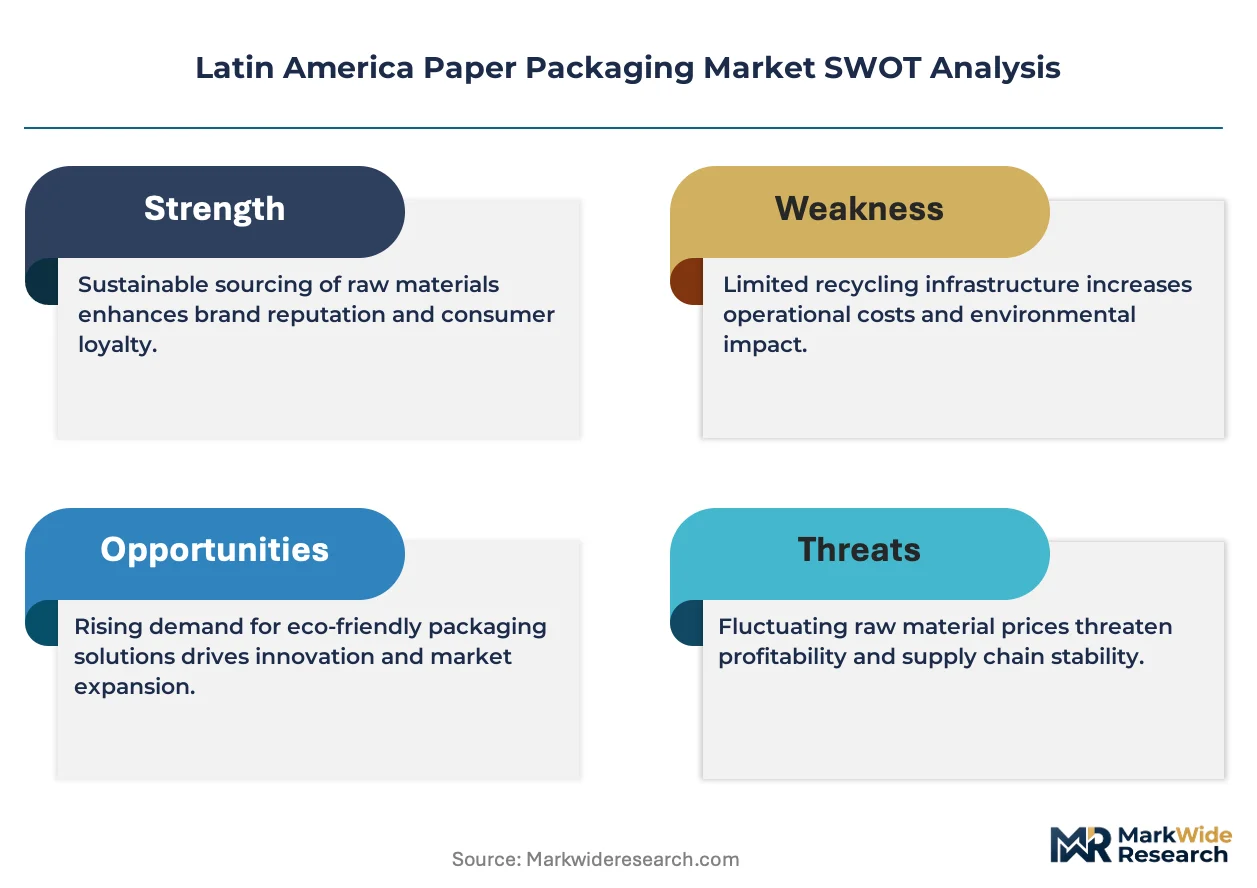
Latin American paper packaging faces structural pressure from IBAMA's deforestation-linked sourcing enforcement, which is forcing pulp suppliers to reconfigure plantation certification and mill traceability systems across Brazil's Atlantic Forest and Amazon biomes.
Growth Catalysts
- E-commerce fulfillment infrastructure:Warehouse automation in São Paulo and Mexico City demands standardized corrugated box formats with RFID-ready print surfaces for real-time inventory tracking.
- SEMARNAT emissions standards:Mexico's 2024 industrial air quality rules are accelerating kiln conversions at containerboard mills toward biomass and natural gas firing, improving output consistency for high-performance linerboard.
- Agricultural export compliance:Phytosanitary packaging mandates for Brazilian soy and Chilean fruit shipments to China and the EU are specifying ISPM-15 compliant wood alternatives, redirecting volume toward kraft paper-based solutions.
Market Restraints
- Eucalyptus pulp input volatility:Brazilian plantation productivity swings with El Niño rainfall patterns, creating 6-9 month fiber cost cycles that compress converter margins.
- Recycled fiber supply fragmentation:Informal collection networks across Colombia and Peru recover less than 35% of post-consumer OCC, forcing mills to import baled waste from the US Gulf Coast.
- Plastic substitution ceiling:Moisture-sensitive food categories in tropical climates retain multilayer plastic barriers where paper-based alternatives fail shelf-life specifications.
Strategic Opportunities
- Colombia's underdeveloped folding carton base:Bogotá's pharmaceutical and personal care manufacturing clusters currently import 40% of their paperboard from Brazil, creating localization incentives.
- Extended producer responsibility frameworks:Pending legislation in Chile and Peru will mandate brand-funded collection infrastructure, opening equipment and logistics contracts for integrated packaging suppliers.
- Digital print convergence with barrier coating:Water-based inkjet systems combined with bio-based moisture barriers enable short-run customization for craft beverage brands in Mexico's Baja California and Jalisco states.
Industry Challenges
- Forest certification audit capacity:FSC and PEFC chain-of-custody verification faces 12-18 month backlogs at accredited bodies, delaying export qualification for mid-tier converters.
- Legacy equipment integration:Pre-2015 corrugators lack servo-controlled scoring and slotting precision required for automated case packing lines at dairy and meat processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Paper Packaging Market |
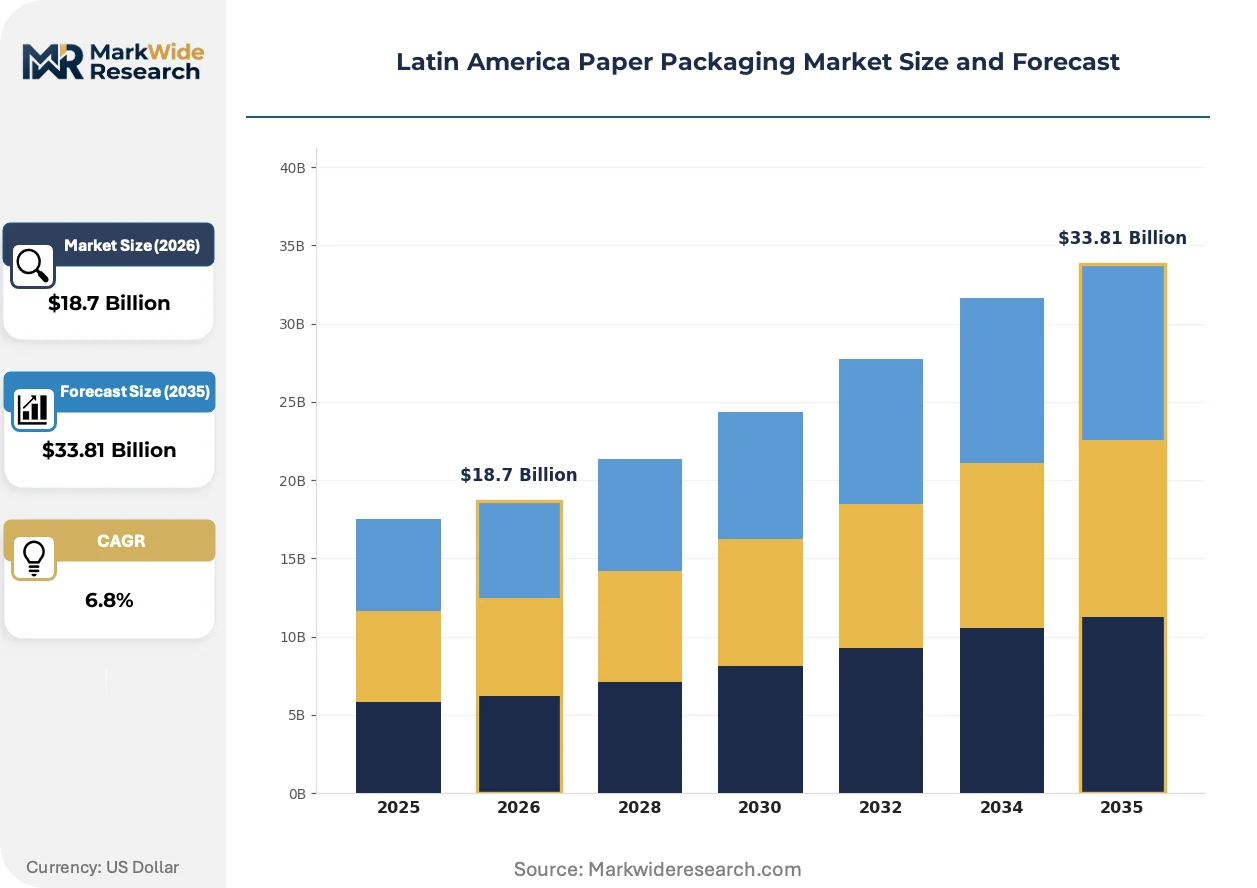
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cartons, Bags, Wrapping Paper, Boxes Product Type: Corrugated Packaging, Paperboard, Kraft Paper, Specialty Paper End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Application: Retail Packaging, Industrial Packaging, E-Commerce Packaging, Export Packaging |
| Companies Covered | Suzano, Mondi Group, Smurfit Westrock, Tetra Laval, Stora Enso, Klabin, Graphic Packaging International Corporation, Rengo, International Paper Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Paper Packaging Market Shifts & Advancements
Material science advances and regulatory tightening are converging to redefine substrate performance requirements across Latin American paper packaging, with particular intensity in food contact and export-grade applications.
Barrier coating technology is migrating from fluorochemical and petroleum-based formulations toward bio-derived alternatives including nanocellulose, chitosan, and alginate composites. Brazilian beverage exporters and Chilean salmon processors are piloting these substrates for 18-month shelf-life targets. The shift is compressing incumbent chemical suppliers' pricing power while creating qualification bottlenecks at ANVISA and FDA for novel food contact substances.
IBAMA's 2023 updated forest sourcing traceability protocol now requires geolocation tagging of all pulpwood harvested from native vegetation areas, with blockchain-verified chain-of-custody documentation mandatory for export licenses. This industrial consequence has triggered consolidation among smaller independent pulp traders unable to absorb compliance system costs. The pharmaceutical and premium food segments in Brazil's Southeast region are responding by demanding FSC 100% certification as a procurement prerequisite, bypassing mixed-source alternatives.
Consolidated buying patterns among multinational CPG subsidiaries are displacing fragmented regional converter relationships with direct mill partnerships and specification lock-ins. São Paulo-based beverage bottlers and Mexico City snack food operations now negotiate 36-month volume commitments in exchange for dedicated production slots and custom flute profiles. This concentration is most visible in Brazil's São Paulo state, where three beverage groups account for the majority of B-flute and E-flute corrugated demand.
Latin America Paper Packaging Market Segmentation
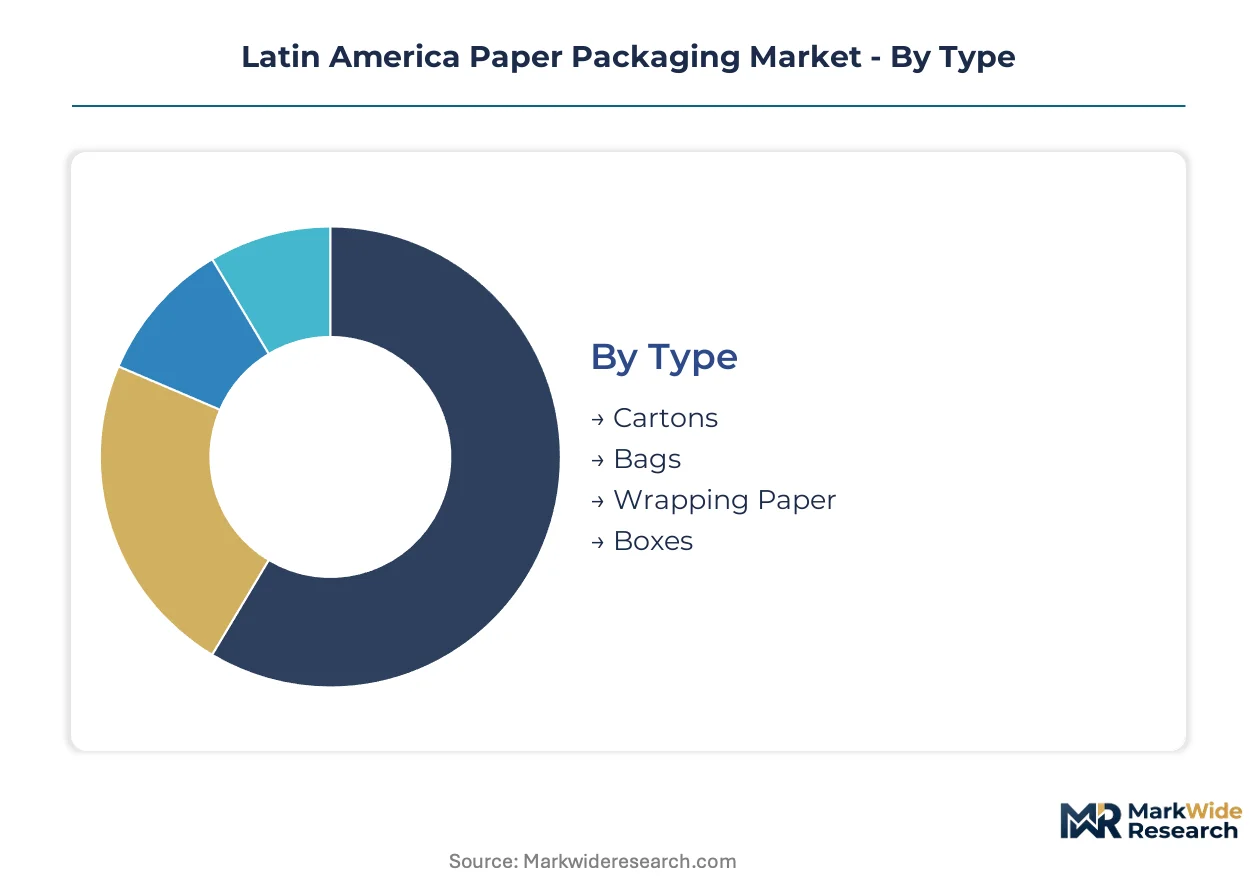
Latin American converters configure production lines around substrate performance tiers and end-use compliance requirements. Segment boundaries reflect how IBAMA certification, ANVISA food contact rules, and export phytosanitary standards partition demand across equipment investments and qualification timelines.
Type:
Application requirements determine which structural format captures volume in each end-use corridor.
- Cartons:Folding carton substrates range from 200-400 gsm solid bleached sulfate, engineered for high-fidelity offset print and die-cut precision. Pharmaceutical blister packs and premium cosmetic boxes in São Paulo's ABC Paulista industrial belt specify cartons with ANVISA-certified barrier coatings.
- Boxes:Rigid and set-up boxes deploy thick paperboard or composite structures for gift and electronics presentation. Mexico City's Polanco and Santa Fe retail corridors drive demand for rigid boxes with magnetic closures and foil stamping.
- Bags:Multiwall sack constructions combine kraft plies with polyethylene barriers for cement, agricultural inputs, and chemical bulk. Brazilian grain exporters in Mato Grosso specify sewn open-mouth bags with ISPM-15 compliant marking for EU shipments.
- Wrapping Paper:Tissue-weight and kraft wrapping grades serve protective interleaving, decorative gift, and industrial void-fill functions. E-commerce fulfillment centers in Guadalajara consume machine-glazed wrapping for automated void-fill systems.
Boxes hold installed capacity. Cartons is rotating up the share rankings.
Product Type:
Margin structure and capital intensity separate the four substrate categories competing for converter investment.
- Corrugated Packaging:Fluted medium bonded to linerboard creates compressive strength for distribution stress. São Paulo beverage bottlers and Mexico City snack processors specify E-flute and B-flute profiles for automated case packing lines.
- Paperboard:Folding boxboard and solid bleached sulfate deliver print surfaces for pharmaceutical inserts and personal care cartons. ANVISA and COFEPRIS pharmaceutical contact-material rules redirect demand toward certified substrate grades with full chain-of-custody documentation.
- Kraft Paper:Unbleached sulfate pulp yields tear-resistant industrial packaging for bulk commodities. Chilean salmon processors and Brazilian soy exporters pilot kraft-based alternatives to ISPM-15 wood crating for Asian and European cold-chain shipments.
- Specialty Paper:Grease-resistant, moisture-barrier, and release-coated grades serve food service and medical sterilization wraps. Bio-based barrier formulations using nanocellulose and chitosan are qualifying at ANVISA for 18-month shelf-life beverage applications.
Corrugated Packaging dominates volume throughput. Specialty Paper is climbing the fastest on unit margin expansion.
End User:
Regulatory exposure and volume scale differentiate how each customer vertical procures packaging.
- Food & Beverage:The largest demand vertical spans processed foods, fresh produce, and beverages requiring moisture barriers and migration-compliant food contact surfaces. Brazil's southeast beverage cluster and Mexico's Baja California craft distilleries specify custom flute profiles and digital-print compatibility.
- Pharmaceuticals:Folding cartons, labels, and inserts must satisfy ANVISA and COFEPRIS stability testing for drug contact materials. Bogotá's pharmaceutical manufacturing base imports certified paperboard from Brazilian mills pending local qualification capacity.
- Personal Care:Premium cosmetic and hygiene brands demand high-gloss print surfaces and structural rigidity for shelf presence. São Paulo's Jundiaí and Campinas personal care corridors specify metallized and holographic board finishes.
- Consumer Goods:Electronics, home appliances, and durables require protective corrugated with anti-static and abrasion-resistant treatments. Guadalajara's consumer electronics assembly plants source triple-wall corrugated for export cushioning.
Food & Beverage holds installed capacity. Pharmaceuticals is gaining share fastest on compliance-driven specification upgrades.
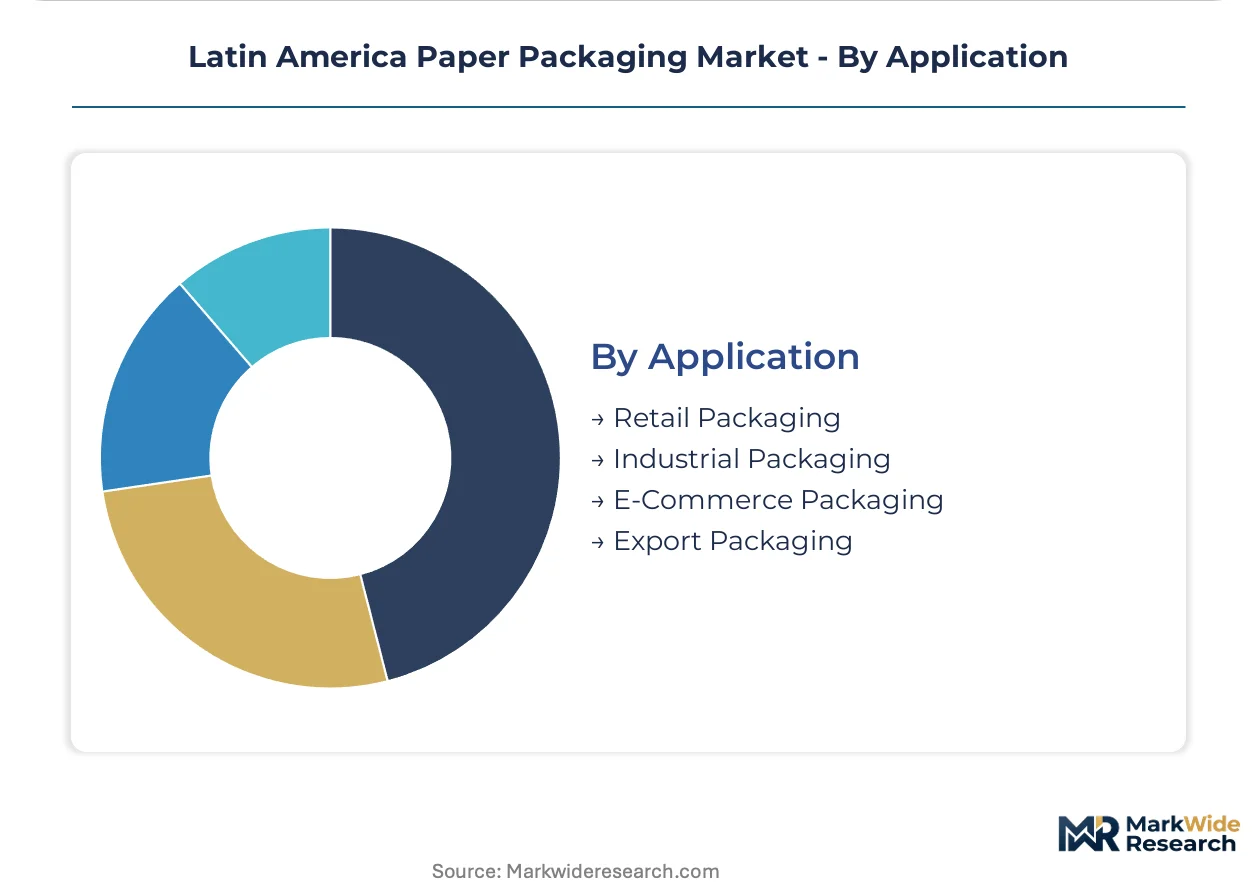
Application:
Distribution channel requirements partition demand across performance specifications and print complexity.
- E-Commerce Packaging:Corrugated boxes with RFID-ready print surfaces and easy-open features serve warehouse automation in São Paulo and Mexico City. Standardized RSC formats with 1.5-2.0 burst strength ratings accommodate automated sortation stress.
- Export Packaging:Phytosanitary compliance and ocean-container compression requirements drive kraft paper and heavy-duty corrugated specifications. Brazilian soy and Chilean fruit shipments to China require ISPM-15 alternatives with moisture-resistant barriers.
- Retail Packaging:Shelf-ready displays and primary cartons demand high-impact graphics and structural differentiation. Mexico's OXXO and Brazil's Ambev retail networks specify shelf-ready packaging with tear-away perforations.
- Industrial Packaging:Bulk commodity protection for grain, cement, and chemicals prioritizes tear strength and weather resistance over print quality. Colombian cement distributors specify multiwall sacks with PE liners for humidity protection in Cartagena port storage.
Industrial Packaging holds installed capacity. E-Commerce Packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA and IBAMA compliance requirements in Brazil are reshaping procurement patterns across Latin American paper packaging, with traceability mandates now extending to converted products destined for export markets.
Brazil
São Paulo state's beverage bottlers and processed food exporters generate concentrated demand for E-flute and B-flute corrugated formats. IBAMA's 2023 geolocation tagging protocol for native vegetation pulpwood forces converters to requalify suppliers. Suzano and Klabin anchor integrated supply from plantation to boxboard in the Southeast region.
Mexico
SEMARNAT's 2024 industrial air quality rules accelerate kiln conversions toward biomass firing at containerboard mills. Mexico City warehouse automation and Guadalajara e-commerce fulfillment centers specify RFID-ready corrugated with standardized RSC formats. Baja California craft distilleries pilot digital-print compatibility for short-run customization.
Chile
Salmon processors and fruit exporters drive demand for ISPM-15 compliant kraft paper alternatives to wood crating. SMA forestry certification enforcement shapes pulp sourcing timelines. Cold-chain shipments to Asian markets specify moisture-resistant barriers for 18-month shelf-life targets.
Colombia
Bogotá's pharmaceutical and personal care manufacturing clusters import certified paperboard pending local ANVISA-equivalent qualification capacity. Pending extended producer responsibility legislation will mandate brand-funded collection infrastructure. Cement distributors in Cartagena specify multiwall sacks with PE liners for port storage humidity protection.
Argentina
Grain exporters in the Pampas region specify sewn open-mouth kraft bags for EU and Asian shipments. Informal recycled fiber collection networks recover less than regional averages, forcing mills to source OCC from neighboring markets. Buenos Aires retail corridors sustain demand for shelf-ready display packaging.
Latin America Paper Packaging Market Competitive Landscape
Vertically integrated pulp-to-boxboard operators and regional containerboard specialists split the market between cost-controlled fiber supply and logistics network density. Brazilian players leverage captive eucalyptus plantations to compress fiber input cycles, while multinational converters compete through scale and recycling infrastructure. Three archetypes dominate: plantation-integrated pulp producers, regional corrugated scale operators, and specialty substrate importers. Capacity additions and certification compliance investments constitute the primary competitive vectors.
Among plantation-integrated operators, Suzano exemplifies backward integration from forestry to converted packaging, while Klabin occupies a similar position with Paraná state operations. Smurfit Westrock represents the regional scale archetype across multiple Latin American markets. These three anchors illustrate how fiber cost control and logistics density separate competitive tiers in corrugated and containerboard supply.
| Leading Market Players |
|---|
| Suzano |
| Mondi Group |
| Smurfit Westrock |
| Tetra Laval |
| Stora Enso |
| Klabin |
| Graphic Packaging International Corporation |
| Rengo |
| International Paper Company |
| Others |
Supply & Pricing Matrix
São Paulo state's corrugated capacity concentration grants integrated pulp-to-boxboard operators outsized leverage over pricing negotiations with beverage bottlers and processed food exporters across Brazil's southeast corridor. IBAMA's traceability mandates add compliance premiums to certified fiber grades, compressing margins for converters lacking backward integration into plantation assets.
Pricing Analysis
Price spreads between Brazilian Southeast and Andean markets reflect freight differentials and import duty structures on kraft linerboard. Three-tier pricing structure across premium, standard, and economy levels separates FSC 100% certified grades from mixed-source alternatives and uncertified commodity stock. Cost compression in standard-grade corrugated is intensifying because El Niño-driven fiber input volatility extends converter hedging costs. Small and mid-sized regional converters exhibit highest price sensitivity, while multinational CPG subsidiaries leverage volume commitments for dedicated production slots.
Supply Chain Analysis
Integrated plantation operators Suzano and Klabin hold captive pulp capacity, while Smurfit Westrock anchors containerboard scale across Brazil, Mexico, and Chile. Geographic supply concentration centers on Brazil, Mexico, and Chile, with Colombian and Peruvian markets drawing from imported bales. Raw material dependencies rest on eucalyptus pulp, recovered OCC, and bio-based barrier formulations. Single-source vulnerability runs through informal recycled fiber collection networks recovering less than regional averages. Distribution runs through direct mill partnerships consolidating fragmented regional converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational CPG subsidiaries negotiating long-term volume commitments, displacing fragmented regional converter relationships across Latin American paper packaging procurement.
For Market Incumbents: Harden FSC and PEFC chain-of-custody documentation systems against 12-18 month certification backlogs threatening export qualification timelines. Anchor capacity additions in Paraná and São Paulo states to defend fiber cost advantages against El Niño-driven input volatility. Prioritize servo-controlled corrugator upgrades enabling automated case packing line compatibility at dairy and meat processors. For New Entrants and Emerging Players: Establish a beachhead in Colombia's pharmaceutical folding carton segment, where Bogotá manufacturing clusters import 40% of certified paperboard from Brazilian mills pending local ANVISA-equivalent qualification capacity. Target digital print convergence with bio-based moisture barriers for craft beverage brands in Mexico's Baja California and Jalisco states. Lead with short-run customization capabilities and water-based inkjet systems bypassing incumbent qualification bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because extended producer responsibility frameworks across Chile, Peru, and Colombia will mandate brand-funded collection infrastructure opening equipment and logistics contracts. Acquisition focus should center on mid-tier converters with established ANVISA certification and traceable fiber sourcing systems. Monitor pending legislation implementation timelines as inflection indicator for recycled fiber availability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | FSC and PEFC chain-of-custody systems secure export qualification for IBAMA-compliant pulp sourcing. |
| Digital Print Capability Expansion | Water-based inkjet systems enable short-run customization for craft beverage brands in Baja California. |
| Biomass Kiln Conversion | SEMARNAT emissions compliance at Mexican containerboard mills improves linerboard output consistency. |
| Extended Producer Responsibility Positioning | Equipment and logistics contracts await pending legislation in Chile, Peru, and Colombia. |
| Barrier Coating Qualification | Bio-based nanocellulose formulations target ANVISA approval for 18-month shelf-life beverage applications. |
Research Methodology
Desk research of customs and trade data, forestry certification registries, and regulatory filings preceded structured interviews with containerboard mill procurement directors, corrugated converter operations managers, beverage bottler supply chain leads, and pharmaceutical packaging specification engineers. Secondary validation drew from ANVISA food contact substance databases, IBAMA traceability protocol documentation, and SEMARNAT emissions compliance records. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Assumptions held fixed include IBAMA geolocation tagging protocol enforcement intensity and SEMARNAT kiln conversion timelines, while El Niño rainfall pattern severity and extended producer responsibility legislation passage were varied across scenarios. Segmentation dimensions modeled encompass substrate type, end-use vertical, application format, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline values. Industry-specific inputs incorporated eucalyptus plantation productivity cycles and pharmaceutical contact-material qualification timelines.
Sensitivities concentrate around El Niño-driven fiber input volatility, pending EPR framework implementation delays, and certification audit capacity backlogs. Forecasts reflect documented assumptions on regulatory enforcement trajectories and recycled fiber collection infrastructure development. Quarterly review of IBAMA compliance cost pass-through rates and Colombian pharmaceutical import substitution progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Display Paper Box Market