
 China Paper Packaging Market | 2026-2036
China Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Paper Packaging Market Outlook
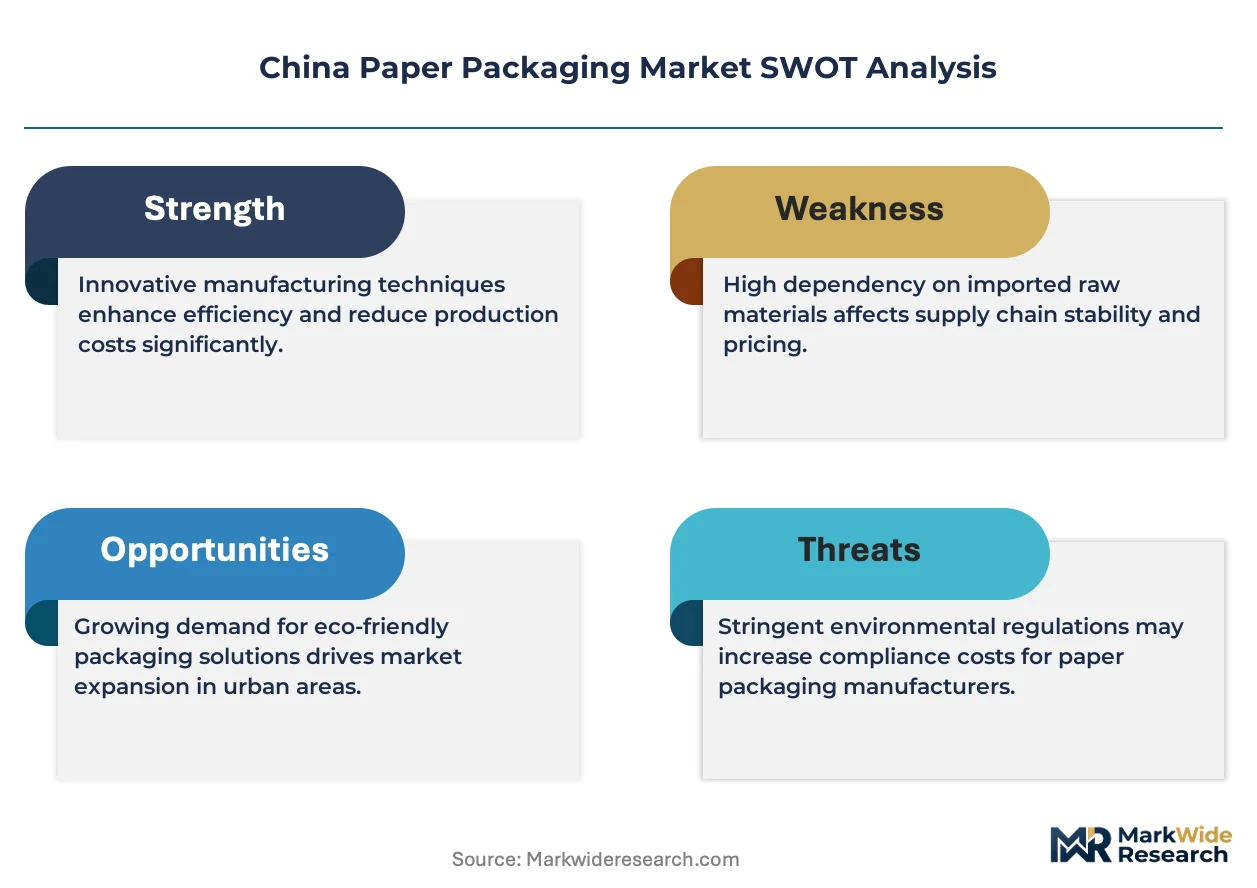
Buyer concentration across China's e-commerce fulfillment sector is broadening as platform operators diversify supplier rosters beyond captive converters. Nine Dragons Paper sustains upstream integration from recovered fiber through linerboard production, anchoring cost positions in corrugated supply. Shandong Bohui Paper Group leverages coated paper expertise to serve premium folding carton accounts in food and personal care segments. Anhui Shanying Paper Industry competes on recycled-content specialization, aligning procurement with circular economy mandates from major brand owners.
China paper packaging encompasses fiber-based containment and protection systems manufactured from kraft, recycled, or coated paper stocks through corrugation, folding, or bag conversion processes, typically specified by basis weight, burst strength, and moisture resistance to secure goods through distribution and retail presentation. Corrugated boxes dominate volume throughput due to structural utility in electronics and appliance logistics, while folding cartons command margin pools in healthcare and personal care where print fidelity and tamper evidence carry premium specification. Recycled paper material grades anchor cost-sensitive commodity segments, though virgin pulp and coated paper alternatives occupy premium positioning where surface quality and regulatory compliance for food contact applications justify higher input expense.
SAMR enforces labeling and food contact safety standards that constrain substrate selection and adhesive chemistry for domestic-market packaging, while MEE oversight of wastewater and emissions from pulping and coating operations shapes mill location and technology investment decisions. GB standards for recyclability and the dual carbon goals are progressively tightening embodied carbon thresholds, redirecting procurement toward certified fiber sources and energy-efficient converting equipment. Stakeholders must monitor enforcement variance across provincial environmental bureaus and anticipate how extended producer responsibility pilots in Shanghai and Shenzhen will reshape post-consumer collection economics and recycled fiber availability.
Market Dynamics
China's dual carbon goals are compressing embodied carbon thresholds across paper packaging supply chains, redirecting procurement toward certified fiber sources and energy-efficient converting equipment while tightening material specifications for domestic-market compliance.
Growth Catalysts
- GB standards for packaging recyclability:Tightening specifications for fiber recovery rates and contaminant limits are accelerating substitution of plastic with paper-based alternatives in food contact and logistics applications.
- E-commerce logistics expansion:Third-party fulfillment platforms are broadening adoption of corrugated shipping containers as order volumes surge across electronics and appliance categories.
- Yangtze River Delta cluster concentration:Dense converting capacity in Zhejiang and Jiangsu provinces creates procurement efficiencies for consumer goods manufacturers seeking integrated supply partnerships.
Market Restraints
- Recovered fiber cost volatility:Post-consumer collection economics fluctuate with extended producer responsibility pilot programs in Shanghai and Shenzhen, creating input price instability for recycled-content producers.
- Upstream linerboard supply concentration:Cost positions in corrugated supply depend on captive integration from recovered fiber through linerboard production, limiting negotiating leverage for independent converters.
- Food contact safety compliance friction:SAMR enforcement of substrate selection and adhesive chemistry constraints creates qualification timelines that delay new product introductions for domestic-market packaging.
Strategic Opportunities
- Healthcare and personal care folding carton premiumization:Print fidelity and tamper evidence specifications in these segments command margin pools that justify coated paper alternatives and specialized converting investment.
- Extended producer responsibility scaling:Pilot programs in Shanghai and Shenzhen are reshaping post-consumer collection economics, creating first-mover advantages for converters with certified circular supply chains.
- Digital print-coating convergence:Integration of inkjet systems with water-based barrier coatings enables short-run customization for regional brand owners without plate changeover costs.
Industry Challenges
- Provincial environmental bureau enforcement variance:MEE oversight of wastewater and emissions from pulping and coating operations creates compliance complexity for multi-site operators navigating inconsistent local interpretations.
- Legacy equipment retrofit capex burden:Energy-efficient converting equipment upgrades require capital deployment against compressed payback periods as dual carbon thresholds tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Paper Packaging Market |
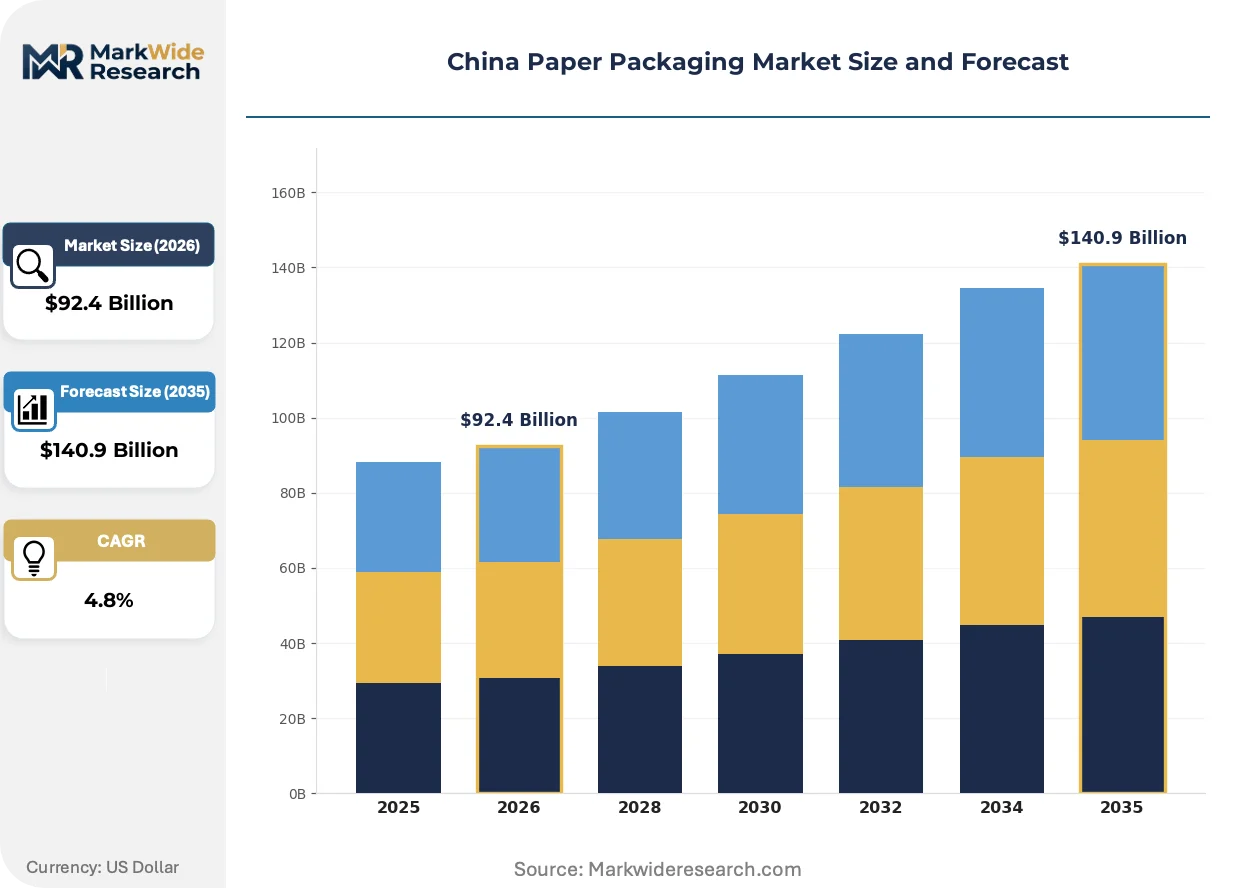
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Corrugated Boxes, Folding Cartons, Paper Bags, Wrapping Paper End User: Food & Beverage, Healthcare, Electronics, Personal Care Material: Recycled Paper, Virgin Pulp, Kraft Paper, Coated Paper Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Shandong Bohui Paper Group Co., Ltd, Guangdong Danqing Printing Co., Ltd., Nine Dragons Paper (Holdings) Limited, Qingdao Haimu Packaging Co., Ltd., Xiamen Hexing Packaging Printing Co., Ltd., SUN PAPER, Shanghai Custom Packaging Co., Ltd., Guangdong JieCheng Paper & Printing Co., Ltd., Anhui Shanying Paper Industry Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Paper Packaging Market Strategic Shifts
Water-based barrier coatings and digital print integration are reshaping specification patterns across food contact and premium presentation segments, while provincial carbon accounting systems reconfigure mill location decisions.
Water-based barrier coatings are consolidating performance parity with polyethylene laminates for moisture-sensitive applications. Food and personal care brand owners in the Yangtze River Delta are specifying these alternatives at accelerating rates to meet SAMR food contact safety standards. The technology is consolidating market share in folding carton segments where surface quality and regulatory compliance justify premium positioning.
MEE oversight of wastewater and emissions is tightening embodied carbon thresholds for pulping and coating operations. Industrial consequence includes mill relocation toward provinces with renewable energy access and carbon accounting infrastructure. Converting capacity in Jiangsu and Zhejiang faces the most acute compliance pressure, driving technology investment in closed-loop water systems.
Third-party logistics procurement models are fragmenting buyer concentration across e-commerce fulfillment. Platform operators are diversifying supplier rosters beyond captive converters, compressing contract durations and expanding spot-market purchasing. This pattern is most visible in electronics logistics corridors connecting Shenzhen manufacturing hubs to coastal port infrastructure.
China Paper Packaging Market Segmentation
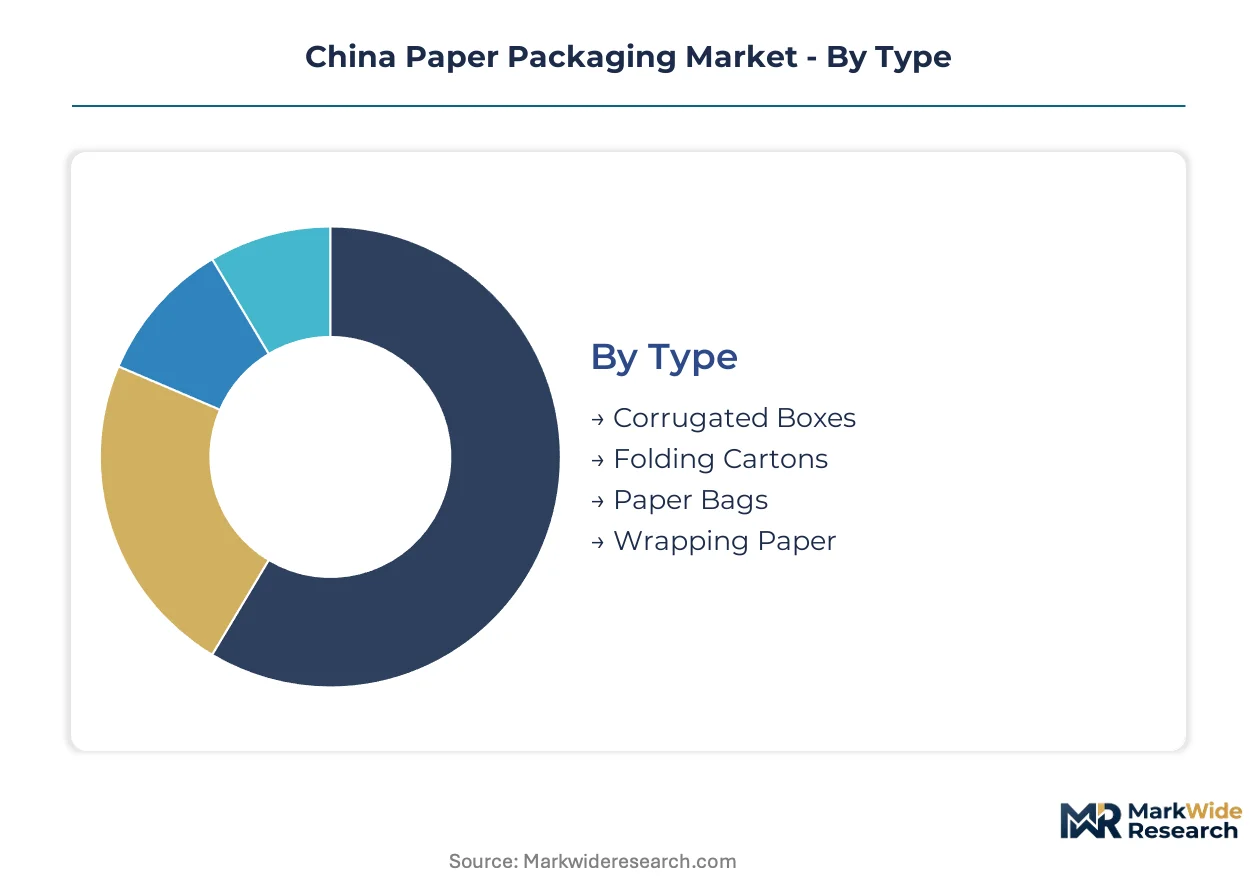
Segmentation in China's paper packaging market reveals how dual carbon mandates and GB recyclability standards are reshaping procurement patterns across converting capacity. Material specifications and end-use compliance requirements now determine supplier selection more than volume scale alone.
Type:
Supply concentration across converting formats reflects divergent capital intensity and technical barriers to entry.
- Corrugated Boxes:Fluted medium sandwiched between linerboard facings delivers structural rigidity for heavy-goods logistics. Electronics manufacturers in the Yangtze River Delta specify burst strength ratings above 200 psi for appliance shipments through third-party fulfillment platforms.
- Folding Cartons:Die-cut paperboard converted into rigid enclosures with tuck or lock closures. Healthcare and personal care brand owners in Jiangsu province demand print fidelity above 175 lpi and tamper-evident closures that satisfy SAMR food contact safety standards.
- Paper Bags:Flat or gusseted constructions from kraft or recycled stocks for retail carryout and food service.
- Wrapping Paper:Lightweight tissue or kraft grades for protective interleaving and gift presentation applications.
Corrugated boxes absorb the bulk of installed capacity; folding cartons are expanding most quickly.
End User:
Application-driven specification tiers separate commodity logistics from premium presentation segments.
- Food & Beverage:Substrate selection governed by SAMR migration limits and GB standards for direct food contact. Dairy and ready-meal processors in Zhejiang specify water-based barrier coatings as polyethylene laminate replacements.
- Electronics:Corrugated containers with electrostatic discharge coatings and precision die-cuts for component protection. Shenzhen manufacturing clusters drive spot-market purchasing through fragmented third-party logistics procurement.
- Healthcare:Folding cartons with child-resistant features and serialization compliance for pharmaceutical distribution.
- Personal Care:Premium coated paperboard with soft-touch varnishes and holographic authentication elements.
Food and beverage commands the deepest volume base; electronics is climbing the fastest on e-commerce fulfillment expansion.
Material:
Input cost structures and circular economy mandates are reconfiguring fiber sourcing strategies.
- Recycled Paper:Post-consumer fiber processed through deinking and dispersion for linerboard and medium production. Anhui Shanying Paper Industry and similar converters align procurement with extended producer responsibility pilots in Shanghai and Shenzhen.
- Virgin Pulp:Bleached or unbleached kraft pulp for food contact and premium surface quality applications. Pulp integration from captive forestry operations insulates Nine Dragons Paper from recovered fiber price volatility.
- Kraft Paper:Unbleached sulfate pulp with high tear resistance for industrial wrapping and shopping bag applications.
- Coated Paper:Clay or polymer surface treatments for high-resolution printing in cosmetics and pharmaceutical cartons.
Recycled paper holds the largest production footprint; virgin pulp is gaining share fastest on food safety compliance tightening.
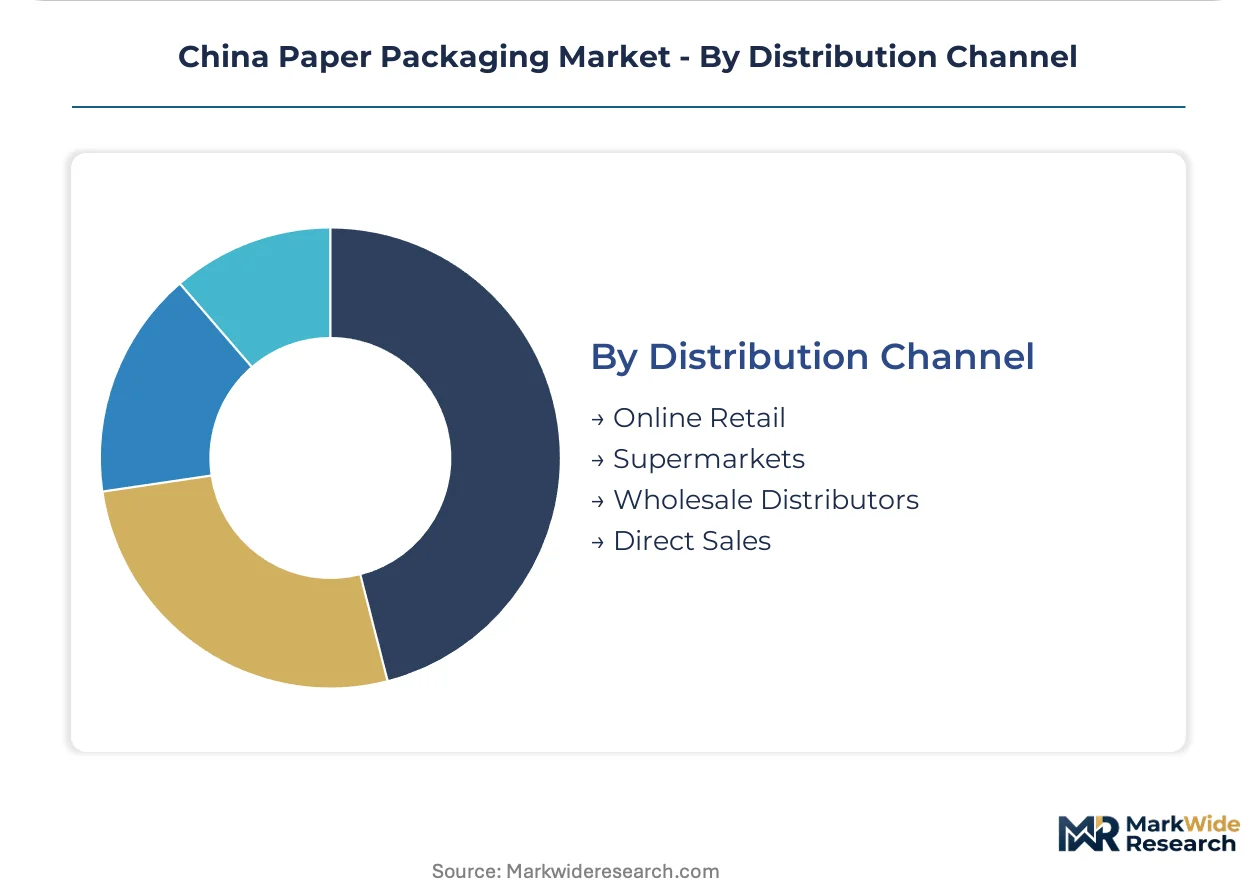
Distribution Channel:
Channel configuration determines order lot sizes, customization requirements, and working capital intensity.
- Online Retail:Direct-to-consumer fulfillment driving short-run digital print adoption and spot-market linerboard purchasing. Platform operators compress contract durations while diversifying beyond captive converters.
- Supermarkets:High-volume private label programs with standardized specifications and seasonal volume spikes.
- Wholesale Distributors:Inventory pooling for small and mid-sized converters lacking direct mill relationships.
- Direct Sales:Integrated supply partnerships between major consumer goods manufacturers and dedicated converting capacity in Jiangsu and Zhejiang.
Direct sales retains the most concentrated volume; online retail is expanding most quickly on platform logistics fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's paper packaging demand concentrates in coastal manufacturing belts where converting capacity clusters proximate to consumer goods production and port infrastructure. Provincial environmental enforcement variance and dual carbon compliance timelines create divergent investment conditions across sub-regional markets.
Yangtze River Delta
Zhejiang and Jiangsu provinces host dense concentrations of folding carton and corrugated converting capacity serving food and personal care brand owners. MEE wastewater discharge standards are tightening fastest here, accelerating mill investment in closed-loop water systems. Ningbo and Suzhou industrial zones see premiumization in healthcare packaging specifications.
Pearl River Delta
Guangdong province anchors electronics logistics demand through Shenzhen manufacturing hubs and third-party fulfillment platform procurement. SAMR food contact safety enforcement creates qualification friction for adhesive chemistry in dairy and ready-meal applications. Dongguan converting clusters specialize in short-run digital print for e-commerce customization.
Beijing-Tianjin-Hebei
Hebei province's linerboard production serves northern China corrugated demand with recovered fiber integration from municipal collection programs. Dual carbon goals are compressing embodied carbon thresholds fastest in this region, redirecting procurement toward certified fiber sources. Tianjin port infrastructure supports export-oriented containerboard logistics.
Shandong Peninsula
Shandong province combines virgin pulp integration with coated paperboard specialization for premium folding carton accounts. GB standards for packaging recyclability are tightening contaminant limits here, accelerating water-based barrier coating adoption. Qingdao and Yantai clusters serve Japanese and South Korean export markets with food contact compliance specialization.
Sichuan-Chongqing
Western China's emerging consumer market drives corrugated demand for appliance and electronics distribution into interior provinces. Extended producer responsibility pilots have not yet reached this region, creating recovered fiber cost advantages for recycled-content producers. Chengdu converting capacity expands to serve e-commerce fulfillment westward from coastal manufacturing.
China Paper Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital print-coating convergence and certified circular supply chains. The vendor base stratifies across three tiers: integrated pulp-to-box operators, regional converting specialists, and niche digital customization shops. Competitive positioning depends on recovered fiber cost management, SAMR compliance qualification speed, and Yangtze River Delta cluster proximity. M&A activity targets folding carton capacity in healthcare and personal care segments; greenfield investment concentrates in water-based barrier coating lines.
Among integrated operators, Nine Dragons Paper (Holdings) Limited and SUN PAPER exemplify upstream pulp control strategies. Anhui Shanying Paper Industry Co., Ltd represents recycled-content specialization aligned with circular economy mandates. Shandong Bohui Paper Group Co., Ltd occupies a position in coated paperboard premiumization for food contact applications. These three anchors illustrate how fiber sourcing strategy and compliance specialization determine competitive tier placement.
| Leading Market Players |
|---|
| Shandong Bohui Paper Group Co., Ltd |
| Guangdong Danqing Printing Co., Ltd. |
| Nine Dragons Paper (Holdings) Limited |
| Qingdao Haimu Packaging Co., Ltd. |
| Xiamen Hexing Packaging Printing Co., Ltd. |
| SUN PAPER |
| Shanghai Custom Packaging Co., Ltd. |
| Guangdong JieCheng Paper & Printing Co., Ltd. |
| Anhui Shanying Paper Industry Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Old corrugated container price indices and linerboard futures on the Shanghai Futures Exchange cascade through converting tiers, compressing margins for independent converters while integrated operators capture spread arbitrage across virgin pulp, recovered fiber, and finished box grades.
Pricing Analysis
Corrugated boxes trade on thin margins anchored to OCC spot markets, while folding cartons command premium spreads tied to coated paperboard certification tiers. Price differentiation hinges on SAMR food contact compliance grade and volume scale commitments from Yangtze River Delta brand owners. Cost compression in commodity corrugated intensifies as third-party logistics platforms fragment procurement into shorter contract windows. Electronics manufacturers exhibit highest price sensitivity, whereas healthcare and personal care segments absorb premium positioning for tamper-evident and child-resistant specifications.
Supply Chain Analysis
Recovered fiber supply rests on municipal collection programs concentrated in Shanghai, Shenzhen, and Guangzhou pilot zones, with virgin pulp integration anchored in Shandong and Hainan mill complexes. Key inputs span OCC grades, bleached kraft linerboard, and water-based barrier coating chemistries. Single-source vulnerability concentrates in linerboard supply from Nine Dragons Paper and SUN PAPER integrated operations. Distribution runs through direct mill partnerships for major consumer goods manufacturers, with spot-market purchasing dominating third-party e-commerce fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's paper packaging sector functions as a vertical-integration race where upstream pulp control and downstream converting capacity determine cost position survival, with dual carbon compliance timelines accelerating consolidation pressure.
For Market Incumbents: Anticipate MEE enforcement variance across provincial bureaus by standardizing wastewater treatment investments across all Jiangsu and Zhejiang facilities. Secure recovered fiber supply through extended producer responsibility pilot partnerships in Shanghai and Shenzhen. Certify circular supply chains ahead of GB recyclability standard tightening to defend margin position against recycled-content specialists.
For New Entrants and Emerging Players: Third-party logistics procurement officers represent the most accessible channel entry point for short-run digital print specialists. Target Dongguan and Chengdu converting corridors where e-commerce fulfillment fragmentation creates spot-market purchasing windows. Lead with water-based barrier coating capabilities for dairy and ready-meal processors seeking polyethylene laminate replacements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor folding carton specialists with SAMR food contact compliance infrastructure in Jiangsu province. Long-term viability centers on healthcare and personal care segments where print fidelity specifications sustain premium pricing. Watch extended producer responsibility program scaling beyond Shanghai and Shenzhen as the inflection signal for recovered fiber economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Pulp | Captive forestry operations insulate Nine Dragons Paper from OCC price volatility through Shandong and Hainan mill assets. |
| Water-Based Barrier Coating Line Expansion | Zhejiang dairy processors specify these alternatives to meet SAMR migration limits and GB food contact standards. |
| Digital Print-Coating Convergence | Dongguan clusters integrate inkjet systems with short-run customization for fragmented third-party logistics procurement. |
| Extended Producer Responsibility Partnership | Shanghai and Shenzhen pilot programs reshape post-consumer collection economics for certified circular supply chains. |
| Healthcare Folding Carton Capacity Acquisition | Jiangsu province demand for child-resistant features and serialization compliance commands sustained premium spreads. |
Study Parameters
Trade association filings, MEE environmental compliance disclosures, and Shanghai Futures Exchange linerboard contract data formed the secondary backbone, supplemented by primary interviews with converting plant managers, procurement leads at Yangtze River Delta consumer goods manufacturers, SAMR regulatory affairs specialists, and third-party logistics platform operators. Bottom-up capacity assessments across Zhejiang and Jiangsu converting clusters triangulated against top-down demand modeling from e-commerce fulfillment volume trends.
Historical trendline analysis of OCC price indices, linerboard capacity utilization rates, and folding carton specification premiums established baseline growth patterns across the projection horizon. Segmentation dimensions encompassed converting format, end-use compliance tier, fiber sourcing strategy, and distribution channel structure. CAGRs derived from elasticity modeling against e-commerce logistics expansion and dual carbon policy implementation timelines, with SAMR enforcement variance and recovered fiber collection economics as key sensitivity inputs.
Several conditions sit outside the modeled scope, including abrupt MEE regulatory reinterpretations, trade policy shifts affecting pulp imports, and technological disruption in alternative packaging substrates. Forecasts reflect documented assumptions about extended producer responsibility program scaling and provincial carbon accounting infrastructure rollout. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Italy Paper Packaging Market