
 Paper Cups Market | 2026-2036
Paper Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cups Market Intelligence
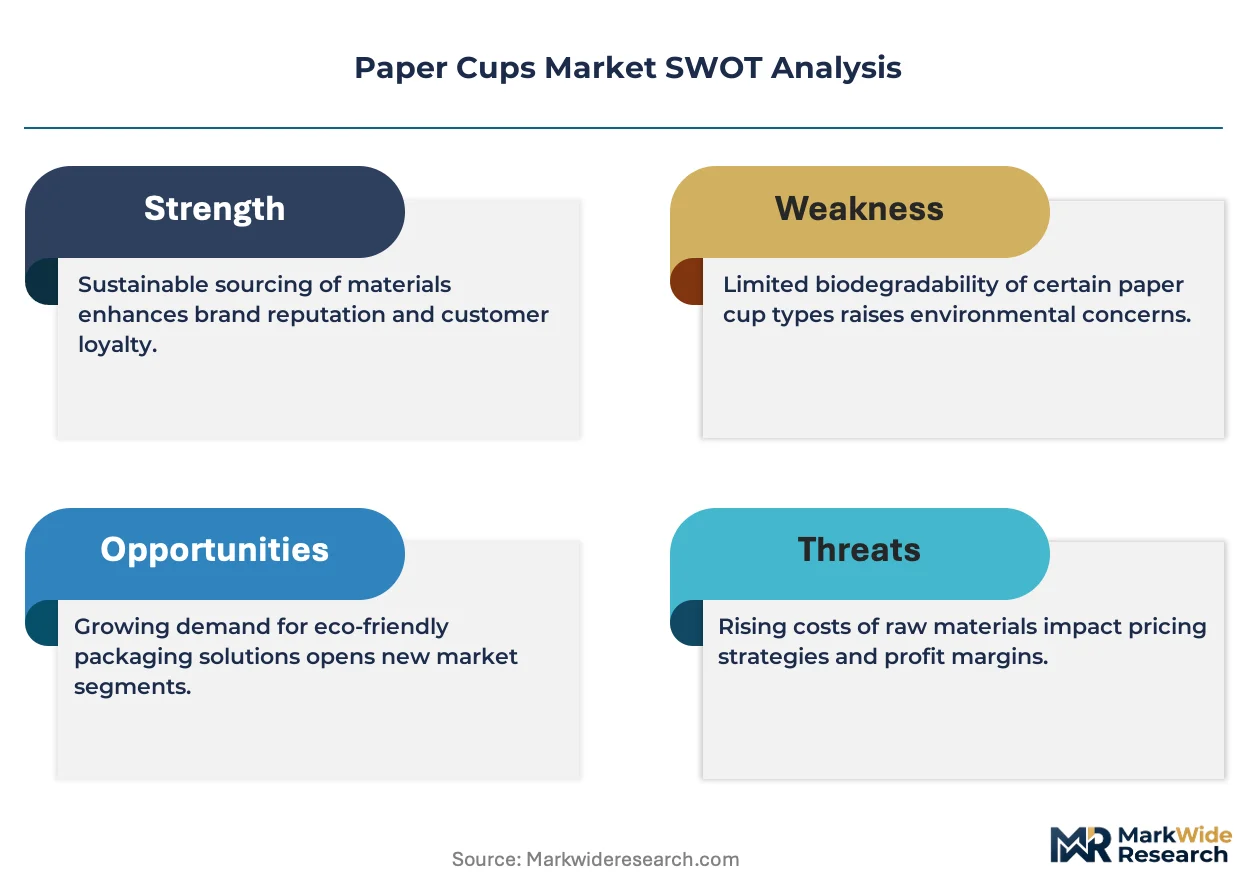
Aftermarket service revenue in cup-lining refurbishment and custom-print design is tilting margin pools away from commodity manufacturing. Huhtamaki Oyj leverages its European coating technology centers to sustain premium positioning in insulated formats. International Paper Company anchors North American supply through integrated pulp-to-cup operations. Dart Container Corporation specializes in high-volume food service contracts that dominate the QSR channel.
Paper cups are cylindrical containers formed from wood-pulp fiberboard, typically lined with polyethylene or polylactic acid to prevent liquid penetration, and manufactured through die-cutting, side-seaming, and bottom-knurling processes for hot and cold beverage service. Double wall construction commands the strongest margin pool in café and specialty retail channels where heat retention determines repeat purchase. Biodegradable coating materials represent the fastest-growing material segment as food service operators face plastic-reduction mandates. Virgin paper still occupies the largest volume share in quick-service applications where cost sensitivity overrides sustainability premiums.
The FDA regulates food-contact substances in the United States, while the EU Green Deal and REACH framework restrict per- and polyfluoroalkyl substances in paper-based food packaging across Europe. China's SAMR enforces GB standards for food-contact paper products, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor regulatory divergence on coating chemistries to avoid stranded inventory or market access barriers.
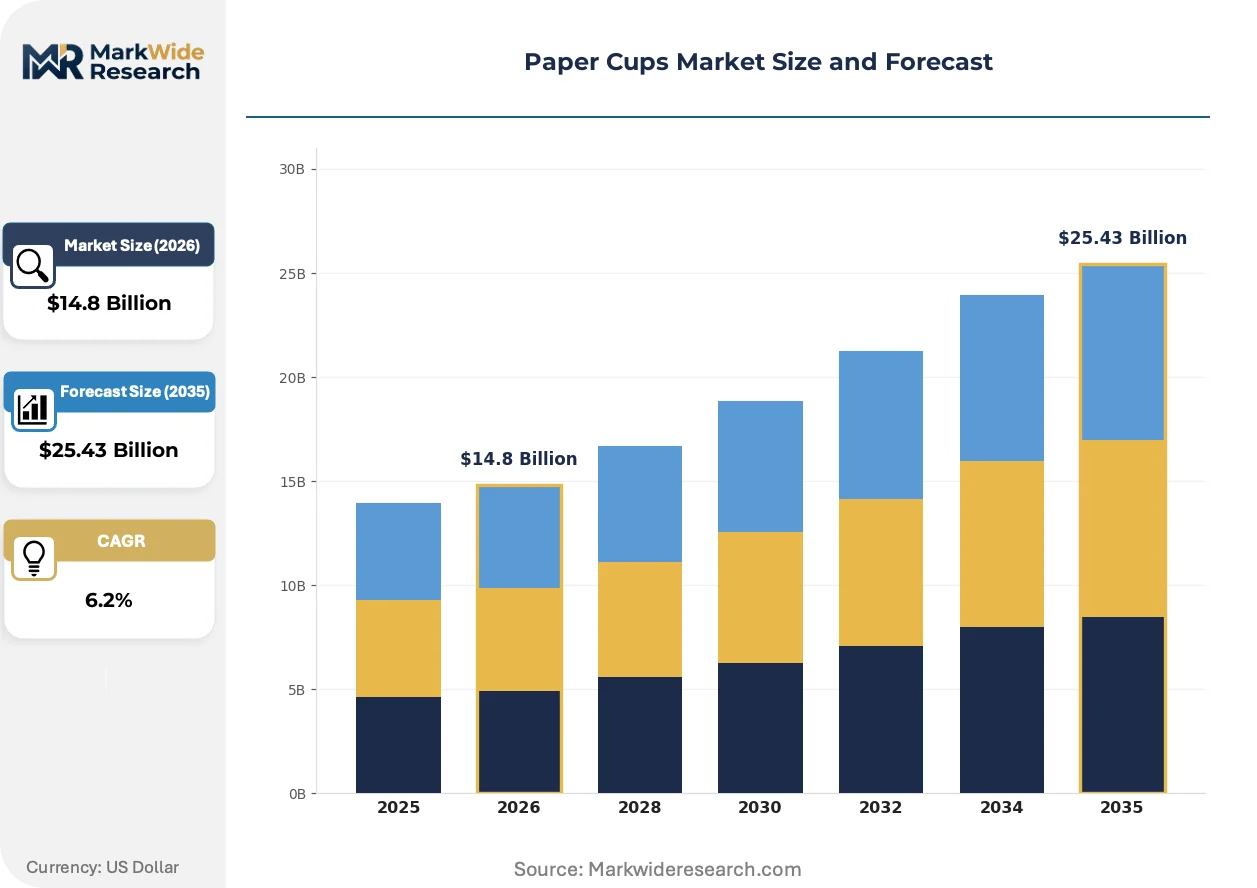
Market Dynamics
Biodegradable coating chemistry is forcing a capital reallocation across the paper cups supply base as food service chains face compliance deadlines under the EU Single-Use Plastics Directive and comparable mandates in China and India.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework bans specific single-use plastic items and mandates recycled content thresholds, accelerating food service migration toward fiber-based alternatives with certified biodegradable linings.
- Café culture penetration:China's tier-one cities are expanding specialty coffee retail footprints, creating concentrated demand for double-wall insulated formats that command premium positioning in Beijing and Shanghai.
- Takeaway expansion:Food service chains across India and Southeast Asia are scaling delivery and grab-and-go operations, driving unit volume growth in cold-cup formats for bubble tea and quick-service beverages.
Market Restraints
- Pulp cost volatility:Virgin wood pulp prices fluctuate with energy and freight inputs, compressing margins for converters lacking long-term fiber supply agreements or integrated pulp operations.
- Coating supply concentration:Specialized polylactic acid and aqueous barrier resin production concentrates among a limited set of chemical suppliers, creating bottleneck risk for cup manufacturers scaling biodegradable output.
- Performance gaps in hot-fill:Current biodegradable coatings exhibit heat tolerance limitations below polyethylene standards, restricting their deployment in high-temperature coffee applications without double-wall construction cost premiums.
Strategic Opportunities
- India's untapped food service infrastructure:Organized quick-service restaurant penetration remains below developed-market levels, presenting whitespace for cup suppliers establishing early partnerships with expanding domestic and international chains.
- Aftermarket service layering:Custom-print design and cup-lining refurbishment services enable margin capture beyond commodity manufacturing, particularly for regional food service brands seeking differentiated packaging.
- China's GB standard evolution:SAMR enforcement of updated food-contact paper standards creates compliance-driven replacement cycles, favoring suppliers with certified in-house testing and regulatory navigation capabilities.
Industry Challenges
- Coating chemistry talent scarcity:Formulation expertise spanning polymer science, food safety, and heat-seal engineering concentrates among a narrow specialist pool, extending R&D timelines for new biodegradable barrier development.
- Legacy equipment retooling:Converting lines optimized for polyethylene extrusion require substantial modification to handle aqueous and PLA coating chemistries, straining capital allocation for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cups Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Specialty End User: Food Service, Retail, Events, Cafés Material: Recycled Paper, Virgin Paper, Biodegradable Coating, Laminated Paper Capacity: 8 oz, 12 oz, 16 oz, 20 oz |
| Companies Covered | International Paper Company, Huhtamaki Oyj, Dart Container Corporation, Benders Paper Cups, Pactiv Evergreen, Berry Global Group, Georgia-Pacific, WestRock Company, Genpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cups Market Strategic Shifts & Innovations
Barrier coating innovation is compressing the performance gap between petroleum-based and bio-based linings, while regulatory fragmentation across major economies forces supply chain regionalization.
Aqueous barrier coatings are collapsing the historical trade-off between compostability and liquid resistance in single-wall cup construction. Specialty coffee chains in Nordic markets and California are piloting these formats at scale, eliminating the polyethylene separation step required for industrial composting and reducing end-of-life complexity for municipal waste systems.
REACH framework restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from European paper food packaging. Cup manufacturers serving EU markets are reformulating barrier layers to exclude PFAS compounds, with quick-service operators accelerating supplier audits to preempt enforcement actions and avoid inventory seizures at port.
Consolidated procurement by multinational food service groups is displacing fragmented regional purchasing, concentrating volume with suppliers offering multi-continent certification coverage and unified quality systems. This pattern is most visible in China, where domestic coffee chains expanding across tier-two cities are adopting the sourcing standards of their international competitors, compressing the supplier base toward integrated global players.
Paper Cups Market Segmentation
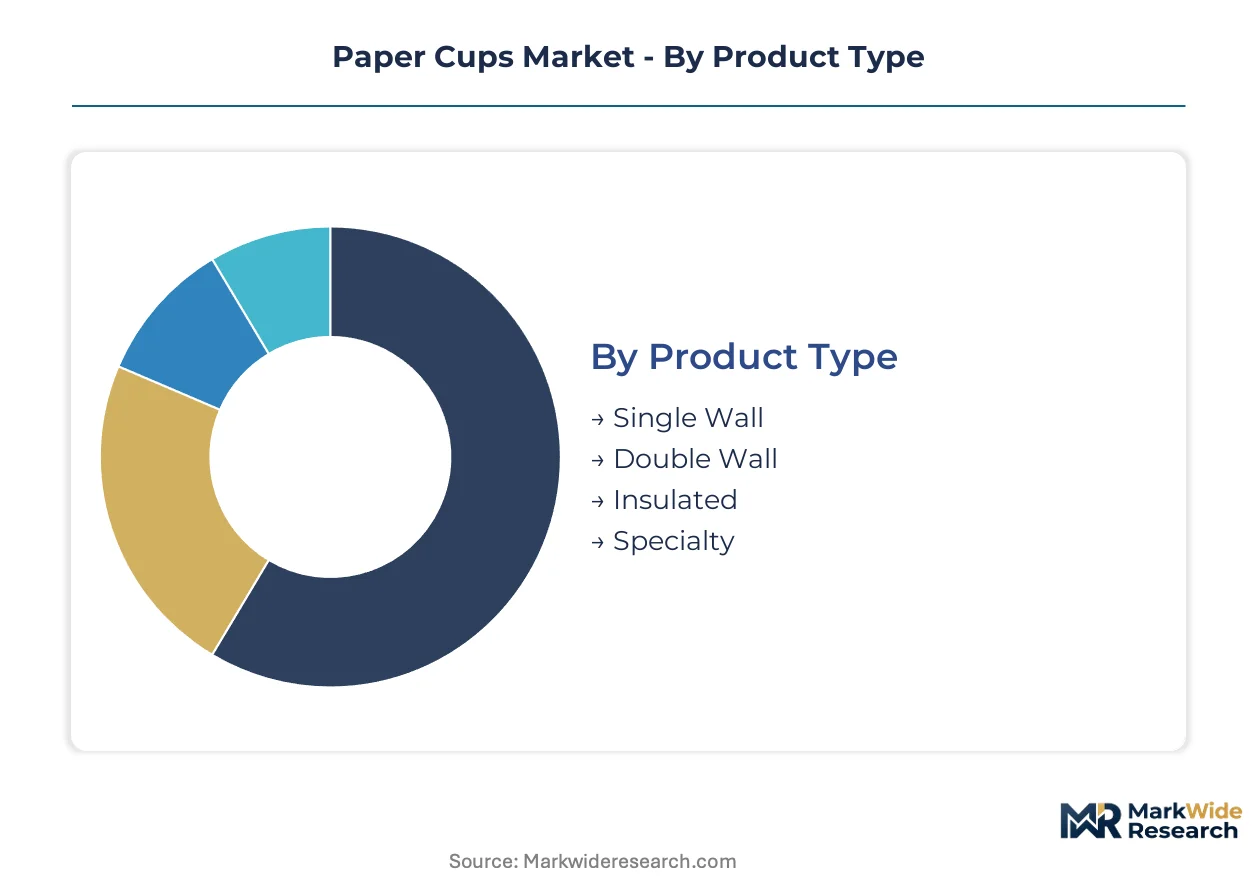
Paper cup segmentation reflects divergent performance requirements across temperature tolerance, sustainability mandates, and consumption occasions. Manufacturers configure production lines around these dimensions to capture margin pools in insulated café formats versus high-volume quick-service cold cups.
Product Type:
Wall construction separates cost tiers from premium heat-retention performance in beverage service applications.
- Single Wall:One-layer fiberboard construction with polyethylene or aqueous barrier coating. Quick-service operators in India and Southeast Asia deploy these for cold beverages where heat insulation is unnecessary, prioritizing unit economics over thermal performance.
- Double Wall:Nested cup construction with trapped air layer providing 40-50% superior heat retention versus single-wall alternatives. Specialty coffee chains in Beijing and Shanghai specify these for Americano and latte service where handheld comfort determines repeat purchase.
- Insulated:Foamed or textured outer layers engineered for extended heat retention in grab-and-go environments. Airport and railway food courts specify these for commuter coffee programs.
- Specialty:Custom die-cut shapes, embossed branding surfaces, or integrated sip-lid systems for limited-edition beverage launches. Regional bubble tea chains commission these for seasonal menu promotions.
Single Wall commands the established base. The steepest expansion runs through Double Wall.
End User:
Customer type determines volume scale, customization depth, and certification requirements in procurement decisions.
- Food Service:Quick-service restaurant chains and institutional caterers purchasing pallet-scale quantities with standardized print specifications. McDonald's and Domino's franchisees in tier-two Chinese cities drive consolidation toward suppliers with SAMR-certified testing capabilities.
- Retail:Supermarket and convenience store private-label programs requiring rapid design turnaround for promotional cycles. Cold-cup formats for refrigerated beverage cases dominate this channel.
- Events:Stadium, festival, and conference contractors sourcing compostable formats to meet municipal waste diversion mandates. Nordic music festivals specify aqueous-coated single-wall cups for industrial composting compatibility.
- Cafés:Independent and chain specialty coffee operators prioritizing Instagram-ready aesthetics and heat retention. Shanghai's independent café density creates concentrated demand for premium double-wall with custom sleeve printing.
Food Service commands the established base. The steepest expansion runs through Cafés.
Material:
Raw material selection captures the tension between regulatory compliance timelines and established supply chain economics.
- Recycled Paper:Post-consumer fiber content ranging from 30-100% depending on food-contact certification requirements. EU Green Deal recycled content thresholds are elevating specification rates in European quick-service contracts.
- Virgin Paper:Unbleached or bleached kraft pulp delivering consistent fiber strength and food-safety traceability. Cost-sensitive operators in India's nascent organized food service sector specify these for cold-beverage applications.
- Biodegradable Coating:Polylactic acid or aqueous barrier formulations enabling industrial composting certification. California's SB 54 implementation and EU Single-Use Plastics Directive deadlines are accelerating migration from polyethylene linings.
- Laminated Paper:Multi-layer constructions combining paper substrates with aluminum or metallized films for extended shelf-life applications. Pre-packaged beverage manufacturers specify these for ambient distribution.
Virgin Paper commands the established base. The steepest expansion runs through Biodegradable Coating.
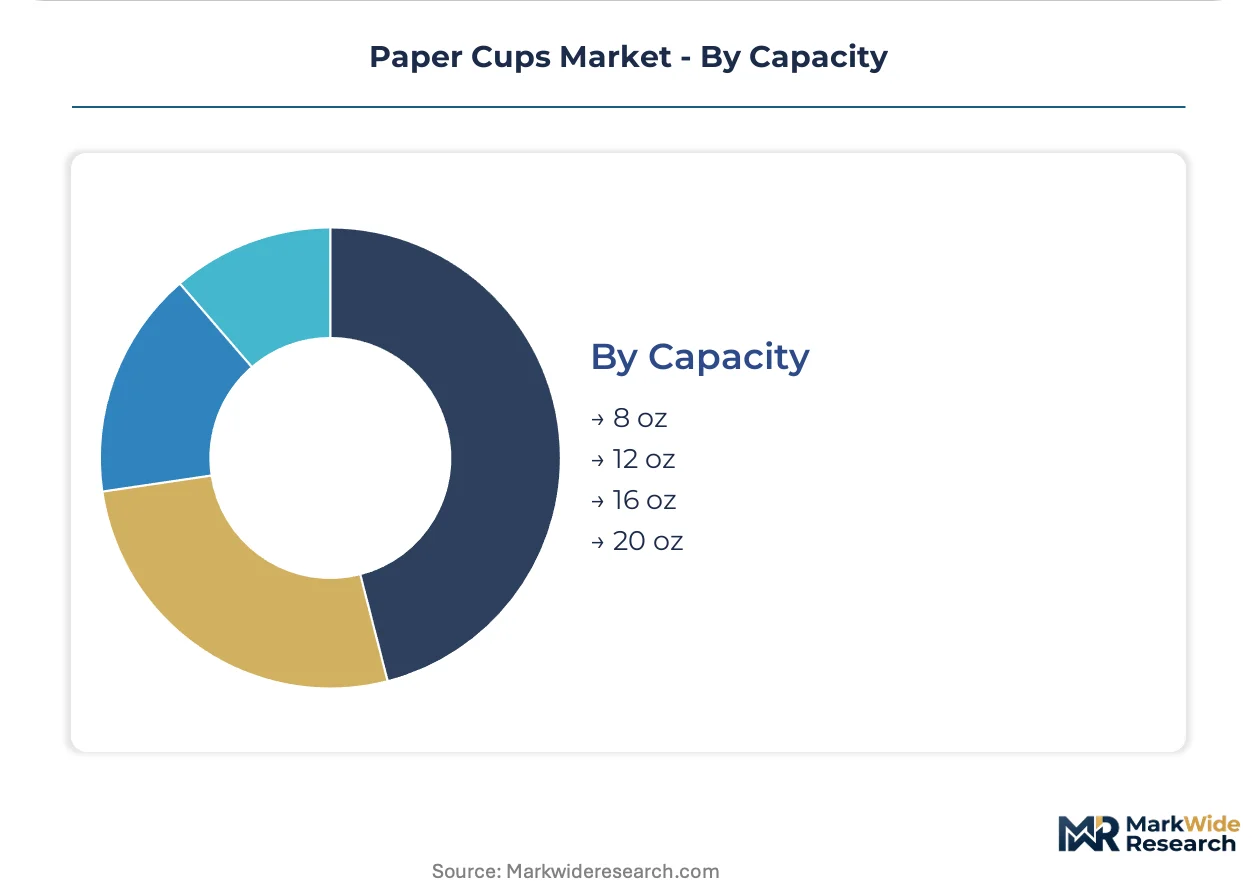
Capacity:
Volume sizing aligns with beverage category conventions and regional consumption patterns in coffee and tea markets.
- 8 oz:Standard espresso-based drink format in European and East Asian café protocols. Italian coffee culture influence preserves demand despite supersizing trends elsewhere.
- 12 oz:North American small-size standard and Chinese tier-one city default for specialty coffee. Starbucks' China menu architecture anchors this specification.
- 16 oz:US medium and large-format default for drip coffee and fountain beverages. Drive-through channel concentration in suburban American markets sustains volume.
- 20 oz:Extra-large format for iced coffee, bubble tea, and fountain soda applications. Southeast Asian bubble tea chains in Bangkok and Jakarta drive specification innovation with sealed-lid compatibility requirements.
12 oz commands the established base. The steepest expansion runs through 16 oz.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys double-wall insulated formats for specialty coffee culture while India and Southeast Asia favor single-wall cold cups for cost-driven takeaway expansion. The United States anchors North American volume through integrated pulp-to-cup supply chains. European operators face the strictest coating chemistry mandates under the EU Single-Use Plastics Directive.
China
Beijing and Shanghai café density drives premium double-wall specifications for heat retention in Americano and latte service. SAMR enforces updated GB standards for food-contact paper products, creating compliance-driven replacement cycles. Tier-two cities including Chengdu and Hangzhou are adopting international chain sourcing standards as domestic coffee brands expand.
United States
Quick-service restaurant chains and institutional food service operators generate pallet-scale demand for standardized cold-cup formats. FDA food-contact substance regulations govern polyethylene and aqueous barrier approvals. The Southeast and Midwest manufacturing corridors host integrated pulp-to-cup operations serving national distribution networks.
Germany
Nordic market spillover and domestic café culture sustain demand for compostable single-wall formats with aqueous coatings. REACH framework restrictions on PFAS compounds force barrier layer reformulation across paper food packaging. The Rhine-Ruhr industrial cluster concentrates converting capacity for EU-wide export.
India
Organized quick-service restaurant penetration below developed-market levels creates whitespace for cold-cup volume growth in bubble tea and beverage delivery. FSSAI food safety standards apply to food-contact paper materials with increasing enforcement stringency. Mumbai and Bangalore food service infrastructure expansion drives unit demand from domestic and international chain partnerships.
Indonesia
Jakarta and Surabaya food service chains scale grab-and-go operations for bubble tea and quick-service beverages. National regulations on food-contact materials align with ASEAN harmonization initiatives. Java-based manufacturing capacity is expanding to serve Southeast Asian export demand for cost-optimized single-wall construction.
Paper Cups Market Key Industry Players
Capability concentration sits with integrated pulp-to-cup operators; scale advantage sits with high-volume food service contract specialists. The vendor base separates into three tiers: global integrated players with multi-continent certification coverage, regional converters serving domestic quick-service chains, and specialty coating technology licensors. Dominant competitive moves include backward integration into pulp supply and strategic partnerships for biodegradable barrier resin access.
Among North American integrated operators, International Paper Company anchors supply chain control through captive pulp operations. Finnish packaging specialists Huhtamaki Oyj exemplify the premium-tier archetype through European coating technology positioning. Dart Container Corporation sits within the scale-driven contract tier, capturing volume concentration in quick-service restaurant procurement. These three patterns represent the structural segmentation governing competitive dynamics.
| Leading Market Players |
|---|
| International Paper Company |
| Huhtamaki Oyj |
| Dart Container Corporation |
| Benders Paper Cups |
| Pactiv Evergreen |
| Berry Global Group |
| Georgia-Pacific |
| WestRock Company |
| Genpak |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's converting corridor is compressing contract margins for single-wall commodity formats while tightening supply for certified biodegradable coatings. This utilization asymmetry rewards integrated operators with captive coating technology and pressures merchant converters toward spot-market pulp procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational quick-service chains and integrated pulp-to-cup operators, insulating volume buyers from pulp cost spikes. Price differentiation separates SAMR-certified premium double-wall formats from uncoated single-wall commodity tiers. Pricing pressure stems from coating chemistry bottlenecks as PLA and aqueous barrier resin supply concentrates among limited chemical suppliers. Food service chains in India and Southeast Asia exhibit highest price sensitivity, while Nordic café operators absorb sustainability premiums for compostable formats.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Dart Container Corporation and Pactiv Evergreen in the United States, Huhtamaki Oyj in Finland, and Georgia-Pacific across the American Southeast. Raw material supply draws from Brazilian eucalyptus pulp, Scandinavian softwood fiber, and corn-derived PLA feedstock. Single-source vulnerability in specialized aqueous barrier resin production creates bottleneck risk for biodegradable cup scaling. Distribution runs through food service redistribution centers, direct chain procurement, and retail private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as EU Single-Use Plastics Directive compliance deadlines force replacement demand across European food service infrastructure.
For Market Incumbents: Harden coating chemistry capabilities through backward integration into barrier resin supply or exclusive partnerships with PLA producers. Lock in long-term fiber supply agreements to neutralize pulp volatility threatening margin stability in commodity single-wall segments.
For New Entrants and Emerging Players: Build out regional converting capacity in India's tier-two cities where organized quick-service penetration trails developed-market saturation. Partner with domestic bubble tea chains for cold-cup volume contracts, leveraging lower capital intensity of single-wall equipment versus insulated format lines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators with multi-continent certification coverage and captive coating technology. Target mid-scale converters in Southeast Asia with established quick-service relationships but limited biodegradable capabilities. Monitor SAMR enforcement actions on GB standard compliance as inflection signal for replacement-driven demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Coating Scale-Up | PLA and aqueous barrier expansion captures EU Green Deal and California SB 54 compliance premiums. |
| Backward Integration into Pulp | Captive fiber supply neutralizes Brazilian and Scandinavian pulp price volatility for margin stability. |
| Regional Certification Investment | SAMR and FSSAI testing capabilities unlock tier-two city expansion in China and India. |
| Aftermarket Service Layering | Custom-print design and refurbishment contracts capture margin beyond commodity manufacturing. |
| Strategic Partnership for Resin Access | Exclusive aqueous barrier supply agreements preempt coating chemistry bottlenecks. |
Research Approach
A spread of perspectives from coating technology specialists, food service procurement directors, pulp supply traders, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU ECHA substance restrictions, FDA food-contact substance filings, Chinese customs trade data, and SEC disclosures from integrated packaging operators. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply balance modeling tracked wall construction tiers, coating chemistry migrations, and regional regulatory enforcement patterns throughout the forecast period. Segmentation dimensions included product type, end-user channel, material specification, and capacity sizing. CAGRs derived from regression analysis of historical volume trajectories adjusted for mandate-driven replacement cycles and café culture penetration rates in tier-one Chinese cities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by chemical suppliers into downstream converting would shift outcomes. Regulatory acceleration on PFAS restrictions or pulp supply disruptions from energy cost spikes could compress margins faster than modeled. Quarterly review of SAMR enforcement bulletins and EU coating chemistry rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market