
 Paper Boxes Market | 2026-2036
Paper Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Boxes Market Analytics
Southeast Asia is fragmenting as Vietnam, Indonesia, and Thailand add containerboard and folding carton capacity to serve relocated consumer goods manufacturing. International Paper leverages its integrated pulp-to-box network across North American mills to sustain cost discipline. Smurfit Kappa anchors European corrugated supply through recycled fiber dominance and pan-regional plant coverage. WestRock competes via specialty coated and high-graphics packaging for branded consumer products.
Paper boxes are rigid or semi-rigid containers manufactured from paperboard, containerboard, or recycled fiber pulp, typically ranging from 200 gsm to 800 gsm in basis weight and formed through cutting, scoring, folding, or adhesive bonding processes; they serve primary functions in product protection, unitization, shelf presentation, and logistics handling across supply chains. Corrugated boxes dominate tonnage and revenue within the product type dimension due to their ubiquity in shipping and bulk distribution, while rigid boxes command premium margin pools in cosmetics and gift applications where structural integrity and surface finish justify higher unit economics. E-commerce end users represent the fastest-growing demand pool as unboxing experience requirements and return-loop durability standards reshape specifications away from pure cost minimization.
FDA food contact regulations in the United States, EU REACH compliance for recycled fiber contaminants, and China's GB standards for packaging heavy metals collectively shape material sourcing, coating chemistries, and cross-border market access for box manufacturers serving multinational brand owners. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content thresholds that redirect investment toward closed-loop fiber recovery systems. Stakeholders must monitor how diverging national recycling infrastructure maturity and enforcement timelines alter competitive cost positions between virgin and recycled fiber supply chains.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing fiber recovery system investments across European corrugated networks while e-commerce fulfillment density in China's coastal export zones pulls containerboard specifications toward return-loop durability standards.
Growth Catalysts
- E-commerce fulfillment density:Unboxing experience requirements and return-loop durability standards in China's coastal export zones are reshaping box specifications away from pure cost minimization toward structural integrity benchmarks.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates and recycled content thresholds redirect capital toward closed-loop fiber recovery systems, tightening material recovery targets for corrugated and folding grades.
- Relocated consumer goods manufacturing:Vietnam, Indonesia, and Thailand are adding containerboard and folding carton capacity to serve manufacturing migration from higher-cost production bases.
Market Restraints
- Recycled fiber input volatility:Old corrugated container availability fluctuates with retail inventory cycles and residential collection rates, compressing margin predictability for mills dependent on post-consumer furnish.
- China's GB standards for heavy metals:Cross-border market access for box manufacturers serving multinational brand owners faces compliance friction from divergent contaminant thresholds between Chinese national standards and EU REACH protocols.
- Plastic substitution in moisture-barrier applications:Polyethylene-coated paperboard and molded fiber alternatives encroach on frozen food and fresh produce segments where wax-impregnated corrugated has historically dominated.
Strategic Opportunities
- India's organized retail expansion:Modern trade penetration in tier-two and tier-three cities creates demand for shelf-ready packaging with high-graphics folding carton specifications previously concentrated in export-oriented manufacturing.
- Dual carbon goals alignment:China's MEE enforcement of carbon intensity benchmarks creates preferential procurement channels for box suppliers with verified Scope 3 fiber traceability and renewable energy certificates.
- Smart packaging convergence:Integration of printed electronics and NFC-enabled authentication into rigid box structures opens premium-margin applications in cosmetics and pharmaceutical anti-counterfeiting.
Industry Challenges
- Skilled die-cutting and creasing technicians:High-graphics folding carton production requires precision setup expertise that aging workforces in mature manufacturing regions struggle to replenish through apprenticeship pipelines.
- FDA food contact certification timelines:Migration testing for recycled fiber contaminants in direct-contact applications extends product development cycles, delaying market entry for sustainable packaging innovations targeting US food service.
- Legacy ERP integration with fiber traceability platforms:Closed-loop recovery systems require real-time inventory visibility that conflicts with batch-oriented production planning systems prevalent in mid-cap box plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Boxes Market |
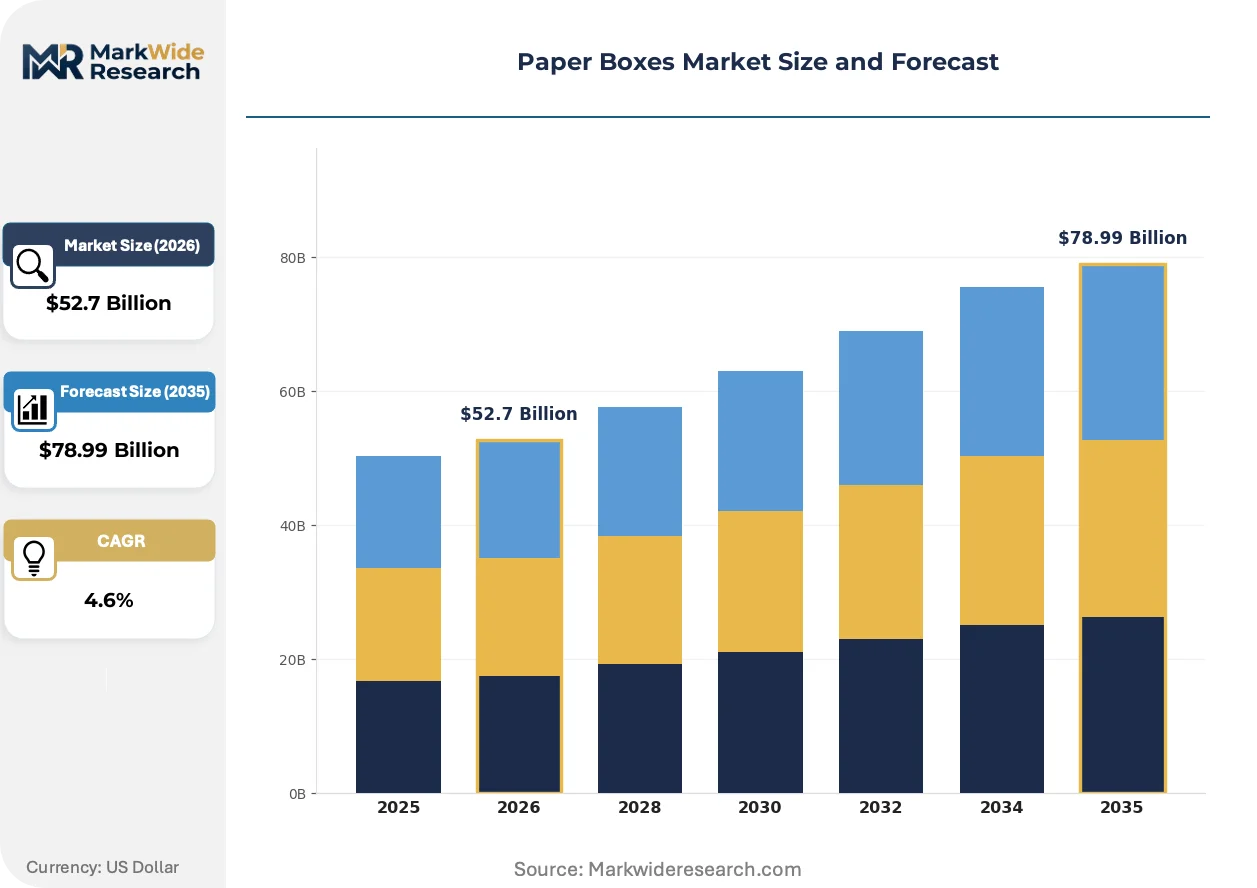
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $78.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxes, Rigid Boxes, Corrugated Boxes, Die-Cut Boxes End User: Food & Beverage, Cosmetics, Electronics, E-commerce Packaging Type: Single Wall, Double Wall, Triple Wall, Printed Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | International Paper, Smurfit Kappa Group, WestRock, Mondi Group, DS Smith, Rengo Co., Ltd., Nine Dragons Paper (Holdings) Limited, Georgia-Pacific, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Boxes Market Evolving Landscape
Active reshaping in paper boxes centers on specification migration from pure cost engineering toward experience-driven structural design, regulatory-forced material provenance transparency, and procurement model compression from spot purchasing to integrated supply contracts.
Water-based barrier coatings are migrating from niche frozen food applications toward mainstream produce and e-commerce segments. Retailers and third-party logistics providers in Germany and the Netherlands are specifying these coatings at accelerating rates to meet EU Green Deal circularity commitments. This migration from wax and polyethylene laminates is compressing the addressable market for traditional moisture-resistant grades while expanding premium positioning for certified-compostable alternatives.
REACH compliance for recycled fiber contaminants is tightening coating chemistry restrictions across European supply chains. Industrial consequence includes mandatory substitution of certain optical brighteners and biocides in paperboard surface treatments. Food-contact folding carton segments serving pan-European brand owners are responding with accelerated virgin fiber blending and third-party chain-of-custody certification to maintain market access.
Buyer concentration among mega-retailers and platform aggregators is compressing supplier negotiation leverage and standardizing box specifications across private-label portfolios. Direct procurement relationships with containerboard mills are displacing traditional converter intermediaries in North American and Western European markets. This concentration is most visible in grocery and consumer electronics verticals where Amazon, Walmart, and Alibaba set structural design and sustainability disclosure requirements that cascade through tiered supply networks.
Paper Boxes Market Segmentation
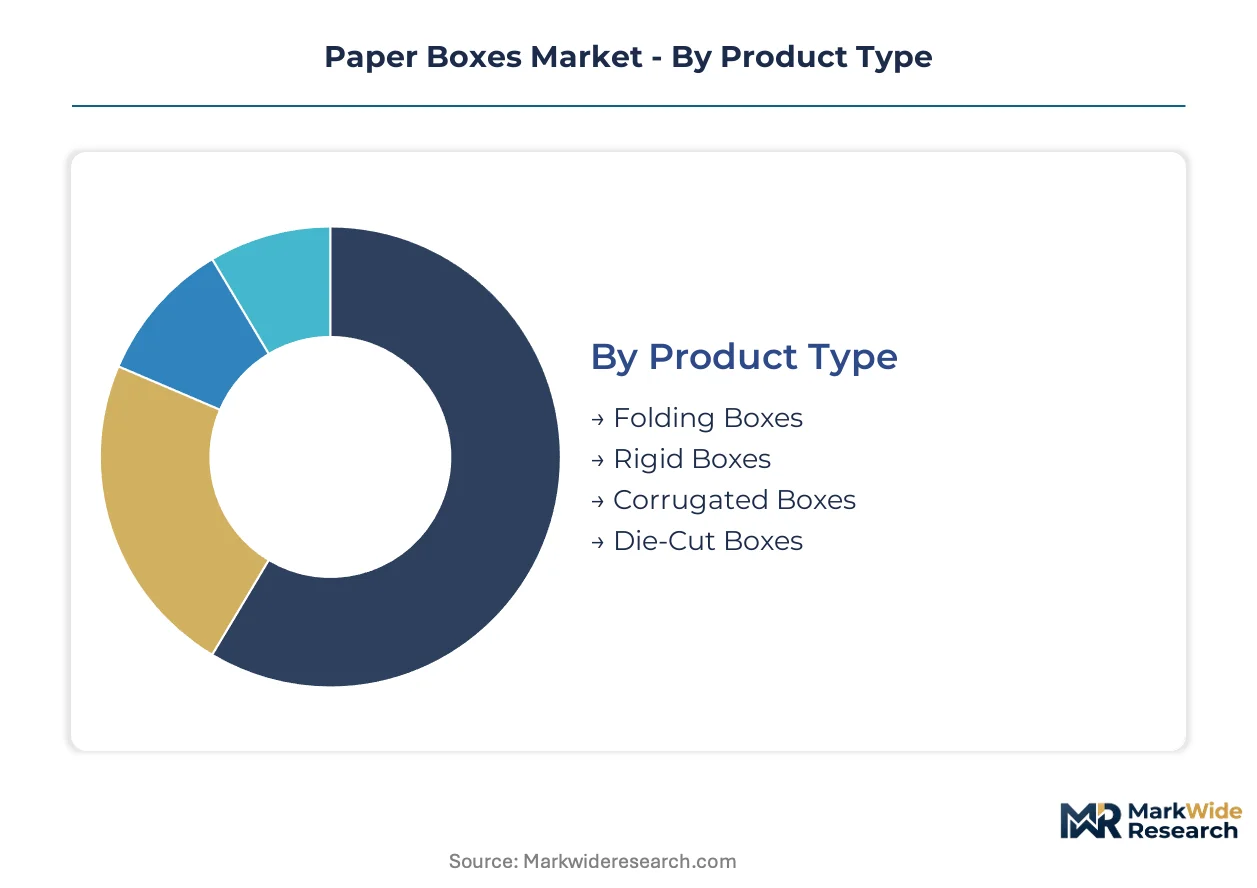
Paper box segmentation reveals divergent margin structures and specification requirements across protective versus presentation applications. Cycle time and inventory velocity vary dramatically between commodity shipping grades and premium rigid formats serving gift and cosmetic markets.
Product Type:
Corrugated formats turn inventory fastest through fulfillment networks, while rigid box production runs extend weeks due to specialty substrate curing and hand-finishing steps.
- Folding Boxes:Manufactured from 200-400 gsm paperboard with crease-and-fold construction, these formats serve high-volume consumer goods where shelf-ready graphics justify unit cost premiums. Demand concentrates in European pharmaceutical blister packs and North American cereal cartons where EU REACH coating compliance and FDA food contact certification create dual regulatory friction.
- Corrugated Boxes:Multi-layer flute constructions ranging from E-flute micro-corrugation to heavy-duty triple-wall profiles dominate tonnage and logistics infrastructure investment. China's coastal export zones pull specifications toward return-loop durability standards as e-commerce fulfillment density reshapes structural integrity benchmarks away from pure cost minimization.
- Rigid Boxes:Thick paperboard laminates over solid chipboard or greyboard cores deliver premium unboxing experiences. Luxury cosmetics and electronics brands in South Korea and Japan specify these for gift sets where surface finish and structural rigidity command margin premiums.
- Die-Cut Boxes:Custom-cut corrugated or paperboard formats with integrated locking tabs and display features. Specialty retail and promotional applications in Germany and the Netherlands drive specification migration toward water-based barrier coatings meeting EU Green Deal circularity commitments.
Corrugated boxes dominate installed base across fulfillment networks. Rigid boxes are where expansion concentrates for margin recovery amid fiber input volatility.
End User:
Cost tier separation runs deepest here, with food service specifications compressing toward commodity pricing while cosmetic applications sustain premium positioning through certification requirements.
- Food & Beverage:Direct-contact folding cartons and corrugated shipping cases face stringent FDA migration testing and EU EFSA contaminant thresholds. Frozen food segments in the United States are accelerating water-based coating adoption as polyethylene laminates face regulatory pressure.
- E-commerce:Unboxing experience requirements and return-loop durability standards in China's manufacturing belts reshape box specifications toward structural integrity benchmarks. Amazon and Alibaba procurement concentration standardizes disclosure requirements that cascade through tiered supplier networks.
- Cosmetics:High-graphics folding cartons and rigid gift boxes command premium positioning through anti-counterfeiting features and surface finish quality. REACH-compliant coating chemistries and third-party chain-of-custody certification maintain pan-European market access.
- Electronics:Anti-static corrugated and precision die-cut inserts protect high-value components through multi-modal distribution. India's tier-two and tier-three organized retail expansion creates demand for shelf-ready packaging specifications previously concentrated in export-oriented manufacturing.
Food and beverage anchors volume throughput across containerboard mills. E-commerce is climbing the fastest as fulfillment density reshapes regional capacity allocation.
Packaging Type:
Structural wall count directly maps to load-bearing requirements and fiber consumption per unit, with printed formats commanding premium positioning through graphics complexity.
- Single Wall:Standard C-flute or B-flute constructions serve lightweight consumer goods and retail-ready display cases. European supermarket private-label penetration standardizes these specifications across pan-regional supplier networks.
- Double Wall:BC-flute combinations deliver stacking strength for warehouse club bulk packs and industrial parts distribution. Germany's third-party logistics providers specify these for palletized automotive component shipments.
- Triple Wall:Heavy-duty AAA or A-flute profiles replace wooden crates in export agricultural and machinery applications. China's GB standards for heavy metals compliance create cross-border friction for recycled fiber-based grades serving multinational brand owners.
- Printed:High-graphics flexo or litho-laminated surfaces enable brand differentiation at point of sale. Skilled die-cutting and creasing technician scarcity in mature manufacturing regions constrains capacity expansion for precision folding carton production.
Single wall dominates unit volume across retail distribution. Printed formats are gaining share fastest as brand owners consolidate procurement around experience-driven specifications.
Distribution Channel:
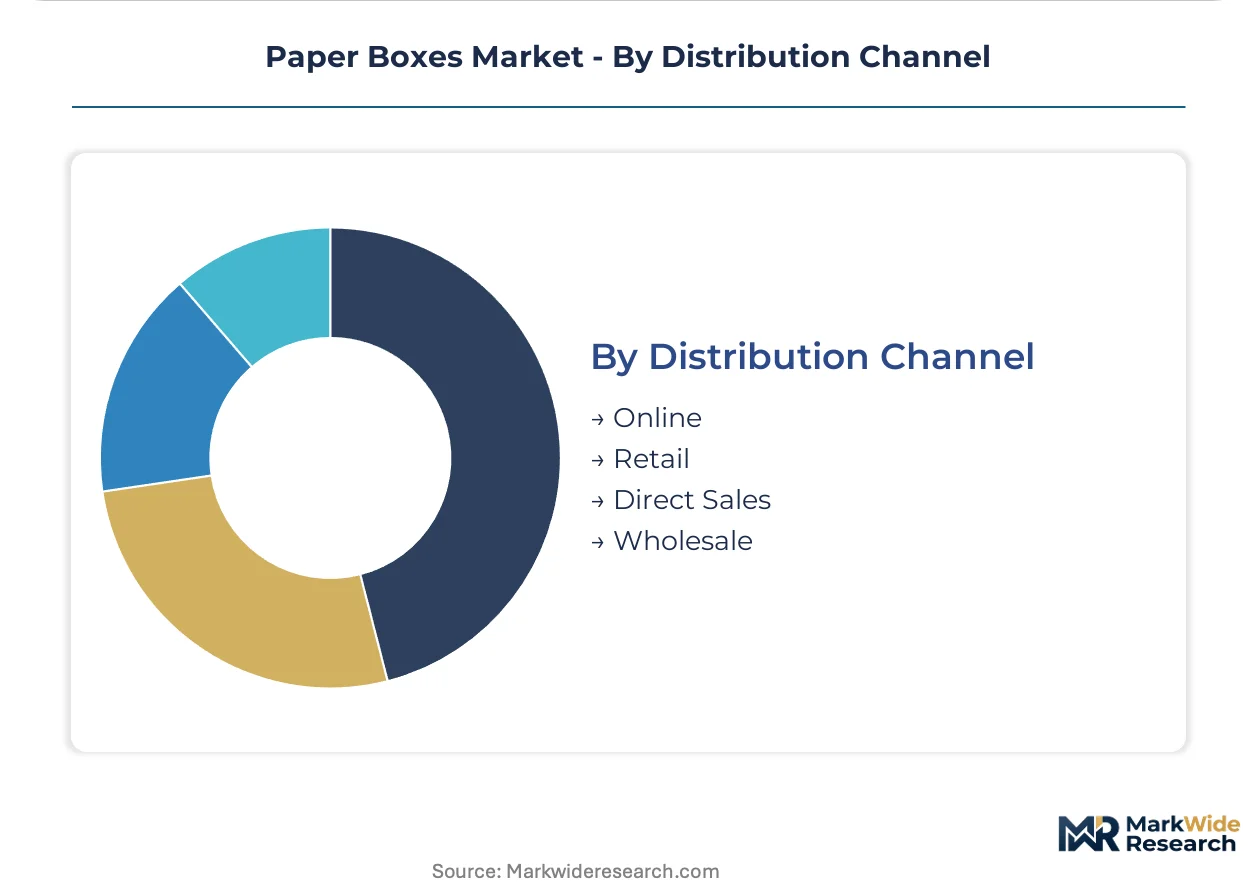
Customer type fragmentation separates spot purchasers from integrated supply contract holders, with channel choice determining specification standardization versus customization flexibility.
- Direct Sales:Converter-to-brand relationships enable collaborative design and just-in-sequence delivery for high-volume consumer goods. Walmart and Target direct procurement models displace traditional distributor intermediaries in North American markets.
- Wholesale:Stock-and-distribute models serve mid-cap manufacturers with standardized box sizes and rapid turnaround. Vietnam and Indonesia's relocated consumer goods manufacturing bases are adding regional folding carton capacity to serve this channel.
- Online:Digital procurement platforms aggregate spot demand from small-batch users and seasonal promotions. India's B2B marketplace penetration creates price transparency that compresses margin for non-differentiated corrugated grades.
- Retail:Big-box and specialty store private-label packaging specifications cascade through co-packer networks. EU Packaging and Packaging Waste Regulation extended producer responsibility mandates redirect investment toward closed-loop fiber recovery systems serving this channel.
Wholesale channels anchor installed base across fragmented manufacturing bases. Direct sales are expanding most quickly as buyer concentration compresses supplier negotiation leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for packaging heavy metals anchor the dominant geography, with MEE enforcement of carbon intensity benchmarks redirecting procurement toward suppliers with verified fiber traceability. The EU Packaging and Packaging Waste Regulation tightens material recovery targets across corrugated networks. India's organized retail expansion in tier-two cities pulls folding carton specifications toward high-graphics shelf-ready formats.
United States
FDA food contact regulations govern recycled fiber migration testing in direct-contact folding cartons, compressing development timelines for sustainable packaging innovations. E-commerce fulfillment density across the Southeast and Texas logistics corridors reshapes containerboard specifications toward return-loop durability. The Pacific Northwest pulp-to-box networks sustain cost discipline through integrated fiber supply.
Germany
EU REACH compliance for recycled fiber contaminants tightens coating chemistry restrictions across paperboard surface treatments. Third-party logistics providers in the Ruhr industrial belt specify double-wall BC-flute constructions for palletized automotive component shipments. Water-based barrier coating adoption accelerates in the Netherlands-adjacent logistics zones to meet EU Green Deal circularity commitments.
China
Dual carbon goals enforcement creates preferential procurement channels for box suppliers with renewable energy certificates and Scope 3 traceability. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate containerboard consumption as coastal export zones pull specifications toward structural integrity benchmarks. GB standards for heavy metals compliance create cross-border friction for recycled fiber grades serving multinational brand owners.
India
FSSAI food contact standards intersect with BIS packaging norms to shape material sourcing for domestic and export-oriented production. Modern trade penetration in Maharashtra and Gujarat tier-two cities generates demand for shelf-ready folding carton specifications previously concentrated in export manufacturing. B2B marketplace penetration creates price transparency that compresses margins for non-differentiated corrugated grades.
Vietnam
Relocated consumer goods manufacturing from higher-cost production bases drives containerboard and folding carton capacity additions across the northern industrial provinces. DGFT export facilitation frameworks support packaging material integration into regional supply chains. The Red River Delta corridor concentrates new capacity to serve wholesale distribution channels for mid-cap manufacturers.
Paper Boxes Market Competitive Landscape
Capability concentration sits with specialty coated and high-graphics producers; scale advantage sits with integrated pulp-to-box networks. The market structures around three tiers: multinational integrated producers with captive fiber supply, regional converters serving wholesale distribution, and specialty fabricators focused on premium rigid and printed formats. Dominant competitive moves include backward integration into recycled fiber recovery systems and geographic expansion through regional folding carton capacity additions.
Among North American integrated producers, International Paper exemplifies scale-driven positioning through mill network coverage, while WestRock occupies a position in specialty coated packaging for branded consumer products. Smurfit Kappa anchors European supply through recycled fiber dominance and pan-regional plant coverage, representing the regional converter archetype with extended producer responsibility compliance integration.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Kappa Group |
| WestRock |
| Mondi Group |
| DS Smith |
| Rengo Co., Ltd. |
| Nine Dragons Paper (Holdings) Limited |
| Georgia-Pacific |
| Graphic Packaging International |
| Others |
Value Network & Pricing Analysis
Containerboard overcapacity in China's coastal provinces compresses mill operating rates below break-even thresholds, forcing suppliers toward long-term offtake contracts and degrading spot-market pricing power across Asia-Pacific export corridors.
Pricing Analysis
Geographic price spreads between European REACH-compliant grades and Southeast Asian export specifications exceed transport cost differentials, reflecting regulatory compliance premiums. Pricing stratifies across premium, standard, and economy tiers based on fiber traceability certification and volume commitment scale. Cost compression in commodity corrugated runs through recycled fiber input volatility as old corrugated container availability fluctuates with retail inventory cycles. Food service buyers exhibit highest price sensitivity due to thin margin structures, while cosmetics brands accept premium positioning for anti-counterfeiting features.
Supply Chain Analysis
Old corrugated container availability draws from residential collection networks in North America, European retail return systems, and China's domestic recovery infrastructure. Recycled fiber dependency centers on post-consumer furnish quality, water-based barrier coating chemistry migration, and renewable energy certificate verification. Single-source vulnerability concentrates in China's Yangtze River Delta manufacturing belt where dual carbon goals enforcement redirects procurement toward verified Scope 3 traceability. Distribution runs through converter-to-brand direct sales relationships displacing traditional wholesale intermediaries in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper boxes market faces high-growth disruption as EU Packaging and Packaging Waste Regulation mandates reshape capital allocation toward closed-loop fiber recovery systems and recycled content thresholds.
For Market Incumbents: Build regulatory compliance moats through backward integration into certified fiber recovery networks serving pan-European brand owners. Invest in water-based barrier coating capacity to capture frozen food segment migration from polyethylene laminates. Anchor position against plastic substitution threats in moisture-barrier applications through compostable certification pipelines. For New Entrants and Emerging Players: Establish a beachhead in India's tier-two and tier-three organized retail expansion where shelf-ready folding carton specifications outpace domestic supply capacity. Target high-graphics die-cut formats for electronics unboxing experiences in Vietnam's relocated manufacturing corridors. Pursue co-packer relationships with mid-cap consumer goods brands seeking rapid turnaround outside integrated mill networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty rigid box fabricators serving cosmetics and pharmaceutical anti-counterfeiting applications with multi-year brand contracts. Long-term viability favors acquisition targets with verified Scope 3 fiber traceability and renewable energy certificates aligned with China's MEE enforcement trajectories. Monitor EU Green Deal circularity commitment acceleration as inflection signal for water-based coating chemistry substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Captures closed-loop economics under EU extended producer responsibility mandates. |
| Water-Based Barrier Coating Scale-Up | Positions suppliers for Netherlands and Germany retailer specifications under EU Green Deal. |
| Geographic Expansion in Vietnam | Serves relocated consumer goods manufacturing from higher-cost production bases. |
| Smart Packaging Convergence | Opens premium-margin rigid box applications in South Korean cosmetics anti-counterfeiting. |
| Direct Procurement Relationship Building | Displaces distributor intermediaries as Amazon and Alibaba concentrate buyer leverage. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with containerboard mill managers, folding carton procurement leads at consumer goods brands, third-party logistics specification officers, and water-based coating R&D directors; and secondary validation through customs trade data, FEFCO industry statistics, EPA fiber recovery reports, and SEC 10-K filings from integrated producers. Bottom-up capacity utilization modeling triangulated against top-down demand segmentation across product type, end user, and regional regulatory clusters.
Forecast inputs considered e-commerce fulfillment density trajectories in China's coastal export zones, EU Packaging and Packaging Waste Regulation enforcement timelines, and India's organized retail penetration rates across tier-two cities. Segmentation dimensions modeled include corrugated versus rigid versus folding box construction, food and beverage versus cosmetics versus electronics end-use applications, and single versus double versus triple wall structural profiles. CAGRs derived from fiber input cost elasticity analysis and buyer concentration-driven specification standardization trends.
Macroeconomic conditions sit as an overlay; deviation in pulp futures pricing, ocean freight rate volatility, or residential recycling participation rates would shift the trajectory. Cross-checking against FEFCO containerboard consumption statistics and RISI price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market