
 Molded Fiber Pulp Cap Market | 2026-2036
Molded Fiber Pulp Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Pulp Cap Market Foresight
Modular lid-and-cup bundling is restructuring how food service buyers evaluate total packaging cost. Huhtamaki leverages its thermoforming heritage to offer integrated cup-lid systems that reduce leakage failure rates. Brødrene Hartmann anchors European supply through its molded fiber network serving dairy and egg packaging. PulPac differentiates through its dry-molded fiber technology, eliminating water-intensive production steps that burden conventional pulp molding.
Molded fiber pulp caps are engineered from cellulose fibers—typically bamboo, recycled paper, sugarcane bagasse, or wood pulp—pressed into dimensionally stable closures that seal liquid and solid contents across temperature ranges. Wall thickness, fiber blend ratio, and hydrophobic coating density determine barrier performance against moisture and grease. The Lids segment leads volume as beverage chains standardize fiber replacements for plastic flat and dome lids. Sugarcane pulp occupies the fastest-expanding material niche, capitalizing on agricultural waste streams in tropical processing regions. Food Service dominates end-user demand, though Retail channels are deepening stock-keeping unit counts as supermarkets introduce private-label prepared meals.
The EU Green Deal and F-Gas Regulation indirectly shape fiber cap demand by tightening rules on plastic incineration and fluorinated barrier coatings. FDA food-contact substance notifications and California's SB 54 extended producer responsibility law compel U.S. brands to document fiber sourcing and recyclability pathways. Stakeholders must monitor how Germany's Packaging Act amendments and India's Plastic Waste Management Rules calibrate enforcement timelines, as these will determine where capacity investments convert to purchase orders first.
Market Dynamics
Quick-service restaurant chains are consolidating purchasing around integrated cup-lid systems, compressing supplier margins while favoring converters with thermoforming and fiber molding capabilities under one roof. This bundling dynamic is restructuring competitive positioning across the molded fiber pulp cap value chain.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates fiber alternatives for beverage lids across member states, forcing procurement switches at major food service operators in Germany and France.
- Sugarcane bagasse processing expansion:Tropical agricultural waste streams in Brazil and India are scaling pulp supply for moisture-resistant cap formulations.
- Quick-service restaurant standardization:Chains are specifying fiber lids across franchise networks, creating volume pull that justifies dedicated production lines.
Market Restraints
- Hydrophobic coating cost volatility:PFAS-free barrier chemistry inputs fluctuate with specialty chemical feedstock markets, squeezing converter margins.
- German packaging converter concentration:Central European supply clusters create single-point vulnerability for brands sourcing across the EU.
- Performance gap in hot-fill applications:Fiber caps degrade above 85°C, limiting penetration into soup and hot beverage segments where polypropylene retains dominance.
Strategic Opportunities
- India Plastic Waste Management Rules:State-level enforcement timelines are opening procurement windows for fiber lid imports and local production partnerships.
- Retail private-label prepared meals:Supermarket chains are expanding fiber-capped SKUs in chilled ready-meal sections, creating channel diversification beyond food service.
- Dry-molded fiber convergence with barrier coating:Waterless production paired with spray-applied hydrophobic layers cuts capital intensity and water treatment costs.
Industry Challenges
- Compostability certification timelines:TÜV and BPI validation cycles for industrial and home composting claims extend 12-18 months, delaying product launches.
- Thermoforming-to-fiber line conversion capex:Legacy plastic lid equipment requires substantial retooling investment for fiber pulp compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Pulp Cap Market |
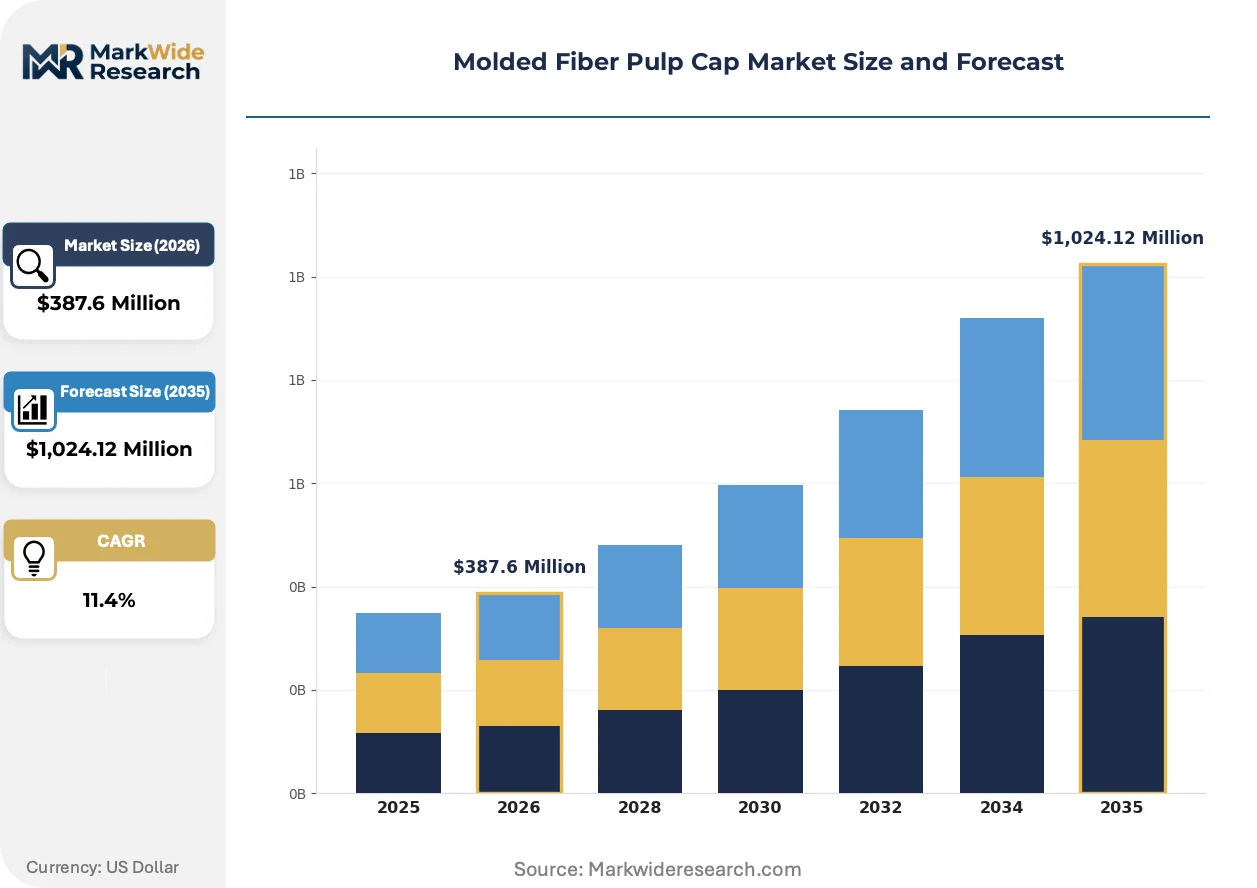
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cups, Trays, Containers, Lids End User: Food Service, Retail, Packaging, Consumer Goods Material: Bamboo Fiber, Recycled Paper, Sugarcane Pulp, Wood Fiber Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki, UFP Technologies, Brødrene Hartmann, Sabert Corporation, PulPac, Stora Enso, Genpak, Henry Molded Products, Omni-Pac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Pulp Cap Market Shifts & Advancements
Barrier coating chemistry and production water intensity are the primary vectors of technical differentiation, with dry-molded processes and PFAS-free formulations commanding premium positioning.
Dry-molded fiber technology eliminates the slurry and vacuum-forming steps that consume 15-20 liters of water per kilogram of finished pulp product. Quick-service chains in Northern Europe are qualifying these caps for cold beverage applications where leakage tolerance is tight. The process is expanding into dairy and prepared food segments previously blocked by moisture sensitivity concerns.
California's SB 54 extended producer responsibility law requires brands to document fiber sourcing and fund end-of-life collection infrastructure. Food service operators serving the California market are demanding chain-of-custody certification from lid suppliers, compressing the compliant supplier base. Dairy brands with California distribution are accelerating fiber cap adoption to meet 2032 recycling rate targets.
Chain-level sustainability scorecards now weight packaging recyclability in supplier selection criteria. Procurement teams at major quick-service operators are unbundling lid purchasing from cup contracts to evaluate total system cost including leakage failure and customer complaint rates. This behavior is most visible in Germany, where packaging converters compete on integrated system performance rather than unit price alone.
Molded Fiber Pulp Cap Market Segmentation
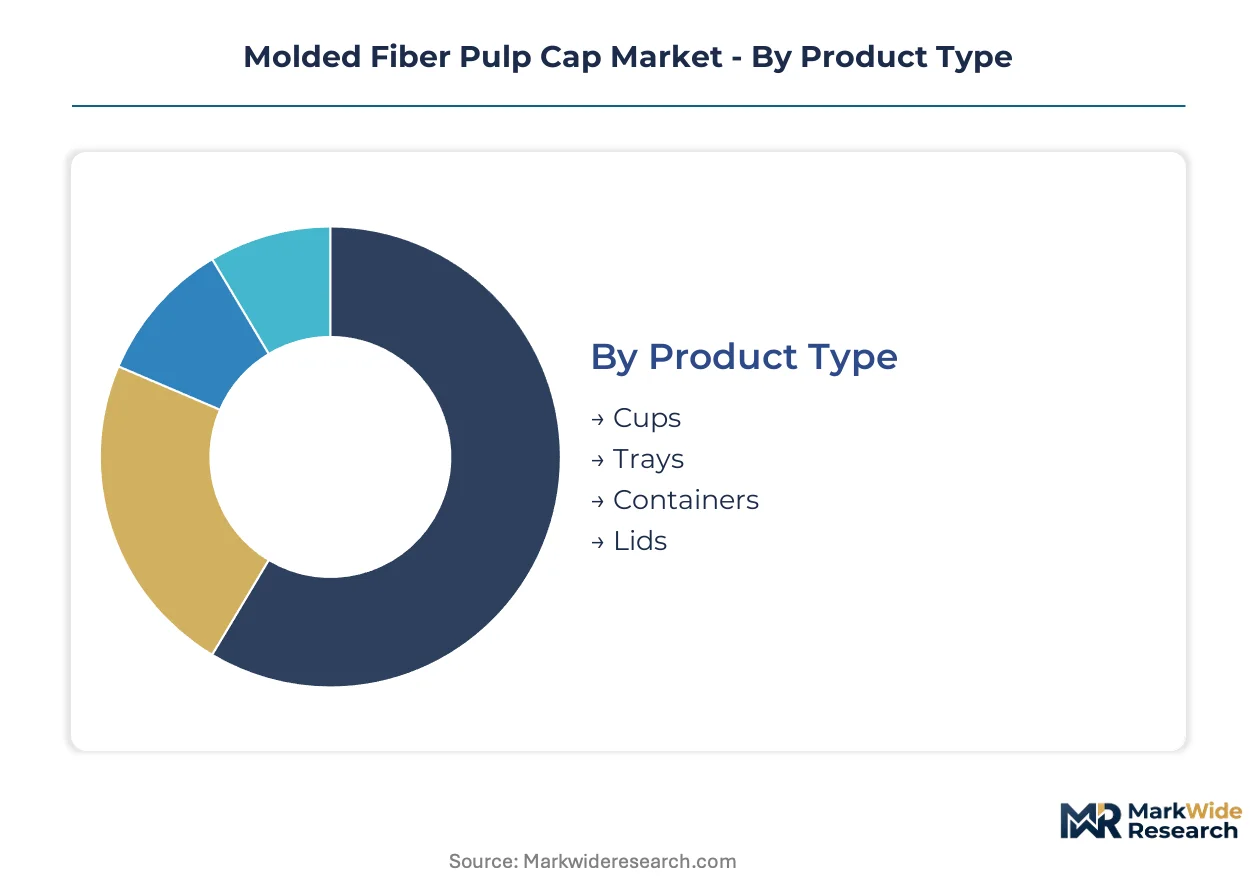
Molded fiber pulp caps serve distinct functional roles across beverage sealing, food containment, and retail presentation. Segmentation reveals where material specifications, distribution economics, and end-use performance requirements create divergent competitive arenas.
Product Type:
Integration depth varies sharply: lids function as standalone replacement components compatible with existing cup inventories, while cups, trays, and containers demand coordinated system redesigns across food service operations.
- Lids:Pressed cellulose closures with calibrated rim diameters seal cold beverages across quick-service restaurant networks. Beverage chains in Germany and France are standardizing fiber lids to comply with EU Single-Use Plastics Directive mandates, creating concentrated procurement pull.
- Cups:Tapered sidewall constructions with integrated rim profiles require matched lid geometries. Dairy brands across Central Europe are adopting fiber cup-lid bundles for chilled products, leveraging Hartmann's thermoforming-to-fiber production lines.
- Trays:Shallow-formed pulp structures with compartmentalized cavities serve prepared meal presentation. Retail supermarkets in California are expanding tray SKUs for private-label chilled meals under SB 54 extended producer responsibility requirements.
- Containers:Deep-drawn fiber vessels with flange-sealing rims target solid and semi-liquid food containment. Sugarcane pulp formulations from Brazilian processing streams are penetrating this segment for moisture resistance.
Volume placements concentrate in Lids; the faster expansion belongs to Containers as retail prepared meal formats proliferate.
End User:
Cost tier stratification separates high-volume contract food service from fragmented retail procurement, with packaging intermediaries and consumer goods brands occupying distinct margin bands.
- Food Service:Quick-service restaurant chains and institutional caterers specify fiber caps through centralized procurement. Chains are unbundling lid purchasing from cup contracts to evaluate total system cost including leakage failure rates.
- Retail:Supermarket private-label programs and specialty food stores stock fiber-capped products for consumer takeaway. California's SB 54 recycling rate targets are accelerating fiber adoption among dairy brands with state distribution.
- Packaging:Contract converters and co-packers supply fiber caps as components to brand owners. German packaging converters dominate Central European supply, creating single-point vulnerability for EU-wide sourcing.
- Consumer Goods:Household product brands utilize fiber caps for dry goods and personal care items. This segment trails food applications due to lower regulatory pressure and performance requirements.
Food Service commands absolute volume; Retail channels are climbing fastest as chilled ready-meal sections expand fiber-capped SKU counts.
Material:
Application requirements dictate fiber blend selection, with agricultural waste streams and recycled content pathways offering divergent sustainability credentials and barrier performance profiles.
- Sugarcane Pulp:Bagasse fibers from tropical sugar processing yield high-lignin pulp with natural moisture resistance. Brazilian and Indian agricultural waste streams are scaling supply for cap formulations targeting tropical and subtropical markets.
- Bamboo Fiber:Rapid-growth grass cellulose provides tensile strength for thin-wall lid constructions. Asian bamboo processing clusters are supplying fiber for premium positioning in Northern European quick-service chains.
- Recycled Paper:Post-consumer fiber streams offer established collection infrastructure and cost positioning. FDA food-contact substance notifications govern recycled content limits in U.S. food service applications.
- Wood Fiber:Virgin and sustainably certified softwood pulps deliver consistent fiber length for dimensional stability. Nordic forestry certification schemes support chain-of-custody documentation for EU Green Deal compliance.
Sugarcane Pulp holds the steepest expansion trajectory; Recycled Paper maintains the broadest installed base across existing production capacity.
Distribution Channel:
Customer type and order scale determine channel selection, with direct relationships dominating large food service accounts and wholesale intermediaries serving fragmented retail demand.
- Direct Sales:Converter-to-brand relationships for high-volume food service and packaging accounts. Quick-service restaurant chains are consolidating purchasing around integrated cup-lid systems through direct negotiation.
- Wholesale:Distributor networks aggregate demand from regional food service operators and smaller retail chains. German wholesale channels serve Central European packaging converters with fiber pulp raw materials and finished caps.
- Supermarkets:Retailer-controlled supply chains for private-label and branded fiber-capped products. California supermarket chains are demanding chain-of-custody certification from lid suppliers under extended producer responsibility frameworks.
- Online Retail:E-commerce platforms for specialty and small-batch fiber cap procurement. This channel remains marginal for volume but serves niche sustainability-focused brands and startup food companies.
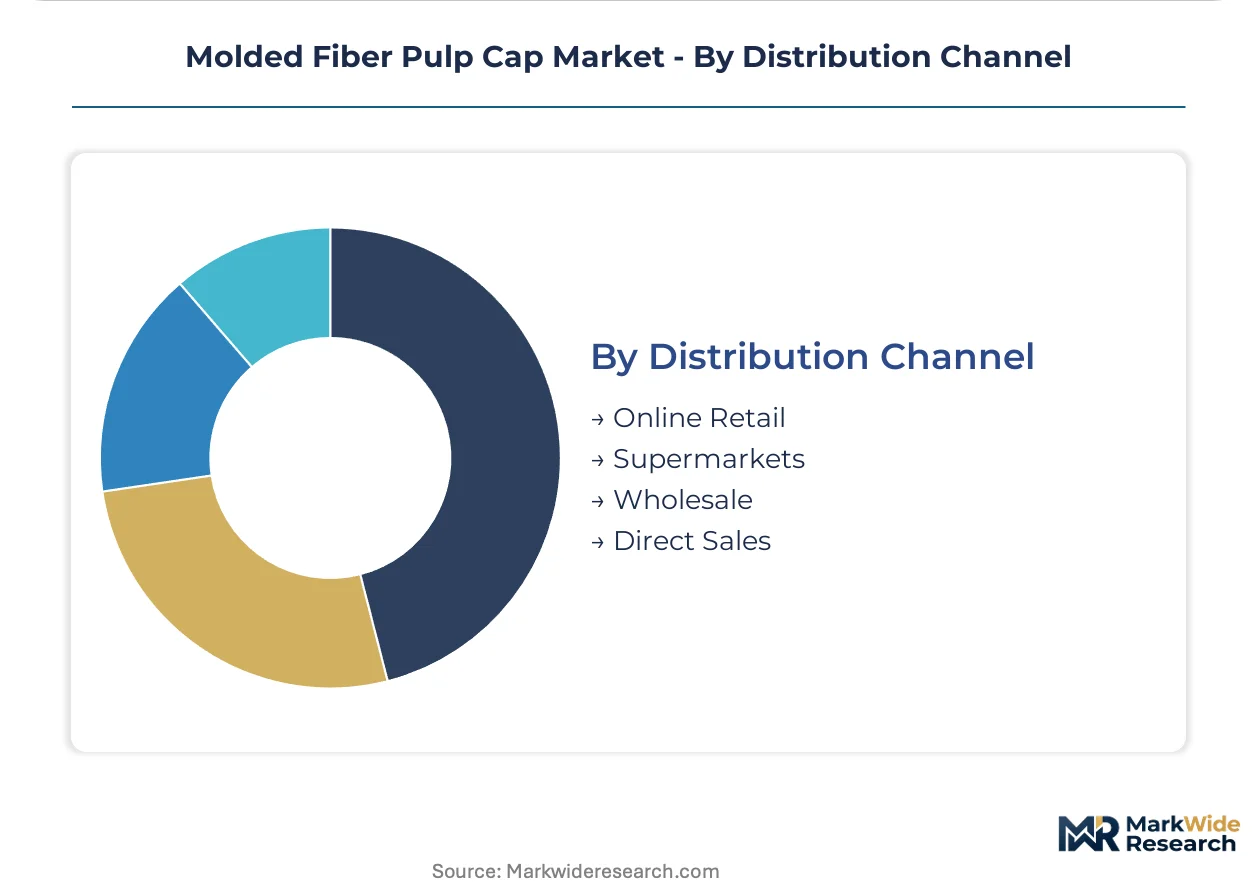
Direct Sales capture the largest contract values; Wholesale channels are gaining share fastest as mid-tier food service operators consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for food processing have attracted molded fiber converters seeking duty-free raw material imports and streamlined customs clearance for export-bound production.
Germany
Packaging converters in Baden-Württemberg and North Rhine-Westphalia supply Central European beverage brands with fiber lids certified under the EU Green Deal. The Packaging Act amendments tighten extended producer responsibility timelines. Stuttgart-area thermoforming specialists are retrofitting lines for pulp compatibility to serve quick-service restaurant procurement clusters.
United States
California's SB 54 mandates 30% recycled content in food packaging by 2032, forcing dairy and beverage brands to document fiber sourcing chain-of-custody. FDA food-contact substance notifications govern recycled paper limits in lid formulations. Los Angeles and San Francisco Bay Area co-packers are consolidating supplier relationships around compliant fiber cap vendors.
India
Maharashtra and Gujarat house sugarcane bagasse processing streams feeding moisture-resistant pulp formulations for tropical markets. The Plastic Waste Management Rules ban select single-use plastics at state-level enforcement timelines. Mumbai-Pune industrial corridors host emerging joint ventures between European converters and local packaging manufacturers.
Brazil
São Paulo state sugar-ethanol complexes generate bagasse waste streams scaling pulp supply for export-oriented cap production. The national bioeconomy framework incentivizes agricultural residue valorization. Campinas and Ribeirão Preto processing clusters are qualifying fiber formulations for dairy and chilled beverage applications.
France
Île-de-France quick-service restaurant headquarters drive procurement standardization across franchise networks subject to EU Single-Use Plastics Directive compliance. ECHA restrictions on fluorinated compounds accelerate PFAS-free barrier coating adoption. Lyon-area packaging research centers are validating industrial compostability certifications for fiber lid exports.
Molded Fiber Pulp Cap Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the molded fiber pulp cap value chain. The supplier base fragments between integrated packaging groups with thermoforming heritage and emerging dry-molded fiber technology developers. Three archetypes dominate: conglomerates with multi-material capabilities, regional converters with agricultural waste supply contracts, and technology licensors specializing in waterless production processes. Capacity expansion and strategic technology licensing represent the primary competitive vectors as procurement consolidates around integrated cup-lid systems.
Among Nordic forestry-integrated groups, Huhtamaki and Stora Enso exemplify conglomerate archetypes with backward control over virgin fiber supply chains. Brødrene Hartmann anchors the regional converter tier through its molded fiber network serving Central European dairy and egg packaging demand. PulPac occupies the technology licensor position, representing dry-molded fiber process developers eliminating water-intensive production steps that burden conventional pulp molding operations.
| Leading Market Players |
|---|
| Huhtamaki |
| UFP Technologies |
| Brødrene Hartmann |
| Sabert Corporation |
| PulPac |
| Stora Enso |
| Genpak |
| Henry Molded Products |
| Omni-Pac |
| Others |
Supply & Pricing Matrix
Quick-service restaurant chains with centralized procurement functions dictate contract structures across the molded fiber pulp cap market, compressing supplier margins through volume bundling while rewarding converters with integrated thermoforming and fiber molding capabilities. This buyer concentration shifts pricing power toward food service operators capable of standardizing lid specifications across franchise networks.
Pricing Analysis
Short lead-time premiums separate urgent procurement from scheduled contract volumes, with German packaging converters commanding price advantages for EU Single-Use Plastics Directive-compliant lids delivered within compressed windows. Three-tier pricing structure across premium, standard, and economy levels reflects barrier coating chemistry, compostability certification tier, and volume scale commitments. Pricing pressure stems from PFAS-free chemistry input volatility squeezing converter margins. Mid-tier food service operators exhibit highest price sensitivity, while premium quick-service chains prioritize leakage performance over unit cost.
Supply Chain Analysis
California's SB 54 recycled content mandates and India's Plastic Waste Management Rules are reshaping sourcing patterns, compelling brands to document fiber provenance and localize production partnerships. Supply concentrates in Germany, Brazil, and India, with bagasse processing streams in São Paulo state and Maharashtra feeding moisture-resistant pulp formulations. Raw material dependencies center on sugarcane bagasse, bamboo fiber, and specialty hydrophobic coatings. Single-source vulnerability runs through German converter clusters serving Central European demand. Distribution runs through direct converter-to-brand relationships for high-volume accounts, with wholesale intermediaries aggregating fragmented retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded fiber pulp cap market is becoming a vertical-integration race, with players pursuing backward control over bagasse supply streams and thermoforming equipment retrofit capabilities to capture margin and secure capacity.
For Market Incumbents: Extend barrier coating R&D partnerships to lock in PFAS-free chemistry supply before regulatory deadlines tighten, and retrofit legacy thermoforming lines in Baden-Württemberg to pulp compatibility to defend against dry-molded fiber technology licensors. Dry-molded fiber process developers threaten incumbent water-intensive production economics. Capacity addition in São Paulo state sugar-ethanol corridors anchors bagasse supply security. For New Entrants and Emerging Players: E-commerce platforms for specialty fiber cap procurement offer the lowest customer acquisition cost route to initial revenue, bypassing entrenched direct sales relationships controlling quick-service procurement. Retail private-label prepared meals in California represent the most penetrable white-space segment, with supermarket chains demanding chain-of-custody certification that compliant entrants can deliver. A sustainability scorecard-focused go-to-market angle resonates with procurement teams unbundling lid purchasing from cup contracts. For Investors and Strategic Acquirers: The window for entry favors technology licensors with waterless production processes and regional converters holding agricultural waste supply contracts in tropical processing regions. Long-term viability hinges on securing compostability certification capabilities and barrier coating chemistry partnerships before industrial validation cycles extend product launch timelines. Acquisition target archetype: dry-molded fiber technology developers with spray-applied hydrophobic layer IP. The signal to watch is TÜV and BPI certification backlog length as an inflection indicator for compliant supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Supply | São Paulo state sugar-ethanol complexes secure agricultural waste streams for moisture-resistant pulp formulations. |
| Thermoforming Line Retrofit for Pulp Compatibility | Stuttgart-area specialists capture quick-service procurement clusters demanding integrated cup-lid systems. |
| PFAS-Free Barrier Coating Partnership | ECHA restrictions on fluorinated compounds accelerate compliant chemistry supply agreements with European converters. |
| Industrial Compostability Certification Investment | TÜV validation cycles for fiber lids unlock premium positioning in German and French quick-service networks. |
| Joint Venture in Maharashtra-Gujarat Corridor | Mumbai-Pune industrial partnerships localize production for India's Plastic Waste Management Rules enforcement windows. |
Research Methodology
Independent corroboration across converter production data, EU regulatory filings, and agricultural commodity trade records underwrites the qualitative findings in this study. Primary interviews with food service procurement directors, packaging converter operations managers, barrier coating chemistry suppliers, and sustainability certification auditors combined with secondary validation from FDA food-contact substance notifications, EU Green Deal implementation documents, and state-level plastic waste regulations. Bottom-up capacity assessments across German, Brazilian, and Indian production clusters triangulate with top-down demand modeling from quick-service restaurant chain standardization announcements.
Rate-of-change decomposition across material substitution velocity, regulatory compliance timeline acceleration, and end-user procurement pattern shifts structures the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type integration depth, end-user cost tier stratification, material fiber blend selection, and distribution channel customer scale. CAGRs derive from volume trajectory analysis calibrated to EU Single-Use Plastics Directive enforcement phases and California SB 54 recycled content milestones. Industry-specific forecast inputs incorporate sugarcane bagasse processing capacity expansion in tropical regions and PFAS-free coating chemistry commercialization timelines.
Inputs from converter production disclosures and regulatory agency guidance documents were available through the study window; gaps in real-time procurement contract terms and proprietary barrier coating formulations introduce uncertainty bands around volume assumptions. Forecasts reflect documented enforcement timelines and announced capacity investments, with revision risk hinging on Germany's Packaging Act amendment calibrations and India's state-level plastic ban enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Tube Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market