
 Litho Laminated Cartons Market | 2026-2036
Litho Laminated Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Litho Laminated Cartons Market Foresight
Asset-light leasing models for high-speed folder-gluer lines is reconfiguring competitive entry barriers for mid-sized converters. WestRock Company leverages its captive paperboard supply to sustain margin control across integrated operations. Smurfit Kappa Group anchors European litho laminated capacity through regional sheet plants and local design services. Graphic Packaging International specializes in beverage multi-packs, competing on speed-to-shelf for carbonated soft drink and beer brands.
Litho laminated cartons consist of printed lithographic paper laminated to corrugated or solid fiberboard substrates, typically achieving four- to six-color process reproduction with aqueous or UV coatings for moisture resistance and scuff protection; these structures serve primarily as shelf-ready retail packaging where brand graphics, structural integrity, and supply chain efficiency converge. Double wall configurations command premium positioning in electronics and fragile goods segments where stacking strength requirements exceed single wall performance. Display formats within the packaging format dimension represent the fastest-growing application as retailers reduce labor costs through pre-merchandised floor-ready units. Lithography retains dominance in high-volume food and beverage runs where color consistency and fine-line reproduction justify longer makeready cycles.
The US EPA and OSHA frameworks govern emissions from adhesive lamination and coating operations, while FDA regulations specify substrate and ink compliance for direct food contact applications. The EU F-Gas Regulation and REACH chemical restrictions increasingly shape adhesive formulation choices and lamination chemistry across export-oriented converters. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in water-based adhesive systems or solvent recovery infrastructure before compliance deadlines tighten.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing converter decision timelines around water-based adhesive transitions and extended producer responsibility compliance investments.
Growth Catalysts
- Shelf-Ready Packaging Mandates:German retailers are requiring floor-ready display units that reduce in-store labor costs, pulling litho laminated carton procurement from food and beverage brands into centralized European supply chains.
- REACH Chemical Restrictions:ECHA oversight of lamination adhesives and UV coating chemistries is accelerating formulation shifts toward compliant water-based systems that maintain bond integrity.
- High-Speed Folder-Gluer Leasing:Asset-light equipment models are lowering entry barriers for mid-sized converters seeking four- to six-color process reproduction capability without full capital commitment.
Market Restraints
- Paperboard Input Concentration:Captive supply control by integrated majors limits spot market availability and squeezes margin flexibility for independent converters in North American and European markets.
- Recyclability Chemistry Friction:Aqueous coating systems required by EU circularity mandates can compromise moisture resistance performance in beverage multi-pack applications.
- Flexible Plastic Substitution:Shrink-wrapped collation formats retain cost advantages in high-volume carbonated soft drink distribution where shelf aesthetics matter less than logistics efficiency.
Strategic Opportunities
- Electronics Double-Wall Penetration:Fragile goods segments in Germany and France present underexploited demand for stacking-strength configurations that single-wall alternatives cannot satisfy.
- UV LED Curing Convergence:Combination of energy-efficient curing technology with aqueous coating platforms enables compliance with EU F-Gas Regulation while maintaining production speeds.
- Design-to-Shelf Services:Local design capabilities bundled with regional sheet plant networks offer converters a service layer that distant competitors cannot replicate.
Industry Challenges
- Adhesive Formulation Expertise Gap:Water-based lamination chemistry requires rheology and substrate compatibility knowledge that legacy solvent-system technicians must rapidly acquire.
- Coordinated Compliance Timelines:EPA emissions frameworks and FDA food contact specifications operate on divergent review cycles, forcing dual-track regulatory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Litho Laminated Cartons Market |
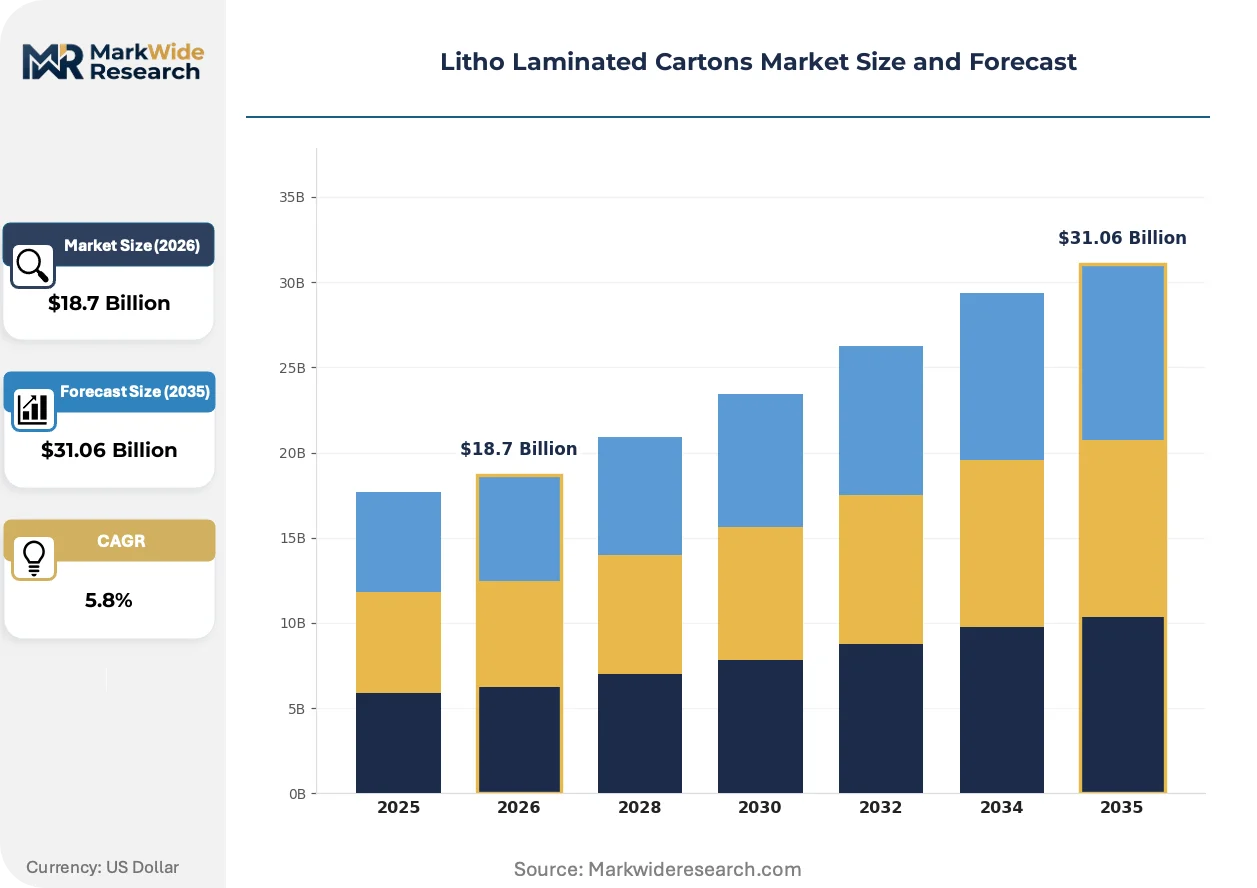
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Corrugated, Rigid End Use Industry: Food & Beverage, Personal Care, Electronics, Pharmaceuticals Packaging Format: Box, Sleeve, Tray, Display Printing Technology: Flexographic, Lithography, Gravure, Digital |
| Companies Covered | International Paper Company, Smurfit Kappa Group, Graphic Packaging International, Mayr-Melnhof Karton AG, Parksons Packaging Ltd., WestRock Company, Packaging Corporation of America, DS Smith Plc, Grief, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Litho Laminated Cartons Market Shifts & Advancements
Digital workflow integration and regulatory chemistry evolution are compressing traditional makeready-to-delivery cycles while reshaping converter capability requirements.
Extended color gamut ink systems paired with closed-loop spectrophotometry are digitizing prepress proofing and on-press color matching for litho laminated production. Beverage multi-pack converters in Germany and the Netherlands are adopting these platforms to reduce makeready waste and accelerate speed-to-shelf for seasonal promotional runs. The technology is digitizing quality control handoffs between brand design studios and folding carton production floors.
The EU F-Gas Regulation is restricting hydrofluorocarbon use in industrial processes including adhesive lamination and coating curing operations. Converters face capital allocation decisions between solvent recovery infrastructure and water-based system conversions before phase-down deadlines tighten. German sheet plants with integrated beverage packaging lines are most exposed due to high-volume coating throughput requirements.
CPG procurement teams are consolidating carton specification decisions at regional headquarters rather than national operating units. This centralization compresses supplier qualification timelines and elevates design-to-delivery capability as a selection criterion over unit cost alone. The shift is most visible in Central European retail supply chains where German folding carton converters compete on integrated service breadth.
Litho Laminated Cartons Market Segmentation
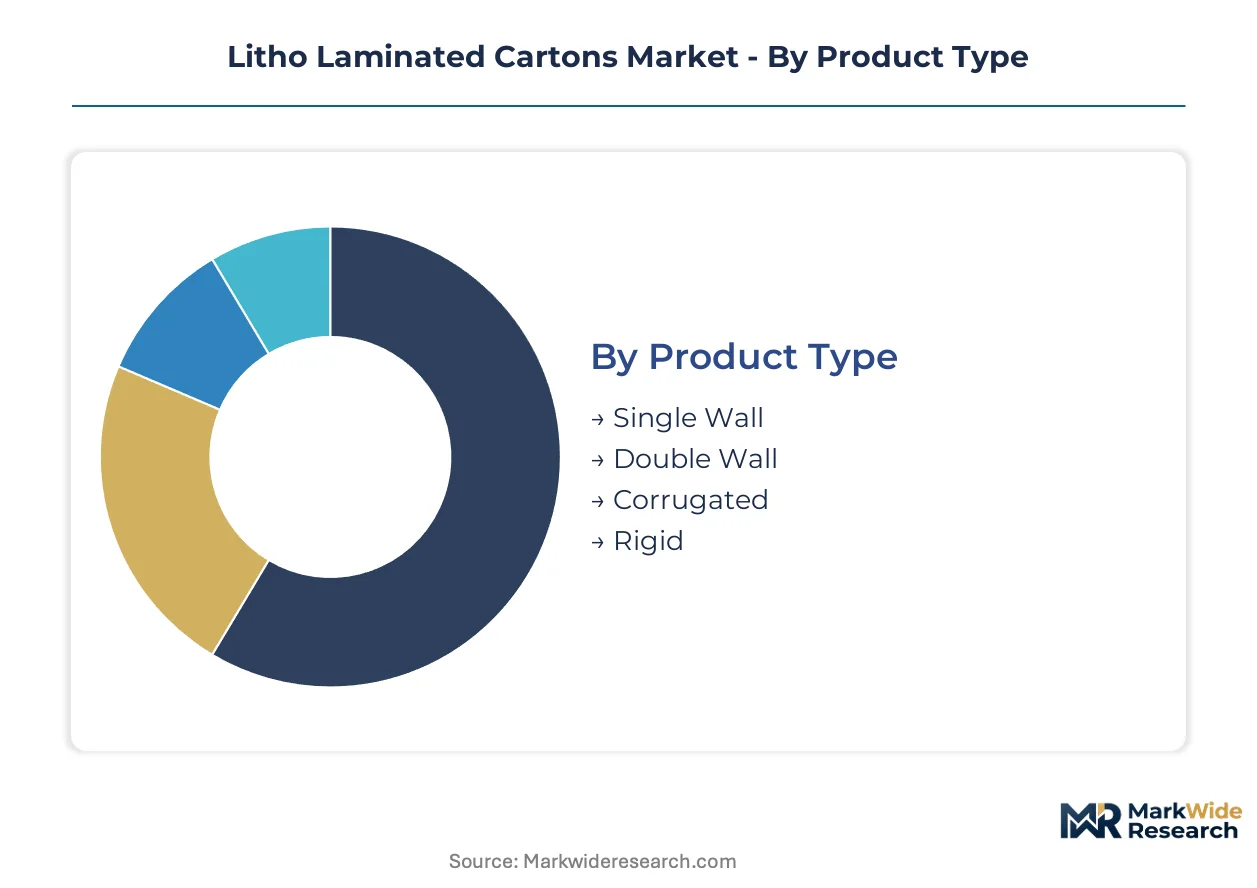
Structural configuration and substrate layering determine stacking performance, moisture resistance, and print reproduction fidelity across litho laminated carton specifications. Procurement teams segment demand by load-bearing requirements, shelf-ready display needs, and regulatory compliance for direct food contact applications.
Product Type:
Cost tier differentiation separates commodity-grade single-wall specifications from premium double-wall configurations engineered for fragile goods protection.
- Single Wall:One corrugated fluting layer bonded to linerboard delivers lightweight structural integrity for dry food and personal care applications. German retailers specify this grade for shelf-ready beverage multi-packs where handling stresses remain moderate and logistics cost minimization drives procurement.
- Double Wall:Twin fluting layers separated by an intermediate liner provide stacking strength for electronics and fragile goods segments. Demand concentrates in France and Germany where e-commerce fulfillment requires pallet-load stability through multi-node distribution networks.
- Corrugated:Fluted medium between flat liners achieves calibrated crush resistance for industrial transit packaging.
- Rigid:Solid fiberboard construction without corrugation suits premium cosmetic and gift applications requiring edge crush resistance.
Single Wall holds installed capacity. Double Wall is rotating up the share rankings.
End Use Industry:
Application-specific performance requirements shape adhesive selection, coating chemistry, and barrier specifications across vertical demand pools.
- Food & Beverage:Direct food contact compliance mandates FDA substrate specifications and migration-tested ink systems for cereal, frozen meals, and beverage multi-packs. REACH chemical restrictions are accelerating water-based adhesive transitions in EU-serving converter operations.
- Personal Care:Scuff-resistant UV coatings and fine-line lithographic reproduction support premium brand positioning for cosmetics and skincare cartons. French and German brands drive specification centralization at regional headquarters.
- Electronics:Electrostatic discharge protection and stacking strength requirements favor double-wall configurations with conductive coatings.
- Pharmaceuticals:Serialization compatibility and tamper-evident closure integration dominate specification conversations with contract packaging organizations.
Food & Beverage anchors volume throughput. Electronics is gaining share fastest on e-commerce fulfillment expansion.
Packaging Format:
Customer type differentiation separates retail-facing display units from protective transit configurations in procurement decision frameworks.
- Box:Six-panel folding carton structures with tuck or glued closures serve primary packaging for dry goods and beverages. German retail chains specify shelf-ready box formats with pre-applied shelf trays that reduce in-store labor.
- Sleeve:Wraparound paperboard bands encase multi-unit beverage and personal care combinations. Dutch and Belgian converters specialize in high-speed sleeve application for carbonated soft drink promotional packs.
- Tray:Open-top corrugated platforms support display-ready palletization for club store and mass retail channels.
- Display:Pre-merchandised floor units with integrated graphics and product-facing surfaces command premium positioning. This format climbs the fastest on retailer labor cost reduction mandates across Central European supply chains.
Box maintains production volume leadership. Display is ascending the share trajectory on retail automation priorities.
Printing Technology:
Maturity and margin profiles separate established lithographic volume production from emerging digital platforms in converter capital allocation.
- Flexographic:Rotary relief printing on flexible photopolymer plates delivers cost-efficient single- to three-color reproduction for commodity food packaging. Water-based flexo inks align with EU circularity mandates but limit fine-line capability versus lithographic alternatives.
- Lithography:Offset printing from planographic plates achieves four- to six-color process reproduction with aqueous or UV coating options. German beverage multi-pack converters deploy extended color gamut systems with closed-loop spectrophotometry to compress makeready cycles.
- Gravure:Engraved cylinder printing sustains ultra-long runs where cylinder amortization spreads across high-volume publication and promotional packaging.
- Digital:Inkjet and toner-based systems enable variable data and short-run versioning without platemaking overhead.
Lithography dominates installed press capacity. Digital is climbing fastest on promotional versioning demand and makeready reduction targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in litho laminated carton exports to Central European retail chains, while the United States and China balance import dependency in specialty coated grades against domestic volume production for beverage and food applications.
Germany
Folding carton converters in the Rhine-Ruhr and Bavarian industrial corridors supply shelf-ready packaging to Aldi, Lidl, and REWE central procurement. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that compress converter timelines for adhesive reformulation. E-commerce fulfillment hubs around Leipzig and Frankfurt drive double-wall specification demand for electronics palletization.
United States
Beverage multi-pack procurement from Coca-Cola and PepsiCo bottlers sustains high-volume lithographic throughput in the Southeast and Midwest. FDA substrate specifications for direct food contact interact with EPA emissions frameworks governing adhesive lamination operations. Chicago and Atlanta metropolitan areas concentrate folder-gluer capacity serving national retail distribution networks.
China
Export-oriented converters in the Yangtze River Delta produce litho laminated cartons for European and North American consumer electronics brands. GB standards for packaging materials and the dual carbon goals shape coating chemistry investments and energy-efficient curing technology adoption. Shanghai and Suzhou industrial zones host integrated sheet plants with captive design-to-shelf service capabilities.
France
Personal care and cosmetics brands in the Île-de-France region specify premium rigid cartons with UV scuff-resistant coatings for luxury positioning. REACH chemical restrictions through ECHA oversight accelerate water-based adhesive transitions in converter operations. Lyon and Marseille logistics corridors channel display-format production toward Southern European retail supply chains.
India
Domestic FMCG brands in Maharashtra and Gujarat expand litho laminated procurement for modern retail shelf-ready formats. FSSAI food contact compliance and BIS packaging standards create dual-track regulatory management for converters serving export and domestic markets. Mumbai and Ahmedabad industrial belts concentrate mid-sized converters adopting high-speed folder-gluer leasing models.
Litho Laminated Cartons Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate supply and coating chemistry. The vendor base separates into three strata: integrated paperboard producers with captive carton operations, independent folding carton converters leasing equipment for color reproduction capability, and regional sheet plants bundling design services with local production. Consolidation pressure operates through M&A activity among paperboard mills and strategic partnerships between converters and brand design studios.
Among integrated majors, WestRock Company and Smurfit Kappa Group exemplify the captive supply archetype that controls margin exposure through backward integration into paperboard production. Graphic Packaging International occupies a position within the beverage multi-pack specialization tier, where speed-to-shelf capability determines competitive standing. These three companies represent distinct strategic postures: upstream resource control, regional network density, and vertical application focus respectively.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Kappa Group |
| Graphic Packaging International |
| Mayr-Melnhof Karton AG |
| Parksons Packaging Ltd. |
| WestRock Company |
| Packaging Corporation of America |
| DS Smith Plc |
| Grief, Inc. |
| Others |
Supply & Pricing Matrix
Paperboard input concentration among integrated majors compresses margin flexibility for independent converters while simultaneously widening pricing tier spreads between captive-supply operators and spot-market dependents. This structural dependency determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of production capacity around captive mill networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against price volatility. Price differentiation hinges on certification grade for direct food contact compliance and volume scale thresholds that unlock tiered rebates. Cost compression in the standard tier intensifies because REACH-mandated adhesive reformulations add conversion overhead without commensurate price recovery. Beverage multi-pack procurement teams at Coca-Cola and PepsiCo bottlers exhibit highest price sensitivity, while cosmetics brands in France prioritize scuff-resistant UV coatings over unit cost minimization.
Supply Chain Analysis
Extended payment terms from German retail chains strain working capital for mid-sized converters operating without integrated paperboard supply. Raw material sourcing draws from Swedish and Finnish pulp producers, German linerboard mills, and Chinese coating chemical suppliers. Single-source vulnerability concentrates in aqueous adhesive formulations where ECHA registration timelines create approval bottlenecks. Distribution runs through regional sheet plant networks with design-to-shelf bundling, compressing delivery windows for Central European retail supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The litho laminated cartons market functions as a defensive-moat arena where regulatory entrenchment around EU Packaging and Packaging Waste compliance creates durable switching costs for incumbent converters.
For Market Incumbents: Pre-empt water-based adhesive capability gaps by acquiring formulation expertise through targeted hiring of rheology specialists before ECHA phase-down deadlines tighten. Secure backward integration into paperboard supply through long-term offtake agreements with Nordic pulp producers, neutralizing spot market volatility that threatens margin stability. This dual move defends against emerging asset-light entrants leasing high-speed folder-gluer capacity. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors present underpenetrated white-space for modern retail shelf-ready formats serving domestic FMCG brands. Target electronics double-wall specifications in French e-commerce fulfillment hubs where stacking strength requirements exceed incumbent single-wall capacity. A design-to-shelf service bundling strategy with regional sheet plant partnerships offers the most penetrable go-to-market angle against integrated majors. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward converters with UV LED curing infrastructure already deployed. Mid-sized German sheet plants with beverage packaging lines and compliant coating platforms represent the optimal target archetype for consolidation plays. Monitor ECHA substance restriction announcements as the primary inflection signal for valuation adjustments across adhesive-dependent operations.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive System Conversion | REACH compliance deadlines in EU member states force capital allocation decisions before ECHA phase-downs tighten. |
| UV LED Curing Technology Deployment | Energy-efficient curing platforms satisfy EU F-Gas Regulation while maintaining throughput for beverage multi-pack lines. |
| Regional Sheet Plant Network Expansion | Local production proximity to German retail central procurement reduces logistics costs and accelerates speed-to-shelf. |
| Design-to-Shelf Service Bundling | Integrated creative and production capabilities create switching costs that distant competitors cannot replicate. |
| High-Speed Folder-Gluer Leasing Models | Asset-light equipment access lowers entry barriers for mid-sized converters seeking four- to six-color reproduction capability. |
Research Methodology
Initial hypotheses were tested against primary input from folding carton plant managers, CPG procurement leads, adhesive formulation chemists, and retail category buyers and refined through secondary validation. Trade data from Eurostat and UN Comtrade, SEC filings from integrated paperboard producers, ECHA substance registration databases, and German packaging industry association reports anchored supply-side characterization. Bottom-up capacity modeling across regional sheet plant networks was triangulated against top-down demand estimates from beverage and personal care brand procurement disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmented projections by structural configuration, end-use vertical, packaging format, and printing technology platform. CAGRs were derived from regression analysis of historical capacity utilization against macroeconomic drivers and regulatory compliance cost trajectories. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines and REACH chemical restriction phase-down schedules.
Practitioners should monitor ECHA substance restriction announcements, German retailer shelf-ready packaging mandate expansions, and paperboard spot price volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Cupcake Box Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Shaped Liquid Cartons Market
Cartons
Round Corrugated Box Market
Cartons
North America Corrugated Boxes Market
Cartons
Carton Display Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Mono Carton Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Tablet Cartons Market
Cartons
Carton Sealer Machine Market
Cartons
Beverage Cartons Market
Cartons
Wax Boxes Market
Cartons
Japan Corrugated Boxes Market
Cartons
Microwaveable Carton Market