
 Testliner Market | 2026-2036
Testliner Market Size, Share, and Industry Trends Forecast 2026-2036
Testliner Market Analytics
European containerboard producers is expanding recycled fiber capacity to serve the corrugated packaging value chain. Smurfit Kappa Group leverages integrated mill-to-box operations across Ireland and continental Europe. Mondi Group anchors its competitive position through lightweighting R&D at specialty testliner grades. International Paper Company sustains North American supply breadth via long-fiber blending expertise.
Testliner is a multi-ply paperboard manufactured from recycled or virgin fibers, typically ranging from 80 to 350 grams per square meter, engineered as the outer liner in corrugated board where tensile strength and printability matter. Recycled Testliner dominates volume flows in Europe where collection infrastructure supports closed-loop fiber systems, while Kraft Testliner commands premium positioning in moisture-resistant export packaging for pharmaceuticals and electronics. The Application split reveals Packaging as the mature revenue base and Industrial Use as the segment where specification tightening around stackability and climate resilience generates margin expansion.
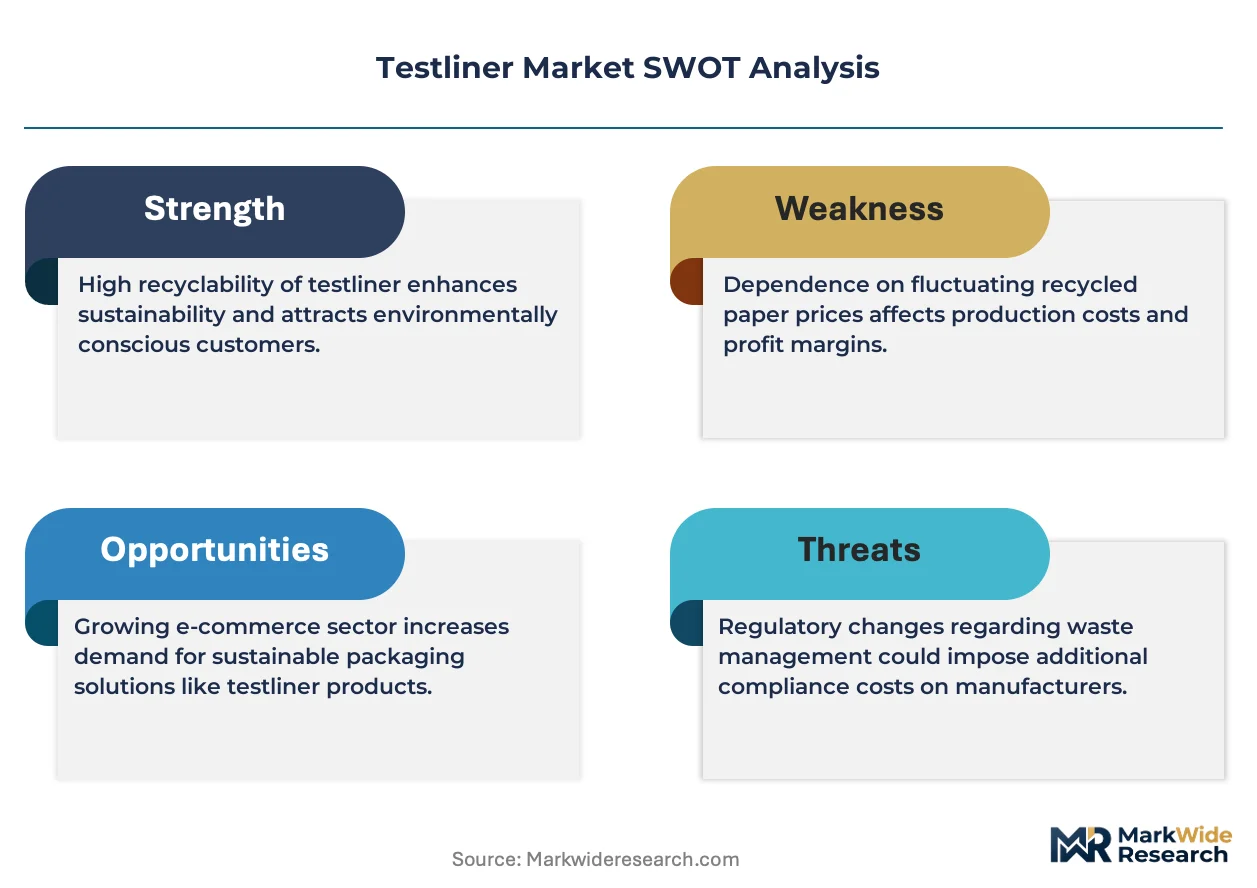
The EU Packaging and Packaging Waste Regulation and the F-Gas Regulation shape material compliance obligations for testliner producers serving temperature-controlled supply chains. FDA food-contact standards and BIS certification requirements govern cross-border market access for recycled-content liners entering food and beverage packaging. Stakeholders must monitor fiber certification schemes and extended producer responsibility frameworks as these mechanisms increasingly determine supplier eligibility and contract renewal terms.
Market Dynamics
Recycled fiber supply concentration across Central European mills is forcing corrugated packaging buyers into longer-term offtake commitments with fewer qualified suppliers, fundamentally restructuring procurement risk allocation.
Growth Catalysts
- E-commerce fulfillment expansion:Automated picking systems in German and Polish distribution centers demand crush-resistant outer liners that withstand repeated handling cycles.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for transport packaging create guaranteed demand pull for certified Testliner grades across member states.
- Lightweighting R&D:Specialty grammage reductions below 100 gsm maintain burst strength while cutting fiber input costs and shipping weight for automotive parts exporters.
Market Restraints
- Old corrugated container price volatility:Collection rate fluctuations in Southern Europe directly compress mill margins when recovered fiber spot markets spike.
- Single-region pulp dependency:Nordic kraft pulp integration into moisture-resistant grades exposes producers to Baltic Sea logistics bottlenecks and energy cost pass-throughs.
- Plastic corrugated substitution:Reusable polypropylene boxes in closed-loop pharmaceutical distribution erode high-margin export packaging volumes.
Strategic Opportunities
- Underpenetrated cold-chain segments:Temperature-controlled pharmaceutical lanes from Belgium into North Africa lack compliant moisture-barrier liner capacity at origin.
- F-Gas Regulation compliance packaging:Insulated box liners meeting EU fluorinated gas phase-out timelines command premium positioning in medical device exports.
- Digital print surface optimization:High-resolution flexo and inkjet compatibility opens short-run customized branding for craft beverage producers in Netherlands and Denmark.
Industry Challenges
- Fiber contamination control:Food-contact FDA and BIS certification requires expensive sorting infrastructure upgrades at recycled pulp mills to eliminate adhesive and ink residues.
- Skilled technician scarcity:Multi-ply former alignment and moisture profile calibration expertise is retiring faster than vocational programs in France and Italy can replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testliner Market |
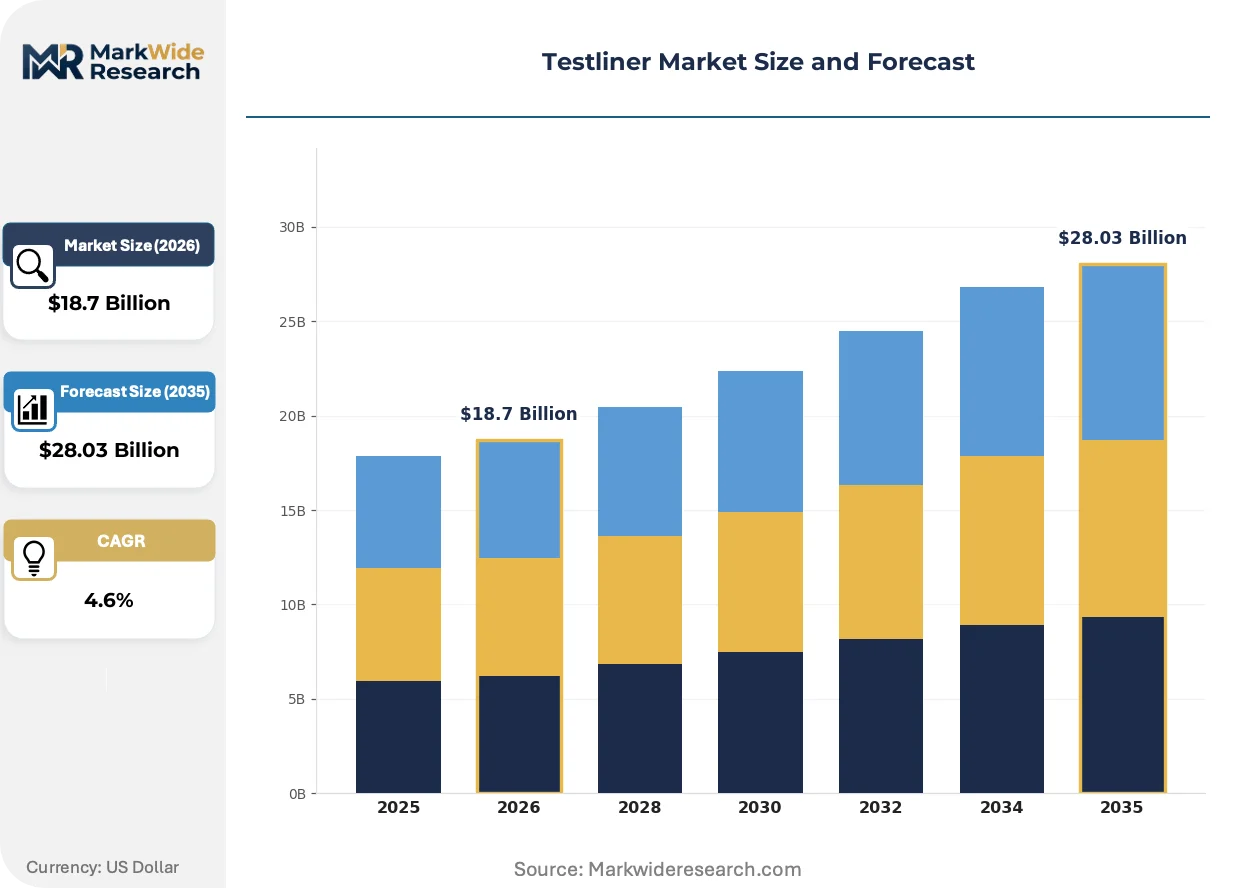
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Testliner, Aromatic Testliner, Kraft Testliner, Virgin Testliner Application: Packaging, Shipping, Industrial Use, Consumer Products End User: Food & Beverage, Electronics, Household Goods, Pharmaceuticals Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Smurfit Kappa Group, Mondi Group, International Paper Company, DS Smith Plc, WestRock Company, Nine Dragons Paper Holdings Limited, Oji Holdings Corporation, Stora Enso Oyj, Sappi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testliner Market Evolving Landscape
Digital manufacturing integration and regulatory compliance automation are compressing product development cycles while fragmenting specification requirements across end-use verticals.
Machine-direction orientation technology is converging with recycled fiber processing to produce high-tensile liners at reduced basis weights. Automotive tier-one suppliers in Stuttgart and Wolfsburg are qualifying these grades for heavy-component dunnage. The convergence is displacing virgin kraft liner in protective packaging applications where printability requirements are secondary.
EU F-Gas Regulation phase-down schedules are forcing cold-chain packaging redesigns across pharmaceutical distribution networks. Temperature-sensitive biologics shippers must now validate insulation systems without hydrofluorocarbon blowing agents. German and Belgian logistics providers are accelerating trials of fiber-based thermal barriers with phase-change material integration.
Consolidated buying by pan-European e-commerce platforms is compressing supplier qualification timelines from 18 months to 6 months. Third-party logistics operators in Rotterdam and Hamburg now mandate ISO 14001 certification and real-time carbon footprint disclosure as table stakes for liner procurement. French and Spanish corrugated converters are restructuring sales organizations around dedicated key account teams rather than regional territory coverage.
Testliner Market Segmentation
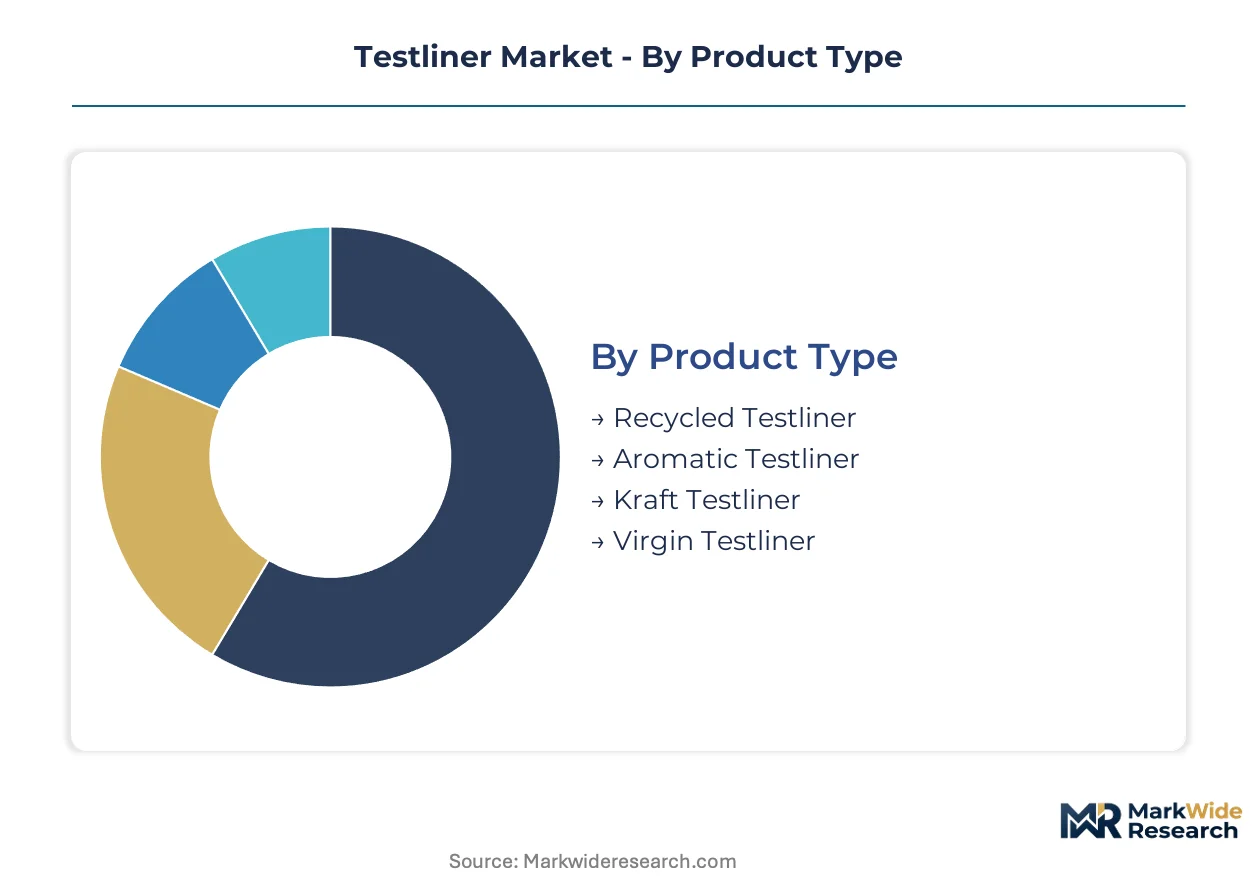
Testliner procurement decisions cascade through multiple segmentation layers, with fiber sourcing and end-use compliance requirements creating distinct value pools. Buyers select grades based on recycled content mandates, moisture resistance needs, and print surface specifications rather than commodity pricing alone.
Product Type:
Mill investment cycles and regulatory deadlines are driving accelerated replacement of legacy liner grades with specification-upgraded alternatives.
- Recycled Testliner:Manufactured from 100% recovered fiber with multi-ply construction ranging 80-200 gsm. German automotive parts exporters and Polish e-commerce fulfillment centers specify this grade for closed-loop compliance with EU Packaging and Packaging Waste Regulation mandates.
- Kraft Testliner:Incorporates unbleached virgin kraft pulp for superior tensile strength and moisture resistance. Belgian pharmaceutical cold-chain shippers and Dutch electronics exporters pay premiums for FDA-compliant moisture-barrier performance in temperature-controlled lanes.
- Aromatic Testliner:Specialty grade with odor-neutralizing treatment for sensitive cargo. French perfume and cosmetics houses specify this grade for luxury packaging where fiber scent contamination risks rejection.
- Virgin Testliner:Produced from bleached chemical pulp for high-resolution print applications. Italian food-contact packaging converters favor this grade for direct-print branding on premium consumer goods.
Recycled Testliner sits at the top of the volume ranking, with Kraft Testliner climbing the fastest as moisture-resistant export packaging specifications tighten.
Application:
End-use margins diverge sharply based on specification complexity and certification burden rather than tonnage scale.
- Packaging:Corrugated outer liners for box construction, spanning 100-350 gsm. German and Spanish food processors dominate procurement, with EU recycled content thresholds guaranteeing baseline demand regardless of economic cycles.
- Industrial Use:Dunnage, separators, and protective interlayers for heavy manufacturing. Stuttgart automotive tier-one suppliers are qualifying machine-direction oriented grades below 100 gsm that displace virgin kraft in component shipping.
- Shipping:Export-ready corrugated containers with enhanced stackability. Rotterdam and Hamburg logistics providers mandate burst strength certifications above industry minimums for transoceanic lanes.
- Consumer Products:Direct-print retail packaging with brand surface requirements. Netherlands craft beverage producers and Danish specialty food brands drive short-run digital print compatibility specifications.
Packaging captures the dominant revenue base, while Industrial Use expands most quickly as lightweighting R&D penetrates protective applications.
End User:
Customer procurement sophistication varies dramatically across verticals, with regulatory exposure determining supplier qualification intensity.
- Food & Beverage:The most certification-intensive segment, requiring FDA and BIS compliance for recycled-content food-contact applications. French and Italian converters invest in expensive sorting infrastructure upgrades to eliminate adhesive and ink residues from recovered fiber streams.
- Pharmaceuticals:Temperature-sensitive biologics distribution demands F-Gas Regulation-compliant thermal barriers. Belgian logistics providers trial fiber-based insulation with phase-change material integration as hydrofluorocarbon phase-down deadlines approach.
- Electronics:Moisture-resistant export packaging for semiconductors and consumer devices. Dutch and German electronics manufacturers specify Kraft Testliner for humidity-controlled sea freight to Southeast Asian assembly plants.
- Household Goods:Standard corrugated applications with lower specification barriers. Spanish and Portuguese retailers source primarily on price and availability through distributor networks.
Food & Beverage maintains the largest installed procurement base, with Pharmaceuticals gaining share fastest as cold-chain compliance requirements multiply.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with direct relationships commanding premium positioning.
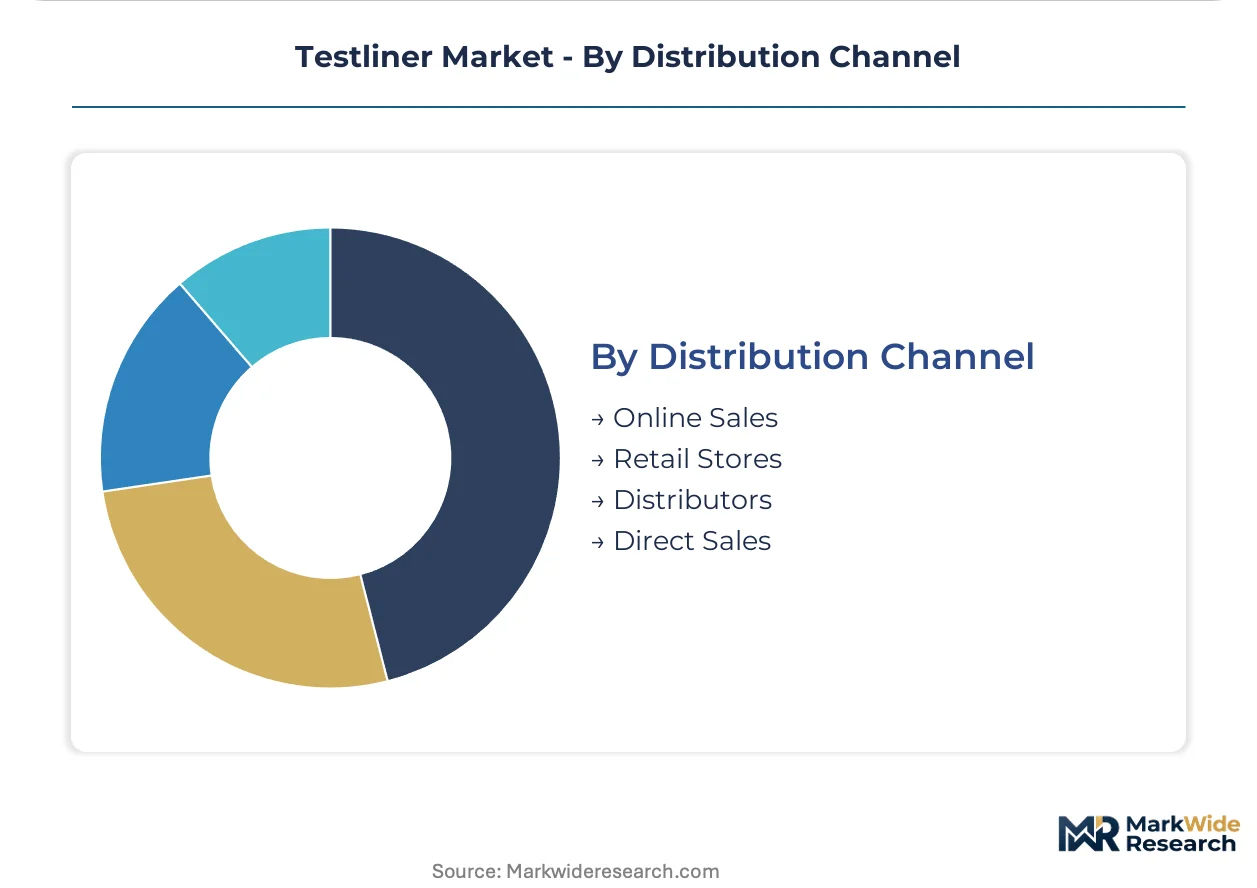
- Direct Sales:Mill-to-converter relationships for high-volume, specification-critical accounts. Smurfit Kappa and Mondi Group deploy integrated mill-to-box operations across Ireland and continental Europe to capture this channel.
- Distributors:Regional inventory holders serving mid-tier converters with shorter lead time requirements. Southern European mills rely on distributor networks to manage recovered fiber price volatility exposure.
- Online Sales:Emerging channel for standardized grades and spot procurement. Small Spanish and Portuguese converters utilize digital platforms for trial quantities and emergency restocking.
- Retail Stores:Limited relevance for testliner as a B2B input material; primarily serves artisan and small-batch packaging producers in craft segments.
Direct Sales anchors the highest-margin volume, with Distributors retaining the broadest geographic coverage across fragmented converter bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping Testliner production geography as mills migrate toward jurisdictions with lower compliance costs for recycled fiber processing. The EU Packaging and Packaging Waste Regulation creates divergent cost structures across member states, pushing capacity expansion toward Central European collection hubs while premium grades concentrate in Nordic kraft pulp regions.
Germany
Automotive parts exports from Stuttgart and Wolfsburg drive demand for machine-direction oriented grades below 100 gsm. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that German mills meet through integrated collection networks. The Rhine-Ruhr industrial corridor hosts the densest concentration of multi-ply former capacity serving e-commerce fulfillment centers in Poland and the Netherlands.
Belgium
Pharmaceutical cold-chain distribution into North Africa generates premium demand for F-Gas Regulation-compliant moisture-barrier liners. The Port of Antwerp-Bruges anchors temperature-controlled logistics infrastructure where Belgian logistics providers trial fiber-based thermal barriers with phase-change material integration. ECHA chemical compliance frameworks govern adhesive and coating specifications for food-contact applications.
Netherlands
Craft beverage producers in Amsterdam and Rotterdam drive short-run digital print compatibility specifications for consumer-facing packaging. The Dutch national packaging covenant imposes extended producer responsibility fees that favor closed-loop fiber systems. The Randstad logistics cluster mandates ISO 14001 certification and real-time carbon footprint disclosure for liner procurement contracts.
Poland
E-commerce fulfillment center expansion around Warsaw and Wrocław absorbs crush-resistant outer liners for automated picking systems. EU cohesion fund investments upgrade recovered fiber sorting infrastructure to meet food-contact BIS certification requirements for export markets. Silesian industrial zones attract German automotive tier-one suppliers qualifying lightweight dunnage grades.
France
Perfume and cosmetics houses in Paris specify aromatic Testliner grades for luxury packaging where fiber scent contamination risks rejection. ANSM pharmaceutical packaging standards govern temperature-sensitive biologics distribution from Lyon and Strasbourg. The Île-de-France converter base is restructuring sales organizations around dedicated key account teams for pan-European platforms.
Testliner Market Competitive Landscape
European producers anchor the integrated mill-to-box tier; Asian specialists hold scale positions in recovered fiber processing. The vendor base splits between consolidated pan-regional operators with captive pulp supply and fragmented national converters dependent on spot fiber markets. Three archetypes dominate: vertically integrated packaging conglomerates, recycled fiber specialists with backward integration into collection networks, and virgin kraft producers diversifying into hybrid grades. Competitive moves center on lightweighting R&D partnerships with automotive OEMs and mill acquisitions securing OCC supply concentration zones.
Within the integrated European tier, Smurfit Kappa Group and Mondi Group exemplify mill-to-box operations spanning Ireland and continental Europe. International Paper Company occupies a position representing North American long-fiber blending expertise serving moisture-resistant export specifications. These three anchors demonstrate how geographic origin and corporate structure map to competitive archetype: Dublin-based Smurfit Kappa Group and Vienna-based Mondi Group sit within the EU regulatory compliance cluster, while Tennessee-incorporated International Paper Company represents transatlantic supply breadth.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Mondi Group |
| International Paper Company |
| DS Smith Plc |
| WestRock Company |
| Nine Dragons Paper Holdings Limited |
| Oji Holdings Corporation |
| Stora Enso Oyj |
| Sappi Limited |
| Others |
Value Network & Pricing Analysis
Multi-ply former alignment expertise concentrated in the Rhine-Ruhr corridor and northern France feeds directly into pricing-tier spreads across the Testliner market, with labor-cost differentials between these established industrial zones and emerging Polish capacity creating measurable gaps between premium specification grades and commodity recycled liners.
Pricing Analysis
Distributor margin layers absorb recovered fiber price volatility while direct-to-OEM channels command volume discounts for automotive tier-one suppliers in Stuttgart. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant Kraft Testliner for Belgian pharmaceutical cold-chain from basic recycled grades serving Spanish household goods retailers. Cost compression in the standard tier is intensifying because old corrugated container spot markets spike unpredictably across Southern Europe. Mid-tier corrugated converters exhibit highest price sensitivity, while pharmaceutical logistics providers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive exporters and Dutch electronics manufacturers, while distributor networks serve fragmented converter bases in Portugal and Greece. Supply concentrates in Germany, Poland, and Belgium, with Nordic kraft pulp integration for moisture-resistant grades drawing from Swedish and Finnish fiber streams. Raw material dependencies center on recovered old corrugated containers, unbleached kraft pulp, and specialized barrier coatings. Single-source vulnerability runs through Baltic Sea logistics corridors for virgin fiber imports. Distribution runs through integrated mill-to-box operators alongside independent regional inventory holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Testliner market reads as a late-cycle quality story, with specification tightening around F-Gas Regulation compliance and FDA food-contact certification driving demand shifts toward premium moisture-barrier and aromatic grades.
For Market Incumbents: Cement backward integration into recovered fiber collection networks across Central European hubs to secure OCC supply concentration zones against price volatility. Lock in long-term offtake commitments with German automotive tier-one suppliers qualifying machine-direction oriented grades below 100 gsm, while investing in contamination-control sorting infrastructure to defend FDA certification positioning against emerging Polish capacity. For New Entrants and Emerging Players: Digital platform procurement for standardized grades offers the lowest barrier to entry, enabling spot-market participation without mill infrastructure. Target underpenetrated cold-chain segments in temperature-controlled pharmaceutical lanes from Belgium into North Africa, where compliant moisture-barrier liner capacity at origin remains scarce. Lead with F-Gas Regulation compliance packaging as the qualifying wedge for premium positioning. For Investors and Strategic Acquirers: Packaging conglomerates with captive pulp supply are the most active acquirer in this space, consolidating recycled fiber specialists to secure closed-loop systems. Long-term viability hinges on exposure to regulatory-mandated recycled content thresholds rather than cyclical packaging demand. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal for margin expansion in certified grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive OCC supply insulates German mills from Southern European spot market volatility. |
| Lightweighting R&D Partnerships | Machine-direction orientation trials with Stuttgart automotive OEMs displace virgin kraft in dunnage. |
| F-Gas Compliance Certification | Belgian pharmaceutical cold-chain shippers validate fiber-based thermal barriers ahead of phase-down deadlines. |
| Digital Print Surface Optimization | Netherlands craft beverage producers drive short-run flexo compatibility for premium branding. |
| Extended Producer Responsibility Alignment | Dutch national packaging covenant fees favor closed-loop fiber systems with ISO 14001 disclosure. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Nordic region, with primary inputs from each. The analysis combines structured interviews with mill operations directors, corrugated converter procurement leads, automotive tier-one supplier packaging engineers, and pharmaceutical logistics compliance officers with secondary validation from trade customs data, EU regulatory filings, and industry association reports. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates across the analysis window.
Granularity-level modeling disaggregates the market by fiber sourcing type, end-use compliance tier, application specification intensity, and regional production hub clustering. CAGRs derive from segment-level growth rate blending weighted by current revenue footprints, incorporating automotive export volume trajectories, e-commerce fulfillment center expansion pipelines, and pharmaceutical cold-chain infrastructure investment cycles as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path for machine-direction orientation and digital print compatibility; alternative pathways for thermal barrier phase-change material integration would alter the outlook. Forecasts reflect documented assumptions regarding EU regulatory enforcement timelines and recovered fiber collection rate stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Paperboard Partition Market