
 North America Paper Packaging Market | 2026-2036
North America Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paper Packaging Market Outlook
The EPA's recycled fiber content requirements under the Comprehensive Procurement Guideline is repositioning procurement standards across federal and state agencies. International Paper Company leverages its integrated pulp-to-box network across the southeastern United States to secure virgin and recycled fiber supply. Smurfit Westrock anchors its competitive position through mill system optimization and containerboard scale. Packaging Corporation of America differentiates via lightweight linerboard technology that reduces material intensity per shipping unit.
North America paper packaging encompasses corrugated containers, folding cartons, paper bags, and protective wraps manufactured from wood pulp, recycled fiber, or agricultural residues, typically ranging from 150 to 450 grams per square meter in basis weight depending on application. Its primary purpose is to contain, protect, and transport goods while providing printable surfaces for branding and regulatory labeling. Boxes dominate product type volume due to e-commerce fulfillment and retail ready packaging requirements, while eco-friendly packaging types capture expanding margin pools as brand owners mandate plastic elimination. Flexible paper packaging competes in food service and dry goods segments where barrier coatings replace multi-material laminates.
The EPA enforces recycled content standards that shape municipal and federal purchasing, while state-level extended producer responsibility frameworks in California and Maine impose fee structures favoring readily recyclable paper substrates. The FTC Green Guides constrain environmental marketing claims, requiring substantiated recyclability and biodegradability assertions that filter permissible product positioning. Stakeholders must monitor evolving state legislation on plastic alternatives and fiber sourcing certification requirements to align capital deployment with compliance trajectories.
Market Dynamics
E-commerce fulfillment networks are rewiring demand geography across the United States and Canada, pulling corrugated containerboard capacity toward distribution clusters in Ohio, Pennsylvania, and Southern Ontario while EPA recycled content mandates force fiber sourcing recalibration.
Growth Catalysts
- California's single-use plastic restrictions:Food service operators in Los Angeles and San Francisco are redirecting procurement toward molded fiber clamshells and kraft paper wraps, creating pull-through demand for domestic molded pulp capacity.
- Great Lakes industrial corridor concentration:Wisconsin and Michigan paper mills feed integrated box plants serving Midwest manufacturing and distribution networks, reducing freight costs for regional CPG and automotive parts shippers.
- Lightweight linerboard technology:High-performance recycled fiber formulations are enabling basis weight reduction in shipping boxes without compression strength loss, cutting raw material intensity per e-commerce unit.
Market Restraints
- Old corrugated container (OCC) supply volatility:Domestic recycled fiber collection rates fluctuate with municipal recycling program economics, creating input cost instability for mills dependent on post-consumer furnish.
- Southeastern US pulp concentration:Virgin kraft linerboard production clusters in Georgia, Alabama, and Mississippi, exposing buyers to hurricane disruption risk and limited alternative supply during weather events.
- Barrier coating performance gaps:Water-based and bio-based grease-resistant coatings for food contact applications still underperform fluorinated alternatives in high-temperature holding, limiting molded fiber penetration in hot food service.
Strategic Opportunities
- Canadian prairie agricultural residue utilization:Wheat straw and flax stalks in Manitoba and Saskatchewan offer alternative fiber feedstocks for specialty paper packaging with lower water intensity than wood pulp.
- FTC Green Guides compliance services:Third-party substantiation of recyclability and biodegradability claims is creating adjacent revenue pools for testing laboratories and certification bodies serving brand owners.
- Direct-to-store replenishment formats:Retail-ready packaging with pre-printed shelf display surfaces is penetrating discount grocery and club store channels, replacing traditional corrugate with printed die-cut displays.
Industry Challenges
- Containerboard machine tender expertise:Operating high-speed corrugators and linerboard machines requires specialized mechanical knowledge that is aging out of the workforce faster than training programs replace it.
- FSC and SFI chain-of-custody audits:Brand owner mandates for certified fiber sourcing impose documentation complexity and audit costs that smaller independent box plants struggle to absorb.
- Legacy ERP integration with e-commerce order systems:Mid-tier converters face friction connecting corrugated quoting engines to customer procurement portals, slowing digital order capture against integrated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paper Packaging Market |
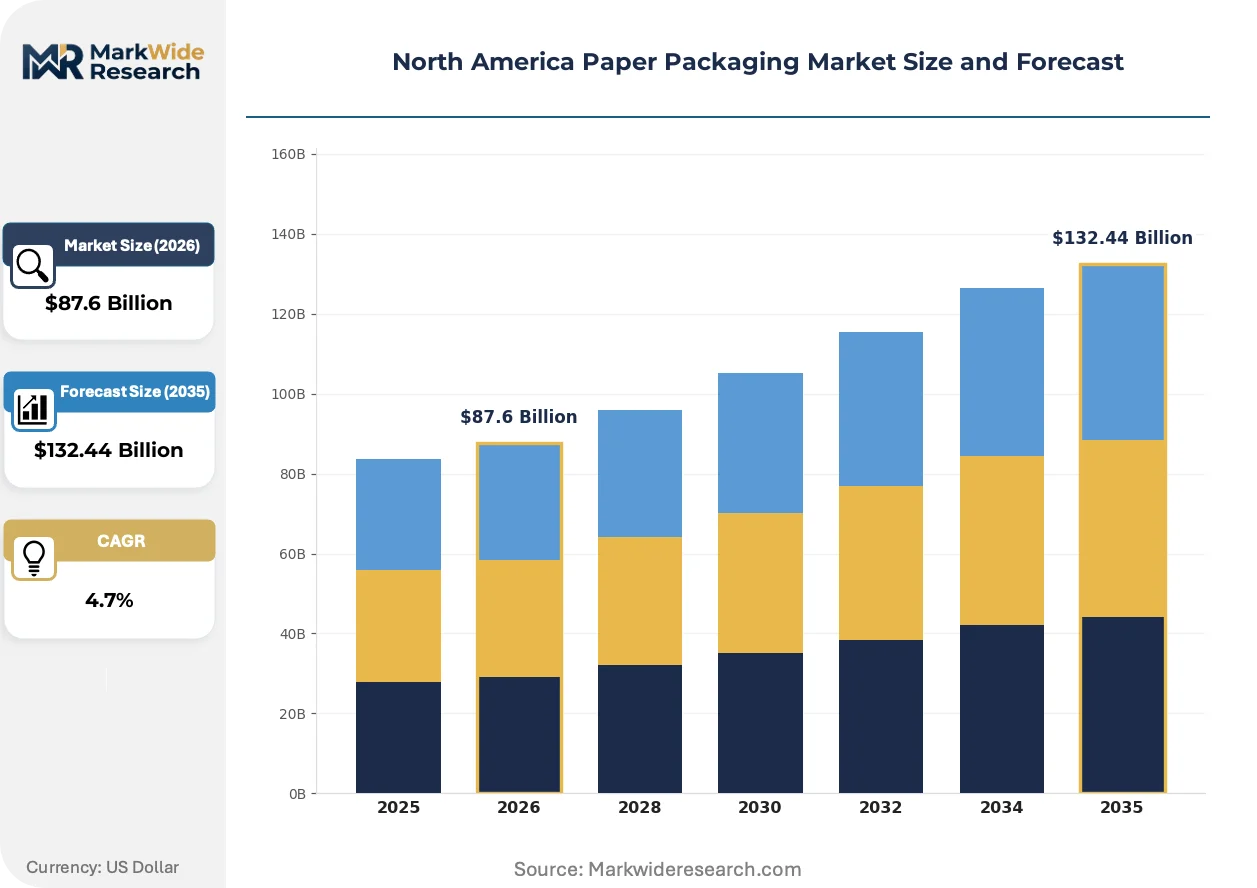
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $132.44 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Sheets End User: Food & Beverage, Electronics, Healthcare, E-commerce Packaging Type: Flexible, Rigid, Eco-friendly, Laminated Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | International Paper Company, Smurfit Westrock, Packaging Corporation of America, Graphic Packaging Holding Company, Georgia-Pacific LLC, Mondi Group, Cascades Inc., Sonoco Products Company, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paper Packaging Market Strategic Shifts
Digital printing and smart packaging layers are compressing production runs and enabling batch-level customization, while regulatory pressure on plastic elimination accelerates material substitution timelines across food and consumer goods segments.
Water-based flexographic and single-pass inkjet printing systems are decentralizing corrugated box production by enabling economical short runs with variable graphics. Regional independent converters in Texas and Illinois are installing these systems to serve craft beverage and specialty food clients needing seasonal artwork changes. This technology is decentralizing order fulfillment away from centralized mega-plants toward distributed micro-factories positioned near urban consumption zones.
The EPA's Comprehensive Procurement Guideline recycled content requirements are mandating minimum post-consumer fiber percentages in federal and state agency purchases. Packaging suppliers to government contracts must now certify furnish composition through third-party verification, shifting procurement evaluation criteria toward documented circularity metrics rather than unit price alone. Federal supply schedules and state cooperative purchasing agreements are the procurement channels most affected, with vendors re-engineering product specifications to meet threshold compliance.
Brand owner sustainability scorecards are compressing supplier qualification cycles and unbundling packaging from logistics services. Major CPG buyers in the Northeast and Pacific Coast are issuing requests for proposals that separate box supply from warehousing and fulfillment, enabling direct converter relationships that bypass traditional distributor intermediaries. This pattern is most visible in organic and natural foods verticals, where private equity-backed brands prioritize supply chain transparency and carbon accounting granularity that integrated logistics providers struggle to deliver.
North America Paper Packaging Market Segmentation
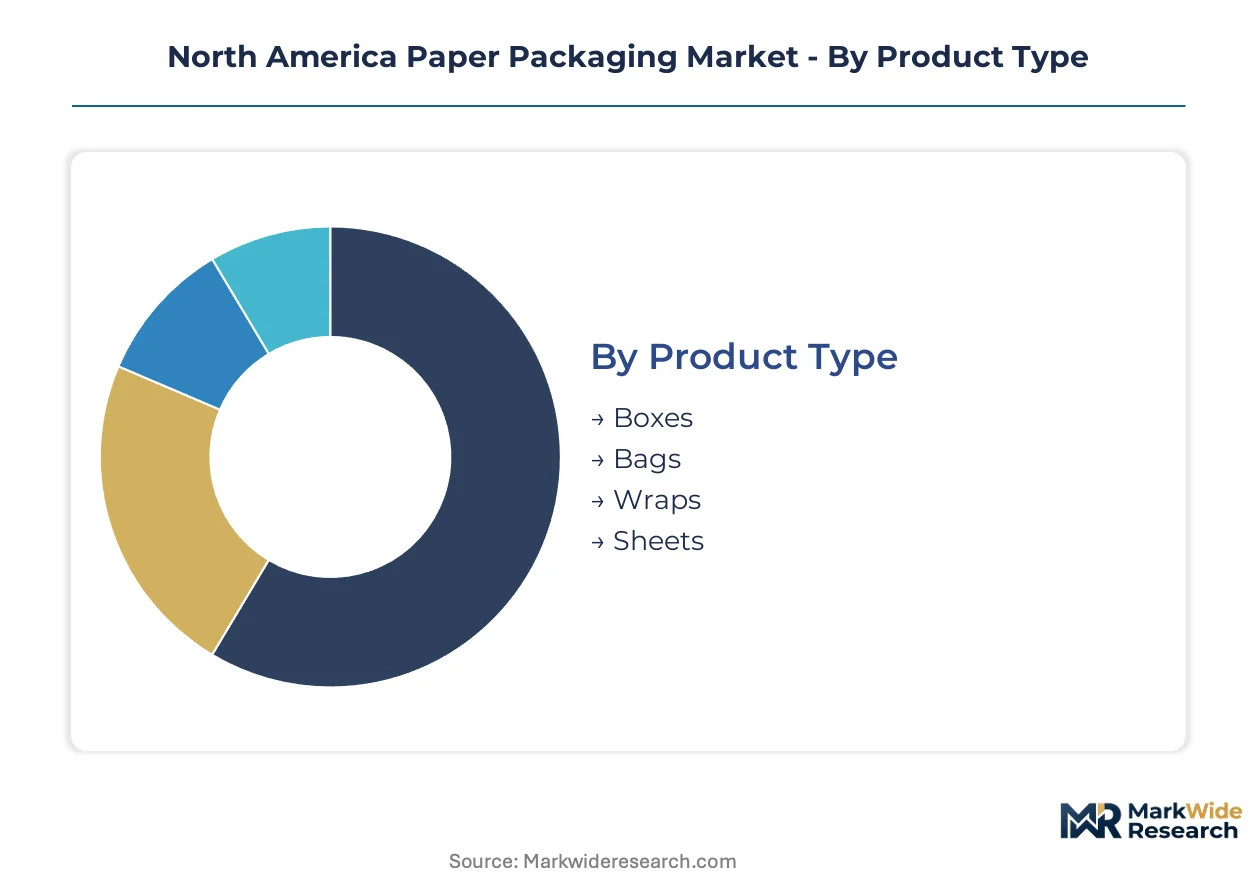
Segmentation in North America paper packaging exposes how e-commerce fulfillment, food service plastic bans, and federal recycled content mandates are redirecting capital toward specific product configurations and channel structures. Understanding these splits reveals where volume concentrates versus where margin expansion is occurring.
Product Type:
Boxes function as standalone shipping systems with complete structural independence, while bags, wraps, and sheets typically embed into larger packaging assemblies or protective layering schemes.
- Boxes:Corrugated containers built from linerboard and medium flute structures dominate e-commerce fulfillment networks across Ohio, Pennsylvania, and Southern Ontario distribution clusters. Amazon, Walmart, and Target fulfillment centers specify 32 ECT and 44 ECT grades for automated handling compatibility, pulling containerboard capacity toward regional box plants.
- Bags:Multiwall paper sacks and retail carry bags serve construction materials, agricultural feed, and food service applications where California's single-use plastic restrictions are redirecting grocery and quick-service restaurant procurement toward kraft paper alternatives with twisted paper handles.
- Wraps:Protective kraft and tissue papers interleave between automotive parts and glassware shipments across Michigan and Ohio manufacturing corridors, functioning as embedded cushioning rather than primary containment.
- Sheets:Flat corrugated pads and solid fiberboard slip sheets replace wooden pallets in Canadian retail distribution, enabling unit load stabilization without secondary packaging bulk.
Volume placements concentrate in Boxes; the faster expansion belongs to Eco-friendly packaging types gaining share fastest from plastic substitution mandates.
End User:
Cost tier stratification separates commodity-sensitive bulk shippers from premium-brand owners funding sustainability certification and custom print specifications.
- Food & Beverage:Molded fiber clamshells and kraft paper wraps are displacing polystyrene and polypropylene in Los Angeles and San Francisco food service markets where municipal ordinances mandate plastic elimination. Hot-holding performance gaps in water-based grease barriers constrain penetration in fried chicken and pizza delivery segments.
- E-commerce:Direct-to-consumer fulfillment networks in Texas, Illinois, and Georgia specify retail-ready packaging with pre-printed shelf display surfaces, compressing production runs and demanding digital print compatibility from regional converters.
- Electronics:Anti-static corrugated and molded pulp cushions protect semiconductor and consumer device shipments from Silicon Valley and Austin manufacturing clusters to assembly points in Mexico.
- Healthcare:Sterile barrier systems and temperature-validated shipping containers serve pharmaceutical distribution from New Jersey and Puerto Rico manufacturing hubs, requiring FDA-compliant fiber sourcing documentation.
Revenue concentration sits with Food & Beverage; Electronics represents the steepest expansion trajectory from reshoring-sensitive supply chains.
Packaging Type:
Maturity differentiation separates established rigid formats from emerging eco-friendly substrates still scaling coating and sealing performance to match incumbent plastic barriers.
- Rigid:Corrugated and solid fiberboard boxes provide structural integrity for heavy-goods shipping across Midwest automotive and appliance manufacturing networks, with Wisconsin and Michigan integrated mills supplying regional box plants.
- Flexible:Paper-based pouches and wraps with water-based barrier coatings compete in dry goods and bakery segments where moisture resistance requirements remain moderate.
- Eco-friendly:Molded fiber and agricultural residue-based packaging from Manitoba wheat straw operations serve organic and natural foods brands prioritizing carbon accounting transparency and plastic elimination scorecards.
- Laminated:Multi-material paper-plastic combinations face regulatory pressure from Maine and California extended producer responsibility frameworks that penalize non-recyclable substrates with higher fee structures.
Shipments cluster in Rigid formats; the climbing trajectory belongs to Eco-friendly alternatives as brand owner mandates compress substitution timelines.
Distribution Channel:
Customer type fragmentation separates high-volume contract purchasers from fragmented spot buyers with divergent service and specification requirements.
- Wholesalers:Industrial distributors in Chicago, Atlanta, and Dallas aggregate corrugated orders from small and mid-tier manufacturers, consolidating freight to box plants and managing inventory for customers lacking direct mill relationships.
- Online Retail:Amazon Business and Staples Advantage procurement portals enable mid-market shippers to bypass traditional distributor relationships, though legacy ERP integration friction slows adoption for smaller converters.
- Supermarkets:Kroger, Albertsons, and Publix specify retail-ready packaging with shelf-ready display characteristics, pushing pre-printed die-cut display requirements back to converter design teams.
- Convenience Stores:7-Eleven and Circle K chains source lightweight bags and wraps for grab-and-go food service, prioritizing unit cost over structural performance in high-turnover, low-margin categories.
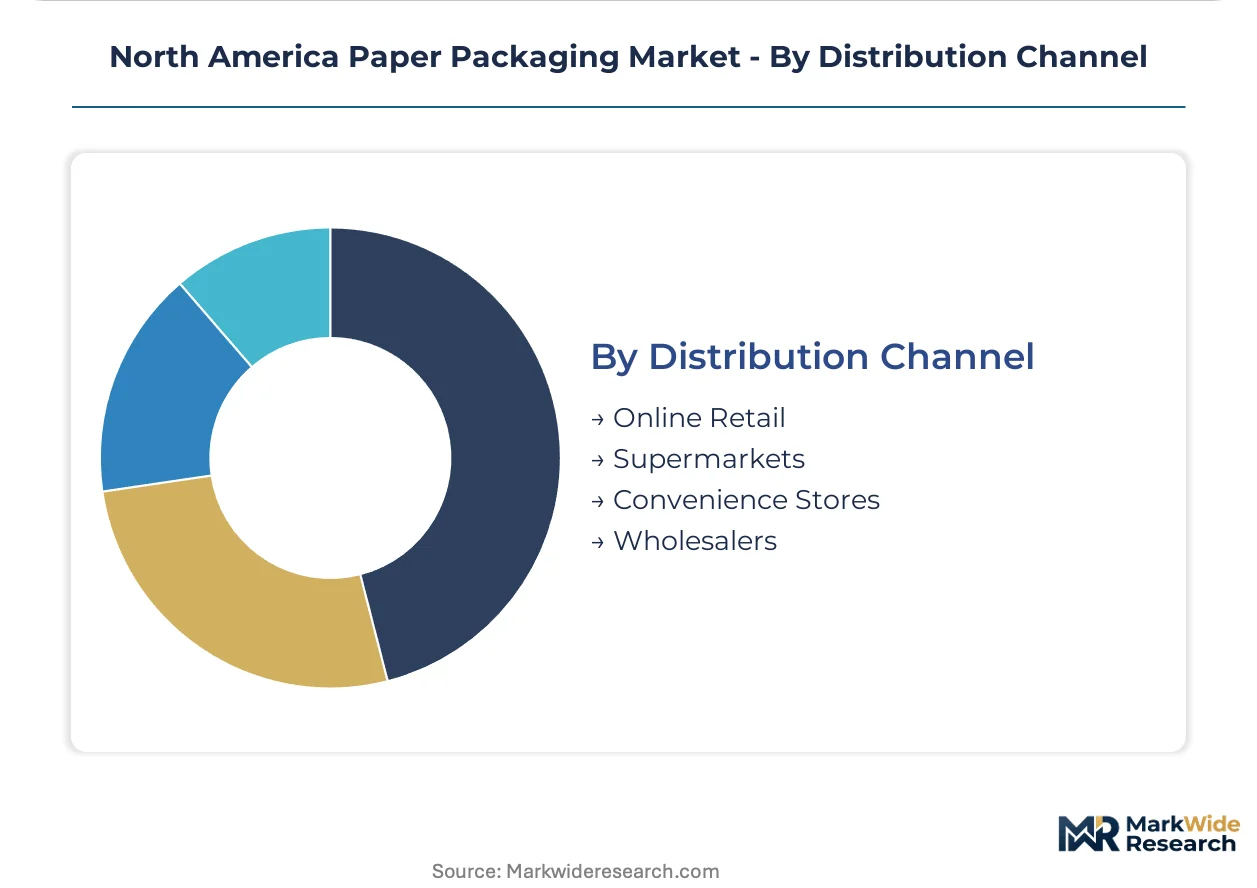
Transaction volume flows through Wholesalers; the channel gaining share fastest is Online Retail from procurement portal expansion and distributor disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of North American paper packaging output while Canada supplies integrated pulp and recycled fiber feedstocks. Mexico's manufacturing export growth is pulling corrugated capacity toward border distribution zones.
United States
EPA recycled content mandates under the Comprehensive Procurement Guideline redirect federal agency purchasing toward certified post-consumer fiber products. California and New York state-level single-use plastic restrictions accelerate molded fiber adoption in food service channels. The Great Lakes industrial corridor anchors production concentration, with Wisconsin and Michigan mills feeding integrated box plants serving Midwest automotive and CPG distribution networks.
Canada
Canadian prairie agricultural residues including wheat straw and flax stalks offer alternative fiber feedstocks with lower water intensity than conventional wood pulp. Health Canada and PMRA regulate food-contact packaging materials, shaping barrier coating approval pathways for domestic converters. Ontario and Quebec host the majority of integrated containerboard capacity, with Quebec-based Cascades Inc. operating recycled fiber mills serving Northeast US markets.
Mexico
Nearshoring of electronics and automotive assembly is expanding demand for protective corrugated and anti-static packaging across Nuevo León and Baja California manufacturing clusters. Mexico's federal environmental standards under SEMARNAT establish baseline recycled content expectations without matching California's stringency. The Mexico City metro area concentrates converting capacity for domestic consumer goods distribution, while northern border states feed cross-border e-commerce fulfillment.
Southeast United States
Virgin kraft linerboard production clusters in Georgia, Alabama, and Mississippi expose buyers to hurricane disruption risk during Atlantic storm seasons. The region's pulp mill concentration supports integrated box plant networks serving Florida retail distribution and Caribbean export markets. Atlanta anchors a major corrugated converting hub, with regional independent converters installing digital print systems to serve craft beverage and specialty food clients.
Pacific Coast
Los Angeles and San Francisco municipal ordinances mandate plastic elimination in food service packaging, creating concentrated demand for molded fiber clamshells and kraft paper wraps. Washington and Oregon state extended producer responsibility frameworks impose fee structures favoring readily recyclable paper substrates over multi-material alternatives. The Pacific Northwest hosts specialty paper producers serving organic and natural foods brands with carbon accounting transparency requirements.
North America Paper Packaging Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-box networks with captive fiber supply and regional scale advantages. Market concentration is moderate, with a tiered player base separating multinational integrated producers from independent regional converters and specialty niche operators. Three strategic archetypes dominate: vertically integrated forest products conglomerates with mill system optimization capabilities; independent converters leveraging digital print flexibility for short-run customization; and specialty molded fiber producers capturing plastic substitution premiums. Dominant competitive moves include capacity expansion in e-commerce corridor geographies and strategic partnerships with brand owners for retail-ready packaging development.
Within the integrated producer tier, International Paper Company exemplifies the southeastern US pulp concentration model, while Smurfit Westrock represents mill system optimization and containerboard scale advantages. Packaging Corporation of America occupies a position emphasizing lightweight linerboard technology and material intensity reduction. Among specialty and regional players, Cascades Inc. anchors Canadian recycled fiber integration, and Georgia-Pacific LLC sits within the forest products conglomerate archetype with diversified building products and packaging exposure.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Westrock |
| Packaging Corporation of America |
| Graphic Packaging Holding Company |
| Georgia-Pacific LLC |
| Mondi Group |
| Cascades Inc. |
| Sonoco Products Company |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
Old corrugated container (OCC) index volatility cascades through North American paper packaging supply chains, compressing margins for recycled fiber-dependent mills while concentrating pricing power among integrated producers with captive pulp supply in Georgia and Alabama.
Pricing Analysis
Throughput-based pricing anchors contract structures for e-commerce fulfillment centers, where Amazon and Walmart procurement teams negotiate per-unit rates tied to automated handling compatibility and damage-free delivery guarantees. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified retail-ready packaging from generic RSC shipping containers and spot-market surplus corrugate. Pricing pressure stems from lightweight linerboard technology enabling basis weight reduction without compression strength loss. Small and mid-tier manufacturers exhibit highest price sensitivity, while organic and natural foods brands prioritize carbon accounting transparency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from major CPG buyers mandate multi-supplier qualification across integrated producers in the United States, Canadian recycled fiber specialists, and Mexican border-state converters. Geographic supply concentrates in the United States, Canada, and Mexico, with virgin kraft linerboard production anchored in Georgia, Alabama, and Mississippi. Raw material dependencies center on OCC collections, wood pulp from southeastern pine plantations, and agricultural residues from Manitoba wheat straw operations. Hurricane exposure across Atlantic coast pulp mills creates single-source vulnerability during storm seasons. Distribution runs through industrial distributors in Chicago, Atlanta, and Dallas consolidating freight for fragmented spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American paper packaging sits in a material-transition phase, with water-based barrier coatings and digital print systems displacing fluorinated grease barriers and flexographic plate setups across food service and e-commerce segments.
For Market Incumbents: Anticipate molded fiber capacity shortages in California and New York by securing agricultural residue supply contracts with Manitoba and Saskatchewan operators before feedstock competition intensifies. Reinforce mill system optimization through lightweight linerboard R&D to defend against basis weight reduction demands from Amazon and Target fulfillment networks. Channel control through direct converter relationships bypasses distributor intermediaries that integrated logistics providers struggle to disintermediate. For New Entrants and Emerging Players: Enter via specialty molded fiber production serving Los Angeles and San Francisco food service markets where municipal plastic bans outpace domestic capacity expansion. White-space targets include hot-holding applications for fried chicken and pizza delivery where water-based grease barriers underperform fluorinated alternatives. The most penetrable segment is craft beverage and specialty food clients needing seasonal artwork changes through digital print compatibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional independent converters in Texas and Illinois installing single-pass inkjet systems to serve distributed micro-factory demand near urban consumption zones. Long-term viability hinges on backward integration into recycled fiber supply or specialty coating formulation capabilities. The signal to watch is EPA enforcement intensity under the Comprehensive Procurement Guideline redirecting federal purchasing toward certified post-consumer fiber products.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Linerboard Scale-Up | High-performance recycled fiber formulations cut material intensity per e-commerce unit for Amazon and Walmart. |
| Agricultural Residue Integration | Manitoba wheat straw and flax stalks reduce water intensity versus wood pulp for organic foods brands. |
| Digital Print System Deployment | Single-pass inkjet enables economical short runs with variable graphics for craft beverage seasonal artwork. |
| FTC Green Guides Compliance Services | Third-party substantiation of recyclability claims creates adjacent revenue for testing laboratories. |
| Direct-to-Store Replenishment Formats | Pre-printed shelf display surfaces penetrate discount grocery and club store channels for Kroger and Albertsons. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with containerboard mill managers, corrugated plant engineers, CPG procurement directors, food service packaging buyers, and sustainability certification specialists. EPA Comprehensive Procurement Guideline documentation, FTC Green Guides enforcement records, California and Maine extended producer responsibility frameworks, and Health Canada food-contact approvals provided regulatory boundary conditions. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis.
Granularity-level modeling disaggregated volume and value across product type, end-use vertical, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level demand elasticity analysis against e-commerce penetration curves and plastic substitution mandate timelines. Industry-specific forecast inputs included OCC collection rate projections, linerboard machine tender availability, and digital print adoption rates among regional independent converters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hurricane disruption severity in southeastern pulp corridors and municipal recycling program funding volatility affecting post-consumer fiber supply. Forecasts reflect assumptions regarding EPA enforcement consistency and state-level plastic ban expansion trajectories. Deviation in California single-use plastic restriction implementation speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market