
 Urology Guidewires Market | 2026-2036
Urology Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Guidewires Market Intelligence
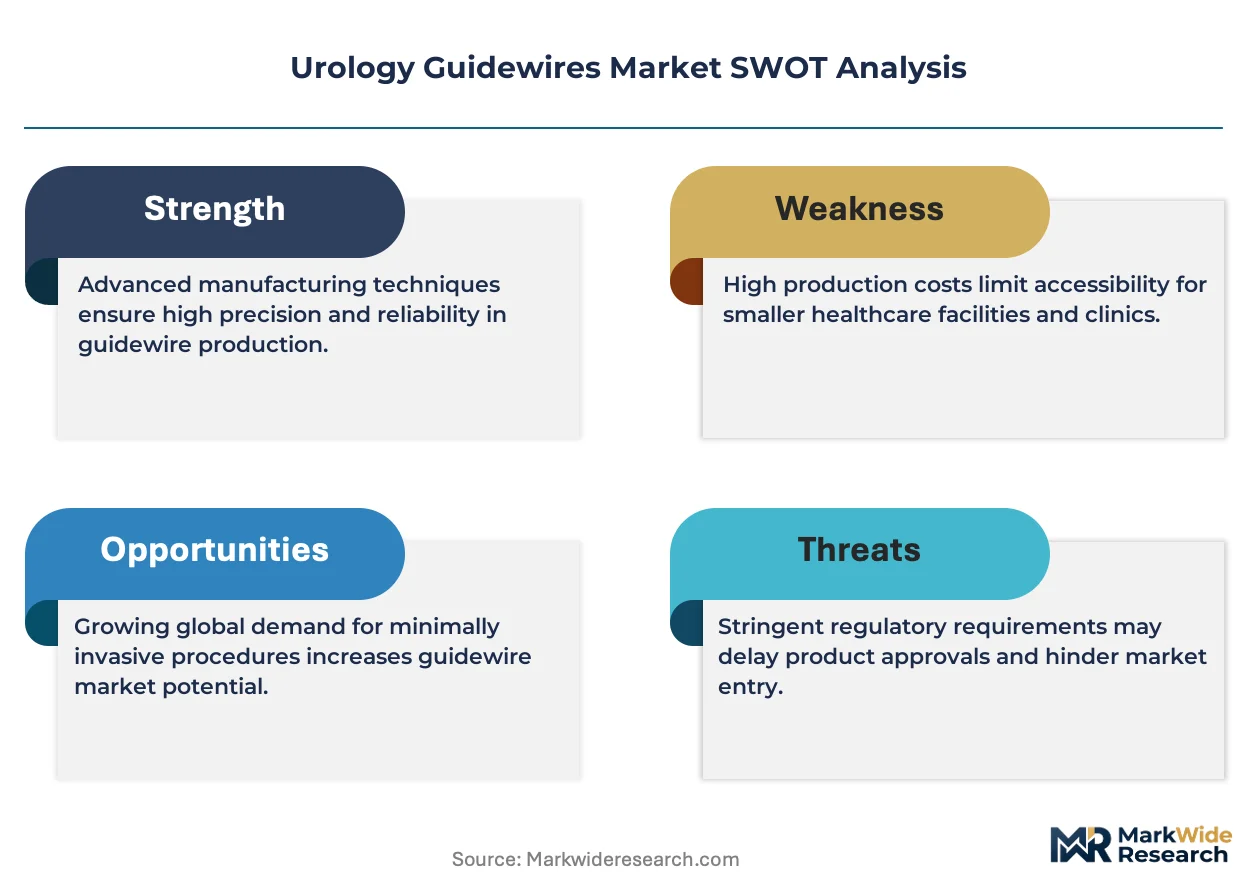
ISO 13485 certification is redrawing competitive boundaries in urology guidewire manufacturing, forcing smaller suppliers to invest in quality management infrastructure or exit hospital contracts. Boston Scientific Corporation leverages its vertically integrated nitinol processing capabilities to control supply continuity for torqueable designs. Cook Medical anchors its position through deep specialization in stiff guidewire geometries for complex renal access. Medtronic competes by extending its global distribution footprint into ambulatory settings across multiple continents.
A urology guidewire is a long, flexible instrument typically constructed from nitinol or stainless steel cores with hydrophilic polymer coatings, engineered to navigate the tortuous ureteral anatomy and establish access for endoscopes or catheters during minimally invasive procedures. Hydrophilic guidewires dominate procedural preference due to reduced friction during ureteral negotiation, while pediatric guidewires represent a concentrated margin pool despite lower absolute volume. Stainless steel retains cost-sensitive share in diagnostic cystoscopy, whereas hybrid material constructions command premium positioning in flexible ureteroscopy where kink resistance and torquability determine clinical outcomes.
FDA 510(k) clearances and EU MDR technical documentation requirements impose substantial validation burdens on coating biocompatibility and fatigue testing, effectively filtering market access to well-capitalized manufacturers. Japan's PMDA maintains distinct sterilization validation standards that delay entry for non-domestic suppliers. Stakeholders must monitor how FDA guidance on reusable versus single-use accessories evolves, as this determination will reshape capital allocation between disposable guidewire portfolios and reprocessing infrastructure investments.
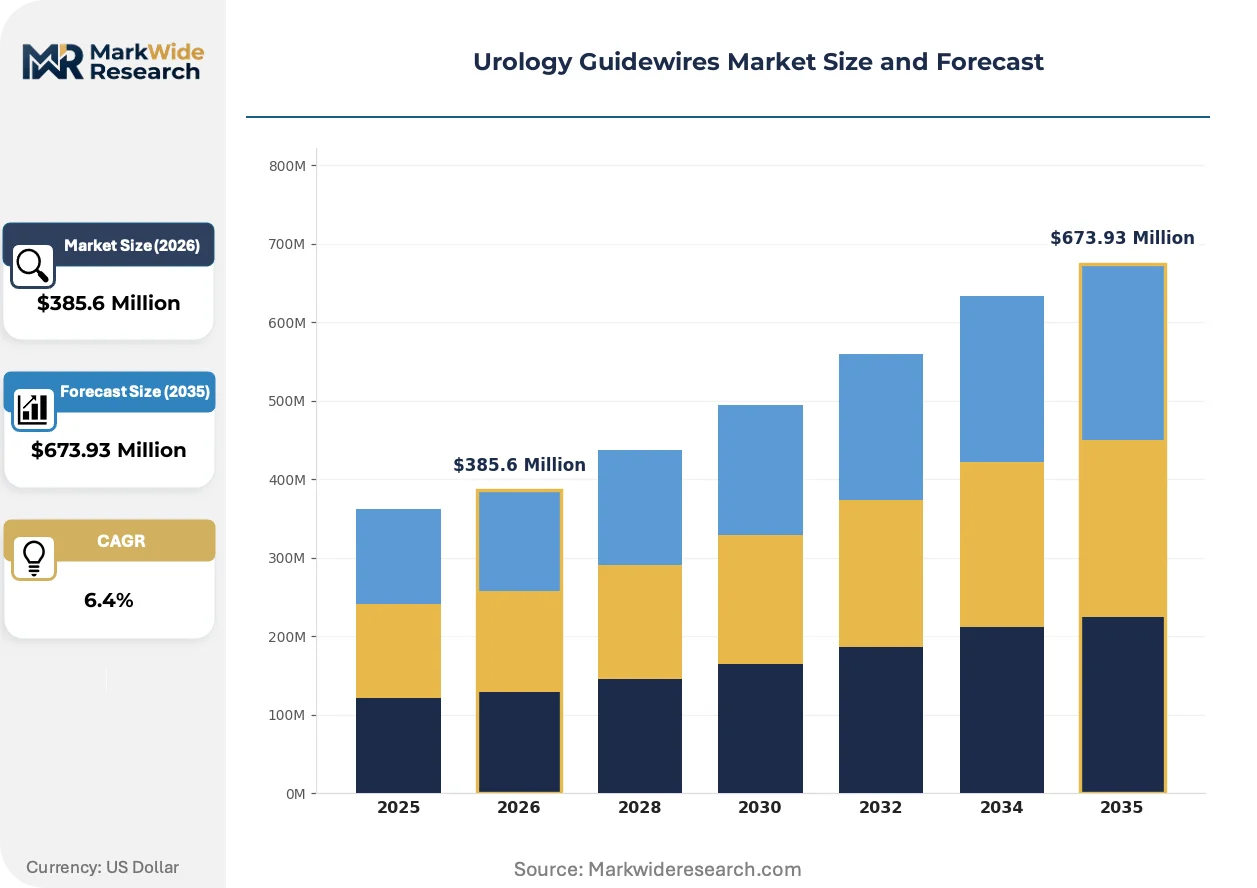
Market Dynamics
The urology guidewires market is experiencing structural compression as EU MDR conformity requirements force manufacturers to rebuild technical documentation for nitinol fatigue validation, filtering out undercapitalized suppliers and concentrating procurement among ISO 13485-certified producers with captive testing infrastructure.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter biocompatibility validation for hydrophilic polymer coatings is elevating quality barriers, rewarding manufacturers with pre-existing laboratory infrastructure and accelerating hospital consolidation around certified suppliers.
- Ambulatory surgical centers:Same-day ureteroscopy procedures are expanding addressable procedure volume beyond traditional hospital settings, creating dedicated guidewire SKUs optimized for rapid turnover and single-use economics.
- Pediatric urology specialization:Smaller-diameter guidewire demand from pediatric nephrolithiasis centers commands premium positioning despite lower absolute unit volume, attracting R&D investment toward 0.018-inch and 0.025-inch platform extensions.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster among limited specialty melt shops, exposing manufacturers to price volatility and allocation risk during aerospace demand cycles.
- Japan PMDA sterilization validation:Distinct ethylene oxide residual limits and biological indicator requirements impose 18-24 month entry delays for non-domestic suppliers, effectively ceding share to established local distributors.
- Reusable guidewire reprocessing economics:Hospital central sterile departments face capital intensity for automated cleaning validation systems, creating friction against single-use displacement in cost-constrained European public health systems.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract manufacturers to establish nitinol wire drawing and coating operations, enabling regional supply base development for South Asian and Middle Eastern markets.
- Hybrid construction guidewires:Convergence of torqueable stainless steel proximal segments with superelastic nitinol distal tips is opening premium positioning in flexible ureteroscopy where kink resistance determines procedural success.
- Direct-to-ambulatory distribution:Bypassing traditional hospital purchasing committees through specialized urology distributor networks is capturing same-day surgery center volume with tailored inventory and consignment models.
Industry Challenges
- Coating chemist talent scarcity:Polyurethane and polyvinylpyrrolidone formulation expertise concentrates among legacy cardiovascular device engineers, forcing competitive recruitment from adjacent interventional segments.
- ISO 13485 certification timeline:New entrant quality management system implementation requires 12-18 months of documented process validation before notified body audit, compressing runway for venture-backed startups.
- Legacy cystoscopy suite compatibility:Stiff stainless steel guidewire inventory in diagnostic settings creates switching friction against hydrophilic platform conversion, requiring dual-sku maintenance during extended replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Guidewires Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Guidewires, Stiff Guidewires, Torqueable Guidewires, Pediatric Guidewires Material: Stainless Steel, Nitinol, Polyurethane, Hybrid Materials End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Flexible Ureteroscopy, Cystoscopy, Renal Procedures, Diagnostic Procedures |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Medtronic, Teleflex Incorporated, Olympus Corporation, Microport Urocare, Endoso, Advin Healthcare, Ace Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Guidewires Market Strategic Shifts & Innovations
Active material science advancement and regulatory documentation burdens are simultaneously elevating performance thresholds and supplier qualification barriers, reshaping competitive position around proprietary nitinol processing capabilities and coating chemistry expertise.
Polytetrafluoroethylene-silicone hybrid coatings are supplanting traditional hydrophilic polymer layers in premium flexible ureteroscopy applications. Academic medical centers in Germany and Japan are adopting these surfaces for reduced friction coefficients during tortuous ureteral navigation. This technology is supplanting conventional coating platforms in accounts where procedural efficiency metrics determine vendor selection and contract renewal.
EU MDR Annex I general safety and performance requirements now mandate explicit fatigue testing documentation for guidewire tip configurations under cyclic bending loads. Manufacturers must submit validated simulation data and physical testing protocols to notified bodies, extending technical file preparation timelines. Small and mid-cap suppliers without captive finite element analysis capabilities are outsourcing to specialized contract research organizations, diluting margin structures.
Hospital procurement committees are unbundling guidewire purchasing from bundled endoscope service contracts, creating standalone competitive bidding events. German university hospitals and Japanese designated cancer centers are leading this disintermediation, establishing direct relationships with guidewire specialists rather than accepting sole-source arrangements from endoscope OEMs. This pattern is most visible in high-volume stone centers where annual guidewire consumption exceeds ten thousand units.
Urology Guidewires Market Segmentation
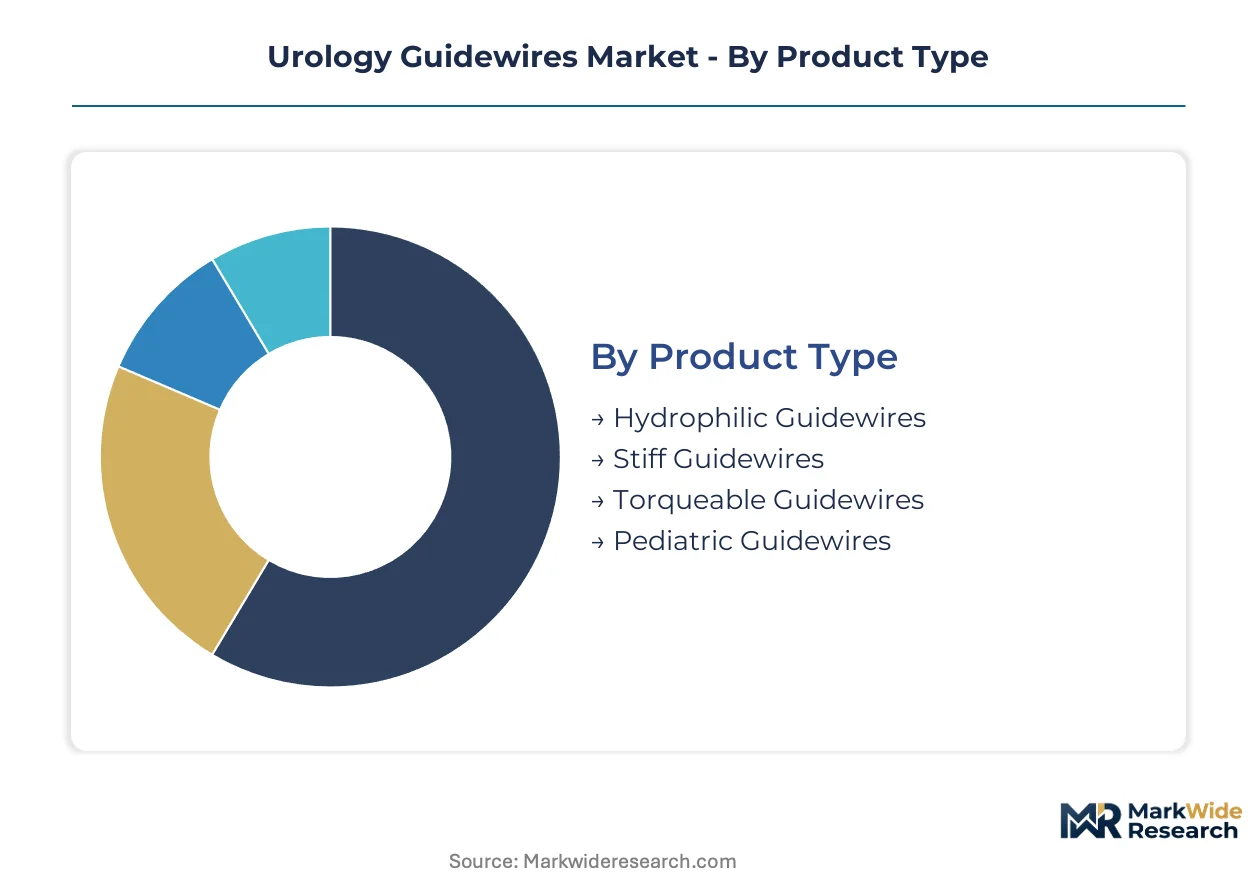
Urology guidewire segmentation reflects divergent regulatory pathways across product categories. Material composition and coating chemistry determine FDA 510(k) versus EU MDR classification burdens, while end-user channel selection shapes sterilization validation requirements and distribution economics.
Product Type:
FDA hydrophilic coating biocompatibility standards and EU MDR Annex I fatigue documentation requirements create divergent compliance costs across guidewire constructions, filtering supplier participation by technical file preparation capacity.
- Hydrophilic Guidewires:Polyvinylpyrrolidone or polyethylene oxide surface layers reduce friction coefficients during tortuous ureteral navigation. Demand concentrates in German university hospitals and Japanese designated cancer centers where procedural efficiency metrics determine vendor selection, though coating chemist scarcity elevates R&D costs.
- Torqueable Guidewires:Nitinol cores with engineered stiffness gradients transmit rotational force through flexible segments. Adoption is climbing fastest in ambulatory surgical centers performing same-day ureteroscopy, where kink resistance determines clinical outcomes and single-use economics dominate procurement.
- Stiff Guidewires:Stainless steel proximal shafts with rigid distal geometries for complex renal access.
- Pediatric Guidewires:0.018-inch and 0.025-inch diameter platforms for pediatric nephrolithiasis centers.
Established volume favors hydrophilic platforms; emerging adoption favors torqueable designs.
Material:
Raw material selection governs supply chain risk exposure and pricing tier positioning, with superelastic alloy concentration among limited specialty melt shops creating allocation vulnerability during aerospace demand cycles.
- Nitinol:Nickel-titanium superelastic alloys enable kink recovery and shape memory for tortuous anatomy navigation. Procurement clusters in United States and Japan where aging demographics sustain procedural volume, though nitinol raw material concentration exposes manufacturers to price volatility.
- Hybrid Materials:Convergence of torqueable stainless steel proximal segments with superelastic nitinol distal tips commands premium positioning. Hospitals in Germany and Japan are leading disintermediation from bundled endoscope contracts, creating standalone bidding opportunities for hybrid constructions.
- Stainless Steel:Cost-sensitive share retention in diagnostic cystoscopy suites.
- Polyurethane:Coating substrate for hydrophilic polymer layers.
Cost-driven procurement favors stainless steel; performance-premium positioning favors hybrid constructions.
End User:
Channel-specific sterilization infrastructure and inventory turnover requirements are fragmenting distribution models, with same-day surgery centers demanding consignment arrangements distinct from hospital central sterile department workflows.
- Ambulatory Surgical Centers:Same-day ureteroscopy volume is expanding fastest in United States facilities shifting from traditional hospital settings. Dedicated SKUs optimized for rapid turnover and single-use economics are capturing this channel, though automated cleaning validation capital intensity creates friction in European public health systems.
- Hospitals:Bundled endoscope service contracts historically dominated procurement, though German university hospitals and Japanese cancer centers are unbundling guidewire purchasing. High-volume stone centers exceeding ten thousand annual units now establish direct supplier relationships.
- Specialty Clinics:Urology-focused outpatient facilities with moderate procedural volume.
- Research Institutions:Academic medical centers driving coating technology evaluation.
Procurement scale favors hospitals; volume growth rate favors ambulatory surgical centers.
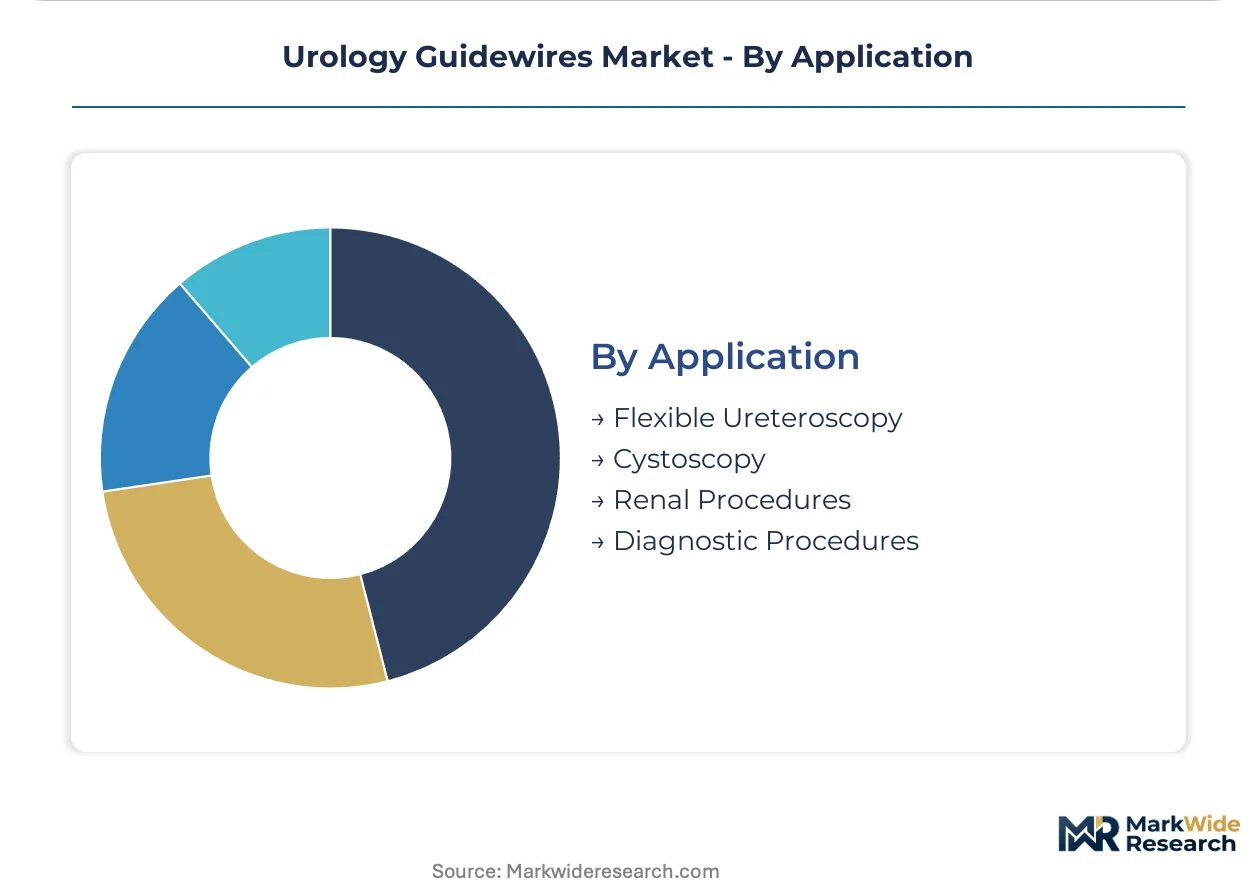
Application:
Procedural complexity and reimbursement coding determine guidewire specification requirements, with flexible ureteroscopy commanding premium material constructions while diagnostic applications tolerate cost-optimized alternatives.
- Flexible Ureteroscopy:Polytetrafluoroethylene-silicone hybrid coatings are supplanting traditional hydrophilic polymer layers in premium applications. German and Japanese academic centers adopt these surfaces for reduced friction coefficients during tortuous navigation, with procedural efficiency metrics determining contract renewal.
- Renal Procedures:Complex access requirements drive stiff guidewire demand from specialized centers. Cook Medical anchors position through deep specialization in stiff geometries, while Boston Scientific leverages vertically integrated nitinol processing for torqueable designs.
- Cystoscopy:Diagnostic suite compatibility creates switching friction against hydrophilic conversion.
- Diagnostic Procedures:Cost-sensitive stainless steel retention in high-volume screening settings.
Reimbursement intensity favors renal procedures; technology substitution pace favors flexible ureteroscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is attracting contract manufacturers to establish nitinol wire drawing operations, reshaping regional supply bases. Reimbursement frameworks and sterilization standards diverge sharply across major demand centers, fragmenting market entry pathways.
United States
Ambulatory surgical centers are shifting same-day ureteroscopy volume away from traditional hospitals, expanding addressable procedure counts. FDA 510(k) clearance pathways maintain rigorous coating biocompatibility validation standards. Boston Scientific Corporation leverages vertically integrated nitinol processing in Massachusetts to control supply continuity for torqueable designs.
Germany
University hospitals are unbundling guidewire purchasing from bundled endoscope service contracts, creating standalone competitive bidding events. EU MDR Annex I fatigue documentation requirements mandate explicit cyclic bending load testing for tip configurations. Academic medical centers in Bavaria and Baden-Württemberg are adopting polytetrafluoroethylene-silicone hybrid coatings for reduced friction coefficients.
Japan
Aging demographics sustain procedural volume for minimally invasive urology interventions. PMDA maintains distinct ethylene oxide residual limits and biological indicator requirements that delay entry for non-domestic suppliers. Designated cancer centers in Tokyo and Osaka are establishing direct supplier relationships rather than accepting sole-source arrangements from endoscope OEMs.
India
Domestic manufacturing incentives under the PLI scheme are enabling regional supply base development for South Asian markets. CDSCO medical device regulations are tightening material traceability standards for imported nitinol-based devices. Contract manufacturers in Maharashtra and Gujarat are establishing nitinol wire drawing and coating operations to serve Middle Eastern export channels.
Urology Guidewires Market Key Industry Players
Listed leaders compete with private specialists across quality certification tiers, with ISO 13485 compliance redrawing contract eligibility boundaries. The supplier base concentrates among manufacturers with captive nitinol processing infrastructure and established notified body relationships. Three archetypes dominate: vertically integrated nitinol processors, coating chemistry specialists, and regional distribution anchors. Competitive moves center on backward integration into raw material supply and direct-to-ambulatory distribution channel development.
Within the integrated processor tier, Boston Scientific Corporation exemplifies upstream control over superelastic alloy supply chains. Cook Medical occupies a position among stiff geometry specialists serving complex renal access requirements. Medtronic sits within the scale-driven distribution archetype, extending footprint into ambulatory settings across multiple continents.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Medtronic |
| Teleflex Incorporated |
| Olympus Corporation |
| Microport Urocare |
| Endoso |
| Advin Healthcare |
| Ace Medical Devices |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between nitinol melt shops and guidewire manufacturers lock in alloy supply visibility while fixing raw material cost baselines for 24-36 month procurement cycles. These arrangements insulate Boston Scientific and Cook Medical from aerospace demand spikes that otherwise trigger allocation rationing, though EU MDR compliance investments are compressing operating margins across all tiers.
Pricing Analysis
Certification level creates the primary spread between premium ISO 13485-validated producers and uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, coating chemistry complexity, and torquability performance specifications. Price erosion runs through the economy tier as Indian contract manufacturers undercut legacy suppliers on stainless steel diagnostic guidewires. Ambulatory surgical centers exhibit highest price sensitivity due to single-use economics, while Japanese designated cancer centers prioritize performance over cost.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Shanghai to Long Beach has elevated inbound logistics costs for nitinol wire shipments sourced from Chinese specialty melt shops. Superelastic alloy supply concentrates in United States, Japan, and Germany where vacuum arc remelting capabilities anchor production. Raw material feeds from nickel and titanium sponge producers in Russia and Kazakhstan rest on geopolitical stability. Single-source vulnerability persists for hydrophilic polymer coating chemistries concentrated among legacy cardiovascular suppliers. Distribution runs through specialized urology distributor networks and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urology guidewires market is recovering from EU MDR documentation bottlenecks as notified body capacity expands and technical file backlogs clear. Cyclical recovery momentum hinges on ambulatory surgical center construction pipelines in United States metropolitan markets.
For Market Incumbents: Compound defensive moats by securing captive nitinol processing capacity in Massachusetts or Indiana to insulate against aerospace allocation cycles. Deepen coating chemistry expertise through targeted recruitment from interventional cardiology segments where polyurethane formulation talent concentrates. Prioritize ISO 13485 certification maintenance to defend hospital contract eligibility against emerging Indian competitors. For New Entrants and Emerging Players: Same-day surgery center inventory management represents a service-layer gap where incumbents under-serve with hospital-centric SKU configurations. Target ambulatory settings in Texas and Florida with consignment models and rapid-turnover packaging formats. Penetrate through direct distributor relationships rather than competing for bundled endoscope contracts at academic medical centers. For Investors and Strategic Acquirers: Coating chemistry specialists with proprietary polytetrafluoroethylene-silicone formulations offer the most defensible acquisition target archetype in this market. Long-term viability centers on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor FDA guidance evolution on reusable versus single-use accessories as the critical inflection signal for capital allocation between disposable portfolios and reprocessing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for nitinol-based torqueable designs in United States ambulatory settings. |
| CE Marking Pathway | EU MDR Annex I compliance enables procurement eligibility at German university hospitals unbundling from endoscope OEMs. |
| Hospital System Partnership | Direct relationships with Japanese designated cancer centers bypass traditional distributor markups in high-volume stone centers. |
| Software Companion Development | Digital tracking platforms for guidewire inventory optimize consignment economics at same-day surgery centers. |
| Reimbursement Strategy | CPT code alignment for flexible ureteroscopy procedures secures procedural volume in United States outpatient settings. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with urologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgery center administrators. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation filings, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up procedure volume estimates and top-down manufacturer shipment data were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by material composition, coating chemistry, end-user channel, and procedural application. CAGRs were derived from regression analysis against demographic drivers, reimbursement trend trajectories, and regulatory approval pipeline velocity. Nitinol raw material price indices and ambulatory surgical center construction permits served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR notified body operations; material policy shifts would require re-modeling. Specific risks include Japan PMDA sterilization standard revisions, nitinol supply disruption from aerospace demand cycles, and hospital procurement committee decisions on reusable guidewire reprocessing economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Asia-Pacific Respiratory Devices Market