
 Asia-Pacific Respiratory Devices Market | 2026-2036
Asia-Pacific Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Respiratory Devices Market Outlook
Aftermarket service revenue is narrowing as manufacturers shift toward subscription-based digital platforms and remote patient monitoring. ResMed leverages its cloud-connected device ecosystem to sustain recurring revenue streams across Australia and Southeast Asia. Philips anchors its position through intensive R&D in ventilator miniaturization, while Mindray competes aggressively on cost-engineered electromechanical platforms for hospital procurement tenders.
Asia-Pacific respiratory devices encompass electromechanical and digital systems engineered to deliver controlled airflow, oxygen concentration, or medicated aerosols with precision parameters such as pressure thresholds measured in cmH2O and flow rates calibrated for individual patient physiology. These systems serve the primary commercial purpose of managing chronic obstructive pulmonary disease, sleep-disordered breathing, and acute respiratory failure across clinical and domiciliary environments. CPAP devices and oxygen concentrators command the largest installed base, yet wearable technology segments are expanding fastest as ambulatory monitoring gains clinical acceptance. Homecare settings represent the margin-rich channel where digital connectivity enables remote adherence tracking and preventive intervention.
Japan's PMDA maintains stringent premarket approval pathways for Class III and IV respiratory devices, while Australia's TGA enforces ISO 13485-aligned quality management audits that shape supplier qualification across the region. China's NMPA accelerates review timelines for innovative devices under its priority review pathway, directly influencing which technologies achieve commercial scale. Stakeholders must monitor how divergent cybersecurity requirements for connected inhalers and CPAP systems across these regimes affect product architecture decisions and regional launch sequencing.
Market Dynamics
Subscription-based digital platforms are compressing aftermarket service revenue across the Asia-Pacific respiratory devices sector, forcing manufacturers to restructure revenue models around recurring software streams rather than discrete hardware sales.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for medical devices are accelerating domestic manufacturing capacity for ventilators and oxygen concentrators, reducing import dependency for hospital networks.
- Hospital infrastructure upgrades:China's tertiary care facilities are expanding respiratory care units with centralized oxygen delivery systems and high-flow nasal cannula capabilities.
- Remote patient monitoring:Cloud-connected CPAP platforms enable adherence tracking and preventive intervention, creating recurring revenue channels in Australia's homecare segment.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller and sensor chip fabrication, creating vulnerability for device manufacturers sourcing electromechanical control systems.
- PMDA approval timelines:Japan's premarket review pathways for Class III respiratory devices extend certification cycles, delaying product launches by 18-24 months relative to TGA or NMPA processes.
- Reagent and consumable cost volatility:Polymer prices for tubing and filtration membranes fluctuate with petrochemical feedstock costs, compressing margins on disposable components.
Strategic Opportunities
- Vietnam's underpenetrated homecare segment:Nasal CPAP adoption remains below 15% of diagnosed sleep apnea cases, presenting whitespace for ambulatory device distribution partnerships.
- Indonesia's NMPA-equivalent fast-track pathway:Priority review mechanisms for innovative devices are accelerating market entry timelines for digital inhaler platforms.
- Wearable-CPAP convergence:Integration of miniaturized blower technology with biometric sensors is creating new product categories for nocturnal oxygen saturation monitoring.
Industry Challenges
- Embedded systems engineering talent:Firmware development for pressure-sensing algorithms and motor control loops faces acute scarcity across Australia's medical device cluster.
- Cybersecurity certification fragmentation:Divergent requirements for connected inhalers across PMDA, TGA, and NMPA regimes force redundant architecture testing and regional launch sequencing delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Respiratory Devices Market |
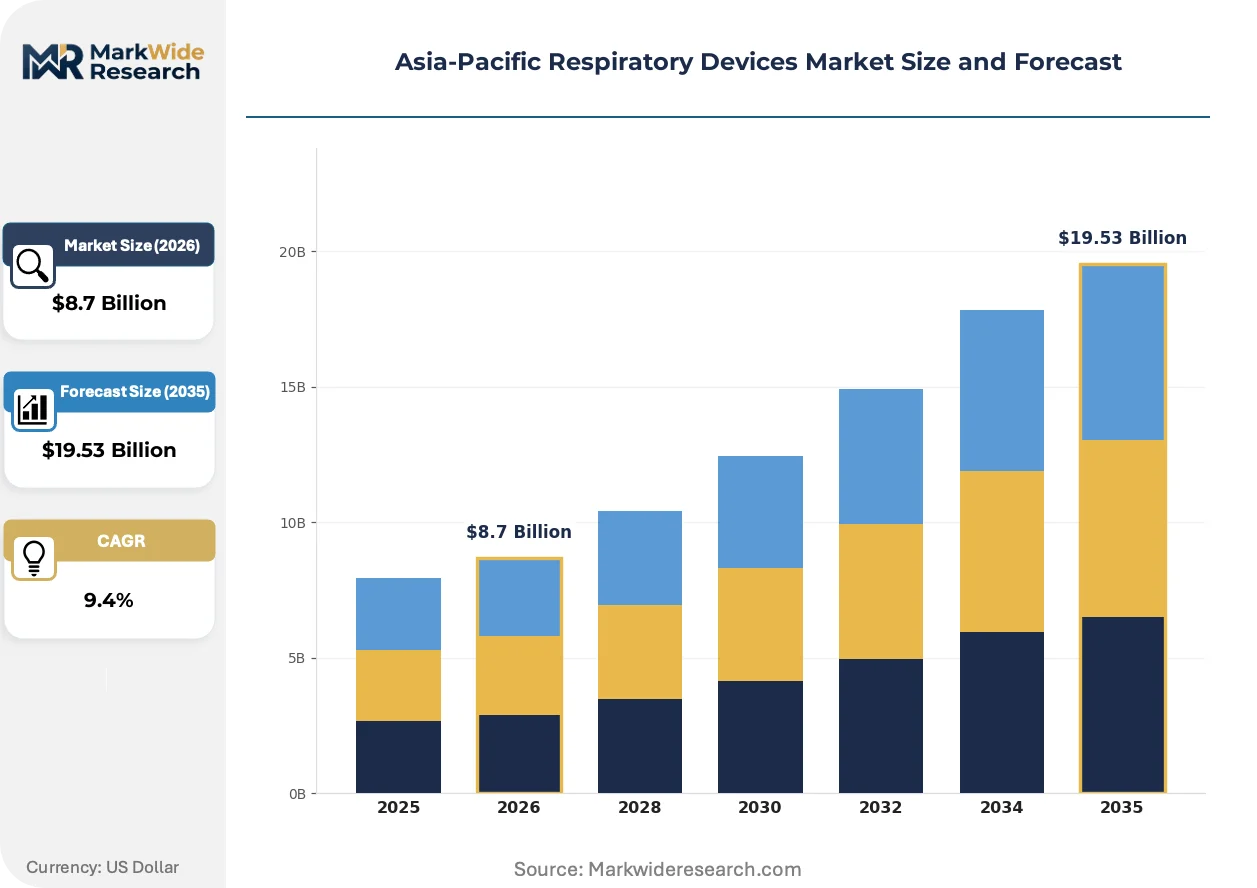
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Oxygen Concentrators End User: Hospitals, Homecare Settings, Clinics, Rehabilitation Centers Technology: Electromechanical, Manual, Digital, Wearable Application: Asthma, COPD, Sleep Apnea, Cystic Fibrosis |
| Companies Covered | Medtronic, Mindray, ResMed, Invacare Corporation, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., GE Healthcare, ICU Medical, Fisher & Paykel Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Respiratory Devices Market Strategic Shifts
Digital connectivity architectures are redefining competitive differentiation in respiratory care, with software-enabled adherence platforms displacing hardware-centric value propositions across the Asia-Pacific installed base.
Pressure-sensing algorithms is hybridizing with acoustic respiratory event detection to create next-generation auto-titrating CPAP systems. Australian sleep clinics are piloting these dual-modality devices for complex apnea phenotypes. The convergence is compressing demand for standalone diagnostic polysomnography equipment in favor of integrated therapy platforms.
China's NMPA priority review pathway is accelerating commercial scale for innovative ventilator miniaturization technologies. Domestic manufacturers are exploiting compressed timelines to outpace multinational incumbents in municipal hospital procurement tenders. The regulatory tailwind most directly benefits electromechanical platforms with embedded connectivity modules seeking rapid market authorization.
Hospital procurement committees are unbundling after-sales service contracts from device capital expenditure, forcing manufacturers to price maintenance separately or absorb costs within hardware margins. Australian and Southeast Asian health systems are leading this disintermediation, with public tenders now requiring transparent lifecycle cost disclosure. The shift is most visible in China's provincial centralized purchasing programs, where total cost of ownership scoring dominates award criteria.
Asia-Pacific Respiratory Devices Market Segmentation
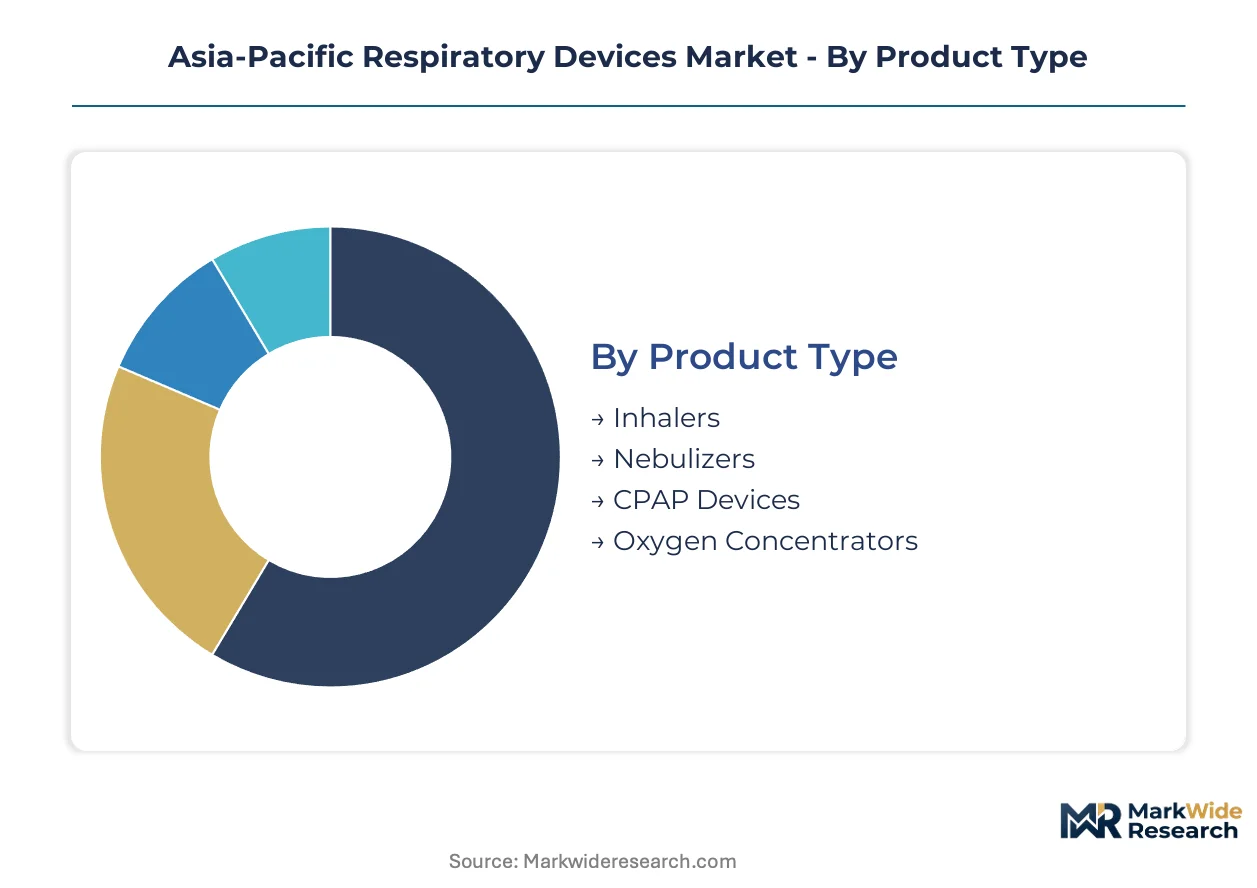
Respiratory device segmentation reveals divergent margin structures and regulatory pathways across the Asia-Pacific region. Product architecture choices cascade into distinct reimbursement codes and procurement channels that shape manufacturer positioning.
Product Type:
Mature electromechanical platforms anchor hospital procurement while emerging digital modalities capture homecare expansion.
- CPAP Devices:Auto-titrating blower systems with pressure-sensing algorithms calibrated in cmH2O thresholds dominate sleep-disordered breathing management. Australian homecare providers and China's tertiary hospital networks drive replacement cycles as cloud-connected adherence platforms displace legacy hardware-only units.
- Oxygen Concentrators:Pressure swing adsorption systems delivering 90-96% oxygen purity at 1-10 LPM flow rates serve COPD and acute respiratory failure. India's hospital infrastructure upgrades under PLI incentives concentrate demand for portable units, though semiconductor sourcing from Taiwan creates supply vulnerability for control board fabrication.
- Inhalers:Metered-dose and dry-powder platforms deliver bronchodilator and corticosteroid aerosols with particle size optimization for pulmonary deposition.
- Nebulizers:Jet and mesh technologies convert liquid medication into respirable droplets for pediatric and geriatric populations with coordination difficulties.
CPAP devices handle the majority of throughput; oxygen concentrators are expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive institutional procurement from recurring-revenue homecare channels.
- Homecare Settings:Domiciliary oxygen therapy and nocturnal CPAP adherence programs generate subscription-based recurring revenue through remote monitoring platforms. Australia's cloud-connected device penetration leads regional adoption, while Vietnam's diagnosed-but-untreated sleep apnea population presents whitespace for ambulatory distribution partnerships.
- Hospitals:Tertiary care facilities in China and India deploy centralized oxygen delivery infrastructure and high-flow nasal cannula systems for acute respiratory failure. Procurement committees now unbundle service contracts from capital expenditure, forcing transparent lifecycle cost disclosure in tender evaluations.
- Clinics:Outpatient respiratory diagnostics and initial therapy titration serve as gatekeepers to homecare conversion.
- Rehabilitation Centers:Post-acute weaning protocols and pulmonary rehabilitation programs utilize ventilator miniaturization technologies for step-down care.
Hospitals command the dominant procurement volume; homecare settings deliver the steepest margin expansion.
Technology:
Application context determines whether precision electromechanics or patient-facing digital interfaces take priority in product development.
- Digital:Cloud-connected architectures with embedded cellular or Wi-Fi modules enable real-time adherence transmission to clinical dashboards. China's NMPA priority review pathway accelerates market authorization for platforms with remote patient monitoring capabilities, compressing launch timelines relative to Japan's PMDA processes.
- Electromechanical:Motor control loops, pressure transducers, and flow sensors constitute the core engineering substrate for all active therapeutic delivery. Australia's medical device cluster faces acute firmware development scarcity for these embedded systems.
- Manual:Hand-powered or gravity-dependent devices serve resource-constrained settings without reliable electricity access.
- Wearable:Miniaturized blower technology integrated with biometric sensors creates ambulatory nocturnal oxygen saturation monitoring categories.
Electromechanical platforms carry the installed base; digital connectivity is climbing the fastest on commercial priority.
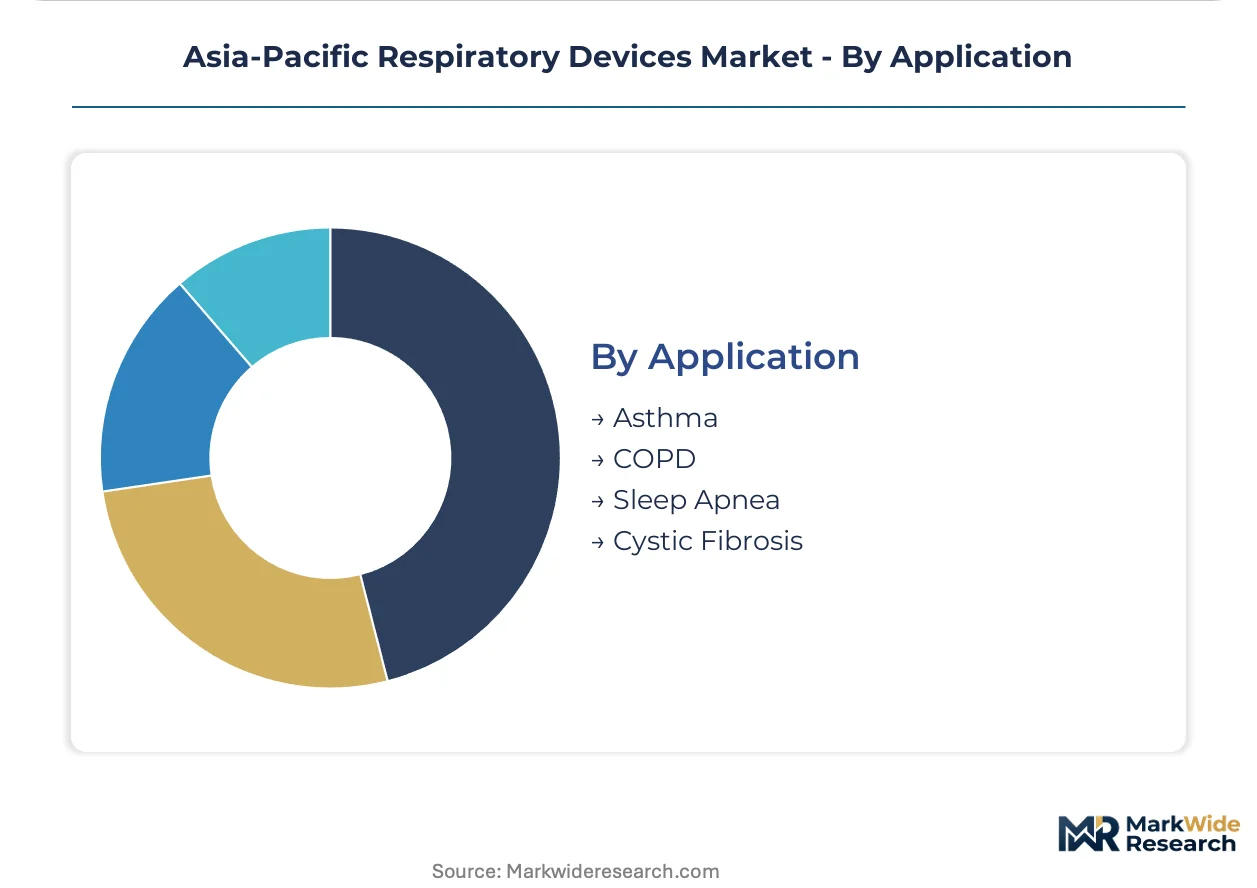
Application:
Customer type segmentation aligns reimbursement pathways with chronic disease prevalence and acute intervention requirements.
- Sleep Apnea:Obstructive and central apnea phenotypes drive CPAP and adaptive servo-ventilation device prescription. Australian sleep clinics pilot dual-modality pressure-sensing and acoustic detection systems that compress demand for standalone polysomnography equipment.
- COPD:Chronic airflow limitation necessitates long-term oxygen therapy and acute exacerbation management through portable concentrators and hospital ventilator systems. China's aging demographic and India's air quality challenges concentrate regional disease burden.
- Asthma:Reversible bronchoconstriction managed through inhaled corticosteroid and bronchodilator delivery platforms.
- Cystic Fibrosis:Mucus clearance and chronic infection management require specialized nebulized antibiotic and airway oscillation technologies.
COPD addresses the largest patient population; sleep apnea is gaining share fastest on device connectivity monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tertiary hospitals deploy centralized oxygen delivery infrastructure at scale, while Australian homecare providers monetize cloud-connected adherence platforms through subscription models that diverge sharply from India's procurement-focused hospital tenders.
China
Provincial centralized purchasing programs unbundle service contracts from device capital expenditure, forcing transparent lifecycle cost disclosure in tender evaluations. NMPA accelerates review timelines for innovative ventilator miniaturization technologies under its priority review pathway. Municipal hospital networks in Beijing-Tianjin-Hebei and the Yangtze River Delta concentrate procurement volume for high-flow nasal cannula systems.
India
Hospital infrastructure upgrades concentrate demand for portable oxygen concentrators and ventilators as tertiary care facilities expand respiratory care units. PLI scheme production-linked incentives accelerate domestic manufacturing capacity, reducing import dependency for electromechanical control systems. Manufacturing clusters in Maharashtra and Gujarat scale assembly operations for pressure swing adsorption systems serving municipal hospital networks.
Australia
Homecare settings generate recurring revenue through remote patient monitoring platforms that track CPAP adherence and enable preventive intervention. TGA enforces ISO 13485-aligned quality management audits that shape supplier qualification across the region. Sydney and Melbourne medical device clusters face acute firmware development scarcity for embedded pressure-sensing algorithms and motor control loops.
Japan
Sleep clinics pilot dual-modality pressure-sensing and acoustic detection systems that compress demand for standalone diagnostic polysomnography equipment. PMDA maintains stringent premarket approval pathways for Class III and Class IV respiratory devices, extending certification cycles relative to regional peers. Tokyo-Osaka industrial corridors concentrate R&D investment in ventilator miniaturization and wearable-CPAP convergence technologies.
Vietnam
Nasal CPAP adoption remains below fifteen percent of diagnosed sleep apnea cases, presenting whitespace for ambulatory device distribution partnerships. The country's national medical device regulator aligns review processes with ASEAN harmonization frameworks, accelerating market entry for digital inhaler platforms. Ho Chi Minh City and Hanoi concentrate private healthcare investment that drives homecare oxygen therapy expansion.
Asia-Pacific Respiratory Devices Market Competitive Environment
Capability concentration sits with electromechanical specialists engineering precision pressure-sensing algorithms; scale advantage sits with diversified health technology conglomerates leveraging integrated supply chains. The vendor base stratifies into three tiers: premium-tier players commanding hospital procurement through R-intensive portfolios, mid-tier regional fabricators competing on cost-engineered platforms, and emerging domestic manufacturers exploiting regulatory fast-tracks. Dominant competitive moves include portfolio diversification into digital connectivity architectures and geographic expansion through distribution partnerships in underpenetrated homecare segments.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and GE Healthcare exemplify scale-driven positioning through integrated hospital procurement channels. ResMed occupies a distinctive position within the digital-native tier, representing cloud-connected ecosystem architectures that monetize recurring software streams. Mindray exemplifies the cost-engineered regional specialist archetype, competing aggressively on electromechanical platforms for municipal hospital tenders.
| Leading Market Players |
|---|
| Medtronic |
| Mindray |
| ResMed |
| Invacare Corporation |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| GE Healthcare |
| ICU Medical |
| Fisher & Paykel Healthcare |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korea semiconductor supply concentration determines both pricing tier spreads and supply chain shape across Asia-Pacific respiratory device manufacturing. Component scarcity for pressure sensors and motor controllers forces tiered pricing separation between premium cloud-connected platforms and cost-engineered hospital tenders, while procurement committees unbundle service contracts to compress hardware margins.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement in China and India, while Australia's homecare segment monetizes through subscription-based SaaS tiers for remote adherence monitoring. Pricing stratifies across premium connectivity-enabled platforms, standard electromechanical units, and economy-grade manual devices based on NMPA fast-track certification status and after-sales service bundling. Cost compression in economy tiers intensifies as India's PLI scheme accelerates domestic assembly capacity for oxygen concentrators. Municipal hospital procurement committees in China exhibit highest price sensitivity; Australian private homecare providers demonstrate lowest sensitivity due to recurring revenue model conversion.
Supply Chain Analysis
Polymer feedstock costs for tubing and filtration membranes fluctuate with petrochemical input volatility, anchoring raw material exposure for disposable component manufacturing. Taiwan, South Korea, and Japan concentrate microcontroller and precision sensor fabrication, creating single-source vulnerability for pressure transducer and flow sensor modules. Supply chain risk centers on semiconductor allocation constraints that throttle electromechanical platform production during demand surges. Distribution runs through centralized provincial purchasing programs in China, GPO contracts in Australia, and direct hospital tenders in India's Maharashtra and Gujarat manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inhaler platforms and wearable diagnostic substitutes threaten incumbent hardware margins, forcing established manufacturers to defend installed base monetization before connectivity-native entrants capture homecare adherence revenue.
For Market Incumbents: Pre-empt substitution by accelerating software companion development for existing CPAP and oxygen concentrator fleets, converting transactional hardware sales into recurring remote monitoring revenue streams. Secure backward integration into Taiwan-sourced semiconductor supply through preferred allocation agreements or captive sensor module production partnerships. Defend against Mindray-style cost-engineered competitors by embedding NMPA-priority-review connectivity features that justify premium positioning in Chinese municipal tenders. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated nasal CPAP segment, where diagnosed-but-untreated sleep apnea prevalence exceeds device adoption by substantial margins. Exploit Indonesia's ASEAN-harmonized regulatory pathway to accelerate digital inhaler market authorization timelines relative to Japan's PMDA processes. Partner with Australian homecare providers for cloud-connected adherence platform distribution, leveraging their existing remote patient monitoring infrastructure and clinician dashboard integration. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors digital-native device architectures with embedded connectivity modules over legacy electromechanical specialists. Long-term viability across the analysis window hinges on recurring revenue conversion rates in homecare segments and regulatory fast-track exploitation capabilities. Target acquisition archetypes include firmware-development-scarce Australian medical device clusters and Vietnam-focused ambulatory distribution platforms. Monitor NMPA priority review queue velocity as inflection indicator for domestic manufacturer competitive positioning against multinational incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Enables subscription monetization of existing CPAP installed base across Australian homecare networks. |
| NMPA Priority Review Pathway Exploitation | Compresses market authorization timelines for cloud-connected ventilator miniaturization technologies in China. |
| Semiconductor Supply Securement | Mitigates Taiwan allocation risk for pressure sensor modules critical to auto-titrating blower systems. |
| Vietnam Distribution Partnership | Captures whitespace in sub-fifteen-percent nasal CPAP penetration among diagnosed sleep apnea cases. |
| PLI Scheme Manufacturing Scale-Up | Leverages Indian production incentives to reduce import dependency for hospital oxygen concentrator tenders. |
Study Parameters
Cross-validation between hospital procurement database analysis and clinician interview panels anchors the qualitative findings on adherence platform adoption patterns. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare provider operations directors were combined with secondary validation from NMPA registration filings, TGA ISO 13485 audit records, and India PLI scheme beneficiary disclosures. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulation were applied across the analysis window.
Calibration against historical regulatory approval timelines and procurement tender award patterns shaped the projection framework. Segmentation dimensions modeled include product architecture type, end-use setting, connectivity technology tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, homecare penetration trajectory assumptions, and hospital infrastructure investment correlations. Forecast inputs incorporated semiconductor supply elasticity parameters and polymer feedstock cost volatility indices.
Stress conditions across Taiwan semiconductor allocation constraints, PMDA approval timeline extensions, and PLI scheme incentive modification were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud-connected platform conversion rates and ASEAN regulatory harmonization progress. Cross-checking against hospital capital expenditure budget disclosures and medical device import trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Endodontic Devices Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Feeding Tubes Market
Medical Devices
Thrombectomy System Market